
 Mill Mixer Market | 2026-2036
Mill Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Mill Mixer Market Foresight
Modular screw-mixing architecture is fragmenting traditional equipment procurement as end users swap standardized sub-assemblies rather than replace entire units. NDEco leverages its captive foundry network to control casting quality for high-wear auger components. KUHN North America INC. anchors its position through dense dealer coverage across Midwest agricultural processing corridors. Tetra Laval International S.A. differentiates by integrating aseptic filling interfaces directly into its batch mixer platforms.
A mill mixer is an industrial blending machine that combines rotating agitation mechanisms—typically screw, paddle, ribbon, or auger configurations—with precision-engineered chambers to achieve homogeneous dispersion of powders, pastes, or slurries at controlled shear rates and temperatures. Horizontal mixers dominate volume sales for bulk dry blending in food processing due to mature supply chains and lower capital thresholds, while continuous mixers capture expanding margin pools in pharmaceutical applications where real-time release testing and reduced batch-to-batch variation command premium pricing. Ribbon mixing technology retains strong positioning in heavy-duty mixing for construction materials, though paddle mixing gains traction in coating applications requiring gentler product handling.
OSHA machine guarding standards and FDA cGMP equipment qualification requirements shape design priorities for North American suppliers, while REACH substance restrictions and CE machinery directives constrain material selection and export eligibility for European manufacturers. Stakeholders must weigh modular upgrade pathways against total replacement cycles as regulatory scrutiny intensifies on cleanability validation and energy efficiency documentation.
Market Dynamics
Continuous processing architectures are fragmenting capital deployment patterns as pharmaceutical manufacturers trade fixed batch infrastructure for modular, real-time release-capable lines that compress validation timelines and reduce clean-in-place downtime.
Growth Catalysts
- REACH substance certification:European material compliance mandates are forcing alloy substitution toward traceable stainless steel grades, creating replacement demand for legacy carbon-steel mixing chambers across German and French processing facilities.
- Continuous manufacturing:FDA quality-by-design guidelines for pharmaceutical equipment are accelerating adoption of twin-screw extrusion mixers that integrate directly into end-to-end production lines rather than isolated batch operations.
- Precision engineering clusters:Concentrated supplier networks in Stuttgart and Munich enable rapid prototyping of specialized auger geometries for regulated industries, compressing development cycles for custom mixer configurations.
Market Restraints
- High-grade stainless steel volatility:Nickel and molybdenum price swings directly impact casting costs for corrosion-resistant mixing chambers, squeezing margins for European fabricators locked into fixed-price pharmaceutical contracts.
- Foundry capacity concentration:Captive casting operations in Central Europe control premium alloy supply for wear-resistant auger components, creating bottleneck risk for non-integrated mixer assemblers.
- Batch-to-continuous retrofit complexity:Legacy facility layouts and validated cleanroom configurations impose physical constraints that extend payback periods for continuous mixer investments beyond typical capital planning horizons.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO manufacturing license reforms and PLI scheme incentives for active pharmaceutical ingredient production are creating demand for cGMP-qualified mixing equipment in Hyderabad and Ahmedabad clusters.
- Aseptic integration:Convergence between precision mixing and isolator technology is opening white space for equipment suppliers that pre-validate sterile interfaces, reducing customer qualification burden.
- Service unbundling:Independent aftermarket providers are capturing margin pools by offering remote condition monitoring and predictive auger replacement, bypassing OEM service networks.
Industry Challenges
- Cleanability validation expertise:FDA cGMP equipment qualification requirements demand specialized documentation capabilities that outstrip talent availability among mid-tier engineering firms, extending project timelines.
- Legacy control system integration:Continuous mixers must interface with existing SCADA architectures and batch record systems, requiring custom protocol bridges that inflate commissioning costs and technical risk.
- Energy efficiency documentation:CE machinery directives and emerging corporate sustainability reporting obligations are forcing suppliers to generate verified power-consumption data that many lack instrumentation to capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mill Mixer Market |
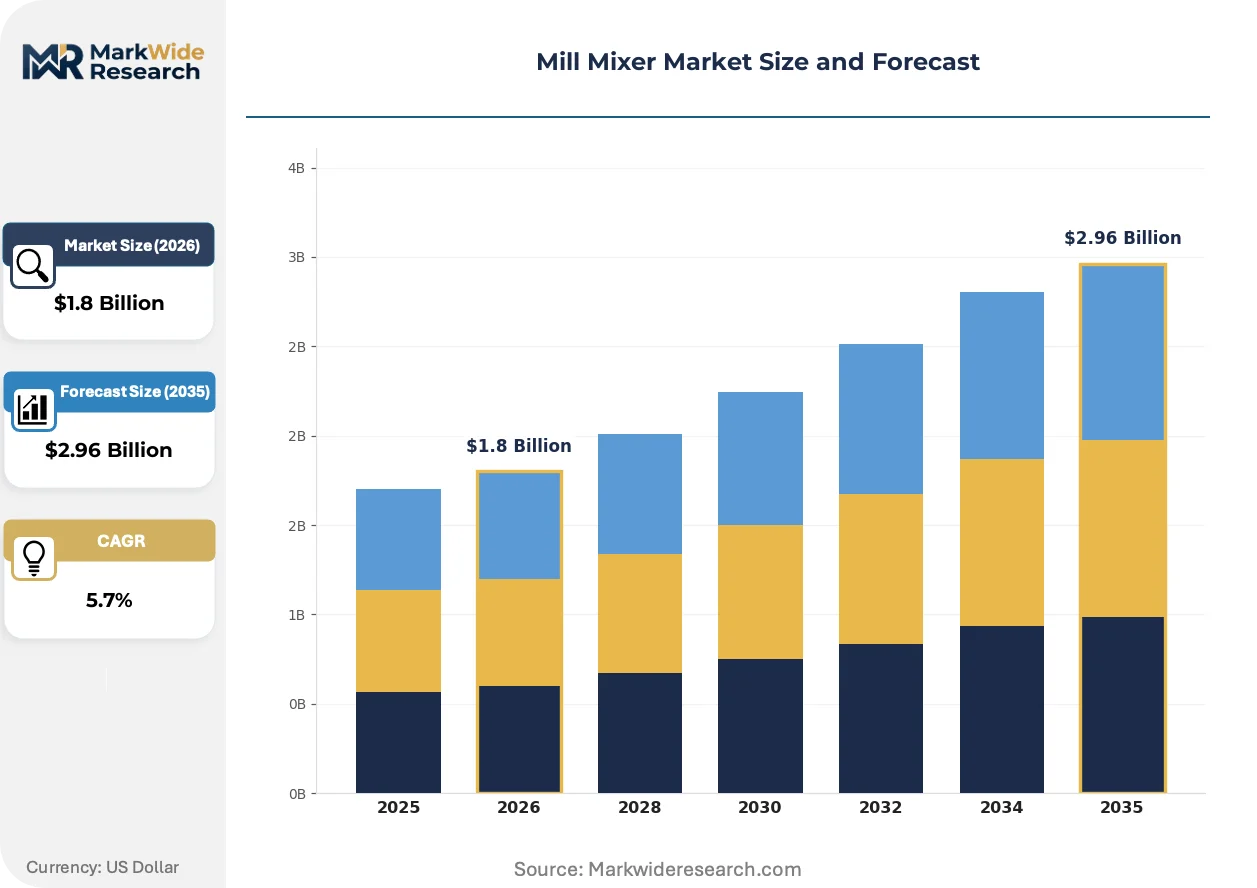
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Mixer, Vertical Mixer, Batch Mixer, Continuous Mixer End User: Food Processing, Chemical Processing, Pharmaceutical, Construction Technology: Screw Mixing, Paddle Mixing, Ribbon Mixing, Auger Mixing Application: Baking, Coating, Dry Blending, Heavy-Duty Mixing |
| Companies Covered | NDEco, Supreme International Ltd., KUHN North America INC., Grupo Tatoma, Triolite, Groupe Anderson, SILOKING Mayer, Seko Industries, Tetra Laval International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mill Mixer Market Shifts & Advancements
Digital twin architectures and real-time analytical integration are compressing the gap between mixing performance and quality assurance, enabling predictive adjustment rather than post-batch correction.
Modular screw-mixing platforms with standardized sub-assembly interfaces are rendering obsolete the traditional capital cycle of complete unit replacement. Pharmaceutical manufacturers in Basel and Boston are adopting these configurations to swap auger geometries and chamber liners without facility shutdowns. The technology is enabling equipment-as-a-service models that transfer obsolescence risk from end users to suppliers.
EMA guidelines on continuous manufacturing quality assurance are tightening validation requirements for real-time release testing systems. European pharmaceutical equipment suppliers must now document statistical process control capabilities that demonstrate mixer output consistency without offline laboratory verification. German precision engineering firms are responding by integrating inline near-infrared spectroscopy directly into auger housing designs.
Buyer concentration among contract manufacturing organizations is compressing vendor selection cycles and intensifying specification standardization. Large CDMOs in Ireland and Singapore are consolidating approved equipment lists to streamline multi-site technology transfer, forcing niche mixer suppliers to achieve qualification across broader platform portfolios. This pattern is most visible in sterile injectables production where aseptic process equivalence across facilities determines supplier viability.
Mill Mixer Market Segmentation
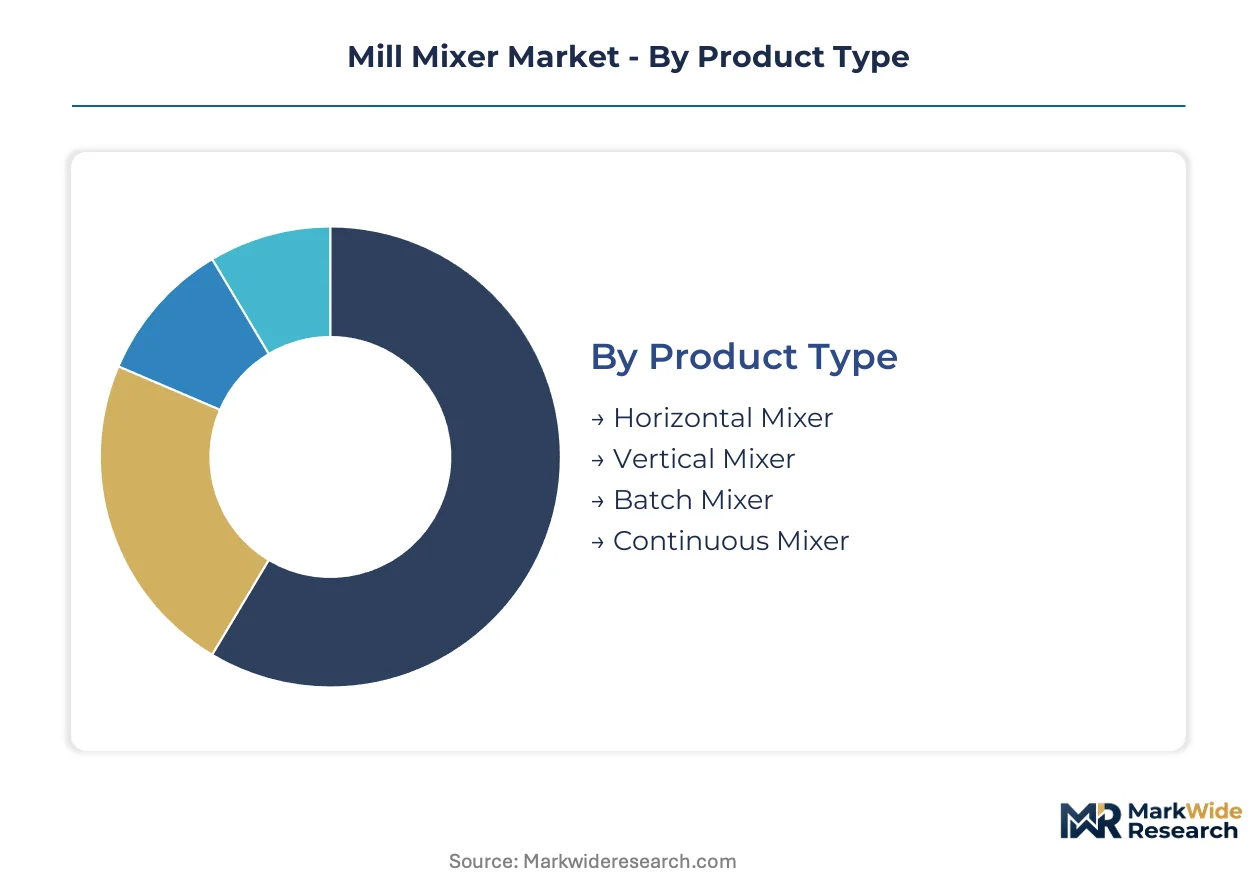
Mill mixer procurement patterns diverge sharply across operational scales and regulatory exposure. Pharmaceutical manufacturers prioritize continuous architectures with real-time release capabilities, while food processors optimize for capital efficiency and rapid changeover.
Product Type:
Cost tier separates batch infrastructure from continuous processing investments, with capital intensity and validation burden driving portfolio allocation.
- Horizontal Mixer:Low-profile chamber geometry suits bulk dry blending with mature supply chains and standardized drive components. Food processors in Germany's baking corridors specify these units for flour premix operations where throughput volume outweighs precision demands.
- Continuous Mixer:Twin-screw extrusion architectures integrate directly into end-to-end production lines, compressing validation timelines for FDA quality-by-design compliance. Pharmaceutical manufacturers in Basel and Boston are retrofitting legacy batch facilities with these configurations to reduce clean-in-place downtime.
- Vertical Mixer:Gravity-fed discharge enables gentle handling of shear-sensitive formulations. Specialty chemical producers specify vertical geometries for coating applications.
- Batch Mixer:Isolated processing chambers dominate construction materials blending where lot traceability requirements remain minimal.
Horizontal mixer configurations hold installed capacity. Continuous mixer architectures are rotating up the share rankings.
End User:
Application maturity dictates specification stringency, with regulated industries imposing material certification and documentation requirements that commodity processors bypass.
- Pharmaceutical:cGMP equipment qualification mandates traceable stainless steel grades and statistical process control documentation. CDSCO manufacturing license reforms in India are expanding demand for qualified mixing equipment in Hyderabad and Ahmedabad clusters.
- Food Processing:FSSAI hygiene standards and rapid changeover requirements favor modular sub-assembly designs. Midwest agricultural processing corridors specify horizontal ribbon mixers for grain premix operations.
- Chemical Processing:REACH substance restrictions constrain alloy selection for corrosion-resistant chambers. European fabricators face margin pressure from nickel and molybdenum price volatility.
- Construction:Heavy-duty mixing for cementitious materials tolerates carbon-steel construction with minimal regulatory overlay.
Food processing retains volume leadership. Pharmaceutical applications are climbing the fastest on value contribution.
Technology:
Shear intensity and wear characteristics determine technology selection, with auger geometry customization separating premium suppliers from commodity fabricators.
- Screw Mixing:Modular auger architectures enable rapid geometry swaps without facility shutdowns. Equipment-as-a-service models are transferring obsolescence risk from end users to suppliers through standardized sub-assembly interfaces.
- Ribbon Mixing:Counter-rotating helical ribbons achieve rapid homogenization of powders and granular materials. Construction materials processors specify these units for heavy-duty blending where abrasive wear dominates lifecycle economics.
- Paddle Mixing:Low-shear gentle handling suits coating applications where particle integrity determines product quality.
- Auger Mixing:Precision-engineered flighting enables controlled conveyance and blending in single-pass configurations.
Ribbon mixing holds installed capacity. Screw mixing architectures are gaining share fastest through modular upgrade pathways.
Application:
Customer concentration patterns separate commodity blending from specialized processing, with contract manufacturing organization procurement standardization reshaping vendor selection cycles.
- Dry Blending:Powder homogenization at controlled moisture levels dominates pharmaceutical excipient preparation. Large CDMOs in Ireland and Singapore are consolidating approved equipment lists to streamline multi-site technology transfer.
- Heavy-Duty Mixing:Abrasive material handling demands wear-resistant auger components sourced from captive Central European foundries. Stuttgart precision engineering clusters enable rapid prototyping of specialized geometries.
- Baking:Flour premix and dough development operations specify horizontal configurations with sanitary finishes.
- Coating:Gentle particle handling requirements favor paddle or vertical mixer architectures.
Heavy-duty mixing holds installed capacity. Dry blending applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and food processors concentrate procurement authority in distinct geographic clusters, with regulatory stringency and precision engineering capabilities determining supplier selection criteria across national markets.
Germany
Precision engineering clusters in Stuttgart and Munich fabricate specialized auger geometries for FDA and EMA-regulated pharmaceutical lines. REACH substance restrictions mandate traceable stainless steel grades, forcing alloy substitution in legacy mixing chambers. Baden-Württemberg suppliers dominate high-wear component casting for continuous processing equipment.
United States
OSHA machine guarding standards and FDA cGMP equipment qualification requirements shape design priorities for domestic fabricators serving pharmaceutical manufacturers in Greater Boston and Research Triangle Park. Midwest agricultural processing corridors specify horizontal ribbon mixers for grain premix operations. Cleanroom retrofit complexity extends payback periods for continuous mixer investments beyond typical capital planning horizons.
India
CDSCO manufacturing license reforms and PLI scheme incentives for active pharmaceutical ingredient production expand demand for cGMP-qualified mixing equipment. Hyderabad and Ahmedabad clusters attract investment from contract manufacturing organizations consolidating approved equipment lists. FSSAI hygiene standards drive modular sub-assembly adoption in food processing applications.
Switzerland
Swissmedic oversight and EMA guideline convergence tighten validation requirements for real-time release testing systems in Basel pharmaceutical manufacturing. Precision equipment suppliers integrate inline near-infrared spectroscopy into auger housing designs to demonstrate statistical process control capabilities. The country's pharmaceutical equipment sector commands premium positioning through documentation expertise.
China
NMPA pharmaceutical equipment standards and MIIT industrial upgrading directives accelerate domestic substitution in precision mixing technology. Yangtze River Delta manufacturing bases expand capacity for stainless steel casting to reduce dependence on Central European foundry supply. GB standards compliance enables export eligibility for equipment serving regulated industries in Southeast Asian markets.
Mill Mixer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by regulatory documentation capabilities and foundry integration depth. The vendor base clusters around three strategic archetypes: precision engineering specialists with captive casting operations, agricultural equipment conglomerates leveraging dealer density, and diversified industrial groups integrating aseptic interfaces. Consolidation pressure intensifies as contract manufacturing organizations narrow approved vendor lists, while backward integration into alloy supply chains emerges as a defensive maneuver against nickel and molybdenum price volatility.
Among North American and European fabricators, NDEco exemplifies the foundry-integrated archetype through upstream control over high-wear component quality. KUHN North America INC. anchors the agricultural processing segment through dense distribution infrastructure across Midwest grain corridors. Tetra Laval International S.A. occupies a position at the aseptic integration frontier, representing the convergence between precision mixing and sterile filling interfaces that reduces customer qualification burden in pharmaceutical applications.
| Leading Market Players |
|---|
| NDEco |
| Supreme International Ltd. |
| KUHN North America INC. |
| Grupo Tatoma |
| Triolite |
| Groupe Anderson |
| SILOKING Mayer |
| Seko Industries |
| Tetra Laval International S.A. |
| Others |
Supply & Pricing Matrix
Stuttgart precision engineering clusters control premium alloy casting capacity for wear-resistant auger components, translating foundry bottleneck leverage into sustained pricing power for continuous mixer configurations serving FDA-regulated pharmaceutical lines.
Pricing Analysis
Fixed-price pharmaceutical contracts with nickel and molybdenum indexation clauses dominate equipment procurement, tying mixer chamber costs to London Metal Exchange volatility. Three-tier pricing structure across cGMP-qualified, standard sanitary, and economy carbon-steel levels separates documentation-heavy pharmaceutical tiers from commodity construction applications. Cost compression in European fabricator margins is intensifying because legacy alloy substitution under REACH mandates accelerates replacement demand without corresponding price elasticity. Contract manufacturing organizations exhibit lowest price sensitivity due to multi-site qualification burdens, while independent food processors negotiate aggressively on capital recovery timelines.
Supply Chain Analysis
Central European captive foundries and Yangtze River Delta stainless steel casting bases hold primary capacity for corrosion-resistant mixing chambers. Mill mixer production draws from nickel-molybdenum alloy feedstock, precision-machined drive components, and certified sanitary surface finishes. Single-source vulnerability concentrates in Baden-Württemberg high-wear component supply, where integrated OEMs control proprietary auger geometries. Distribution runs through authorized dealer networks in Midwest agricultural corridors and direct specification sales for pharmaceutical OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and remote condition monitoring services are expanding faster than hardware replacement cycles, converting capital equipment relationships into recurring revenue architectures.
For Market Incumbents: Build documentation expertise moats through captive cGMP qualification teams that compress pharmaceutical customer validation timelines. Deepen backward integration into specialty alloy supply chains to buffer margin erosion from nickel price volatility. Threat substitution from modular screw-mixing platforms demands preemptive equipment-as-a-service offerings that transfer obsolescence risk from buyers. For New Entrants and Emerging Players: Hyderabad and Ahmedabad pharmaceutical manufacturing clusters offer underpenetrated entry points where CDSCO license reforms expand cGMP equipment demand without entrenched incumbent relationships. Target aseptic integration white space by pre-validating sterile isolator interfaces that reduce customer qualification burden. Go-to-market leverage rests on remote service capabilities that bypass OEM aftermarket networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision engineering specialists with captive foundry integration and FDA documentation capabilities over agricultural equipment conglomerates facing dealer network consolidation pressure. Long-term viability hinges on continuous manufacturing adoption curves in pharmaceutical processing. Acquisition screening should prioritize auger geometry customization expertise and statistical process control instrumentation integration. Watch FDA quality-by-design guideline enforcement intensity as inflection signal for twin-screw extrusion mixer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Integration | Upstream alloy supply control insulates margins from nickel volatility squeezing European fabricators. |
| Equipment-as-a-Service Launch | Recurring revenue models transfer obsolescence risk while locking pharmaceutical customers into long-term relationships. |
| Aseptic Interface Pre-validation | Pre-qualified sterile isolator integration reduces Basel and Boston pharmaceutical manufacturer qualification burden. |
| Predictive Maintenance Platform | Remote auger wear monitoring captures aftermarket margin pools bypassing traditional OEM service networks. |
| India Market Entry Partnership | Hyderabad CDMO consolidation creates demand concentration for cGMP-qualified mixing equipment suppliers. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, pharmaceutical manufacturing executives, and aftermarket service heads anchored the qualitative base for this analysis. Primary interview findings triangulated against SEC 10-K filings, FDA cGMP equipment qualification databases, EMA continuous manufacturing guidance documents, and European foundry production records. Bottom-up equipment shipment estimates cross-validated with top-down pharmaceutical capital expenditure tracking across the analysis window.
Scenario-bracketing around regulatory enforcement intensity and alloy price volatility shaped the projection framework. Segmentation modeling incorporated product architecture, end-use industry regulatory exposure, technology shear intensity, and geographic precision engineering cluster concentration. CAGRs derived from installed base replacement cycles and continuous manufacturing adoption curve analysis, with pharmaceutical quality-by-design compliance timelines and food processing capital efficiency requirements as primary forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular platform disruptors or Chinese stainless steel casting expansions would shift outcomes beyond modeled ranges. Quarterly review of FDA warning letter trends, nickel futures curve movements, and CDSCO manufacturing license issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Brewery Equipment Market