
 Middle East and Africa Digital Signage Market | 2026-2036
Middle East and Africa Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Digital Signage Market Foresight
Cloud-native content management is narrowing the gap between centralized control and edge deployment across the Middle East and Africa. Samsung Electronics leverages its semiconductor-to-display supply chain to sustain price competitiveness in high-brightness outdoor installations. LG Electronics anchors its position through specialized hospitality solutions tailored to Gulf luxury hotel chains. Sharp NEC Display Solutions competes on extended product lifecycles that reduce total cost of ownership for airport operators.
Middle East and Africa digital signage comprises networked electronic display systems ranging from 55-inch indoor LCD panels to modular outdoor LED walls exceeding 10,000 nits brightness, driven by media players and software platforms that schedule, distribute, and analyze visual content for commercial communication. LED display technology captures premium margin pools in the region's outdoor advertising and stadium sectors due to superior luminance and energy efficiency in high-ambient-light environments. Floor-standing kiosk installations represent the fastest-growing installation type as retailers and transit authorities deploy interactive wayfinding and self-service terminals across Saudi Arabia's giga-projects and South Africa's urban renewal zones.
Saudi Arabia's Communications and Information Technology Commission enforces network infrastructure standards that shape how digital signage systems connect across the Kingdom's smart city developments. South Africa's Protection of Personal Information Act restricts audience measurement analytics, compelling vendors to rearchitect data processing workflows. Stakeholders must monitor evolving Gulf data localization requirements and decide whether to deploy regional cloud instances or pursue edge-computing architectures that keep sensitive analytics within national boundaries.
Market Dynamics
Cloud-native content management platforms are compressing deployment timelines across the Middle East and Africa, enabling centralized control over geographically dispersed screen networks while reducing on-site technical dependencies. This architectural shift is restructuring vendor relationships and procurement patterns across retail, transit, and hospitality verticals.
Growth Catalysts
- Giga-project construction:Saudi Arabia's NEOM, Red Sea Project, and Qiddiya developments mandate digital wayfinding and experiential media installations across millions of square meters of new commercial space.
- POPIA compliance infrastructure:South Africa's data protection framework is forcing vendors to develop privacy-preserving audience analytics, creating competitive differentiation for compliant solution providers.
- High-brightness LED maturation:Advances in chip-on-board packaging and thermal management are extending outdoor display lifecycles in Gulf ambient conditions exceeding 50°C.
Market Restraints
- Import duty structures:Gulf Cooperation Council customs classifications impose varying tariff rates on display panels versus fully assembled systems, fragmenting supply chain economics.
- Semiconductor supply concentration:Driver IC and microcontroller sourcing remains concentrated among Taiwanese and South Korean foundries, exposing regional integrators to allocation volatility.
- Power grid instability:Sub-Saharan markets outside South Africa face intermittent electricity supply, degrading display uptime and accelerating hardware degradation.
Strategic Opportunities
- Egyptian urban corridor:Cairo and Alexandria smart city initiatives remain underpenetrated for large-format outdoor LED relative to Gulf peers, offering first-mover positioning.
- Edge AI convergence:On-device computer vision for anonymous audience measurement is converging with 5G network slicing to enable real-time content adaptation without cloud dependency.
- Subscription content models:Regional media houses are launching programmatic advertising marketplaces that transform capital-intensive display networks into recurring-revenue infrastructure.
Industry Challenges
- Localization engineering talent:Arabic-language UX design and right-to-left content management expertise remains scarce across systems integrators serving Gulf luxury retail.
- Legacy AV infrastructure:Existing mall and airport deployments rely on proprietary control protocols that complicate migration to IP-based content distribution.
- Certification timelines:CITC type approval for networked devices in Saudi Arabia extends deployment schedules by 8-14 weeks versus non-connected alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Digital Signage Market |
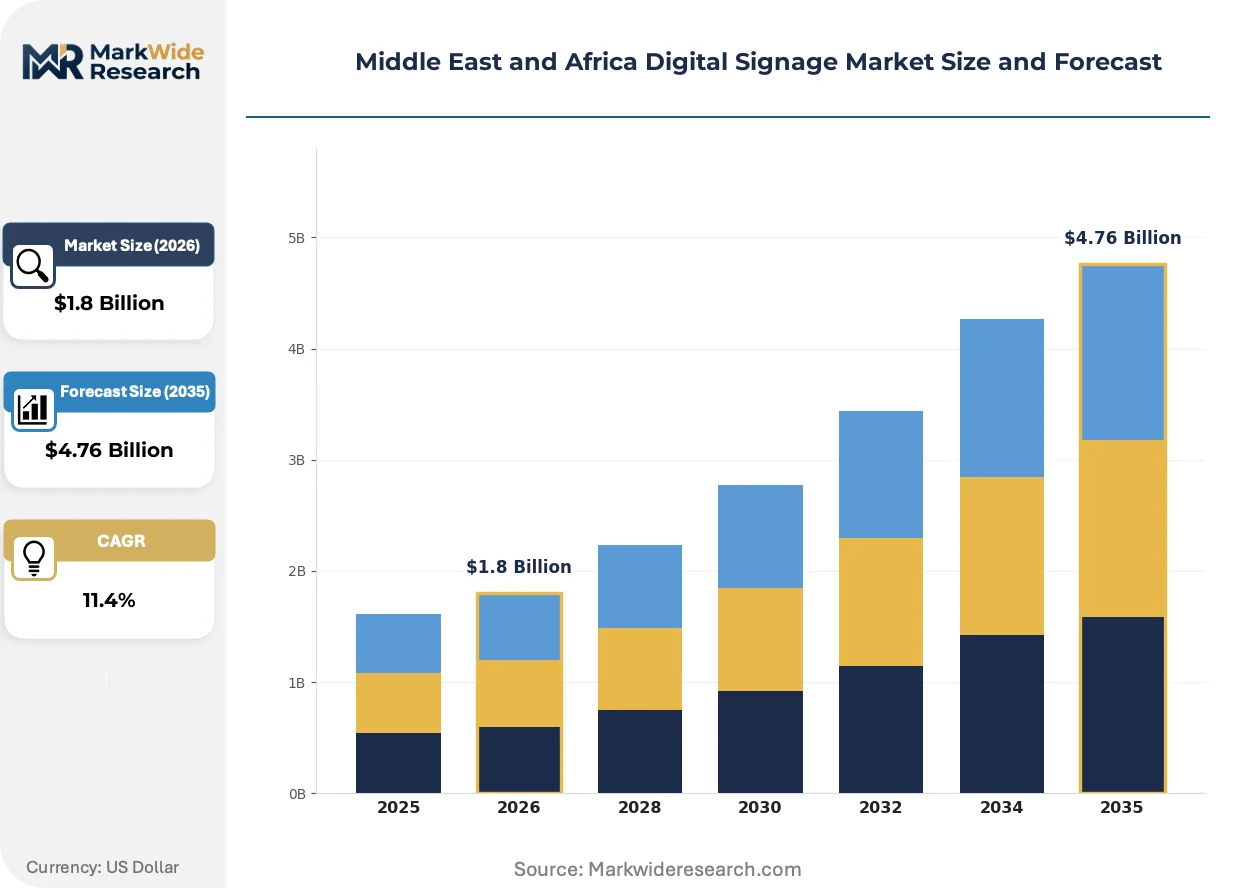
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, Projection, Plasma Installation Type: Wall-mounted, Floor-standing, Outdoor, Kiosk Technology: Digital Signage Software, Content Management, Display Technology, Network Infrastructure End User: Retail, Transportation, Hospitality, Education |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics Inc., Sharp NEC Display Solutions, Ltd., Sony Group Corporation, Koninklijke Philips N.V., NEC Corporation, Panasonic Corporation, Scala, Inc., BrightSign LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Digital Signage Market Shifts & Advancements
Display technology architectures are fragmenting across application requirements, with diverging optimization paths for indoor precision versus outdoor durability. This specialization is forcing vendors to abandon universal product strategies in favor of vertical-specific engineering.
MicroLED is hybridizing with conventional SMD LED architectures in premium outdoor installations, combining the former's pixel density advantages with the latter's field-serviceability and supply chain maturity. Dubai's hospitality developers are specifying hybrid configurations for facade displays requiring both daytime visibility and fine-pitch nighttime resolution. The technology convergence is compressing price premiums for sub-2.5mm outdoor pitch classes previously reserved for indoor applications.
South Africa's POPIA enforcement is mandating privacy-by-design for audience measurement systems, prohibiting biometric identification and restricting data retention periods. Vendors are rearchitecting analytics pipelines to process visual data at the edge, discarding raw imagery before network transmission. Retail chains in Johannesburg and Cape Town are prioritizing compliant solutions over feature-rich alternatives, shifting competitive differentiation toward data governance certifications.
Procurement patterns among Gulf hospitality operators are compressing vendor selection cycles, with flagship property developers bundling digital signage into master systems contracts rather than discrete technology tenders. Integrated facility management providers are absorbing display procurement responsibilities, displacing direct manufacturer relationships. This consolidation is most visible in Abu Dhabi's cultural district developments, where concession operators delegate technology specification to appointed managing agents.
Middle East and Africa Digital Signage Market Segmentation
Segmentation in Middle East and Africa digital signage reveals how divergent technical requirements across display technologies, installation environments, and vertical applications reshape procurement priorities. Service intensity varies sharply between outdoor LED deployments demanding thermal management expertise and software-centric content management platforms requiring continuous updates.
Product Type:
After-sales-service intensity diverges dramatically across display technologies, with outdoor LED requiring field-level component replacement capabilities and LCD demanding pixel-level calibration support.
- LED:Chip-on-board and SMD architectures dominate large-format outdoor advertising across Dubai's Sheikh Zayed Road corridor and Riyadh's King Abdullah Financial District. Thermal management in Gulf ambient conditions exceeding 50°C drives recurring service contracts and specialized technician deployment.
- LCD:High-brightness panels with 700-2500 nits output anchor indoor retail and hospitality networks across Abu Dhabi's Yas Island developments and Johannesburg's mall renovations. Panel replacement cycles and backlight degradation create predictable aftermarket revenue streams for integrators.
- Projection:Laser phosphor and DLP systems serve temporary experiential installations and museum applications where physical display footprint must vanish between uses.
- Plasma:Legacy installations persist in specific control room and broadcast monitoring contexts where burn-in resistance and color accuracy outweigh efficiency concerns.
By volume, LCD leads. By growth pace, LED is ahead.
Installation Type:
Physical mounting configuration determines both upfront engineering complexity and long-term maintenance access economics across the region's divergent built environments.
- Kiosk:Interactive self-service terminals are expanding most quickly across Saudi giga-projects and South African transit hubs, combining wayfinding, payment, and audience analytics in single footprint deployments. POPIA-compliant edge processing requirements add software architecture complexity.
- Outdoor:Modular LED walls exceeding 10,000 nits brightness serve advertising and stadium applications from Doha to Cape Town. Structural engineering for wind loading and sand ingress protection dominates total cost of ownership calculations.
- Wall-mounted:Indoor LCD and narrow-bezel LED configurations dominate retail and hospitality verticals where space efficiency and aesthetic integration take priority.
- Floor-standing:Freestanding displays serve lobby and atrium applications across Gulf luxury hotel chains, with portable deployment options for exhibition and event use cases.
By installed base, wall-mounted dominates. By expansion trajectory, kiosk is gaining share fastest.
Technology:
Technology stack composition shifts margin capture between hardware manufacturers, software vendors, and systems integrators as cloud-native architectures displace on-premise deployments.
- Display Technology:Panel manufacturing and LED module assembly concentrate margin in East Asian supply chains, with regional integrators adding value through customization and installation.
- Content Management:Cloud-native platforms compress deployment timelines and enable centralized control over geographically dispersed networks across multi-site retail and hospitality operators.
- Digital Signage Software:Scheduling, distribution, and analytics applications face localization requirements for Arabic right-to-left content and POPIA-compliant data handling.
- Network Infrastructure:5G slicing and edge computing architectures are reshaping connectivity economics for real-time content adaptation in high-density urban deployments.
By revenue concentration, display technology leads. By margin expansion, content management is climbing fastest.
End User:
Vertical-specific application requirements fragment procurement patterns, with each end-use segment imposing distinct performance specifications and compliance frameworks.
- Retail:Programmable advertising networks and interactive product discovery installations span Gulf mall developments and South African urban renewal zones. Audience measurement analytics face POPIA restrictions in Johannesburg and Cape Town operations.
- Transportation:Wayfinding and real-time information systems anchor Dubai Metro, Abu Dhabi airport, and Riyadh metro deployments. CITC certification requirements extend Saudi deployment schedules.
- Hospitality:Experiential media and guest-facing information displays concentrate in Dubai and Abu Dhabi luxury developments where master systems contracts bundle signage into facility management agreements.
- Education:Campus-wide communication networks and interactive learning installations serve Saudi and UAE higher education expansion, with procurement constrained by public sector tendering cycles.
By deployment value, retail leads. By project pipeline, transportation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
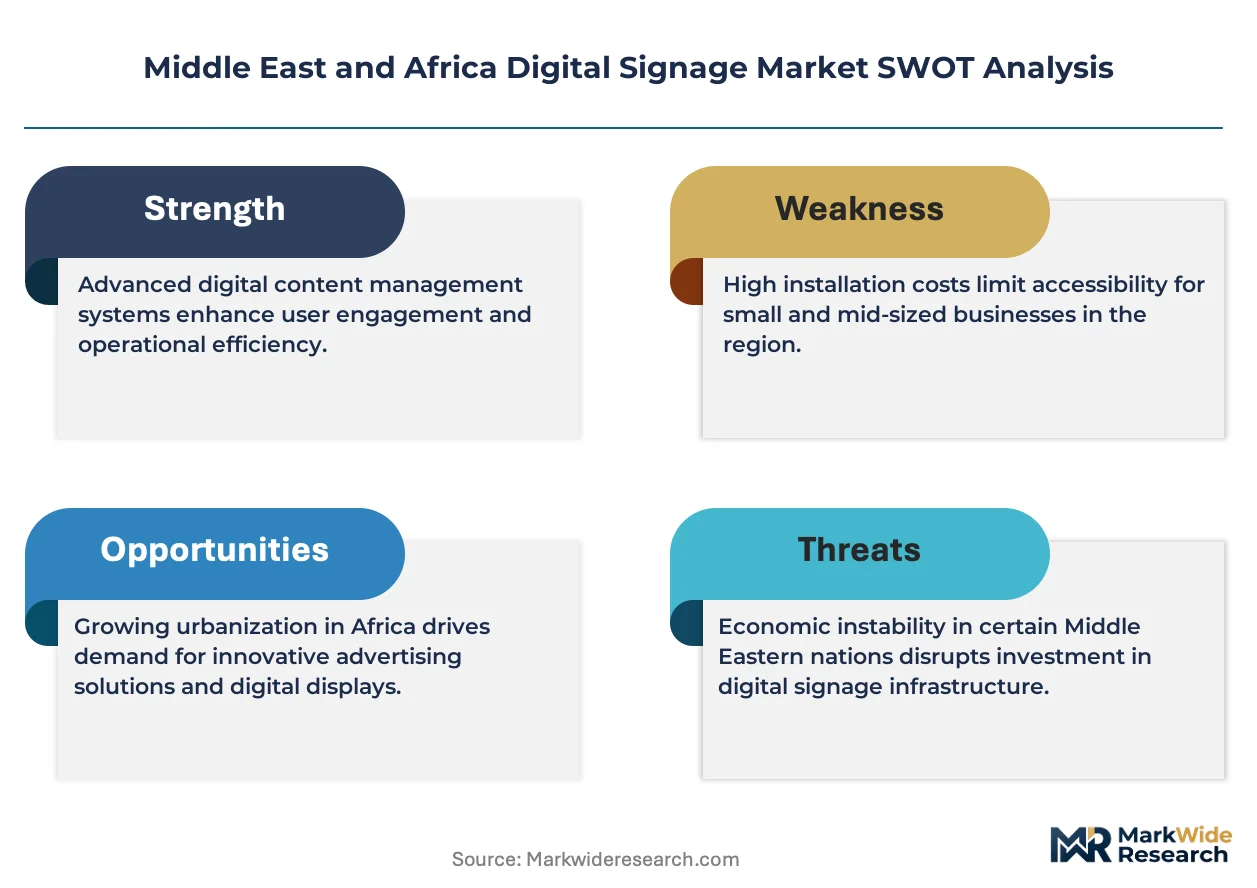
Buyer archetypes concentrate around Gulf sovereign wealth-backed developers, South African retail conglomerates, and Saudi giga-project master planners. These entities command procurement scale that reshapes vendor economics. Their geographic dispersion creates divergent regulatory exposure across data protection, import classification, and network certification regimes.
United Arab Emirates
Dubai's smart city investments and Abu Dhabi's cultural district developments anchor large-format LED demand in transportation and hospitality venues. MOHAP data governance guidelines influence how audience analytics systems process visual data in healthcare-adjacent retail environments. Dubai's Sheikh Zayed Road corridor concentrates outdoor advertising deployments exceeding 10,000 nits brightness specifications.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya giga-developments mandate digital wayfinding across millions of square meters of new commercial space. CITC type approval requirements extend deployment schedules by 8-14 weeks for networked devices versus non-connected alternatives. Riyadh's King Abdullah Financial District hosts dense concentrations of outdoor LED advertising infrastructure subject to thermal management specifications for 50°C ambient conditions.
South Africa
Johannesburg and Cape Town retail chains drive interactive kiosk installations for wayfinding and self-service applications. POPIA restrictions on biometric identification and data retention periods force vendors to rearchitect analytics pipelines for edge processing. Urban renewal zones in Gauteng and Western Cape provinces concentrate procurement activity for compliant audience measurement systems.
Egypt
Cairo and Alexandria smart city initiatives remain underpenetrated for large-format outdoor LED relative to Gulf peers. The country's national telecommunications regulator shapes network infrastructure standards for connected display deployments. New Administrative Capital construction creates concentrated demand for transportation and hospitality digital signage specifications.
Qatar
Doha stadium and transit infrastructure investments sustain high-brightness LED demand for outdoor advertising and wayfinding applications. Import duty structures on display panels versus fully assembled systems fragment supply chain economics for systems integrators. Lusail City development concentrates experiential media installations in hospitality and retail verticals.
Middle East and Africa Digital Signage Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement influence across retail, hospitality, and transportation verticals. The market exhibits tiered concentration where integrated facility management providers absorb display procurement responsibilities from direct manufacturer relationships. Three archetypes dominate: semiconductor-to-display supply chain owners, hospitality-focused solution bundlers, and extended-lifecycle service contractors. Geographic expansion through master systems contracts and portfolio diversification into cloud-native content platforms represent the dominant competitive moves.
Within the supply chain-integrated tier, Samsung Electronics Co., Ltd. and LG Electronics Inc. occupy positions shaped by captive component sourcing and vertical manufacturing scope. Sharp NEC Display Solutions, Ltd. sits within the extended-lifecycle specialist archetype, with procurement patterns among airport operators favoring total cost of ownership reductions over upfront capital expenditure. These three entities exemplify how vendor selection cycles compress when flagship property developers bundle digital signage into integrated facility management agreements rather than discrete technology tenders.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Sharp NEC Display Solutions, Ltd. |
| Sony Group Corporation |
| Koninklijke Philips N.V. |
| NEC Corporation |
| Panasonic Corporation |
| Scala, Inc. |
| BrightSign LLC |
| Others |
Supply & Pricing Matrix
Jebel Ali Port freight corridors connecting East Asian manufacturing hubs to Gulf distribution centers impose cost dynamics that amplify supply concentration effects and compress downstream price differentiation across installation tiers. Display panel procurement from concentrated foundry sources feeds into three-tier pricing structures that separate premium outdoor LED specifications from standard indoor LCD deployments and economy-grade projection systems.
Pricing Analysis
Cost-plus contracts with quarterly indexation to semiconductor commodity benchmarks dominate procurement agreements between Gulf systems integrators and display manufacturers. Price differentiation rests on thermal management certification grades for 50°C ambient operation and volume scale across NEOM-scale giga-project deployments. Cost compression in mid-brightness LCD tiers is intensifying because Taiwanese driver IC allocation volatility forces integrators to absorb buffer inventory carrying costs. Retail chains in South Africa exhibit highest price sensitivity due to POPIA compliance overhead, while Abu Dhabi luxury hospitality developers show lowest sensitivity given master systems contract bundling.
Supply Chain Analysis
Contract manufacturing concentration among Taiwanese ODMs and South Korean EMS providers controls display module assembly capacity for high-brightness outdoor specifications. Geographic supply concentration centers on China for LED chip packaging, South Korea for LCD panel fabrication, and Taiwan for driver IC production. Raw material dependencies span gallium nitride substrates, indium tin oxide coatings, and aluminum heat-dissipation frames. Single-source vulnerability in chip-on-board packaging technology exposes regional integrators to allocation disruptions during foundry capacity constraints. Distribution runs through Dubai-based logistics hubs serving Gulf Cooperation Council markets and Johannesburg distribution centers covering Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of Arabic-language UX engineering talent and POPIA-certified edge-computing architects constrains vendor execution capacity across high-value Gulf and South African deployments. This capability gap reshapes competitive moats around localized software development and compliance infrastructure.
For Market Incumbents: Pre-empt emerging cloud-native platform entrants by acquiring edge-AI analytics specialists with POPIA-compliant architecture credentials. Deepen backward integration into thermal management component sourcing to defend margin position against Taiwanese foundry allocation volatility. Secure exclusive technician certification programs with Saudi CITC to extend deployment timeline advantages over non-compliant competitors. For New Entrants and Emerging Players: Pursue Egyptian urban corridor smart city initiatives where large-format outdoor LED penetration lags Gulf peers by several deployment cycles. Target Cairo New Administrative Capital transportation specifications with bundled content management and hardware procurement offers. Establish partnership channels with integrated facility management providers displacing direct manufacturer relationships in Abu Dhabi cultural district developments. For Investors and Strategic Acquirers: Regional software houses with captive Arabic right-to-left content management platforms represent the most defensible acquisition archetype against global vendor expansion. Long-term viability hinges on recurring-revenue transformation of capital-intensive display networks through programmatic advertising marketplace integration. Monitor Gulf data localization regulation progression as inflection indicator for edge-computing architecture valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Platform Integration | Enables POPIA-compliant audience analytics without cloud dependency for South African retail chains. |
| Regional Cloud Instance Deployment | Satisfies Saudi CITC data localization requirements for NEOM giga-project network infrastructure. |
| Extended Lifecycle Service Contracting | Captures aftermarket revenue from thermal management maintenance in 50°C Gulf ambient conditions. |
| Arabic UX Localization Investment | Addresses capability scarcity constraining Gulf luxury retail and hospitality deployment execution. |
| Programmatic Advertising Marketplace Launch | Transforms capital-intensive LED networks into recurring-revenue infrastructure for media house partners. |
Research Methodology
Desk research of customs trade databases, semiconductor foundry capacity disclosures, and Gulf smart city procurement records preceded structured interviews with systems integration executives, CITC certification consultants, POPIA compliance officers, and hospitality technology procurement directors. Primary fieldwork across Dubai, Riyadh, Johannesburg, and Cairo validated secondary estimates through bottom-up installation tracking and top-down market sizing triangulation.
Assumption sets held fixed Gulf sovereign wealth commitment to giga-project timelines and South African POPIA enforcement intensity while varying semiconductor allocation scenarios and Egyptian regulatory progression. Segmentation modeling spanned display technology, installation environment, content management deployment architecture, and vertical application across retail, transportation, hospitality, and education end uses. CAGRs derived from logistic adoption curve fitting to historical deployment trajectories, incorporating 5G network slicing rollout schedules and edge-computing hardware cost decline curves as technology-specific inputs.
Sensitivities concentrate around Taiwanese foundry capacity allocation volatility, Saudi CITC certification timeline extensions, and South African POPIA enforcement interpretation shifts. Forecasts embed documented assumptions regarding Gulf thermal management specification stability and Egyptian smart city funding continuity. Quarterly review of semiconductor spot pricing indices, CITC type approval queue lengths, and POPIA regulatory guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ediscovery Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Social Networking App Market
Digital Solutions
IT Asset Management Market
Digital Solutions
In-App Purchase Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Online Voting System Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Data Broker Market