
 Case Hardening Steel Market | 2026-2036
Case Hardening Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Case Hardening Steel Market Insights
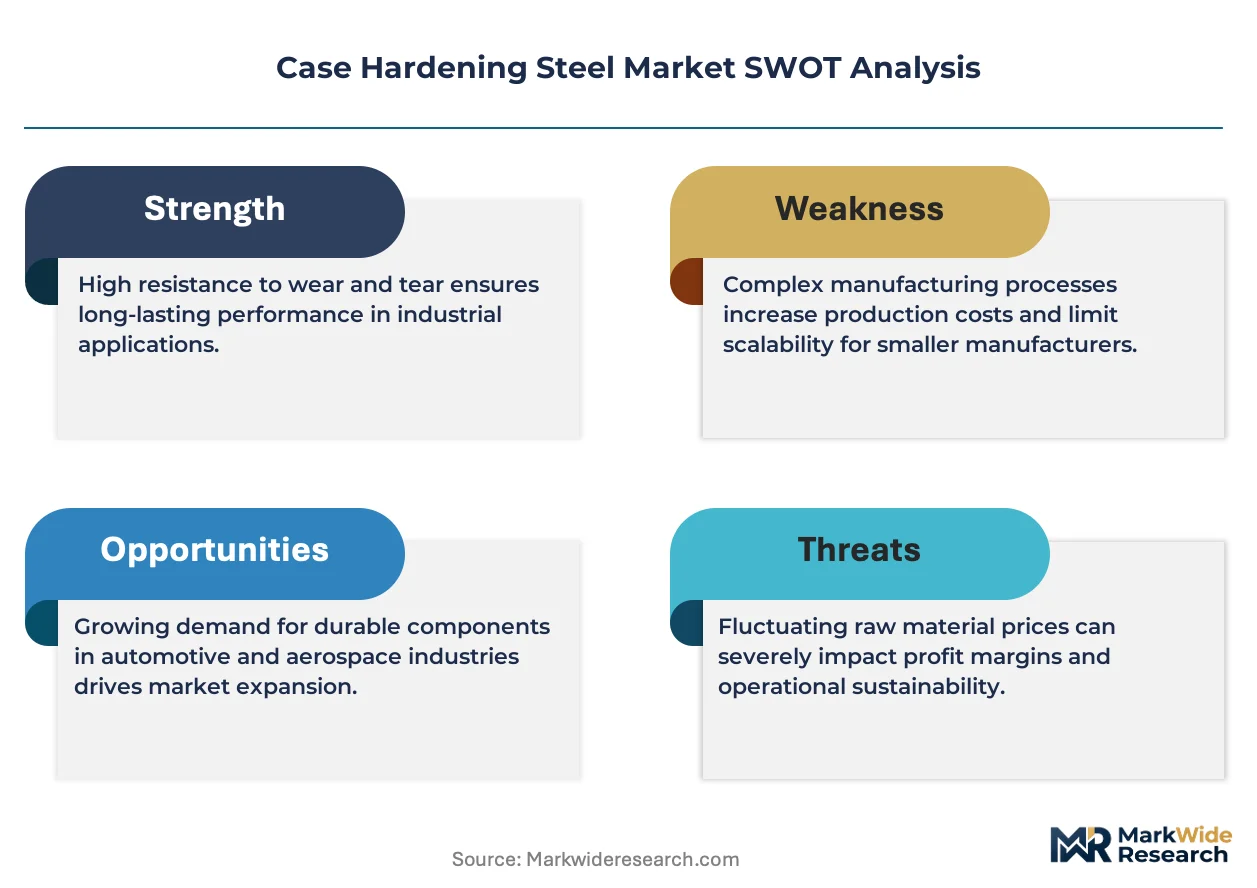
Asset-light leasing models for vacuum carburizing furnaces are rewriting capital barriers for mid-sized forgers. Voestalpine AG leverages its Austrian steelmaking complex to sustain captive supply of precision-engineered case hardening grades. Nucor Corporation competes through electric-arc-furnace flexibility, anchoring quick-turnaround bar production for North American gear shops. Sandvik specializes in premium cleanliness standards, differentiating its offerings for critical aerospace bearing applications.
Case hardening steel refers to low-carbon or low-alloy steels engineered for surface enrichment via carburizing, carbonitriding, or nitriding to achieve case depths of 0.5–3.0 mm and surface hardness exceeding 60 HRC while retaining a ductile core. This dual-property architecture serves transmission gears, camshafts, and heavy-duty machinery components subjected to rolling contact fatigue and impact loading. Among type segments, AISI 8620 dominates volume flows for automotive gears due to its balanced hardenability and machinability, while AISI 15B30 captures expanding share in machinery parts where boron microadditions reduce alloy costs without sacrificing performance. Application segmentation shows hydraulic cylinders generating disproportionate margin pools as oil and gas operators specify ultraclean vacuum-degassed material for sour-service reliability.
EPA emission standards and NHTSA fuel-economy regulations tighten dimensional tolerances on powertrain components, directly elevating specification thresholds for case depth uniformity and core hardness consistency. REACH restrictions on hexavalent chromium post-treatment accelerate European migration to alternative surface finishing chemistries, reshaping supplier qualification protocols. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving alloy-surcharge indices recalibrate sourcing economics between integrated mills and electric-arc-furnace operators.
Market Dynamics
Automotive gear manufacturers are intensifying procurement of vacuum-degassed low-alloy grades to satisfy fatigue-life thresholds imposed by EPA and NHTSA emissions-efficiency mandates, compressing supplier qualification timelines and elevating cleanliness specifications across the value chain.
Growth Catalysts
- EPA and NHTSA powertrain regulations:Tightened fuel-economy and emissions standards force transmission component suppliers to specify case hardening steels with superior core toughness and uniform case depth, expanding premium-grade offtake.
- Vacuum carburizing furnace diffusion:Asset-light leasing models for vacuum carburizing equipment eliminate capital barriers for mid-sized forgers, enabling precision heat-treatment capacity expansion without balance-sheet strain.
- German automotive supply base concentration:Premium-grade consumption clusters in Germany where OEMs and Tier-1 suppliers anchor specification-setting for European powertrain sourcing.
Market Restraints
- Alloy surcharge volatility:Nickel and molybdenum price swings embedded in mill pricing formulas compress margin predictability for distributors serving job-shop gear manufacturers.
- Integrated mill supply concentration:Captive supply from Austrian and German steelmaking complexes limits independent sourcing flexibility for North American precision forgers.
- REACH hexavalent chromium restrictions:Post-treatment chemistry bans force qualification of alternative surface finishing protocols, extending supplier approval cycles.
Strategic Opportunities
- India automotive component manufacturing:PLI scheme incentives for advanced automotive technology manufacturing create import-substitution potential for domestic case hardening steel production.
- Hydraulic cylinder sour-service specification:Oil and gas operators in North American shale basins specify ultraclean vacuum-degassed material, generating disproportionate margin pools relative to commodity gear grades.
- Digital twin convergence with heat-treatment:Integration of predictive metallurgical modeling with furnace control systems enables real-time case depth optimization, reducing rejection rates.
Industry Challenges
- Vacuum carburizing technician scarcity:Specialized furnace operation and atmosphere control expertise remains concentrated among aging workforce cohorts in mature manufacturing regions.
- Core hardness consistency certification:Statistical process control documentation for automotive PPAP submissions demands sustained capital investment in inline testing infrastructure.
- Legacy batch furnace integration:Retrofitting existing atmospheric carburizing lines with sensor networks for Industry 4.0 traceability generates operational friction and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Hardening Steel Market |
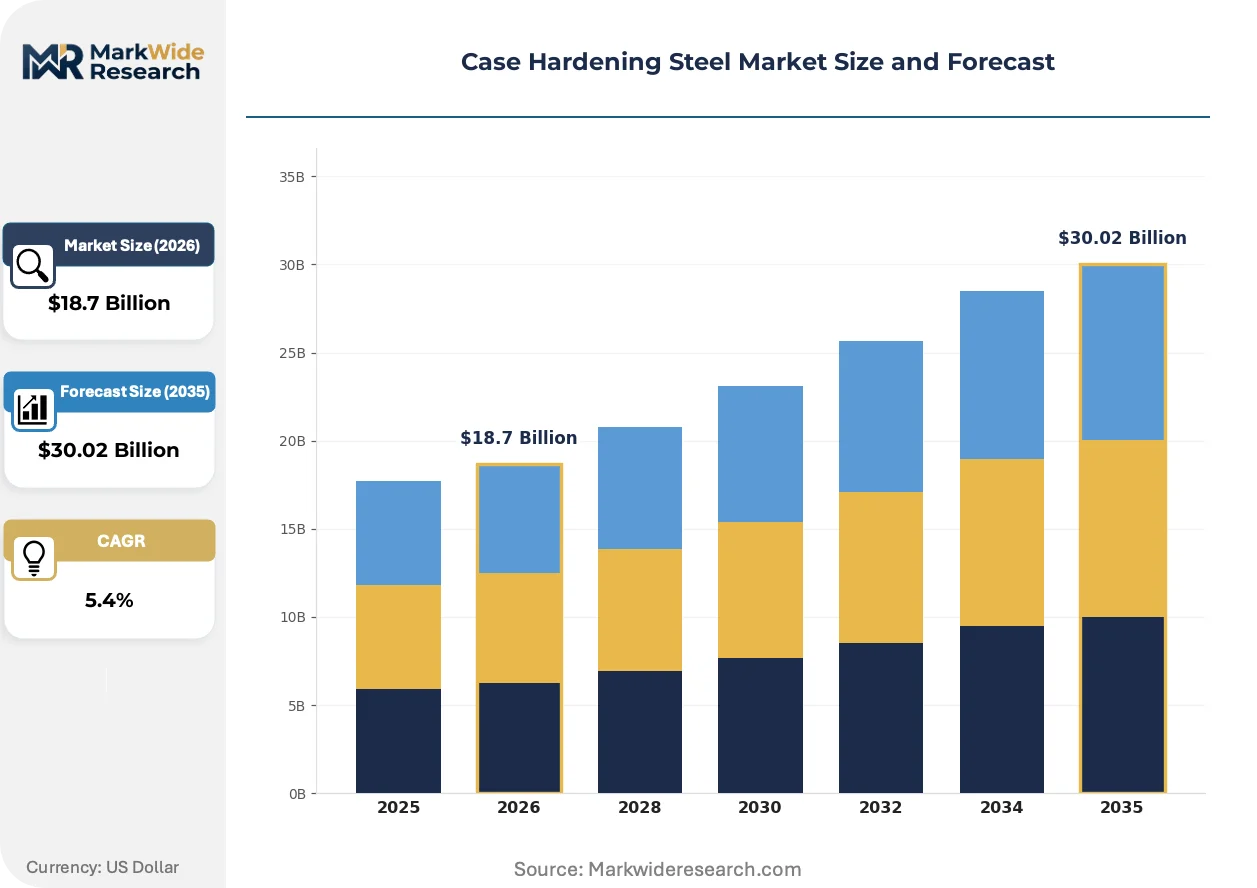
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AISI 15B30, AISI 8620, AISI 4130, AISI 4140 Application: Automotive Gears, Machinery Parts, Pneumatic Tools, Hydraulic Cylinders End User: Aerospace, Automotive, Industrial Machinery, Oil & Gas Form: Bars, Sheets, Rounds, Plates |
| Companies Covered | Swiss Steel Group, Nippon Steel, ArcelorMittal, Hudson Tool Steel Corporation, Nucor Corporation, Voestalpine AG, Sandvik, Tiangong International, Hitachi Metals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Hardening Steel Market Trends and Innovations
Process metallurgy and surface engineering are converging to redefine competitive differentiation, with cleanliness standards, regulatory chemistry bans, and procurement model innovation reshaping how specifications translate into contract awards.
Plasma nitriding is migrating from aerospace bearing applications into automotive camshaft production as Tier-1 suppliers seek distortion-free hardening alternatives to conventional carburizing. German powertrain specialists are piloting plasma-nitrided 42CrMo4 variants for high-volume camshaft lines, compressing post-heat-treatment grinding allowances and enabling near-net-shape forging economics previously unattainable with atmospheric carburizing cycles.
REACH restrictions on hexavalent chromium post-treatment are forcing European suppliers to qualify trivalent chromium and thin-film coating alternatives before 2025 sunset dates. The regulatory friction most acutely affects precision gear manufacturers serving automotive export markets, who must maintain dual-qualified surface finishing lines to satisfy divergent OEM specification pools across EU and non-EU assembly plants.
Leasing structures for vacuum carburizing furnaces are displacing traditional capital purchase models among mid-sized North American forgers. Equipment finance specialists now bundle maintenance, atmosphere gas supply, and metallurgical support into per-kg throughput contracts, enabling job shops to bid precision heat-treatment work without fixed-asset exposure. The model has gained strongest traction in Michigan and Ohio automotive supply corridors where demand volatility discourages balance-sheet-intensive capacity commitments.
Case Hardening Steel Market Segmentation
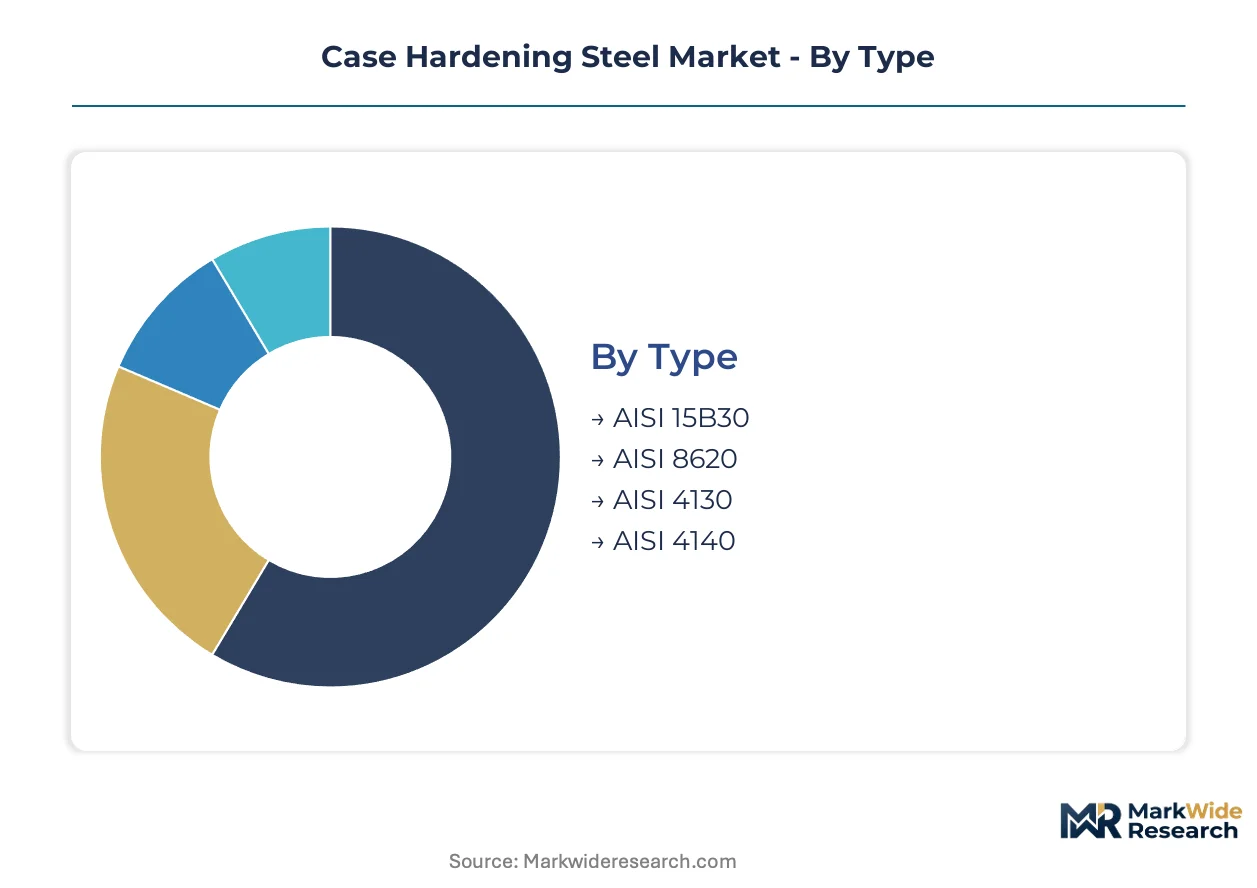
Segmentation in case hardening steel reveals how specification intensity varies sharply across end-use requirements. Automotive gear manufacturers demand vacuum-degassed cleanliness grades that command premium positioning, while industrial machinery procurement tolerates wider chemistry bands. Understanding these tiered demands enables suppliers to align mill capacity with margin-accretive contract pools.
Type:
After-sales service intensity escalates with alloy complexity, as boron-microalloyed grades require specialized metallurgical support for heat-treatment parameter optimization.
- AISI 8620:Nickel-chromium-molybdenum chemistry delivers balanced hardenability and machinability for medium-duty powertrain components. Demand concentrates in German automotive supply corridors where OEMs mandate fatigue-life documentation exceeding 10^7 cycles under EPA and NHTSA efficiency rules.
- AISI 15B30:Boron microadditions reduce nickel and molybdenum content while preserving hardenability, cutting alloy surcharges for cost-sensitive machinery applications. Procurement is accelerating in North American job shops seeking to offset nickel price volatility without sacrificing core toughness specifications.
- AISI 4130:Chromium-molybdenum construction suits higher-strength machinery shafts and aircraft landing gear components requiring through-hardening compatibility.
- AISI 4140:Elevated carbon and manganese content serves heavy-duty crankshafts and connecting rods in industrial compression equipment.
By volume, AISI 8620 leads. By growth pace, AISI 15B30 is expanding most quickly.
Application:
Cost tier stratification separates specification-intensive automotive procurement from price-elastic industrial segments.
- Automotive Gears:Transmission and differential components require 0.5–2.0 mm case depths with 60+ HRC surface hardness and ductile cores. German and Japanese OEMs enforce statistical process control documentation that extends supplier qualification cycles beyond 18 months.
- Hydraulic Cylinders:Oil and gas sour-service specifications demand vacuum-degassed ultraclean grades with sulfur below 0.008% for hydrogen sulfide exposure resistance. North American shale operators in the Permian and Bakken generate disproportionate margin pools relative to commodity gear specifications.
- Machinery Parts:General-purpose shafts and bearings tolerate wider chemistry tolerances, enabling integrated mill volume production with reduced testing overhead.
- Pneumatic Tools:Impact-rated components require surface hardness for wear resistance without the fatigue-life documentation burden of automotive applications.
Automotive Gears dominates volume flows. Hydraulic Cylinders climbs the fastest on sour-service specification premiums.
End User:
Customer type determines certification burden, with aerospace and automotive enforcing the most stringent material traceability protocols.
- Automotive:EPA and NHTSA fuel-economy mandates tighten dimensional tolerances on powertrain components, elevating case depth uniformity requirements and core hardness consistency thresholds across transmission and axle applications.
- Oil & Gas:North American operators specify vacuum-degassed material for downhole and surface equipment exposed to corrosive formation fluids, generating specification premiums that offset commodity steel margin compression.
- Industrial Machinery:Construction and agricultural equipment manufacturers prioritize machinability and weldability over premium cleanliness, sourcing from electric-arc-furnace operators with flexible bar production schedules.
- Aerospace:Bearing and landing gear applications impose premium cleanliness standards with oxide inclusion ratings per ASTM E45, limiting qualified supplier pools to specialized melt shops.
Automotive anchors volume demand. Oil & Gas posts the steepest expansion trajectory on energy infrastructure replacement cycles.
Form:
Supply concentration favors long-product mills with continuous casting and rolling capabilities for bar and round production.
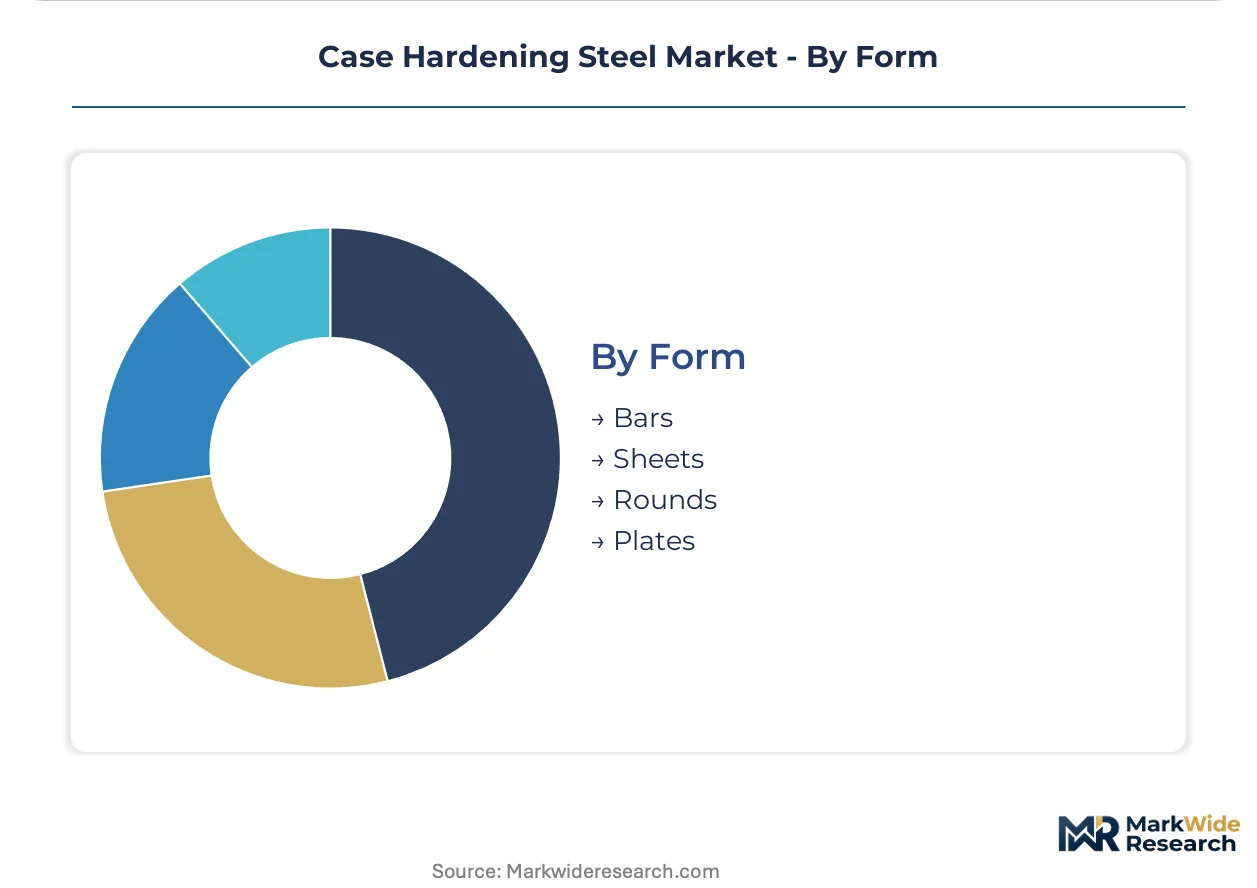
- Bars:Hot-rolled and cold-finished bar stock serves gear blank forging and direct machining applications, with German and Austrian integrated complexes dominating premium-grade supply.
- Rounds:Peeled and turned rounds enable near-net-shape forging economics for high-volume camshaft and crankshaft production lines.
- Sheets:Limited application in thin-walled structural components where surface hardening must coexist with forming requirements.
- Plates:Heavy-section plate serves mining and construction machinery frames requiring local surface hardening on wear surfaces.
Bars lead by tonnage. Rounds gain share fastest on precision forging automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive gear manufacturers concentrate procurement in German supply corridors, while North American shale operators drive premium-grade demand for sour-service hydraulic applications. Steel specification intensity varies sharply across regulatory jurisdictions.
Germany
EPA and NHTSA efficiency mandates filter through German OEM specification-setting, elevating vacuum-degassed cleanliness requirements for transmission gears. REACH hexavalent chromium restrictions accelerate migration to alternative surface finishing chemistries. The Baden-Württemberg and Bavaria automotive clusters anchor premium-grade consumption for powertrain component sourcing.
United States
North American shale operators in the Permian and Bakken basins specify ultraclean vacuum-degassed grades for hydraulic cylinder sour-service reliability. NHTSA fuel-economy standards tighten dimensional tolerances on domestic powertrain manufacturing. Michigan and Ohio automotive supply corridors absorb precision bar production from electric-arc-furnace operators.
China
Domestic automotive component manufacturing scales import-substitution programs for advanced gear steel grades. MIIT industrial upgrading directives prioritize cleanliness standards for critical mechanical components. Yangtze River Delta forging clusters expand vacuum carburizing capacity to serve transmission supply localization.
India
PLI scheme incentives for advanced automotive technology manufacturing create domestic case hardening steel production opportunities. BIS standards evolution tightens material certification protocols for gear and shaft applications. Maharashtra and Gujarat automotive component hubs intensify procurement of fatigue-life documented grades.
Japan
METI industrial competitiveness programs support precision steel development for transmission and bearing applications. JIS standards enforcement maintains strict inclusion rating requirements for automotive OEM qualification. Kansai and Chubu manufacturing belts concentrate heat-treatment expertise for camshaft and gear production.
Case Hardening Steel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated steelmaking complexes with captive melt shop capacity anchor premium-grade supply, while electric-arc-furnace operators flex bar production for cost-sensitive machinery segments. Strategic archetypes separate cleanliness-focused aerospace bearing specialists from scale-driven automotive gear suppliers. Dominant competitive moves include backward integration into precision forging and geographic expansion through distribution partnerships.
Among European integrated steelmakers, Voestalpine AG and Swiss Steel Group exemplify captive supply chain control from melt shop to precision bar finishing. ArcelorMittal occupies a position bridging volume automotive contracts with industrial machinery procurement. These three companies represent contrasting scale-specialization vectors within the premium-grade tier.
| Leading Market Players |
|---|
| Swiss Steel Group |
| Nippon Steel |
| ArcelorMittal |
| Hudson Tool Steel Corporation |
| Nucor Corporation |
| Voestalpine AG |
| Sandvik |
| Tiangong International |
| Hitachi Metals Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese long-product mills is compressing spot pricing for commodity-grade bar stock while tightening vacuum-degassed premium-grade availability in European integrated complexes. This utilization divergence concentrates pricing power among Austrian and German melt shops serving automotive qualification pools.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel and molybdenum indexation dominate mill-distributor agreements. Price differentiation separates vacuum-degassed automotive grades from electric-arc-furnace machinery bar. Pricing pressure stems from alloy surcharge volatility eroding distributor margins. Job-shop gear manufacturers exhibit highest price sensitivity; aerospace bearing OEMs show least.
Supply Chain Analysis
Scrap steel and ferroalloy feedstock flows draw from Turkish recycling hubs and South African chromium sources. Supply concentrates in Germany, Austria, and Japan for premium cleanliness grades. Single-source vulnerability runs through specialized vacuum degassing ladle metallurgy stations. Distribution runs through mill-direct contracts for automotive tiers and steel service centers for job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. Automotive qualification cycles exceeding eighteen months create switching-cost barriers that protect incumbent positions against commodity substitution.
For Market Incumbents: Build certification-documentation moats by investing in inline testing infrastructure for statistical process control. Secure captive vacuum carburizing capacity through equipment leasing partnerships. Plasma nitriding technology threatens conventional carburizing demand; defend by qualifying next-generation distortion-free hardening protocols.
For New Entrants and Emerging Players: Pursue hydraulic cylinder sour-service specifications in North American shale basins where ultraclean vacuum-degassed premiums offset commodity margin compression. Target Indian PLI scheme automotive component manufacturing for import-substitution positioning. Go-to-market through metallurgical support bundling with heat-treatment parameter optimization.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vacuum carburizing furnace leasing models. Long-term viability favors asset-light heat-treatment operators with per-kg throughput contracts over balance-sheet-heavy integrated mills. Acquisition targets include mid-sized forgers with automotive PPAP submission experience. Monitor carbon-border adjustment mechanism implementation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Degassing | Captive cleanliness control secures automotive OEM qualification timelines against alloy surcharge volatility. |
| Leasing Model Expansion for Heat-Treatment Equipment | Per-kg throughput contracts enable mid-sized forgers to bid precision work without fixed-asset exposure. |
| Plasma Nitriding Process Qualification | Distortion-free hardening alternative compresses post-treatment grinding allowances for camshaft production. |
| Alternative Surface Finishing Chemistry Investment | Trivalent chromium qualification ahead of REACH sunset dates maintains European automotive export access. |
| Digital Twin Integration with Furnace Control | Predictive metallurgical modeling reduces rejection rates through real-time case depth optimization. |
Research Methodology
A standing panel of vacuum carburizing furnace operators, automotive Tier 1 procurement managers, steel service center inventory planners, and oilfield equipment metallurgists provided ongoing calibration. Primary interviews combined with secondary validation from customs trade data, mill shipment reports, SEC filings by listed steelmakers, and automotive production databases. Bottom-up grade-volume estimates triangulated against top-down end-use consumption models.
Scenario-bracketing framed projections across conservative, baseline, and accelerated technology-adoption pathways. Segmentation dimensions modeled include steel grade chemistry, application specification intensity, end-user certification burden, and regional production cluster. CAGRs derived from historical volume trajectories adjusted for regulatory mandate timing and capacity addition schedules. Forecast inputs incorporated alloy price index futures and automotive platform electrification content assumptions.
Sensitivities concentrate around REACH regulatory enforcement timing and carbon-border adjustment mechanism coverage expansion. Forecasts reflect assumptions regarding automotive qualification cycle durations and vacuum carburizing technician availability. Material shifts in EPA or NHTSA powertrain efficiency mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Global Special Steel Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Metal Halide Market
Specialty Metals
Dysprosium Market