
 Global Healthcare E-Commerce Market | 2026-2036
Global Healthcare E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare E-Commerce Market Foresight
Platform licensing revenue is tilting from pure product sales toward subscription-based care management models. Amazon Pharmacy leverages its logistics infrastructure to control same-day prescription fulfillment in dense metropolitan zones. JD Health International anchors its position through in-house telemedicine integration with pharmaceutical distribution. Alibaba Health specializes in cross-border wellness imports, navigating complex customs clearance for dietary supplements.
Healthcare e-commerce encompasses the digital sale and distribution of medical goods and services through internet-based platforms, requiring encrypted patient data transmission, cold-chain logistics for temperature-sensitive biologics, and real-time inventory synchronization with pharmacy management systems. Its primary purpose is to reduce patient access friction while enabling scalable chronic disease management. Prescription drugs command the largest transaction value pool, though telemedicine applications generate the fastest user growth as remote consultation becomes embedded in routine care workflows. Third-party marketplaces currently dominate distribution channel volume, yet direct-to-consumer platforms capture superior margins through proprietary patient data and recurring medication subscriptions.
FDA regulations govern prescription verification and patient privacy under HIPAA, while EMA's MDR framework imposes device traceability requirements on European platforms. China's NMPA enforces real-name authentication for controlled substance purchases, creating compliance barriers for cross-border sellers. Stakeholders must monitor evolving data localization mandates and decide whether to build captive pharmacy networks or rely on third-party fulfillment partnerships.
Market Dynamics
Platform economics in healthcare e-commerce are compressing toward integrated care models where prescription fulfillment, telemedicine, and chronic disease management collapse into single-subscription bundles. This structural consolidation rewards captive patient data and penalizes pure-play distributors lacking clinical workflow integration.
Growth Catalysts
- MDR traceability mandates:The EU's Medical Device Regulation forces platform investment in serialized inventory systems, raising compliance barriers for smaller competitors and concentrating volume among certified operators.
- Mobile-first chronic care:India's tier-2 cities demonstrate concentrated demand acceleration as smartphone penetration enables first-time pharmacy access for diabetes and hypertension patients previously served only by physical dispensaries.
- Cold-chain biologics expansion:Temperature-controlled logistics networks for monoclonal antibodies and cell therapies are extending platform serviceable markets beyond small-molecule drugs into high-value specialty pharmaceuticals.
Market Restraints
- Refrigerated last-mile costs:Gel packs, phase-change materials, and validated thermal packaging add 15-25% fulfillment cost premiums for biologics, compressing margins on temperature-sensitive prescriptions.
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces create geographic vulnerability to regional disruptions affecting global generic drug availability.
- Cross-border customs friction:China's NMPA real-name authentication requirements for controlled substances block foreign platforms from serving domestic patients without local entity establishment.
Strategic Opportunities
- Rural telemedicine-pharmacy integration:Brazil's interior municipalities present white space where asynchronous consultation platforms can pair with licensed local dispensaries for prescription fulfillment without urban hospital dependency.
- Wearable-driven medication adherence:Continuous glucose monitors and blood pressure cuffs are converging with e-commerce platforms to trigger automated prescription refills based on real-time biometric thresholds.
- PLI scheme manufacturing incentives:India's Production Linked Incentive program for pharmaceuticals is attracting contract manufacturing investment that platforms can vertically integrate for private-label generic sourcing.
Industry Challenges
- Interoperable EHR integration:Pharmacy management systems must reconcile prescription data across fragmented hospital information systems, delaying same-day fulfillment verification.
- HIPAA-grade infrastructure capex:End-to-end encryption, audit logging, and business associate agreement compliance require substantial fixed investment before transaction volume justifies unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare E-Commerce Market |
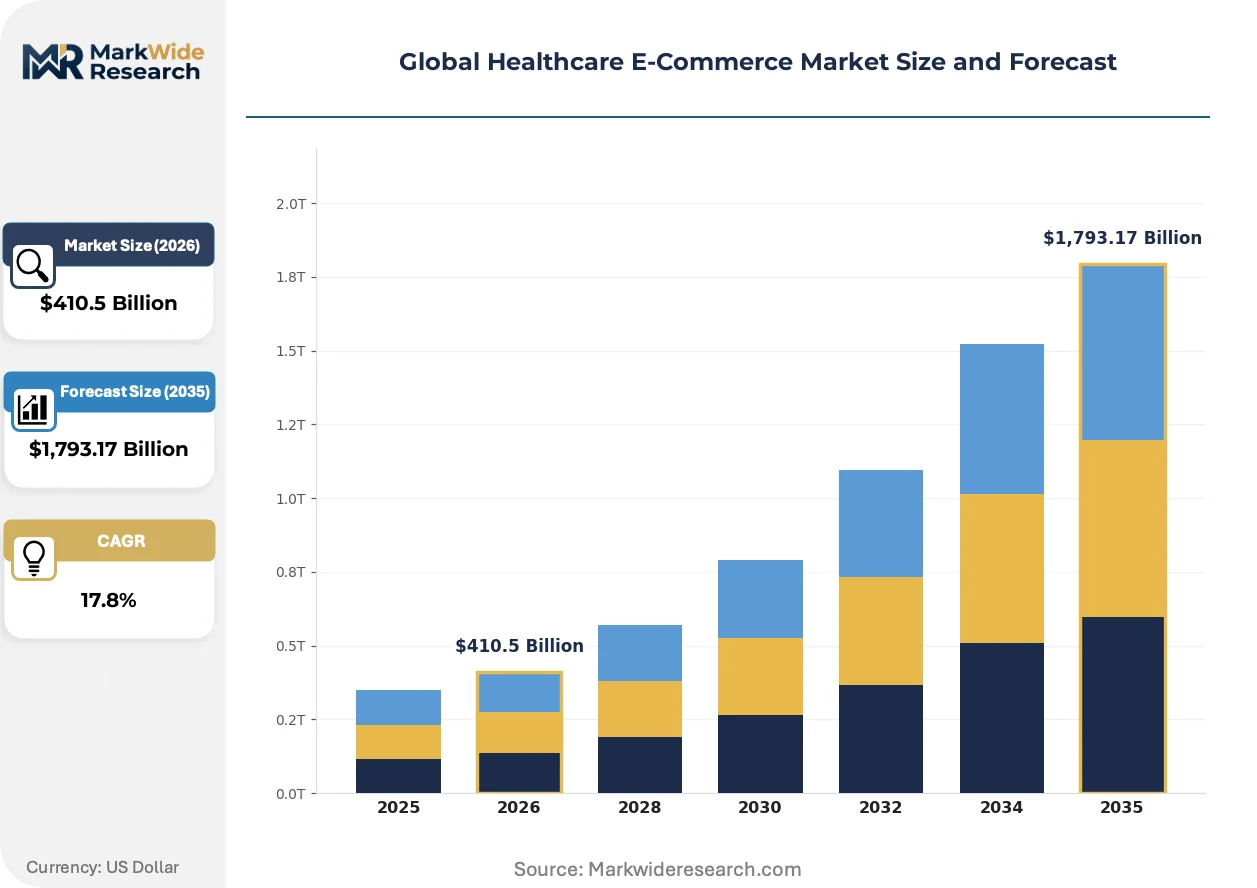
| Market Size in 2026 | $410.5 Billion |
| Market Size in 2035 | $1,793.17 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medicines, Medical Equipment, Wellness Products, Dietary Supplements Application: Pharmacy Services, Telemedicine, Health Insurance, Remote Patient Monitoring, Online Consultation End User: Patients, Caregivers, Pharmacies, Clinics, Diagnostic Centers Distribution Channel: Direct-to-Consumer, Third-Party Marketplaces, Retailer Websites, Mobile Applications, Social Commerce |
| Companies Covered | Amazon Pharmacy, Walmart Health, CVS Health, Walgreens Boots Alliance, Alibaba Health, JD Health International, McKesson Corporation, Cardinal Health, Flipkart Health+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare E-Commerce Market Shifts & Advancements
Distributed ledger architectures and AI-driven diagnostic triage are collapsing the traditional separation between pharmaceutical distribution and clinical decision support. Platforms are racing to embed these capabilities before regulatory clarity hardens competitive positions.
Blockchain-based prescription verification is virtualizing the chain-of-custody documentation that previously required physical paper trails and manual pharmacist inspection. Large hospital systems in Germany and the Netherlands are piloting these systems for opioid tracking, compressing audit timelines from weeks to minutes while reducing diversion risk. The technology is virtualizing compliance infrastructure, allowing platforms to substitute cryptographic proof for expensive third-party logistics oversight.
EMA's MDR Article 27 unique device identification requirements are mandating end-to-end traceability for software-as-medical-device products sold through digital channels. Platforms serving European patients must now integrate with EUDAMED databases for real-time status verification, raising operational complexity but creating defensible data moats against non-compliant competitors. Diagnostic apps and algorithmic triage tools face the steepest compliance ramps.
Subscription bundling is displacing per-transaction pharmacy economics as chronic disease patients consolidate medication, consultation, and monitoring spend with single platforms. Employer-sponsored health plans in the United States are driving this shift by negotiating capitated arrangements that reward medication adherence over prescription volume. The behavioral pivot is most visible in diabetes and cardiovascular therapeutic categories where refill automation reduces emergency utilization.
Global Healthcare E-Commerce Market Segmentation
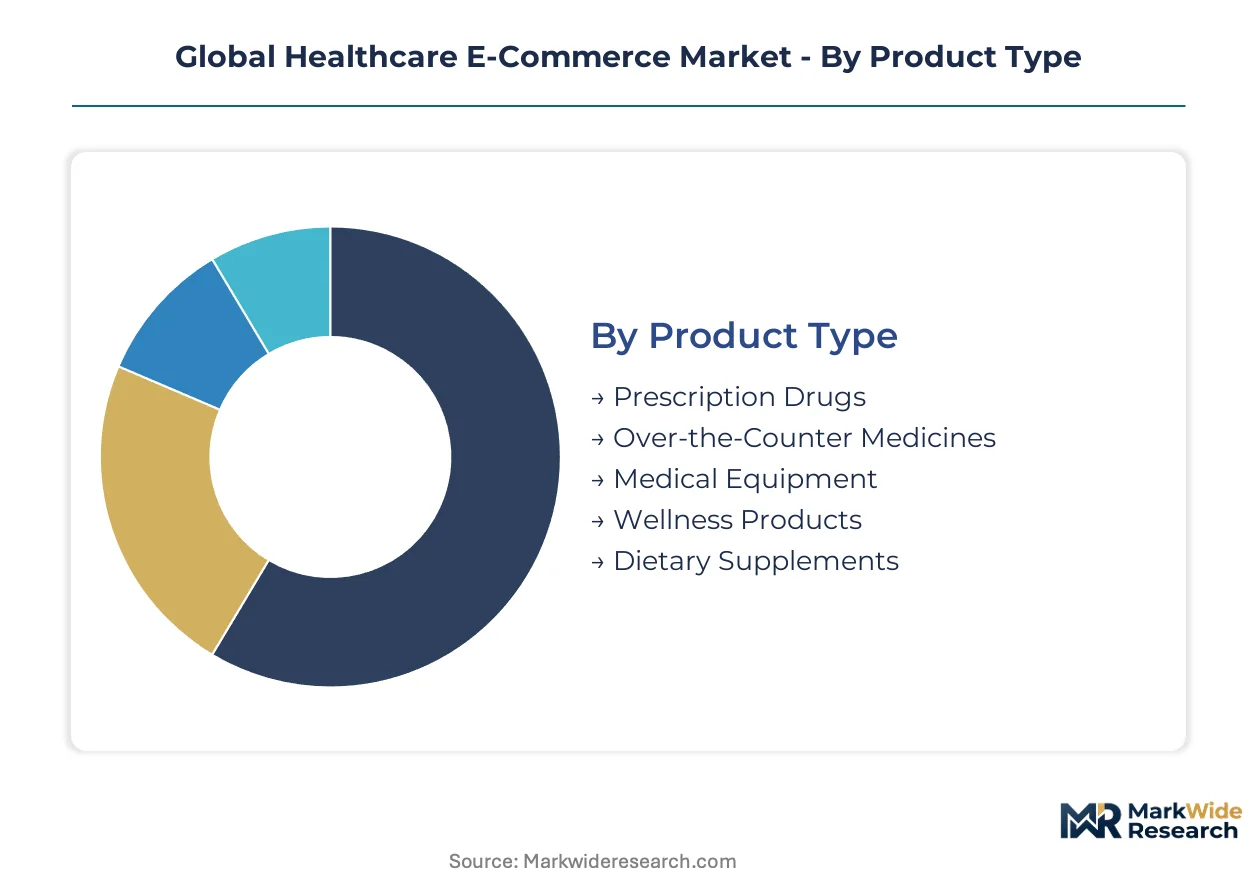
Healthcare e-commerce segmentation reveals divergent margin profiles and regulatory exposure across product categories and service models. Understanding these fault lines enables platform operators to allocate logistics infrastructure and compliance investment toward the highest-velocity revenue pools.
Product Type:
Cycle times vary dramatically, with temperature-sensitive biologics requiring same-day fulfillment while wellness products tolerate 3-5 day windows.
- Prescription Drugs:Regulated pharmaceuticals requiring encrypted prescription verification and cold-chain logistics for biologics. Chronic disease patients in India's tier-2 cities drive concentrated demand acceleration through mobile-first pharmacy access.
- Over-the-Counter Medicines:Non-prescription analgesics, antihistamines, and digestive remedies with lower regulatory friction. Brazil's interior municipalities present white-space opportunity where asynchronous consultation platforms pair with licensed local dispensaries.
- Medical Equipment:Diagnostic devices and home-care apparatus subject to EMA MDR traceability mandates. EUDAMED database integration raises operational complexity for European platform operators.
- Wellness Products:Non-therapeutic lifestyle and preventive health merchandise with minimal regulatory burden. Cross-border customs clearance complexity limits platform serviceable markets for dietary supplement imports.
- Dietary Supplements:Vitamin, mineral, and herbal formulations navigating China's NMPA real-name authentication barriers. Alibaba Health specializes in customs clearance navigation for this segment.
Prescription drugs anchors the volume base while wellness products gains share at the steepest rate.
Application:
Customer acquisition costs stratify sharply, with telemedicine platforms spending heavily on clinical workflow integration while insurance portals leverage employer-sponsored distribution.
- Pharmacy Services:Digital prescription fulfillment and medication management with same-day delivery in dense metropolitan zones. Amazon Pharmacy leverages logistics infrastructure to control fulfillment velocity in urban corridors.
- Telemedicine:Remote clinical consultation embedded in routine care workflows. JD Health International anchors market position through in-house integration with pharmaceutical distribution networks.
- Health Insurance:Digital policy distribution and claims processing with capitated employer arrangements. United States employer-sponsored plans drive subscription bundling that rewards medication adherence.
- Remote Patient Monitoring:Wearable-driven biometric tracking triggering automated prescription refills. Continuous glucose monitors and blood pressure cuffs converge with e-commerce platforms for chronic disease management.
- Online Consultation:Asynchronous physician interaction for non-urgent symptom assessment. Germany and Netherlands hospital systems pilot blockchain-based prescription verification for opioid tracking.
Pharmacy services generates the largest transaction value pool while remote patient monitoring climbs the fastest.
End User:
Procurement authority and price sensitivity diverge, with institutional buyers negotiating volume discounts while individual patients prioritize convenience premiums.
- Patients:Individual consumers managing chronic conditions through subscription-based care models. Diabetes and cardiovascular therapeutic categories show strongest refill automation adoption.
- Caregivers:Family members and home health aides coordinating medication procurement for dependent populations. Elderly care workflows demand simplified mobile interfaces.
- Pharmacies:Licensed dispensaries sourcing inventory through B2B platform channels. India's Production Linked Incentive program attracts contract manufacturing investment for private-label generic sourcing.
- Clinics:Outpatient facilities integrating e-commerce procurement with electronic health record systems. Interoperable EHR integration delays same-day fulfillment verification across fragmented hospital information systems.
- Diagnostic Centers:Laboratory and imaging facilities purchasing reagents and capital equipment. Serialized inventory systems satisfy EU MDR compliance requirements for device traceability.
Patients command the highest transaction frequency while diagnostic centers deliver the steepest per-order value expansion.
Distribution Channel:
Margin capture and data ownership trade off, with direct channels retaining patient relationships while marketplaces absorb customer acquisition costs.
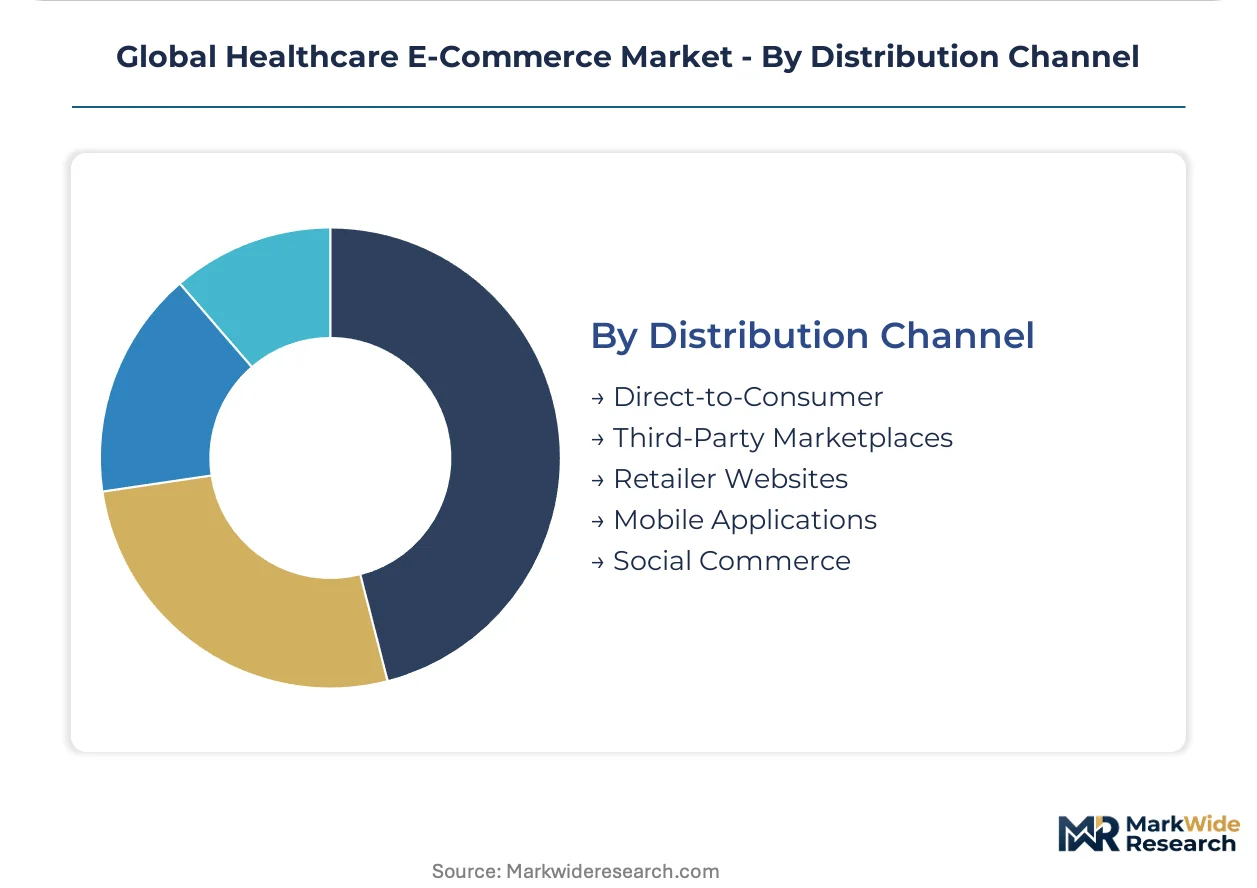
- Direct-to-Consumer:Proprietary platforms capturing superior margins through recurring medication subscriptions and captive patient data. HIPAA-grade infrastructure capex requirements create barriers to entry.
- Third-Party Marketplaces:Aggregator platforms dominating distribution channel volume through consolidated supplier networks. FDA digital health guidance reshapes certification standards for marketplace operators.
- Retailer Websites:Traditional pharmacy chains extending brick-and-mortar presence through digital storefronts. Cold-chain biologics expansion extends serviceable markets beyond small-molecule drugs.
- Mobile Applications:Smartphone-native platforms penetrating India's tier-2 cities where mobile-first health access expands fastest. Gel packs and phase-change materials add fulfillment cost premiums for temperature-sensitive prescriptions.
- Social Commerce:Influencer-driven wellness product distribution through integrated shopping features. Cross-border customs friction blocks foreign platforms from serving Chinese domestic patients without local entity establishment.
Third-party marketplaces dominate volume throughput while direct-to-consumer channels deliver the most defensible margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: Indian tier-2 cities absorb convenience premiums for first-time pharmacy access, while German buyers demand EUDAMED-traceable devices regardless of cost. Brazil's interior municipalities present white-space opportunity where asynchronous platforms bypass urban hospital dependency.
United States
Employer-sponsored health plans drive subscription bundling that rewards medication adherence over prescription volume. FDA digital health guidance and HIPAA enforcement reshape certification standards for platform operators. Amazon Pharmacy leverages logistics infrastructure to control same-day prescription fulfillment in dense metropolitan zones.
India
Smartphone penetration enables first-time pharmacy access for diabetes and hypertension patients previously served only by physical dispensaries. CDSCO regulations and the Production Linked Incentive scheme attract contract manufacturing investment for private-label generic sourcing. Tier-2 cities demonstrate concentrated demand acceleration as mobile-first health access expands fastest.
Germany
Hospital systems pilot blockchain-based prescription verification for opioid tracking, compressing audit timelines from weeks to minutes. EMA MDR Article 27 mandates end-to-end traceability for software-as-medical-device products sold through digital channels. Large hospital networks in the Netherlands and Germany integrate with EUDAMED databases for real-time status verification.
China
Cross-border wellness imports navigate complex customs clearance for dietary supplements. NMPA enforces real-name authentication for controlled substance purchases, creating compliance barriers for cross-border sellers. Zhejiang and Jiangsu province manufacturing clusters concentrate active pharmaceutical ingredient production, creating geographic vulnerability to regional disruptions.
Brazil
Asynchronous consultation platforms pair with licensed local dispensaries for prescription fulfillment without urban hospital dependency. ANVISA regulations govern pharmaceutical distribution while digital health platforms expand into interior municipalities. São Paulo and Rio de Janeiro anchor platform infrastructure investment, yet interior states present the steepest user growth curves.
Global Healthcare E-Commerce Market Competitive Landscape
Capability concentration sits with integrated care platforms; scale advantage sits with logistics-heavy distributors. The market structures around three tiers: technology-native platforms with captive patient data, retail pharmacy chains extending digital storefronts, and wholesale distributors pivoting toward direct-to-consumer channels. Two competitive moves dominate: vertical integration into cold-chain biologics logistics and strategic partnerships with wearable device manufacturers for automated refill triggers.
Within the integrated platform tier, Amazon Pharmacy, JD Health International, and Alibaba Health exemplify divergent geographic and operational specializations. Amazon Pharmacy anchors North American same-day fulfillment through captive logistics infrastructure. JD Health International occupies a position linking telemedicine consultation with pharmaceutical distribution in East Asian markets. Alibaba Health represents cross-border wellness import specialization, navigating customs clearance complexity for dietary supplement categories.
| Leading Market Players |
|---|
| Amazon Pharmacy |
| Walmart Health |
| CVS Health |
| Walgreens Boots Alliance |
| Alibaba Health |
| JD Health International |
| McKesson Corporation |
| Cardinal Health |
| Flipkart Health+ |
| Others |
Supply & Pricing Matrix
Zhejiang and Jiangsu province manufacturing clusters concentrate active pharmaceutical ingredient production, anchoring margin pools with contract manufacturers and generic drug platforms that capture value through captive sourcing relationships rather than pure distribution markups.
Pricing Analysis
Subscription-based care management bundles drive lifetime value beyond per-transaction prescription margins. Three-tier pricing structure across premium biologics, standard small-molecule generics, and economy wellness imports differentiates platforms by cold-chain capability and regulatory certification tier. Pricing pressure stems from refrigerated last-mile logistics costs that add fulfillment premiums for temperature-sensitive therapies. Chronic disease patients in India's tier-2 cities show lowest price sensitivity for first-time pharmacy access, while institutional buyers in Germany demand EUDAMED-traceable devices regardless of cost premium.
Supply Chain Analysis
Tariff exposure between China and major import markets dominates supply chain risk calculus for dietary supplement and API-dependent platforms. Active pharmaceutical ingredient manufacturing draws from Zhejiang, Jiangsu, and select Indian contract manufacturing zones under CDSCO oversight. Cold-chain biologics hinge on validated thermal packaging, phase-change materials, and specialized courier networks. Distribution runs through third-party marketplaces for volume throughput, though direct-to-consumer channels retain superior margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare e-commerce operates through a cyclical recovery phase as FDA digital health guidance and EU MDR compliance waves force platform reinvestment, compressing margins before certification barriers consolidate volume among compliant operators.
For Market Incumbents: Harden cold-chain logistics infrastructure against biologics margin compression while embedding telemedicine workflows to capture subscription bundling economics. Defend against pure-play distributors through HIPAA-grade data moats and EHR interoperability investments that delay same-day fulfillment verification for competitors lacking hospital system integration.
For New Entrants and Emerging Players: Pursue Brazil's interior municipalities where asynchronous consultation platforms pair with licensed local dispensaries, bypassing urban hospital dependency. Target India's tier-2 cities through mobile-first pharmacy access for diabetes and hypertension patients previously served only by physical dispensaries, leveraging PLI scheme manufacturing incentives for private-label generic sourcing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telemedicine platforms lacking pharmaceutical distribution integration. Long-term viability over the mid-cycle window favors operators with captive patient data and recurring medication subscription revenue. Watch for wearable-driven medication adherence convergence as the inflection signal triggering automated prescription refill automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Expansion | Enables biologics fulfillment beyond small-molecule drugs into monoclonal antibody and cell therapy categories. |
| Telemedicine-Pharmacy Integration | JD Health International anchors market position through in-house consultation and distribution linkage. |
| Blockchain Prescription Verification | German hospital systems pilot cryptographic chain-of-custody for opioid tracking and diversion risk reduction. |
| Wearable-Driven Refill Automation | Continuous glucose monitors and blood pressure cuffs trigger prescription replenishment based on biometric thresholds. |
| EUDAMED Database Integration | EMA MDR Article 27 mandates real-time device traceability for software-as-medical-device products. |
Research Methodology
Initial hypotheses were tested against primary input from pharmacy platform executives, cold-chain logistics operators, hospital procurement managers, and regulatory affairs specialists, then refined through secondary validation against FDA digital health guidance documents, EMA MDR submissions, CDSCO filings, NMPA registration databases, and hospital procurement contract records. Bottom-up prescription volume modeling and top-down platform revenue triangulation converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user archetype, and distribution channel, with regional regulatory cluster as the healthcare-specific overlay. CAGRs were derived from prescription volume trajectories, telemedicine user expansion curves, and cold-chain infrastructure deployment timelines.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility affecting cross-border wellness imports or API sourcing costs would shift the trajectory. Forecasts reflect assumptions about regulatory compliance timelines and cold-chain logistics cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Ambient Commerce Enablement Infrastructure Market