
 Asia Pacific Same Day Delivery Market | 2026-2036
Asia Pacific Same Day Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Same Day Delivery Market Insights
Market Dynamics
Last-mile fulfillment revenue is fragmenting between owned-fleet operators and platform-aggregated gig networks across Asia Pacific. SF Express leverages its integrated air-ground infrastructure to sustain premium express positioning in tier-one Chinese cities. JD Logistics anchors same-day capability through automated warehousing density and captive last-mile coverage. Meituan competes via on-demand rider networks optimized for urban food and retail delivery.
Segmentation and Technology
Asia Pacific same day delivery encompasses logistics services guaranteeing parcel receipt within twenty-four hours of order placement, typically requiring real-time inventory positioning, dynamic route algorithms, and distributed micro-fulfillment nodes. On-demand delivery commands premium pricing through instant gratification economics, while automated warehousing reduces sortation latency for express service tiers. Mobile apps and GPS tracking function as baseline infrastructure, with last-mile solutions representing the primary differentiation vector between standard and express delivery propositions.
Regulatory Environment
China's MIIT and SAMR enforce data localization and labor classification rules that reshape platform operating costs, while India's TRAI digital commerce frameworks and state-level motor vehicle regulations govern fleet electrification timelines. E-commerce platforms and logistics providers must monitor evolving labor compliance standards and carbon disclosure requirements across jurisdictions.
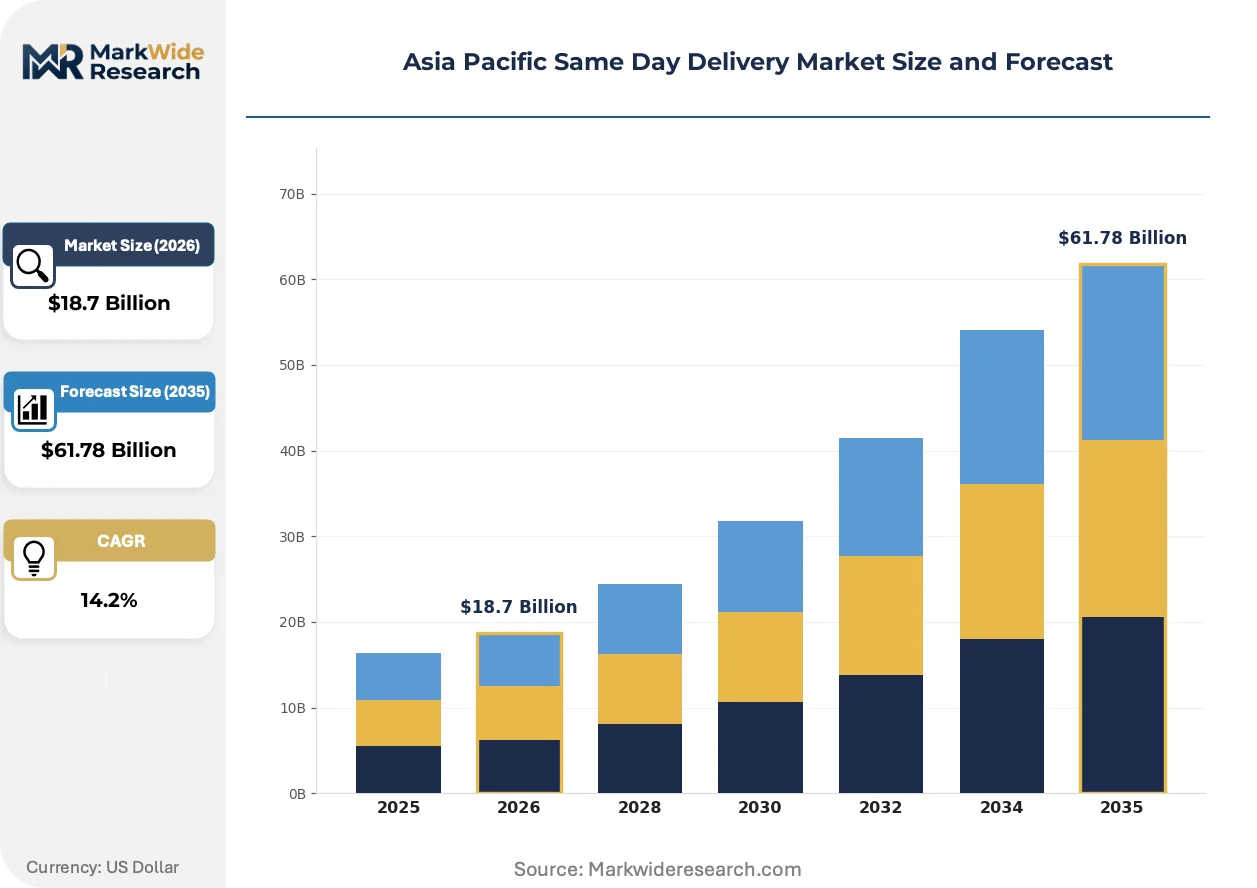
Market Dynamics
China's MIIT digital logistics mandates and India's TRAI e-commerce frameworks are compressing operational timelines while fragmenting fulfillment economics between captive fleets and gig-aggregated networks across Asia Pacific metropolitan corridors.
Growth Catalysts
- Urban consumption density:Southeast Asian e-commerce platforms concentrate same-day demand within Jakarta, Bangkok, and Ho Chi Minh City corridors, creating viable unit economics for micro-fulfillment node deployment.
- TRAI digital commerce frameworks:India's regulatory push for transparent logistics data interoperability reduces friction between marketplace platforms and third-party delivery providers.
- Automated sortation systems:Robotic parcel handling in Chinese automated warehousing reduces processing latency below two hours for express tier commitments.
Market Restraints
- Labor classification compliance:China's SAMR gig worker reclassification rules elevate platform operating costs by mandating social contribution obligations previously externalized to contractor networks.
- Last-mile fleet electrification capex:India's state-level motor vehicle regulations impose battery-swapping infrastructure requirements that strain balance sheets of mid-tier regional operators.
- Cross-border customs latency:ASEAN non-tariff barriers and inconsistent de minimis thresholds fragment same-day feasibility for international origin parcels.
Strategic Opportunities
- Vietnam and Philippines penetration gaps:Archipelagic geography and underdeveloped express infrastructure create first-mover advantages for drone-integrated delivery networks in secondary cities.
- MIIT carbon disclosure mandates:China's dual carbon goals generate compliance-driven demand for route optimization software and electric vehicle fleet management services.
- Pharma cold chain convergence:Temperature-controlled same-day delivery for biologics and vaccines merges with retail express networks, opening premium service tiers in Singapore and Australia.
Industry Challenges
- Rider retention and safety protocols:Platform-aggregated networks face churn exceeding forty percent annually while navigating occupational accident liability frameworks across multiple jurisdictions.
- Legacy warehouse management integration:Real-time inventory positioning requires API connectivity with decade-old ERP systems prevalent among mid-market Southeast Asian retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Same Day Delivery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, On-Demand Delivery, Scheduled Delivery Customer Type: Retail Customers, Businesses, E-Commerce Platforms, Government Agencies Technology: Mobile Apps, GPS Tracking, Last-Mile Solutions, Automated Warehousing Packaging Type: Plastic Bags, Cardboard Boxes, Insulated Containers, Custom Packaging |
| Companies Covered | ZTO Express, Yunda Express, SF Express, DHL Group, YTO Express, JD Logistics, STO Express, FedEx, Meituan, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Same Day Delivery Market Trends and Innovations
Logistics technology in Asia Pacific is compressing fulfillment windows through algorithmic density optimization while regulatory pressure on labor and carbon accountability reshapes network design priorities.
Autonomous mobile robots in Chinese automated warehousing are hybridizing manual and mechanized sortation workflows. Third-party logistics providers in Shanghai and Shenzhen are deploying AMR fleets at scale, reducing parcel handling time by over half while enabling same-day cut-off extensions to late afternoon. This hybridization is compressing the viable geography for premium express tiers inward toward dense urban cores where robot density justifies capital deployment.
China's MIIT data localization rules for logistics platforms mandate domestic server architecture and restrict cross-border data flows. The regulation elevates compliance costs for multinational e-commerce operators while creating procurement preference for domestic cloud and software vendors. Express delivery platforms are responding by segmenting data architectures, running Chinese operations on isolated infrastructure stacks.
Urban consumers across India and Southeast Asia are consolidating purchase decisions around delivery speed guarantees rather than brand loyalty. Quick commerce apps in Mumbai and Bangalore are displacing traditional e-commerce for grocery and essentials, forcing legacy marketplaces to unbundle express delivery as a standalone paid tier. This behavioral shift is most visible in India's tier-one cities where fifteen-minute delivery promises have reset baseline expectations.
Asia Pacific Same Day Delivery Market Segmentation
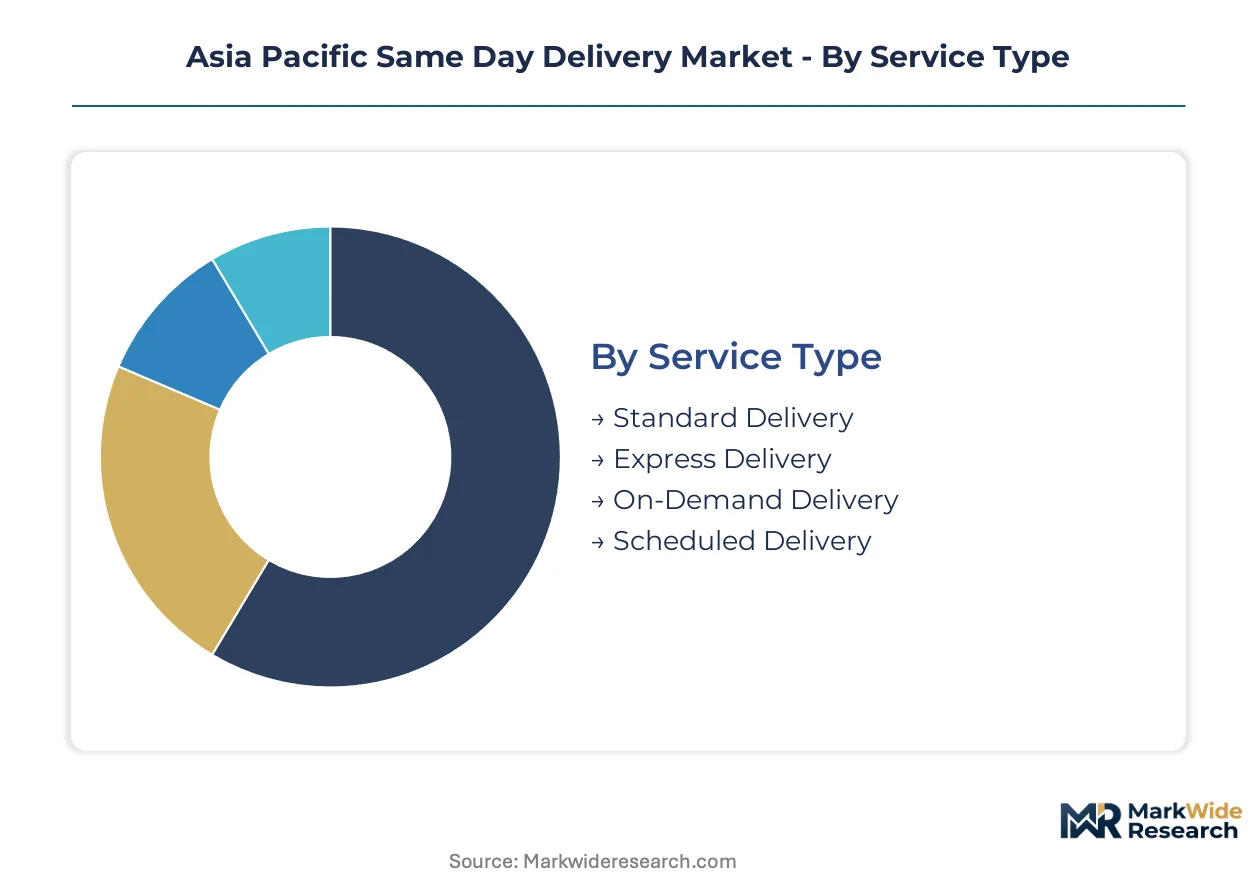
Same-day delivery economics diverge sharply across service tiers and customer profiles, with technology infrastructure and packaging requirements determining viable margin structures across Asia Pacific metropolitan corridors.
Service Type:
Cost tier differentiation separates premium immediacy from scheduled reliability, with each tier commanding distinct fleet configurations and labor models.
- Standard Delivery:Parcel completion within business day windows using consolidated batch routing and non-dedicated fleet assets. Demand concentrates among cost-sensitive e-commerce platforms in India's tier-two cities where unit economics resist premium service premiums.
- Express Delivery:Guaranteed four-to-eight-hour fulfillment through captive fleet networks and priority sortation lanes. JD Logistics and SF Express anchor this tier in Beijing and Shanghai corridors, leveraging automated warehousing density to compress cut-off times.
- On-Demand Delivery:Sub-two-hour fulfillment via gig-aggregated rider pools optimized for food and retail impulse purchases.
- Scheduled Delivery:Pre-selected time windows balancing customer convenience with route density optimization.
Express delivery commands the established base. The steepest expansion runs through on-demand networks.
Customer Type:
Application concentration determines network design priorities, with B2B reliability requirements diverging from consumer immediacy expectations.
- Retail Customers:Individual consumers purchasing through marketplace apps and quick commerce platforms, with delivery speed now outweighing brand loyalty in Mumbai and Jakarta purchase decisions.
- Businesses:Corporate procurement and inter-office document flows requiring SLA-backed reliability and proof-of-delivery compliance.
- E-Commerce Platforms:Marketplace operators internalizing logistics to control customer experience, with Shopee and Lazada building captive fulfillment networks across Southeast Asia.
- Government Agencies:Public sector contracts for document circulation and emergency supply distribution, subject to procurement transparency mandates under India's TRAI frameworks.
E-commerce platforms command the established base. The steepest expansion runs through retail customer adoption of quick commerce apps.
Technology:
Volume scalability depends on technology stack maturity, with mobile infrastructure now baseline and automation emerging as the differentiation frontier.
- Mobile Apps:Consumer-facing order interfaces and rider dispatch platforms functioning as the universal entry point across all service tiers.
- GPS Tracking:Real-time visibility infrastructure enabling dynamic route recalculation and customer communication, now mandatory under China's MIIT data localization requirements.
- Last-Mile Solutions:Micro-fulfillment nodes, locker networks, and crowd-sourced pickup points reducing per-delivery labor cost in dense urban cores. Singapore and Tokyo lead locker network penetration.
- Automated Warehousing:Robotic sortation and AMR fleets compressing processing latency below two hours, with deployment concentrated in Shenzhen and Shanghai facilities.
Mobile apps command the established base. Automated warehousing shows the steepest expansion trajectory.
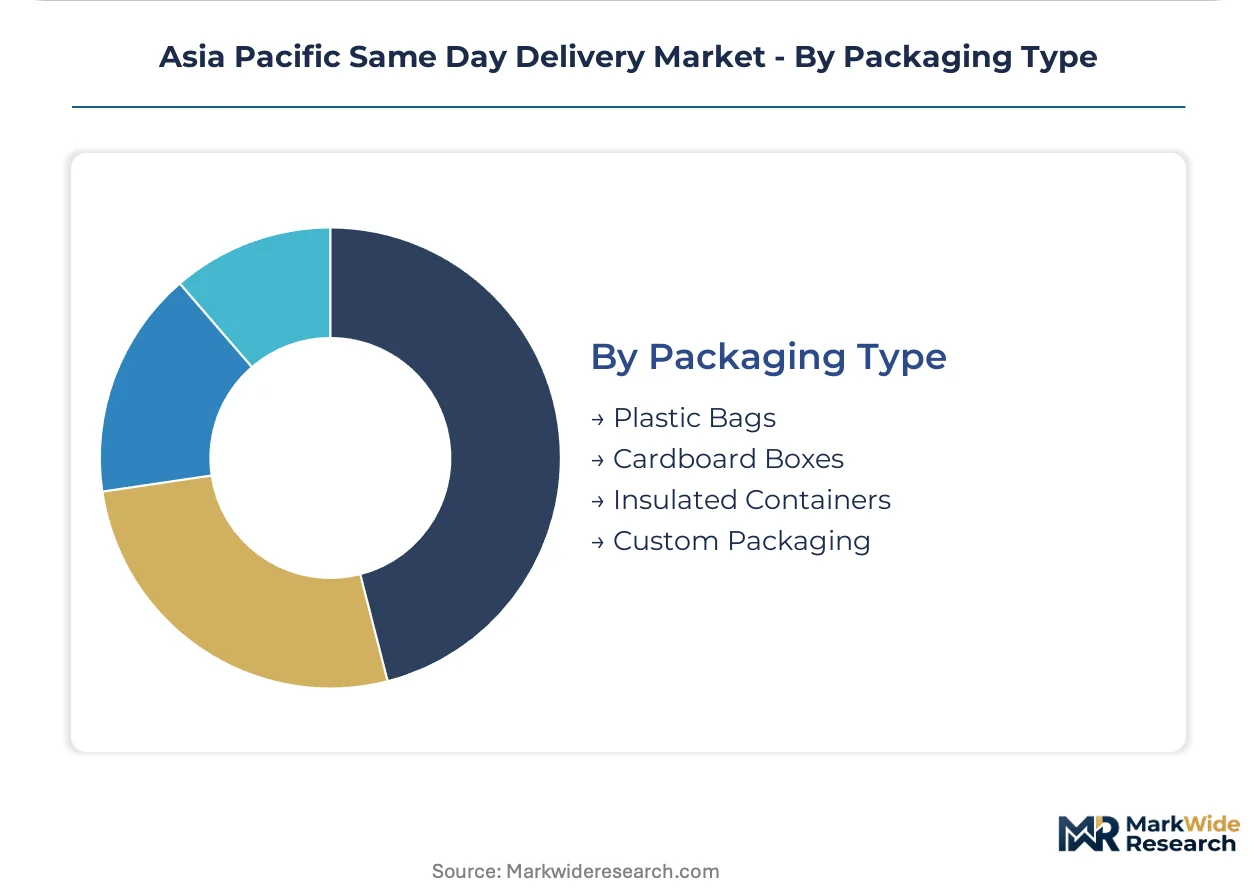
Packaging Type:
Margin structure varies with packaging sophistication, with temperature control and customization commanding premium pricing.
- Plastic Bags:Lightweight poly mailers dominating apparel and document flows, with environmental compliance pressure mounting under China's MEE regulations.
- Cardboard Boxes:Rigid corrugated protection for electronics and fragile goods, with dimensional weight pricing favoring optimization.
- Insulated Containers:Temperature-stable packaging for pharmaceuticals and fresh food, with Singapore and Australia pharma cold chains driving premium service tier development.
- Custom Packaging:Branded unboxing experiences and product-specific protective designs, concentrated among luxury retailers in Tokyo and Seoul.
Cardboard boxes command the established base. Insulated containers gain share fastest on pharma and fresh food convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Asia Pacific metropolitan corridors, with Chinese platforms prioritizing automated warehousing density while Indian and Southeast Asian markets rely on gig-aggregated rider networks for speed-based customer acquisition.
China
Express delivery volume concentrates in the Yangtze River Delta and Pearl River Delta corridors where JD Logistics and SF Express operate automated micro-fulfillment nodes. MIIT data localization mandates require domestic server architecture for logistics platforms, elevating compliance costs for cross-border operators. Shenzhen and Shanghai facilities deploy robotic sortation systems that compress processing windows below two hours for premium service tiers.
India
Quick commerce apps in Mumbai and Bangalore have reset consumer expectations toward fifteen-minute delivery guarantees for grocery and essentials. TRAI digital commerce frameworks mandate transparent logistics data interoperability between marketplace platforms and third-party providers. Delhi-NCR and Hyderabad corridors concentrate demand for same-day fulfillment, with state-level motor vehicle regulations imposing battery-swapping infrastructure requirements on fleet operators.
Japan
Scheduled delivery windows dominate consumer preference in Tokyo and Osaka corridors, with locker network penetration exceeding other Asia Pacific markets. METI carbon disclosure requirements apply to logistics operators above scale thresholds, driving route optimization software procurement. Kansai region distribution centers specialize in custom packaging for luxury retail unboxing experiences.
Singapore
Pharmaceutical cold chain convergence creates premium service tier opportunities for temperature-controlled same-day biologics delivery. The national pharmaceutical regulator enforces GDP standards for vaccine distribution logistics. Jurong logistics cluster hosts specialized insulated container handling facilities serving Australia and Southeast Asia pharma markets.
Vietnam
Archipelagic geography and underdeveloped express infrastructure in Ho Chi Minh City and Da Nang corridors create penetration gaps for drone-integrated delivery networks. The country's national transport ministry issues pilot permits for beyond-visual-line-of-sight UAV operations in designated corridors. Secondary cities present first-mover advantages for autonomous last-mile solutions bypassing legacy road infrastructure constraints.
Asia Pacific Same Day Delivery Market Competitive Landscape
Capability concentration sits with integrated logistics operators owning automated warehousing and captive air-ground networks; scale advantage sits with platform-aggregated gig networks optimized for urban density. The market structures around three archetypes: state-affiliated express carriers with infrastructure monopolies, e-commerce captive logistics divisions, and on-demand food delivery platforms extending into retail. Consolidation pressure operates through strategic partnerships between marketplace operators and third-party fulfillment providers, alongside vertical integration moves by retail platforms acquiring regional courier networks.
Within the integrated infrastructure tier, SF Express and JD Logistics exemplify operators combining automated warehousing density with captive last-mile coverage. ZTO Express occupies a position among volume-focused network carriers optimizing consolidated batch routing economics. Meituan represents the platform-aggregated archetype, leveraging on-demand rider pools for sub-two-hour fulfillment commitments. These three anchors illustrate the competitive tension between asset-heavy integrated models and asset-light gig network scalability across Asia Pacific metropolitan corridors.
| Leading Market Players |
|---|
| ZTO Express |
| Yunda Express |
| SF Express |
| DHL Group |
| YTO Express |
| JD Logistics |
| STO Express |
| FedEx |
| Meituan |
| Others |
Pricing and Supply Chain Analysis
MIIT data localization mandates function as a regulatory chokepoint that compresses pricing tier spreads between multinational and domestic operators while forcing supply chain segmentation into isolated Chinese infrastructure stacks.
Pricing Analysis
Long-term offtake contracts between e-commerce platforms and captive fleet operators anchor pricing stability in tier-one Chinese corridors, while spot-market gig labor pricing dominates Southeast Asian on-demand networks. Three-tier pricing structure across premium express, standard batch, and economy deferred tiers separates JD Logistics' automated warehousing commitments from Meituan's rider-density arbitrage. Cost compression in economy tiers intensifies because TRAI-mandated data interoperability erodes platform switching costs. Price-sensitive Indian tier-two retailers resist premium service premiums, whereas Singapore pharma cold chain buyers accept insulated container surcharges.
Supply Chain Analysis
Upstream feedstock for automated warehousing equipment draws from Japan's precision robotics manufacturers, South Korea's sensor component specialists, and China's domestic AMR assembly clusters. Lithium-ion battery cells for fleet electrification rest on South Korean cathode chemistry and Indonesian nickel processing. Single-source vulnerability concentrates in high-density Shanghai and Shenzhen micro-fulfillment nodes where robot deployment scales. Distribution runs through platform-aggregated rider networks in Jakarta and Bangkok, captive fleet hierarchies in Beijing and Delhi-NCR, and hybrid locker-rider systems in Tokyo and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
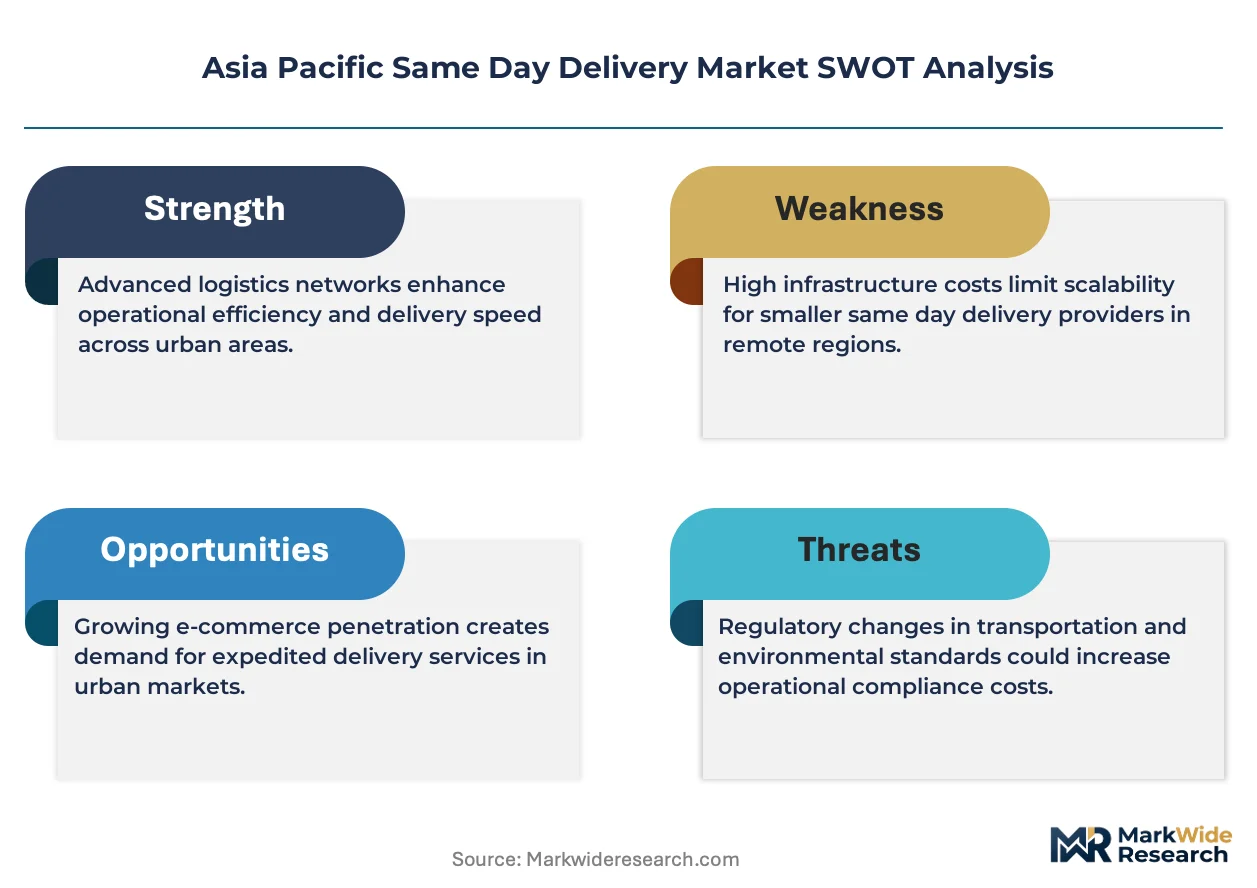
Asia Pacific same-day delivery sits at a platform-economics inflection where TRAI data interoperability and MIIT localization mandates are fragmenting network architectures into jurisdiction-specific stacks.
For Market Incumbents: Build captive warehousing moats through automated sortation density in Yangtze River Delta and Pearl River Delta corridors. JD Logistics and SF Express should deepen backward integration into AMR fleet manufacturing to offset equipment import dependency. SAMR gig worker reclassification elevates social contribution obligations; incumbents must anchor margin defense through robotic labor substitution in Shenzhen facilities. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's secondary city drone corridors where national transport ministry BVLOS permits create first-mover regulatory sandbox advantages. Archipelagic geography in Da Nang and Can Tho bypasses legacy road infrastructure constraints. Target pharma cold chain convergence in Singapore's Jurong cluster through GDP-certified insulated container partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with automated warehousing and captive last-mile coverage. Long-term viability hinges on carbon disclosure compliance under China's dual carbon goals and India's state-level electrification mandates. Acquisition targets should demonstrate robot density above manual sortation thresholds. The signal to watch is MIIT carbon disclosure enforcement timelines as a trigger for route optimization software procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehousing Scale-Up | AMR deployment in Shenzhen reduces parcel handling latency below two-hour express cut-offs. |
| Regulatory Compliance Architecture | Segmented data stacks satisfy MIIT localization while preserving cross-border operational coherence. |
| Fleet Electrification Partnership | Battery-swapping infrastructure alliances address India's state-level motor vehicle mandates. |
| Drone Delivery Pilot Program | BVLOS permits in Vietnamese secondary cities bypass archipelagic road infrastructure gaps. |
| Pharma Cold Chain Certification | GDP standards compliance unlocks Singapore biologics premium service tier pricing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of logistics operator regulatory filings, MIIT mandate documentation, and customs trade data. Primary interviews engaged fleet operations directors, e-commerce platform logistics procurement leads, last-mile technology vendors, and warehouse automation engineers. Secondary validation drew from SAMR labor classification circulars, TRAI digital commerce framework releases, ASEAN customs integration reports, and operator infrastructure disclosure statements. Bottom-up capacity modeling triangulates against top-down consumption density estimates across metropolitan corridors.
Forecast inputs incorporate service tier adoption curves, automation capex cycles, and regulatory compliance cost trajectories across the analysis window. Segmentation dimensions modeled include service type, customer archetype, technology stack maturity, and packaging sophistication. CAGRs derive from logistics volume elasticity against e-commerce penetration rates and fleet productivity metrics. Industry-specific inputs include robot density thresholds for automated warehousing viability and gig network churn rates affecting unit economics.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, fuel price volatility, or cross-border tariff regimes would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement consistency and technology adoption S-curves. Cross-checking against IEA electrification cost benchmarks and ASEAN logistics integration indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Greece E-Commerce Market