
 South Africa E-Commerce Market | 2026-2036
South Africa E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa E-Commerce Market Analytics
Subscription-based loyalty programs and software-defined personalization engines are realigning what South African e-commerce platforms monetize beyond the initial transaction. Takealot leverages its fulfillment infrastructure to anchor next-day delivery promises across major urban centers. Woolworths competes through premium private-label exclusivity that sustains higher-margin basket economics.
South Africa e-commerce denotes digitally mediated retail transactions executed through web interfaces and native applications, typically requiring secure socket layer encryption, payment gateway integration, and last-mile logistics orchestration to complete fulfillment. Its primary commercial purpose is to disintermediate traditional brick-and-mortar distribution, reducing working capital intensity for sellers while expanding product accessibility for buyers. Fashion and electronics categories dominate transaction volumes, though home goods commands stronger repeat-purchase frequency and margin retention. Mobile apps represent the fastest-growing sales channel as smartphone penetration deepens in peri-urban townships, while online marketplaces still occupy the largest revenue pool through aggregator economics.
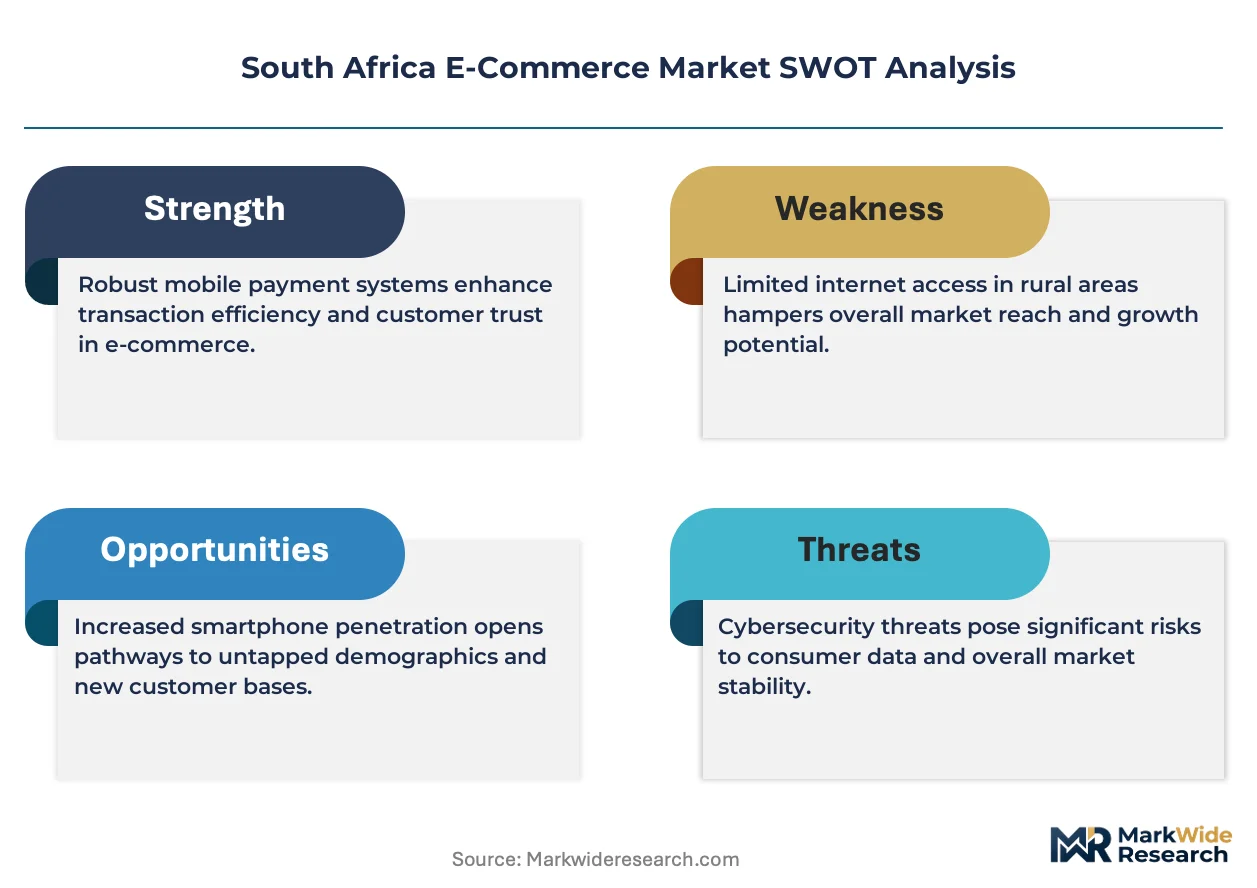
The Consumer Protection Act, enforced by the National Consumer Commission, mandates disclosure standards and cooling-off rights that elevate operational compliance costs for cross-border sellers. The Protection of Personal Information Act, administered by the Information Regulator, imposes data-handling protocols that constrain targeted advertising granularity and retargeting efficiency. Stakeholders must monitor pending amendments to electronic transaction frameworks and decide whether to build captive payment infrastructure or rely on third-party digital wallet providers whose fee structures remain politically sensitive.
Market Dynamics
Mobile-first commerce penetration in peri-urban South African townships is compressing traditional desktop-dependent purchasing pathways and forcing platform architecture redesigns around low-bandwidth connectivity.
Growth Catalysts
- Protection of Personal Information Act:Mandatory data-handling protocols are accelerating investment in compliant customer data platforms among Johannesburg-based retailers, creating competitive differentiation through trust infrastructure.
- Smartphone penetration:Android device adoption in Gauteng and Western Cape townships is expanding addressable user bases beyond historically banked urban cores, unlocking informal sector participation.
- Digital wallet integration:Instant EFT and mobile money rails are reducing checkout abandonment in Durban metropolitan corridors where card penetration remains uneven.
Market Restraints
- Last-mile cost volatility:Fuel price fluctuations and informal addressing systems in South African townships compress margin structures for fulfillment operators serving peri-urban nodes.
- Cross-border payment friction:Rand volatility and correspondent banking limitations create working capital traps for sellers sourcing inventory from Asian manufacturing clusters.
- Consumer Protection Act cooling-off rights:Mandatory return windows and disclosure standards elevate operational overhead for marketplace vendors relative to brick-and-mortar alternatives.
Strategic Opportunities
- Eastern Cape township penetration:Underdeveloped logistics infrastructure in Gqeberha and surrounding areas presents first-mover advantages for platforms building localized fulfillment nodes.
- Buy-now-pay-later convergence:Integration of credit decisioning engines with mobile checkout flows is displacing traditional lay-by systems in fashion and electronics verticals.
- Informal sector formalization:Spaza shop digitization through B2B marketplace interfaces creates captive supply relationships with township micro-retailers.
Industry Challenges
- Last-mile logistics talent scarcity:Driver retention and route optimization expertise shortages constrain scaling of same-day delivery promises in Cape Town and Johannesburg.
- Legacy ERP integration:Inventory synchronization between SAP-dependent national retailers and cloud-native marketplace architectures creates real-time stock visibility failures.
- Cross-border customs clearance timelines:Port of Durban processing delays and SARS documentation complexity extend replenishment cycles for electronics imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa E-Commerce Market |
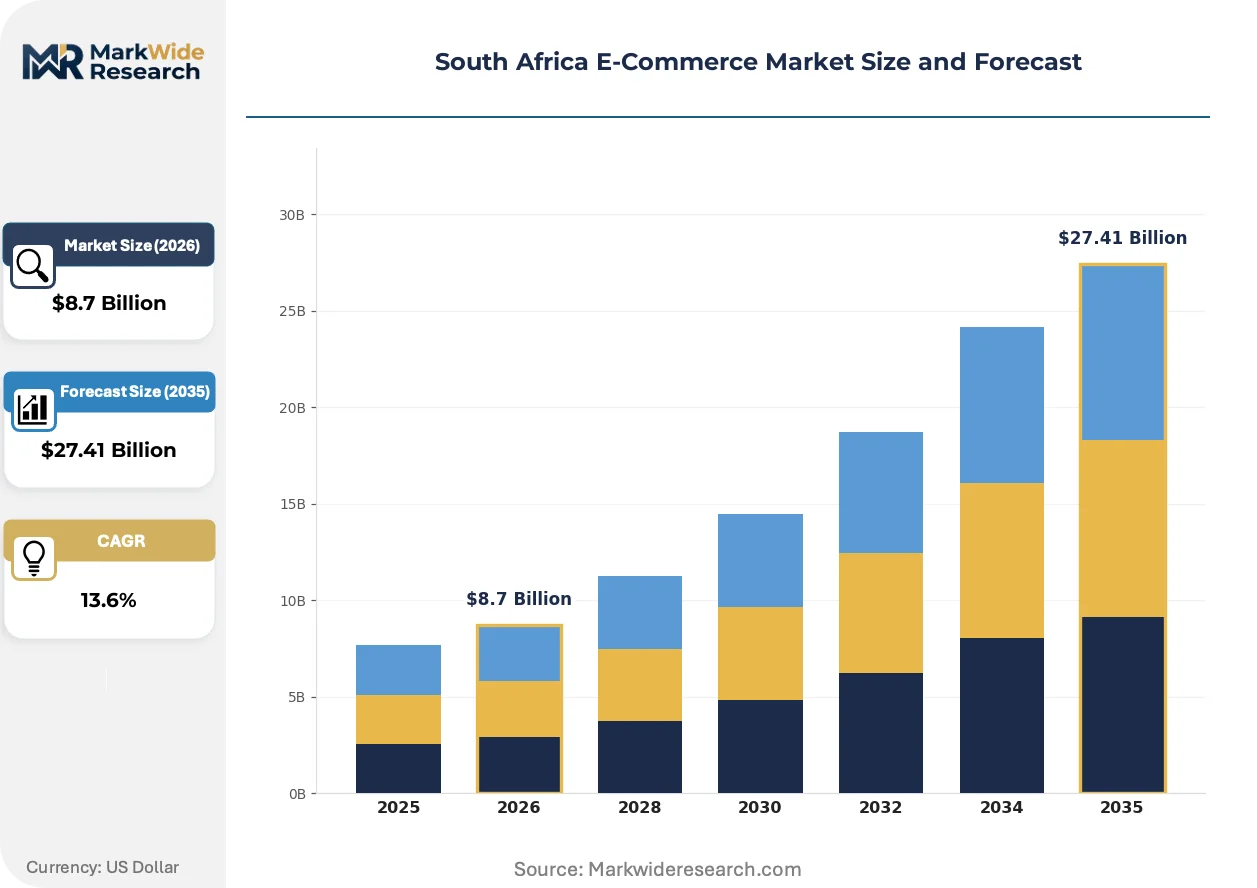
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Goods, Beauty Customer Type: Individual Consumers, Small Businesses, Large Enterprises, Non-profits Sales Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Payment Method: Credit Cards, Digital Wallets, Bank Transfers, Cash on Delivery |
| Companies Covered | Bob Shop, Yuppiechef, Takealot, Clicks, Makro, Superbalist, Woolworths, Home Choice, Zando, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa E-Commerce Market Evolving Landscape
Algorithmic personalization and embedded finance products are restructuring how South African e-commerce platforms capture lifetime value beyond transactional margins.
Machine learning recommendation engines deployed by Cape Town-based fashion retailers are automating size-fit prediction and inventory allocation decisions previously handled by human merchandising teams. Mid-market apparel platforms are adopting these systems to reduce return rates in footwear and denim categories where fit uncertainty drives abandonment. The technology is automating demand forecasting for seasonal collections, compressing the gap between trend identification and stock positioning.
The Consumer Protection Act's cooling-off right enforcement by the National Consumer Commission is mandating transparent pricing disclosure and return workflow integration into checkout flows. Compliance investments are elevating operational costs for cross-border sellers while creating defensive moats for domestic platforms with captive fulfillment infrastructure. Electronics and home appliance verticals face the steepest adaptation requirements given higher average order values and associated return risk.
Subscription loyalty programs are displacing transactional discounting as the primary retention mechanism among Johannesburg-based grocery and beauty platforms. Woolworths WRewards and competing schemes lock in recurring purchase patterns through tiered benefit structures tied to basket frequency rather than single-transaction thresholds. This shift concentrates customer lifetime value calculation in metropolitan corridors where wallet app penetration enables seamless program enrollment.
South Africa E-Commerce Market Segmentation
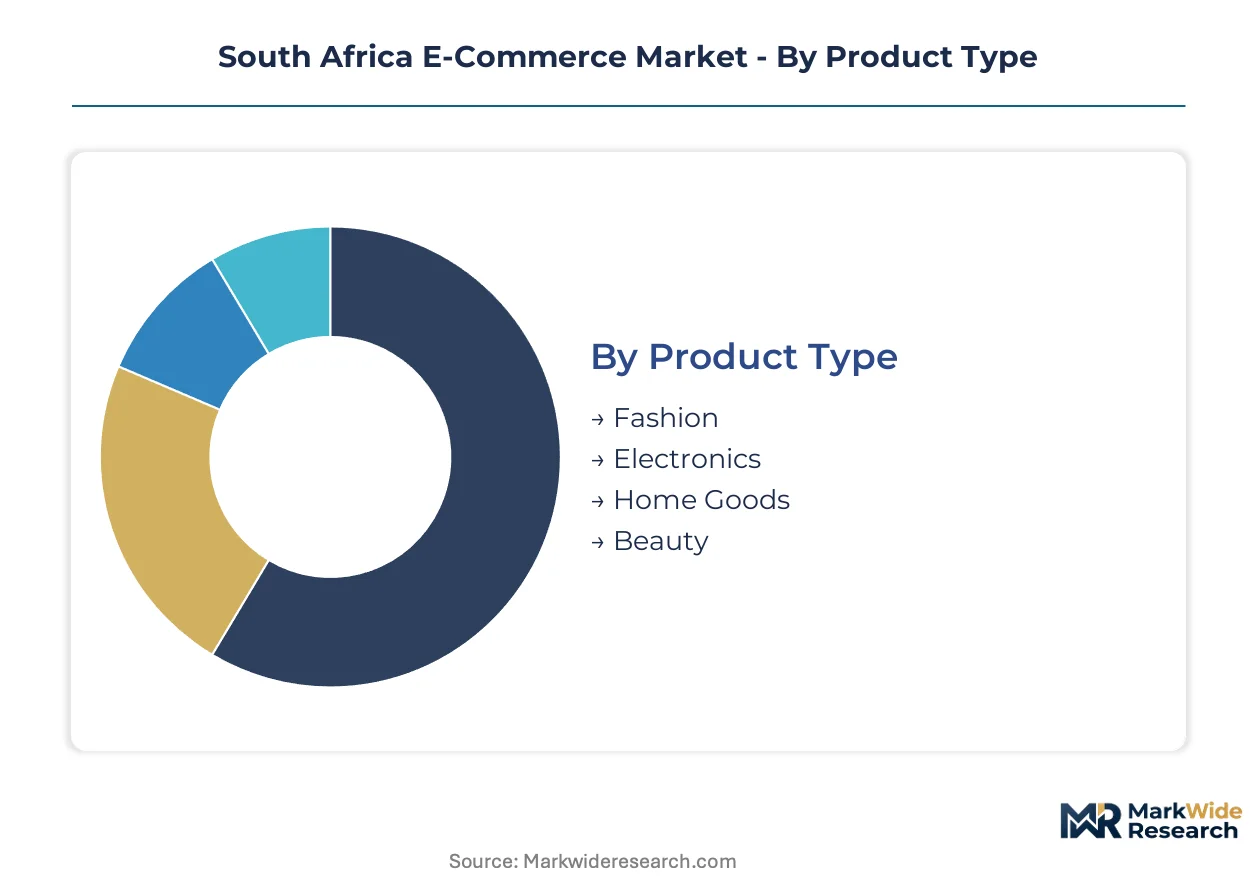
South African e-commerce segmentation reveals how platform architecture, payment rails, and fulfillment economics concentrate value capture across distinct commercial pathways. Understanding these divides illuminates where compliance burdens, technology investments, and customer acquisition costs diverge most sharply.
Product Type:
Fashion and electronics carry the heaviest Consumer Protection Act disclosure obligations due to higher return rates and fit uncertainty, while home goods face lighter cooling-off enforcement.
- Fashion:Size-fit algorithms and virtual try-on tools are reducing return processing costs in Cape Town-based apparel platforms. Demand concentrates in Johannesburg and Durban metropolitan corridors where same-day delivery promises drive conversion.
- Electronics:High-value smartphones and computing equipment require extended warranty disclosures under National Consumer Commission guidelines. Cross-border sellers face working capital compression from Rand volatility against Asian supplier invoices.
- Home Goods:Repeat-purchase frequency exceeds other categories, with bedding and kitchenware sustaining margin retention through subscription replenishment models.
- Beauty:Premium skincare and cosmetics leverage ingredient transparency requirements to justify price positioning above mass-market alternatives.
Leading the category by volume: Fashion. Growing fastest: Electronics.
Customer Type:
Enterprise procurement patterns favor invoice-based settlement terms, while individual consumers drive mobile app transaction velocity through instant EFT rails.
- Individual Consumers:Township smartphone penetration in Gauteng and Western Cape is expanding addressable bases beyond historically banked urban cores. Android device adoption unlocks informal sector participation through simplified KYC flows.
- Small Businesses:Spaza shop digitization via B2B marketplace interfaces creates captive supply relationships with micro-retailers in Eastern Cape townships. Inventory financing gaps constrain scaling beyond single-location operations.
- Large Enterprises:SAP-dependent ERP systems struggle with real-time inventory synchronization against cloud-native marketplace architectures.
- Non-profits:Donation processing and bulk procurement workflows require specialized checkout customization exempt from standard consumer protection cooling-off windows.
Volume leadership sits with Individual Consumers. Small Businesses are climbing the fastest as township formalization accelerates.
Sales Channel:
Mobile apps demand the steepest UX investment for low-bandwidth township connectivity, while online marketplaces absorb the highest regulatory scrutiny under aggregator liability frameworks.
- Online Marketplaces:Aggregator economics concentrate revenue through Takealot and competing platforms, with fulfillment infrastructure anchoring next-day delivery promises. National Consumer Commission disclosure mandates elevate operational overhead for cross-border vendors.
- Mobile Apps:Native application development prioritizes offline browsing and compressed image loading for peri-urban connectivity constraints. Wallet app integration enables one-tap checkout in Durban corridors where card penetration remains uneven.
- Brand Websites:Premium private-label exclusivity sustains higher-margin basket economics through direct customer relationships.
- Social Media:Instagram and TikTok commerce adoption lags due to data cost sensitivity among price-conscious segments.
Online Marketplaces dominate transaction value. Mobile Apps are gaining share fastest as smartphone penetration deepens.
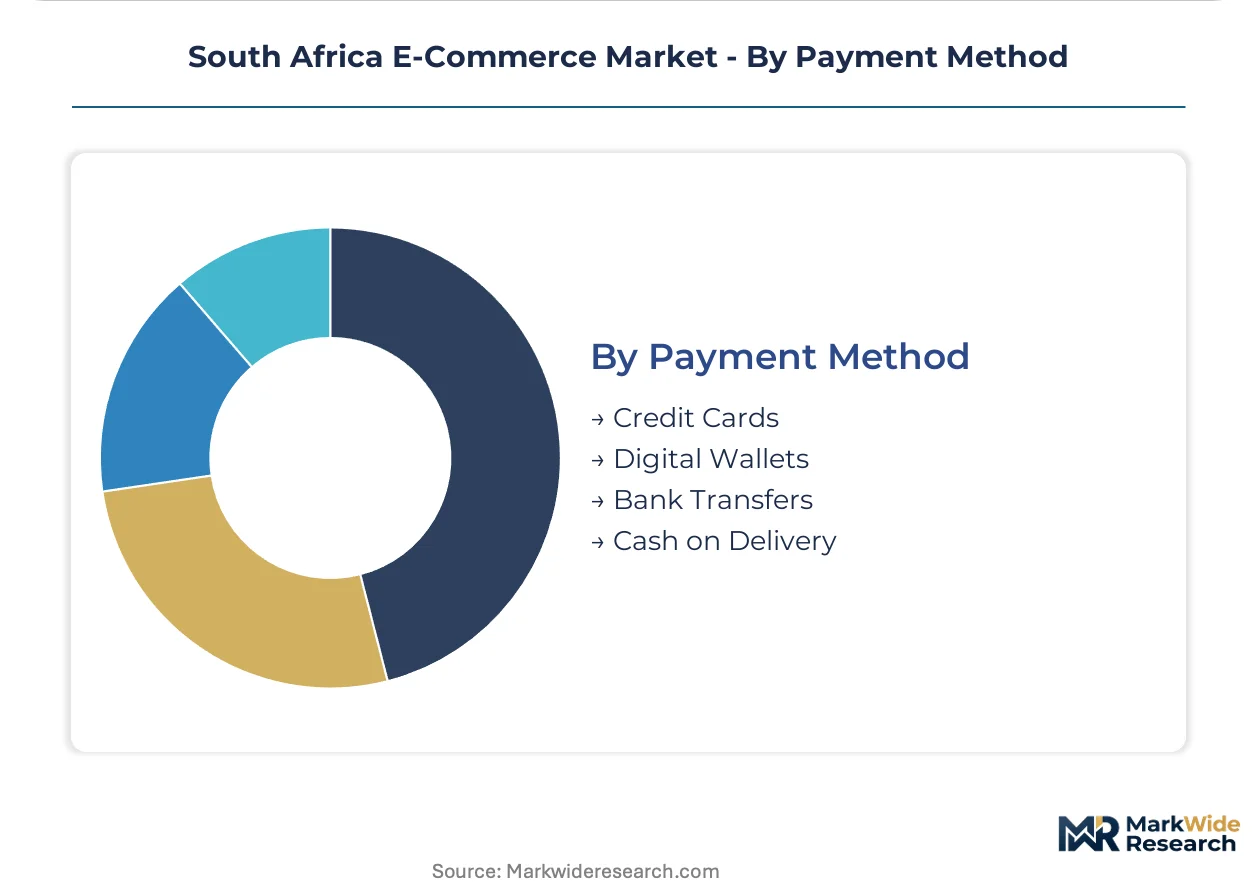
Payment Method:
Digital wallets and instant EFT rails require Information Regulator compliance under POPIA data-handling protocols, while cash on delivery escapes cooling-off right enforcement.
- Digital Wallets:Instant EFT and mobile money integration reduces checkout abandonment in peri-urban nodes with uneven banking infrastructure. POPIA constraints on data retention limit retargeting granularity.
- Credit Cards:Chargeback mechanisms and Section 75 protections align with Consumer Protection Act cooling-off rights, elevating dispute resolution costs for merchants.
- Bank Transfers:Traditional EFT settlement delays compress working capital availability for marketplace vendors.
- Cash on Delivery:Remains prevalent in informal addressing systems where digital payment trust remains underdeveloped.
Digital Wallets lead transaction growth. Credit Cards retain the highest average order value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's e-commerce production concentrates in Gauteng and Western Cape fulfillment corridors, while consumption spreads across peri-urban townships demanding mobile-first infrastructure. This spatial mismatch drives logistics investment patterns and platform architecture decisions.
Gauteng
Johannesburg metropolitan corridors generate the highest transaction velocity through dense same-day delivery networks. The Consumer Protection Act's cooling-off rights enforcement by the National Consumer Commission elevates compliance costs for marketplace vendors operating from Sandton and Pretoria distribution nodes. Takealot anchors fulfillment infrastructure in Johannesburg, compressing delivery windows for electronics and fashion categories.
Western Cape
Cape Town's premium consumer base sustains higher-margin basket economics through private-label exclusivity and subscription loyalty programs. The Protection of Personal Information Act constrains retargeting granularity for Stellenbosch-based fashion retailers deploying algorithmic personalization. Machine learning recommendation engines automate inventory allocation decisions for mid-market apparel platforms serving the Atlantic seaboard corridor.
KwaZulu-Natal
Durban metropolitan demand concentrates in digital wallet penetration where instant EFT rails reduce checkout abandonment. Rand volatility against Asian supplier invoices creates working capital compression for electronics importers using Port of Durban entry points. Mobile money integration unlocks informal sector participation in township nodes surrounding the city.
Eastern Cape
Gqeberha and surrounding township areas present first-mover advantages for platforms building localized fulfillment nodes. Underdeveloped logistics infrastructure constrains same-day delivery promises, forcing compressed image loading and offline browsing features for low-bandwidth connectivity. Spaza shop digitization through B2B marketplace interfaces creates captive supply relationships with micro-retailers.
North West and Limpopo
Rustenburg and Polokwane peri-urban corridors exhibit accelerating smartphone adoption among historically unbanked populations. Cash on delivery remains prevalent where digital payment trust remains underdeveloped and informal addressing systems complicate last-mile routing. Android device adoption expands addressable user bases beyond traditional urban cores.
South Africa E-Commerce Market Competitive Landscape
Capital-heavy fulfillment operators compete with asset-light marketplace aggregators for margin capture in South African e-commerce. The market structure concentrates around three to four dominant platforms with captive logistics infrastructure, while dozens of specialized vertical retailers occupy niche category positions. Strategic archetypes include vertically integrated generalists, premium private-label specialists, and B2B marketplace enablers. Competitive moves center on fulfillment node expansion and subscription loyalty program deployment.
Among South Africa-based integrated retailers, Takealot and Woolworths occupy positions exemplifying divergent margin strategies, while Superbalist represents the fashion-vertical specialist archetype. Takealot anchors generalist marketplace economics through fulfillment infrastructure investment. Woolworths exemplifies premium-tier positioning through WRewards subscription retention mechanics. Superbalist sits within the algorithmic personalization tier, deploying machine learning for size-fit prediction in denim and footwear categories.
| Leading Market Players |
|---|
| Bob Shop |
| Yuppiechef |
| Takealot |
| Clicks |
| Makro |
| Superbalist |
| Woolworths |
| Home Choice |
| Zando |
| Others |
Value Network & Pricing Analysis
Captive fulfillment infrastructure anchors both supply position and pricing power for South African e-commerce platforms, with vertically integrated operators commanding premium positioning through controlled last-mile economics while asset-light aggregators compete on transaction density.
Pricing Analysis
Margin tightening in the mass-market tier reflects fuel price volatility and informal addressing costs that compress delivery economics for township-serving operators. Three-tier pricing structure across premium, standard, and economy levels separates Woolworths' subscription-anchored exclusivity from Takealot's marketplace density and spaza shop B2B interfaces. Price differentiation hinges on delivery speed guarantees and private-label exclusivity. Township micro-retailers exhibit highest price sensitivity, while Atlantic seaboard premium consumers absorb subscription premiums for same-day fulfillment.
Supply Chain Analysis
Dual-sourcing requirements from National Consumer Commission disclosure mandates are forcing electronics importers to qualify multiple Asian manufacturing clusters beyond single-country dependence. Supply concentrates in China, Vietnam, and Bangladesh for fashion and electronics finished goods, with South African platforms drawing from these hubs through Durban port entry points. Component dependencies span semiconductor chips, lithium-ion cells, and synthetic textiles. Single-source vulnerability intensifies around Port of Durban processing delays. Distribution runs through Johannesburg fulfillment nodes that anchor next-day coverage across Gauteng and Western Cape corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South African e-commerce is consolidating around fulfillment-heavy operators as Consumer Protection Act compliance costs and last-mile infrastructure requirements force weaker marketplace vendors toward exit.
For Market Incumbents: Deepen captive logistics infrastructure in Eastern Cape townships before first-mover windows close, while consolidating WRewards-style subscription retention mechanics that lock in metropolitan wallet share. Defend against Superbalist-type algorithmic specialists by investing in size-fit prediction R&D for denim and footwear categories where return rates erode margin. For New Entrants and Emerging Players: Township spaza shop proprietors represent the most penetrable buyer archetype, with B2B marketplace interfaces enabling inventory financing and captive supply relationships that legacy platforms have underdeveloped. Target Gqeberha and surrounding Eastern Cape nodes where localized fulfillment infrastructure remains sparse. Lead with instant EFT integration and compressed-image mobile apps designed for low-bandwidth peri-urban connectivity. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical-specialist acquisitions by generalist platforms seeking algorithmic personalization capabilities or captive township logistics networks. Long-term viability favors operators with owned fulfillment infrastructure and subscription retention mechanics over pure marketplace aggregators exposed to National Consumer Commission disclosure cost inflation. Watch Rand volatility against Asian supplier invoices as the inflection signal for working capital stress among cross-border electronics importers.| Strategic Initiative | Industry Significance |
|---|---|
| Fulfillment Node Expansion | Johannesburg and Cape Town density anchors next-day delivery promises that drive conversion. |
| Subscription Loyalty Program Launch | WRewards-type tiered benefits lock recurring purchase patterns in metropolitan corridors. |
| Algorithmic Personalization Investment | Machine learning size-fit prediction reduces return processing costs in fashion verticals. |
| Digital Wallet Integration | Instant EFT rails reduce checkout abandonment in Durban corridors with uneven card penetration. |
| B2B Marketplace Interface Development | Spaza shop digitization creates captive supply relationships with Eastern Cape micro-retailers. |
Research Methodology
Multi-period observation of transaction velocity, fulfillment infrastructure deployment, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with platform operations executives, last-mile logistics directors, National Consumer Commission compliance officers, and township micro-retailer associations. Secondary validation drew from Takealot and Woolworths annual disclosures, SARS customs processing data, Information Regulator POPIA guidance documents, and mobile network operator smartphone penetration reports. Bottom-up segmentation modeling triangulated against top-down market sizing from banking sector digital wallet transaction disclosures.
Input-output matrices connected smartphone adoption curves, fuel price indices, and Rand volatility patterns to transaction volume and average order value projections across the analysis window. Segmentation dimensions spanned product category, customer archetype, sales channel architecture, payment rail type, and provincial demand cluster. CAGRs derived from logistic diffusion modeling of mobile app penetration and fulfillment node coverage expansion. Forecast inputs included National Consumer Commission enforcement intensity indices and Port of Durban clearance timeline distributions.
Revisions become necessary when Protection of Personal Information Act amendments constrain retargeting granularity beyond current compliance investment trajectories, or when fuel price shocks exceed last-mile cost absorption capacity. Deviation in Rand volatility against Asian supplier currencies would shift the outlook materially for electronics import-dependent platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market