
 Denmark E-Commerce Market | 2026-2036
Denmark E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark E-Commerce Market Outlook
Online marketplace architecture in Denmark is tilting toward integrated fulfillment networks that compress delivery windows. Zalando leverages its European logistics backbone to offer next-day coverage across Zealand and Jutland. Elgiganten anchors consumer electronics demand through click-and-collect integration with its physical store footprint. Boozt specializes in fashion e-commerce, competing on Nordic brand curation and seasonal inventory turnover speed.
Denmark E-Commerce denotes digitally mediated transactions for goods and services conducted over internet-connected platforms, relying on secure payment gateways, inventory management systems, and last-mile distribution networks to complete commercial exchanges. The primary purpose is to reduce friction between producers or retailers and end consumers while enabling data-driven personalization of product discovery and purchasing workflows. Fashion and electronics dominate transaction volumes within product category segmentation, reflecting Danish consumer preference for branded apparel and technology upgrades. B2C channels sustain the largest revenue pools, though B2B procurement platforms for industrial supplies represent an emerging margin opportunity. Mobile apps capture the fastest-growing share of sales channel traffic, driven by smartphone-native shopping behaviors among younger demographics.
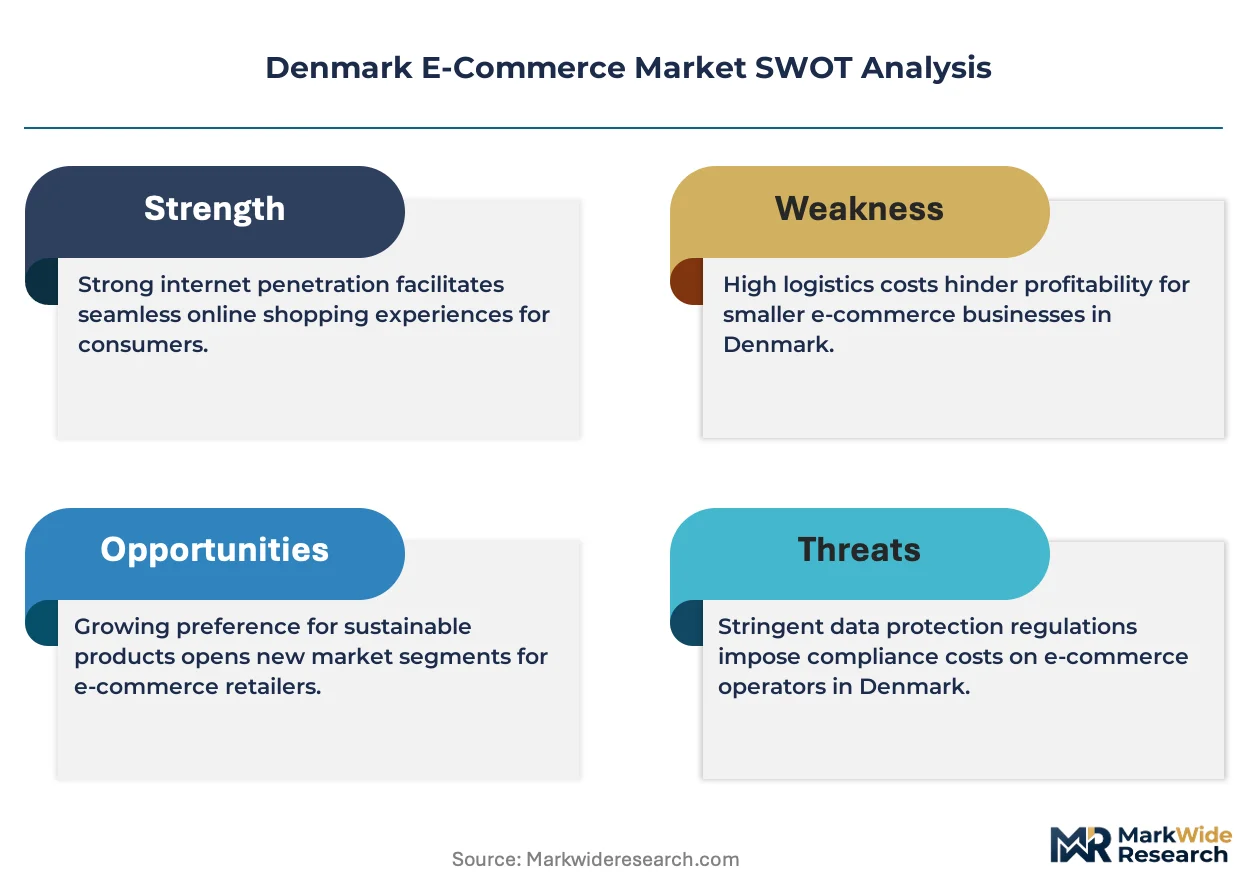
The Danish Business Authority enforces consumer protection standards including withdrawal rights and transparent pricing disclosures for all digital retail transactions. The EU Digital Services Act and GDPR compliance requirements administered by the Danish Data Protection Agency impose content moderation and data handling obligations on platforms operating in Denmark. Stakeholders must monitor how upcoming EU packaging waste regulations reshape fulfillment cost structures and sustainability claims across the value chain.
Market Dynamics
The Danish e-commerce landscape is being fundamentally restructured by the EU Digital Services Act's platform accountability mandates, which force operators to overhaul content moderation systems and algorithmic transparency protocols ahead of enforcement deadlines.
Growth Catalysts
- GDPR-Compliant Data Infrastructure:Danish retailers investing in privacy-first personalization engines are capturing higher customer lifetime value through consent-based targeting frameworks administered by the Danish Data Protection Agency.
- Suburban Household Penetration:Grocery chains report sustained order volume acceleration from Zealand and Jutland residential zones, driven by dual-income families seeking time-compressed fulfillment options.
- Mobile-First Payment Rails:Smartphone-native checkout flows integrating MobilePay and biometric authentication are converting abandoned carts at measurably higher rates than desktop equivalents.
Market Restraints
- Last-Mile Labor Scarcity:Copenhagen and Aarhus distribution hubs face persistent driver shortages during peak seasonal windows, compressing delivery windows and inflating per-stop costs.
- Packaging Waste Compliance Burden:Upcoming EU packaging regulations will mandate extended producer responsibility schemes, forcing fulfillment networks to internalize circular economy costs previously externalized.
- Physical Store Network Lock-In:Established retailers with sunk capital in Zealand and Jutland brick-and-mortar footprints face stranded asset risk when reallocating inventory to pure-play digital channels.
Strategic Opportunities
- B2B Industrial Procurement Platforms:Mid-sized manufacturing enterprises across Funen and Southern Denmark remain underserved by specialized MRO and component sourcing marketplaces.
- Click-and-Collect Infrastructure:Unexploited locker networks and convenience store partnerships in Aarhus peripheral zones offer density arbitrage for cost-conscious fulfillment models.
- CSRD-Aligned Sustainability Claims:The EU Corporate Sustainability Reporting Directive creates first-mover advantage for Danish operators with verified carbon-accounted supply chains and transparent last-mile emissions disclosure.
Industry Challenges
- Warehouse Automation Talent Gap:Robotics integration and WMS optimization require technical competencies scarce in the Danish labor market, delaying fulfillment network upgrades.
- Legacy ERP Integration Friction:Established retailers operating on decades-old inventory systems face data architecture bottlenecks when connecting to real-time marketplace APIs and multi-channel order management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark E-Commerce Market |
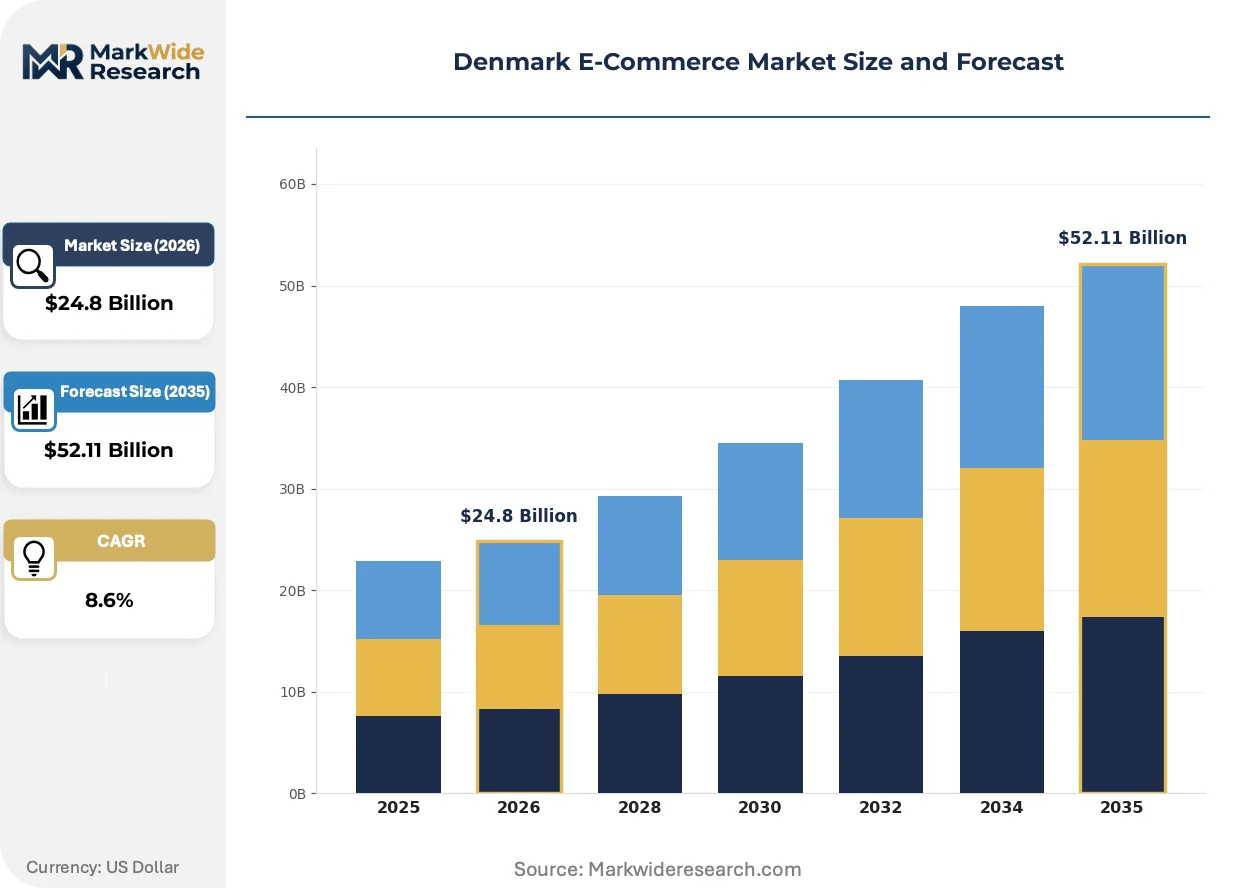
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.11 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Goods, Beauty Products Customer Type: B2C, B2B, C2C, D2C Sales Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Payment Method: Credit Card, PayPal, Mobile Payment, Bank Transfer |
| Companies Covered | Zalando, Elgiganten, Shein, Apple, Ikea, H&M, Boozt, Matas, Coop, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark E-Commerce Market Strategic Shifts
Algorithmic inventory positioning and predictive demand sensing are compressing replenishment cycles across Danish fulfillment networks. Three distinct shifts are redrawing competitive boundaries in the market.
Predictive analytics platforms processing real-time consumption signals from Zealand and Jutland households are rendering obsolete the static safety-stock models that governed pre-pandemic inventory allocation. Regional grocery chains deploy machine learning modules to anticipate suburban basket composition shifts before they materialize. The structural consequence is a collapse in working capital requirements for operators with data infrastructure depth.
The EU Digital Services Act's transparency mandates require Danish platforms to disclose recommendation algorithm parameters and suspend repeat counterfeit sellers. Marketplace operators must restructure seller onboarding workflows and establish Danish-language content moderation teams. Fashion and electronics verticals face the steepest compliance cost escalation given higher counterfeit exposure and algorithmic curation intensity.
Subscription-based replenishment models for household consumables are displacing episodic search-and-purchase behavior among Copenhagen metropolitan consumers. Danish families automate recurring orders for pet supplies, personal care, and pantry staples through platform-native subscription tools. This behavioral pivot concentrates purchase loyalty and reduces price comparison elasticity, particularly among dual-income suburban demographics with predictable consumption rhythms.
Denmark E-Commerce Market Segmentation
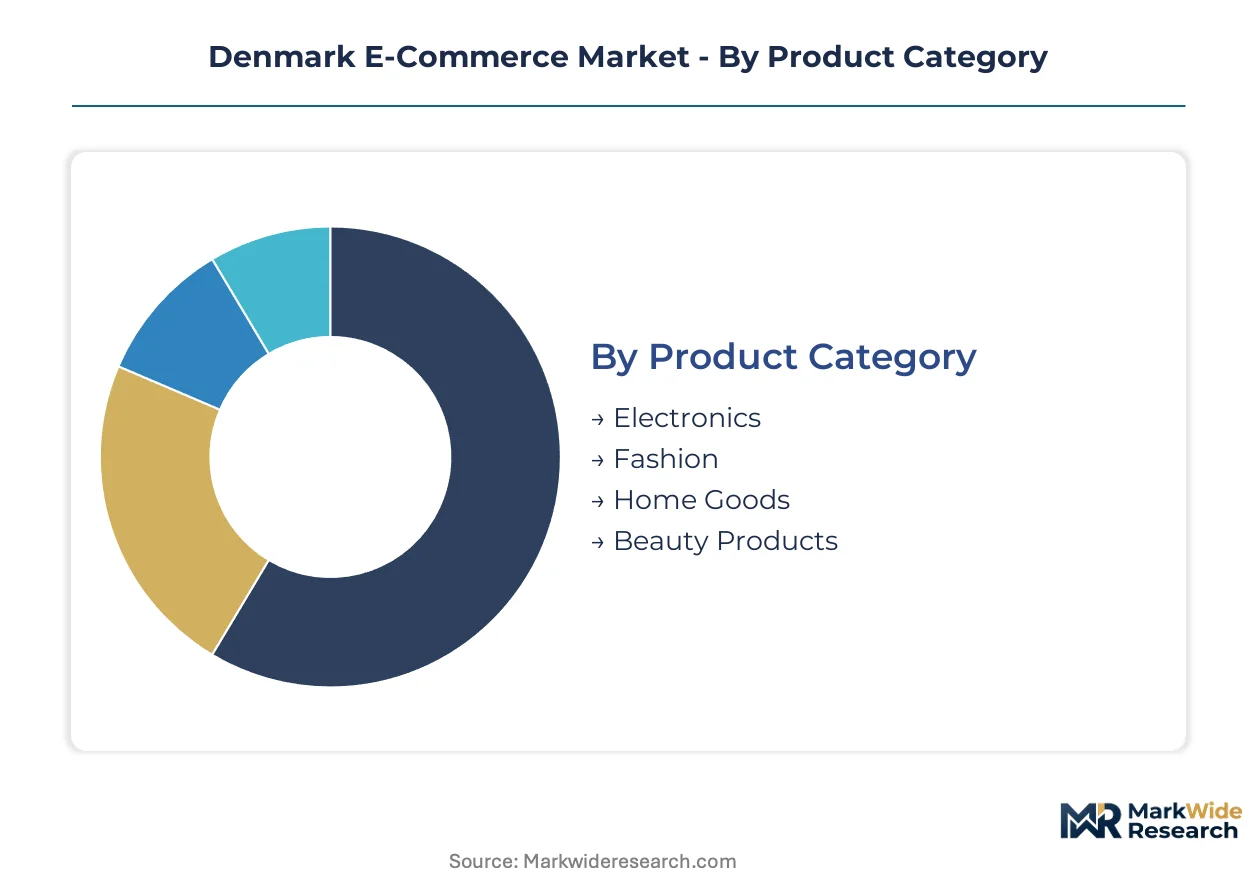
Segmentation in Denmark's e-commerce landscape reveals how distinct fulfillment intensities and service requirements map to profitability profiles. Danish retailers structure operations around these divisions to optimize inventory positioning and last-mile resource allocation across Zealand and Jutland.
Product Category:
After-sales service intensity varies dramatically across product types, with warranty claims and return logistics consuming disproportionate operational bandwidth in certain verticals.
- Electronics:High-value items with complex technical specifications require specialized customer support infrastructure and extended warranty fulfillment networks. Demand concentrates in Copenhagen metropolitan zones where tech-savvy consumers pursue frequent upgrade cycles and premium device categories.
- Fashion:Apparel segments depend on rapid inventory turnover and flexible return policies to accommodate sizing uncertainty and seasonal preference shifts. Zealand suburban households drive order volume through subscription-based replenishment models for branded basics and seasonal collections.
- Home Goods:Bulky fulfillment requirements strain last-mile capacity.
- Beauty Products:Regulatory compliance with EU cosmetic safety standards shapes cross-border sourcing.
By volume, Fashion leads. By growth pace, Electronics is ahead.
Customer Type:
Margin profiles diverge sharply based on order complexity and relationship duration, with enterprise procurement commanding fundamentally different sales economics than individual transactions.
- B2C:Individual consumers purchasing through digital storefronts generate the highest transaction frequency and drive platform infrastructure investments. Copenhagen and Aarhus urban demographics exhibit strongest mobile-first purchasing behaviors with elevated expectations for same-day or next-day fulfillment windows.
- B2B:Industrial procurement platforms serving manufacturing enterprises across Funen and Southern Denmark command larger average order values and longer contract cycles. Mid-sized Danish manufacturers remain underserved by specialized MRO and component sourcing marketplaces, creating expansion opportunity.
- C2C:Peer-to-peer transactions require platform-mediated trust mechanisms.
- D2C:Brand-owned channels bypass marketplace fees but demand proprietary fulfillment investment.
By volume, B2C leads. By margin expansion, B2B is climbing the fastest.
Sales Channel:
Traffic acquisition costs and conversion mechanics differ substantially across channel architectures, influencing how Danish operators allocate marketing spend and technical development resources.
- Online Marketplaces:Aggregator platforms consolidate consumer demand and impose standardized seller performance metrics including delivery speed and return rates. The EU Digital Services Act mandates algorithmic transparency and content moderation investments that reshape marketplace economics for Danish operators.
- Brand Websites:Proprietary storefronts capture first-party customer data and enable personalized merchandising without platform commission structures. Danish fashion and electronics brands prioritize direct channels to build loyalty programs and subscription relationships with suburban household segments.
- Social Media:Discovery-driven purchasing through influencer-curated content accelerates impulse categories.
- Mobile Apps:Native applications integrate biometric authentication and one-tap checkout flows.
By volume, Online Marketplaces lead. By engagement intensity, Mobile Apps are gaining share fastest.
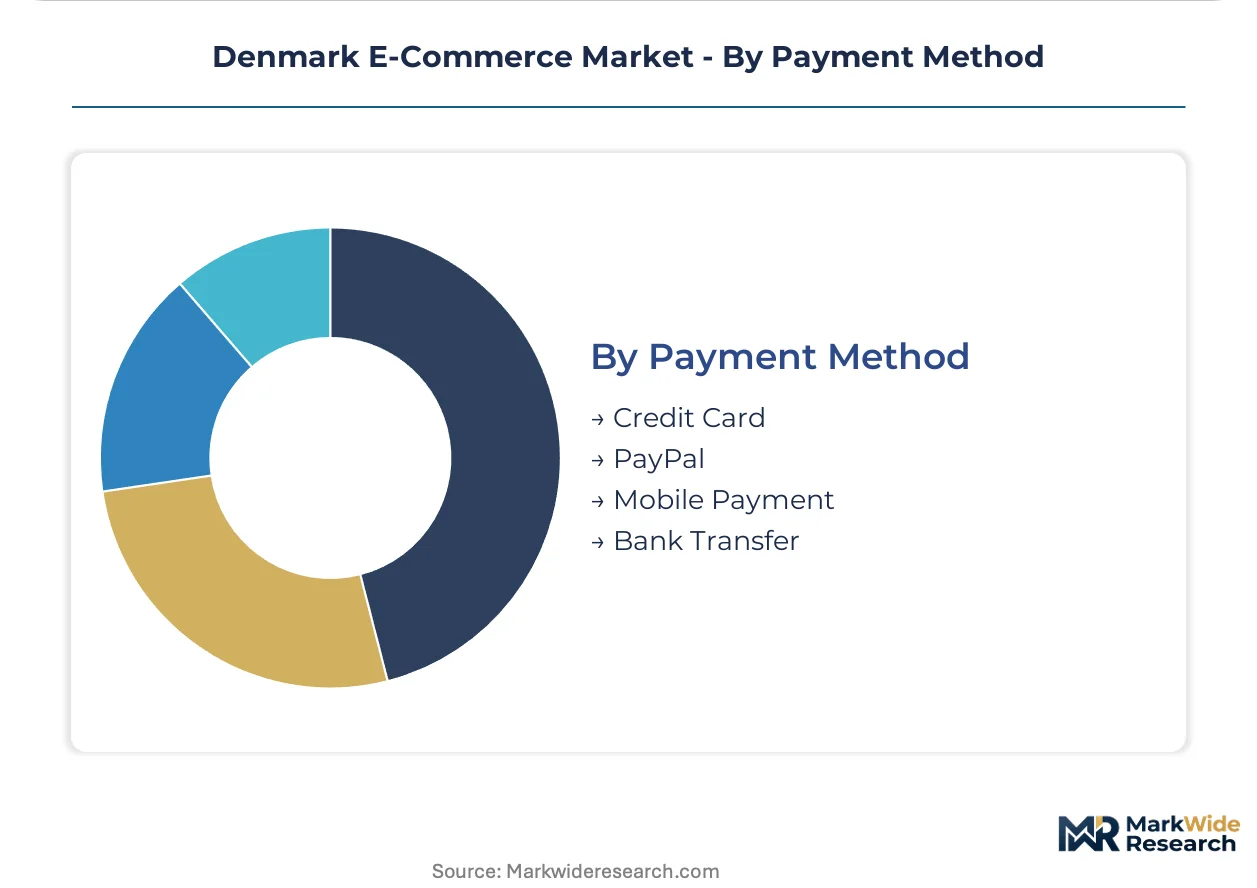
Payment Method:
Checkout friction and fraud exposure vary by payment rail, with Danish consumers showing distinct preferences shaped by mobile banking penetration and trust in domestic financial infrastructure.
- Credit Card:Traditional card networks remain dominant for high-value transactions and cross-border purchases, with Danish issuers implementing strong customer authentication per PSD2 requirements. Copenhagen-based consumers utilize premium card products for electronics and luxury fashion purchases with extended warranty benefits.
- Mobile Payment:Smartphone-native solutions including MobilePay have achieved near-ubiquitous adoption among Danish consumers, particularly for lower-value everyday purchases. Biometric authentication and instant bank integration reduce cart abandonment in grocery and convenience categories across Zealand residential zones.
- PayPal:Cross-border buyer protection appeals to international marketplace users.
- Bank Transfer:Direct debit arrangements suit B2B invoice settlement and subscription billing.
By volume, Mobile Payment leads. By transaction value, Credit Card shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Øresund Bridge and Copenhagen-Malmö Port complex anchor Denmark's logistics capacity, enabling rapid cross-border fulfillment across Zealand and into Southern Sweden. This infrastructure underwrites the concentration of last-mile investments in the Copenhagen metropolitan corridor.
Zealand
Suburban household penetration drives sustained order volume acceleration across Greater Copenhagen and Roskilde municipalities. The Danish Business Authority enforces consumer protection standards including withdrawal rights for all digital transactions. Distribution hubs in Taastrup and Greve leverage automated sorting infrastructure to compress delivery windows for grocery and fashion categories.
Jutland
Aarhus anchors the region's strongest fulfillment infrastructure outside Copenhagen, with mid-sized manufacturing enterprises creating B2B procurement demand. GDPR compliance requirements administered by the Danish Data Protection Agency shape platform data handling obligations. Aalborg and Odense peripheral zones present unexploited click-and-collect density for cost-conscious fulfillment models.
Funen
Industrial procurement platforms for MRO and component sourcing remain underdeveloped across mid-sized manufacturing clusters. The EU Digital Services Act mandates algorithmic transparency for marketplace operators serving Danish consumers. Odense's robotics and automation ecosystem creates talent pipeline potential for warehouse automation upgrades.
Southern Denmark
Cross-border e-commerce flows from Northern Germany influence consumer price comparison behavior in border municipalities. EU packaging waste regulations will force extended producer responsibility schemes across fulfillment networks. Esbjerg's port infrastructure supports direct import channels for international marketplace inventory.
North Denmark Region
Lower population density elevates per-stop delivery costs for pure-play digital operators competing against established store networks. CSRD-aligned sustainability reporting creates first-mover advantage for operators with verified carbon-accounted supply chains. Aalborg's university corridor generates smartphone-native shopping demographics with elevated mobile payment adoption.
Denmark E-Commerce Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fulfillment and payment infrastructure. The Danish e-commerce structure concentrates around three to four dominant marketplace aggregators with pan-Nordic logistics backbones, while specialized vertical players occupy defensible niches. Two strategic archetypes predominate: pan-European fashion and electronics platforms leveraging scale economies, and domestic grocery chains integrating digital channels with physical store networks. Competitive moves center on warehouse automation investments and subscription-based replenishment models that lock in purchase loyalty.
Among pan-European platforms operating in Denmark, Zalando and Elgiganten exemplify the scale-driven archetype with integrated fulfillment networks spanning Zealand and Jutland. Boozt occupies a specialized position within Nordic fashion curation, competing on seasonal inventory velocity rather than assortment breadth. These three companies represent distinct strategic postures: cross-border logistics leverage, physical-digital integration, and regional brand specialization.
| Leading Market Players |
|---|
| Zalando |
| Elgiganten |
| Shein |
| Apple |
| Ikea |
| H&M |
| Boozt |
| Matas |
| Coop |
| Others |
Value Chain & Pricing Dynamics
The Øresund Bridge freight corridor compresses delivery cost differentials between Copenhagen metropolitan zones and peripheral Jutland municipalities, concentrating supply-side leverage among operators with integrated Zealand distribution hubs while fragmenting pricing power for pure-play digital entrants dependent on third-party last-mile networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Danish e-commerce, with premium tiers capturing Copenhagen consumers through same-day delivery guarantees and white-glove installation services. Price differentiation hinges on fulfillment speed and after-sales service intensity, particularly in electronics where extended warranty bundling commands measurable premiums. Cost compression in standard-tier grocery and fashion categories is intensifying because suburban household consolidation drives volume concentration toward chains with captive logistics infrastructure. Small urban households exhibit highest price sensitivity, while dual-income suburban families prioritize convenience over marginal cost savings.
Supply Chain Analysis
EU dual-use technology export controls limit automated warehouse robotics flows from Chinese manufacturers, constraining Danish fulfillment network upgrades and elevating equipment lead times for operators seeking automation. Geographic supply concentration centers on Germany for last-mile delivery vehicles and warehouse automation systems, Poland for apparel manufacturing, and the Netherlands for cross-border fulfillment infrastructure. Raw material dependencies include lithium-ion battery cells for electric delivery fleets, corrugated packaging substrates subject to EU waste regulations, and semiconductor components for IoT-enabled inventory tracking. Single-source vulnerability runs through German automotive OEMs supplying electric vans. Distribution runs through Copenhagen-Taastrup-Greve hub-and-spoke networks with Aarhus as secondary node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among dual-income suburban households consolidating purchase volumes through subscription platforms, fragmenting negotiating leverage for smaller urban consumer segments and elevating switching costs for operators lacking replenishment automation.
For Market Incumbents: Build data infrastructure moats through predictive demand sensing and algorithmic inventory positioning that compress replenishment cycles beyond competitor reach. Incumbents should consolidate click-and-collect density in Aarhus peripheral zones before cost-conscious entrants exploit locker network gaps. The EU Digital Services Act's content moderation mandates threaten margin structures for marketplace operators lacking Danish-language moderation teams. Vertical integration into automated sorting infrastructure at Taastrup and Greve distribution hubs locks in delivery window compression. For New Entrants and Emerging Players: Establish a beachhead in B2B industrial procurement platforms serving mid-sized manufacturing enterprises across Funen and Southern Denmark, where specialized MRO marketplaces remain underdeveloped. Target Odense's robotics ecosystem for warehouse automation talent arbitrage, leveraging proximity to technical competencies scarce in broader Danish labor markets. A direct sales force model penetrating manufacturing procurement offices offers lower customer acquisition costs than competing for saturated B2C traffic. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy retailers with stranded Zealand and Jutland brick-and-mortar footprints seeking digital channel pivots without proprietary fulfillment investment. Long-term viability favors operators with CSRD-aligned carbon-accounted supply chains and verified last-mile emissions disclosure, as sustainability reporting mandates reshape procurement criteria. Watch for inflection when EU packaging waste regulations force extended producer responsibility scheme adoption, compressing margins for operators without circular economy infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Deployment | Robotics integration at Taastrup hubs compresses per-order fulfillment costs below third-party logistics benchmarks. |
| Subscription Platform Launch | Recurring revenue models lock in Copenhagen metropolitan household purchase loyalty and reduce price elasticity. |
| B2B Marketplace Expansion | Industrial procurement platforms capture mid-sized Funen manufacturers underserved by specialized sourcing channels. |
| Click-and-Collect Infrastructure | Locker networks in Aarhus peripheral zones exploit density arbitrage for cost-conscious fulfillment economics. |
| CSRD Compliance Investment | Verified carbon-accounted supply chains create first-mover advantage under EU sustainability disclosure mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Danish Business Authority enforcement records, EU Digital Services Act implementation guidance, and logistics infrastructure databases. Primary interviews engaged e-commerce platform executives, last-mile distribution operators, grocery chain digital channel heads, and warehouse automation specialists. Secondary sources encompassed Danish Data Protection Agency GDPR compliance bulletins, customs trade flow data, and municipal planning documents for Copenhagen and Aarhus distribution zones. Bottom-up transaction volume modeling triangulated against top-down market sizing from retail sector revenue aggregates.
Forecast inputs incorporate mobile payment adoption curves, suburban household penetration rates, and fulfillment infrastructure capacity constraints across the projection horizon. Segmentation dimensions modeled include product category intensity, customer type margin profiles, sales channel traffic acquisition costs, and regional logistics accessibility. CAGRs derived from historical velocity trends adjusted for regulatory phase-in schedules and infrastructure investment pipelines. Industry-specific inputs encompass EU packaging regulation compliance timelines and warehouse automation talent availability.
Macroeconomic conditions sit as an overlay; deviation in Danish consumer confidence indices, freight fuel cost volatility, or cross-border labor mobility would shift the trajectory. Forecasts reflect documented assumptions regarding Digital Services Act enforcement intensity and circular economy cost internalization. Material shifts in EU packaging waste regulation implementation timelines or warehouse automation equipment import restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market