

Ambient Commerce Enablement Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Ambient Commerce Enablement Infrastructure Market Insights
Platform licensing revenue is narrowing relative to managed service margins across the ambient commerce stack. Amazon leverages its fulfillment-integrated sensor networks to anchor in-store experience deployments. NVIDIA specializes in edge inference silicon that sustains real-time analytics throughput for smart shelf applications. Google competes through voice commerce APIs that extend its search infrastructure into retail environments.
Ambient commerce enablement infrastructure comprises distributed sensor arrays, edge computing nodes, and AI-driven contextual intelligence layers that process behavioral signals without explicit user initiation, typically operating with sub-100ms latency to trigger payment, personalization, or inventory actions. The architecture serves retail chains, hospitality providers, and transportation services by collapsing the gap between consumer presence and transactional completion. Cloud-based deployment leads current adoption while edge computing represents the fastest-expanding segment as latency requirements tighten for real-time analytics workloads. Payment integration solutions concentrate margin pools where tokenization standards and processor certifications create vendor stickiness.
The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on contextual intelligence and user behavior tracking deployments across European retail networks. The FCC governs spectrum allocation for in-store IoT mesh networks in the United States, while China's SAMR enforces data localization for consumer-facing analytics platforms. Stakeholders must monitor divergence between regional AI governance frameworks when architecting cross-border ambient commerce infrastructure.
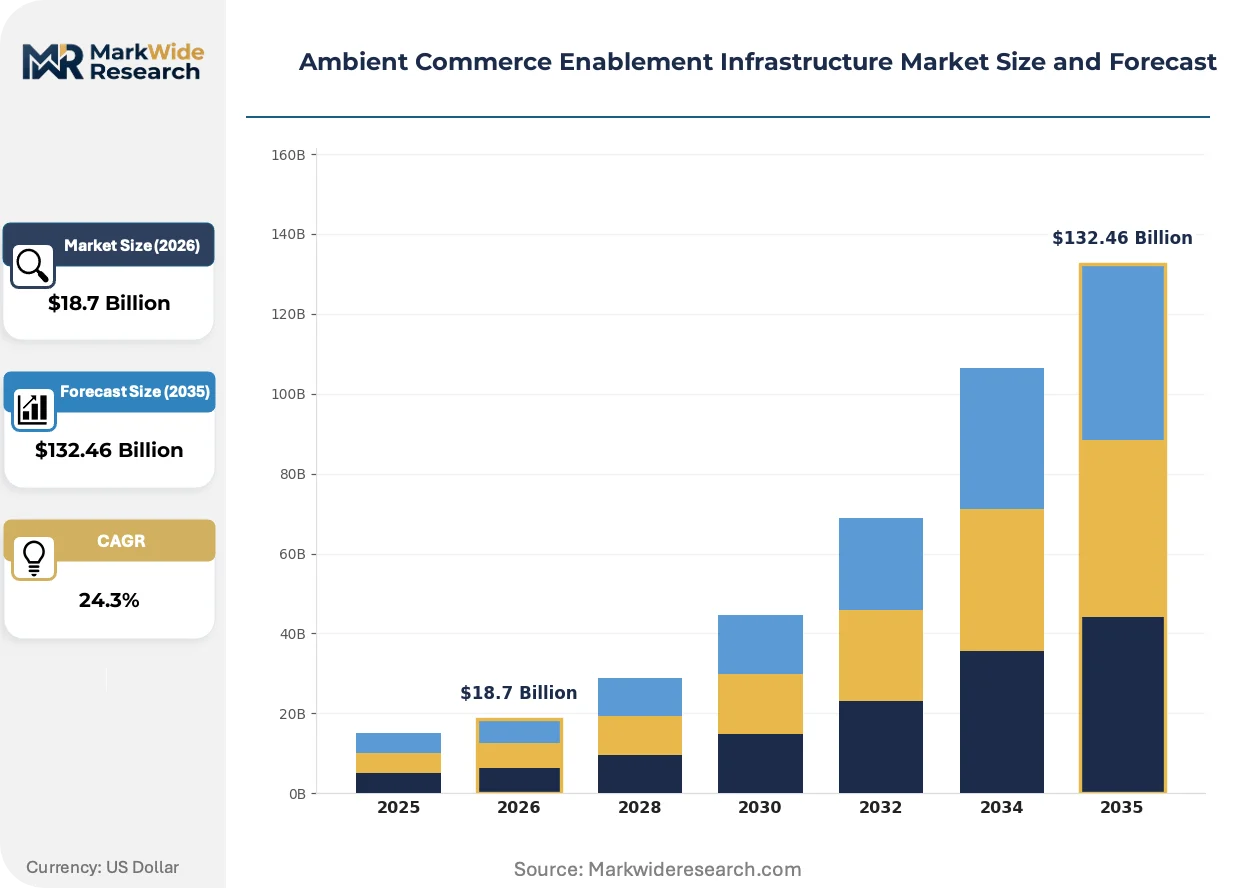
Market Dynamics
Edge computing hardware cost curves are compressing deployment thresholds for distributed sensor networks, enabling retail chains to justify ambient commerce infrastructure at store counts previously reserved for flagship locations. This supply-side cost collapse is accelerating network density without proportional increases in capital allocation.
Growth Catalysts
- EU AI Act compliance mandates:European retail networks must deploy algorithmic transparency layers for consumer-facing analytics, creating certified vendor demand for contextual intelligence platforms that embed explainability by design.
- Smart shelf sensor miniaturization:Weight-sensing and computer vision modules now integrate at sub-$50 per-shelf economics, letting grocery and convenience chains retrofit existing fixtures rather than rip-and-replace.
- Urban commercial density in China:Tier-1 city clusters support sensor-network economies where payment-integrated kiosks achieve utilization rates that amortize hardware costs within eighteen months.
Market Restraints
- GDPR data minimization requirements:Behavioral signal retention limits force infrastructure vendors to architect edge-first processing architectures that never centralize raw biometric or movement data.
- Edge silicon supply concentration:Inference-optimized chip fabrication concentrates among two foundry ecosystems, exposing deployment timelines to capacity allocation decisions outside vendor control.
- Legacy POS integration friction:Tokenized payment triggers must interface with twenty-year-old retail management systems whose API layers lack real-time event handling capacity.
Strategic Opportunities
- India's urban retail modernization:Organized retail penetration in Tier-2 cities remains below fifteen percent, creating first-mover terrain for kiosk networks that bypass traditional checkout infrastructure entirely.
- Voice commerce API convergence:Natural language processing layers are merging with spatial audio localization, enabling hands-free reordering in hospitality environments where screen interaction is impractical.
- Japan's METI smart city incentives:Municipal subsidies for autonomous retail experiments in transit hubs are covering thirty to fifty percent of sensor network deployment costs for qualified operators.
Industry Challenges
- Embedded systems firmware security:Distributed edge nodes require over-the-air update pipelines that satisfy PCI-DSS tokenization standards while maintaining sub-100ms inference latency.
- Computer vision model drift:Seasonal lighting variations and merchandise assortment changes degrade shelf-level accuracy, demanding continuous retraining workflows that most retail IT organizations lack.
- Cross-border data residency conflicts:China's SAMR localization rules and EU GDPR extraterritoriality create architectural impossibilities for unified fleet management across certain country pairs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambient Commerce Enablement Infrastructure Market Trends and Innovations
Latency requirements for real-time payment authorization are forcing architectural decisions that privilege edge inference over cloud round-trips. Three technology and policy vectors are compressing deployment timelines and reshaping competitive positioning.
Event-driven edge inference architectures are collapsing the traditional separation between sensory data capture and transactional completion. Grocery chains in Germany and the United States are retrofitting produce sections with weight-sensing shelves that trigger replenishment orders and customer mobile notifications simultaneously. This compression eliminates the latency buffer that previously justified centralized processing, shifting margin capture toward hardware-integrated platform vendors.
The EU AI Act's risk classification system is mandating human-in-the-loop overrides for high-risk automated decision systems in European retail environments. Contextual intelligence platforms must now embed explainability modules that surface algorithmic logic to store managers before inventory or pricing actions execute. Hospitality and transportation segments face lighter compliance burdens, concentrating vendor engineering resources on grocery and apparel use cases.
Buyer procurement patterns are fragmenting across three distinct contracting models: capital purchase with self-managed integration, subscription-based device-as-a-service, and revenue-share arrangements tied to transaction throughput. Large-format retailers in the United States favor the third model, while German mid-market chains prefer operational leases that transfer firmware liability to vendors. This bifurcation is forcing platform providers to maintain parallel pricing architectures rather than standardized term sheets.
Ambient Commerce Enablement Infrastructure Market Segmentation
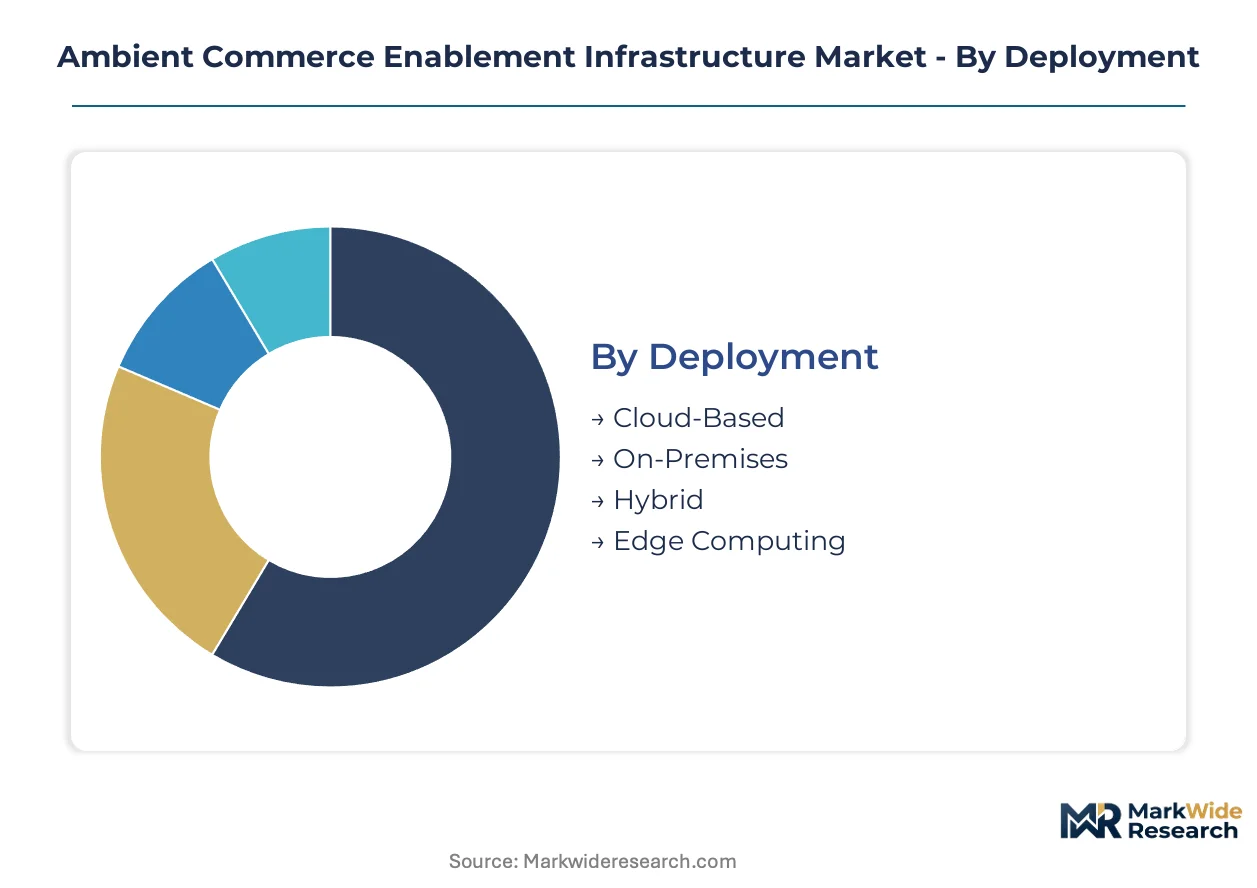
Segmentation in ambient commerce enablement infrastructure reveals how vendor engineering resources and service delivery models must adapt across deployment architectures and end-use environments. Each dimension carries distinct firmware liability profiles and integration complexity that shape contract structures and margin capture.
Deployment:
After-sales-service intensity varies sharply across deployment modes, with edge nodes demanding continuous firmware stewardship while cloud layers shift operational burden to hyperscaler SLAs.
- Edge Computing:Distributed inference nodes process behavioral signals locally with sub-100ms latency requirements. Retail chains in Germany and the United States prioritize this architecture to satisfy GDPR data minimization mandates and eliminate cloud round-trip delays for payment authorization.
- Cloud-Based:Centralized processing layers aggregate cross-store analytics and model training workflows. Demand concentrates among mid-market hospitality providers lacking dedicated edge infrastructure teams, though latency constraints limit deployment to non-transactional use cases.
- Hybrid:Split architectures run inference at the edge while federating insights to cloud data lakes. Grocery chains favor this model for seasonal demand forecasting that combines real-time shelf signals with historical warehouse data.
- On-Premises:Fully isolated deployments serve transportation services and event venues with intermittent connectivity or stringent data residency requirements.
Cloud-based deployment holds the largest share; momentum sits with edge computing.
Solution Type:
Margin pools concentrate where certification requirements and processor integrations create switching costs that lock in vendor relationships across refresh cycles.
- Payment Integration:Tokenization layers and PCI-DSS compliance pipelines embed deeply into legacy POS architectures. This segment commands premium pricing in the United States where large-format retailers demand revenue-share contracting tied to transaction throughput.
- Contextual Intelligence:Algorithmic transparency modules explain automated inventory and pricing decisions to satisfy EU AI Act human-in-the-loop mandates. European grocery chains drive certified vendor demand as compliance deadlines approach.
- Real-Time Analytics:Stream processing engines trigger replenishment orders and customer notifications from shelf-level events.
- User Behavior Tracking:Spatial analytics platforms map shopper journeys without centralizing raw biometric data.
- Personalized Marketing:Trigger-based promotion engines match mobile proximity signals to inventory availability.
Payment integration commands the deepest vendor relationships; contextual intelligence is climbing the fastest.
Application:
Hardware retrofit economics and sensor density requirements fragment addressable markets across physical retail formats and digital touchpoints.
- Smart Shelves:Weight-sensing and computer vision modules integrate at sub-$50 per-shelf economics, enabling grocery and convenience chains to retrofit existing fixtures rather than rip-and-replace. Demand concentrates in China where tier-1 city clusters support sensor-network economies.
- In-Store Experience:Ambient sensor networks collapse the gap between consumer presence and transactional completion through seamless checkout and guided navigation. German retail chains deploy these systems to differentiate against pure-play e-commerce.
- Digital Kiosks:Payment-integrated terminals achieve utilization rates that amortize hardware costs within eighteen months in dense urban commercial zones.
- Mobile Commerce:Proximity-triggered wallet integrations extend ambient infrastructure to handheld devices.
- Voice Commerce:Natural language processing layers merge with spatial audio localization for hands-free reordering in hospitality environments.
In-store experience holds the largest share; smart shelves are gaining share fastest.
End User:
Procurement sophistication and integration legacy vary dramatically across sectors, with retail chains demanding revenue-share models while transportation services prefer capital purchase with self-managed deployment.
- Retail Chains:Large-format grocers and apparel retailers drive volume through kiosk networks and smart shelf retrofits that bypass traditional checkout infrastructure. The United States and Germany anchor demand as edge computing hardware costs compress deployment thresholds.
- Hospitality Providers:Hotels and restaurants deploy voice commerce APIs and spatial audio systems where screen interaction is impractical for guests.
- Transportation Services:Transit hubs and airports leverage autonomous retail experiments subsidized by Japan's METI smart city incentives covering thirty to fifty percent of sensor network costs.
- E-Commerce Platforms:Pure-play operators extend fulfillment-integrated sensor networks into physical pickup locations.
- Event Organizers:Temporary deployments for sports and entertainment venues require rapid-install edge nodes with minimal infrastructure dependency.
Retail chains hold the largest share; hospitality providers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail chains in the United States deploy edge-heavy architectures prioritizing payment integration speed, while German operators favor explainable AI layers that satisfy regulatory transparency mandates before transaction completion.
United States
FCC spectrum allocations for in-store IoT mesh networks enable dense sensor deployments across grocery and convenience formats. Large-format retailers demand revenue-share contracting tied to transaction throughput, concentrating vendor relationships among payment-integrated platform providers. Edge computing hardware cost curves compress deployment thresholds in Texas and California retail corridors.
Germany
EU AI Act algorithmic transparency mandates drive certified vendor demand for contextual intelligence platforms embedding explainability by design. GDPR data minimization requirements force edge-first processing architectures that never centralize raw behavioral data. Retail chains in Bavaria and North Rhine-Westphalia retrofit produce sections with weight-sensing shelves triggering replenishment orders.
China
Tier-1 city clusters support sensor-network economies where payment-integrated kiosks achieve utilization rates amortizing hardware costs within eighteen months. SAMR data localization rules enforce architectural isolation for consumer-facing analytics platforms. Yangtze River Delta and Pearl River Delta commercial density anchors smart shelf deployment volumes.
Japan
METI smart city incentives cover thirty to fifty percent of sensor network deployment costs for autonomous retail experiments in transit hubs. Municipal subsidies concentrate in Kanto and Kansai regions where hospitality providers deploy voice commerce APIs for hands-free reordering. Edge inference latency requirements tighten for real-time payment authorization in dense urban commercial zones.
India
Organized retail penetration in Tier-2 cities remains below fifteen percent, creating first-mover terrain for kiosk networks bypassing traditional checkout infrastructure. BIS certification requirements shape vendor qualification criteria for payment-integrated deployments. Maharashtra and Karnataka urban retail modernization programs accelerate digital kiosk network density.
Ambient Commerce Enablement Infrastructure Market Competitive Landscape
Capability concentration sits with semiconductor and cloud infrastructure specialists; scale advantage sits with fulfillment-integrated retail operators and hyperscaler platform providers. The vendor base organizes around three strategic archetypes: edge inference silicon fabricators, voice commerce API platforms, and sensor-network-integrated retail operators. Dominant competitive moves include backward integration into captive edge hardware supply and strategic API licensing partnerships that extend search infrastructure into physical retail environments.
Within the fulfillment-integrated operator archetype, Amazon anchors scale-driven positioning through sensor-network deployment across physical retail footprints. Among semiconductor specialists, NVIDIA exemplifies edge inference capability concentration for real-time analytics throughput. Google occupies a position within the voice commerce API tier, representing hyperscaler platform extension into retail environments through natural language processing layers.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Microsoft |
| Samsung Electronics |
| Alibaba Group |
| Cisco Systems |
| IBM |
| NVIDIA |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in edge inference silicon foundries concentrates bargaining power with Taiwan Semiconductor Manufacturing and Samsung Foundry, forcing infrastructure vendors to accept longer lead times and prepayment terms while passing cost rigidities through to retail chain buyers in Germany and the United States.
Pricing Analysis
Long-term offtake agreements dominate procurement between large-format retailers and payment-integrated platform providers, though spot purchasing persists for edge computing hardware subject to foundry allocation volatility. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS certified deployments with dedicated firmware support from self-managed integrations. Cost compression in standard-tier contextual intelligence platforms is intensifying because NVIDIA and Qualcomm are prioritizing automotive and data center allocations. Mid-market hospitality providers exhibit the highest price sensitivity, while United States grocery chains with revenue-share arrangements show greater tolerance for upfront hardware premiums.
Supply Chain Analysis
Export-control restrictions on advanced inference accelerators limit flows from United States designers to Chinese manufacturing partners, fragmenting procurement strategies across geopolitical blocs. Taiwan, South Korea, and the United States anchor supply for 7nm and below edge silicon, while China maintains captive capacity at mature nodes for domestic kiosk deployments. Raw material dependencies include gallium nitride substrates, high-bandwidth memory stacks, and precision MEMS sensors. Single-source vulnerability concentrates in EUV lithography equipment held by ASML. Distribution runs through direct OEM relationships for tier-one retail chains and regional systems integrators serving mid-market hospitality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States large-format retailers demanding revenue-share contracting, fragmenting vendor margins and forcing platform providers to absorb hardware depreciation risk.
For Market Incumbents: Pre-empt margin erosion by securing captive edge silicon allocation through foundry partnership commitments before automotive and data center sectors absorb remaining capacity. Defend against hyperscaler voice commerce API encroachment by embedding explainability modules that satisfy EU AI Act mandates before Google or Amazon achieve certification. Prioritize backward integration into sensor module assembly to reduce exposure to Chinese MEMS supply volatility. For New Entrants and Emerging Players: Tier-2 Indian cities with organized retail penetration below fifteen percent represent the most penetrable entry point for kiosk networks bypassing legacy POS infrastructure entirely. Japanese transit hub subsidies covering thirty to fifty percent of deployment costs create a second beachhead for qualified operators with METI relationships. Lead with device-as-a-service operational leases that transfer firmware liability to vendors, matching German mid-market procurement preferences. For Investors and Strategic Acquirers: Capital is best deployed toward edge-first contextual intelligence platforms with EU AI Act certification and existing foundry allocation guarantees. Long-term viability hinges on architectural isolation from cloud round-trip dependencies as latency requirements tighten. Watch for inflection when United States large-format retailers begin demanding sub-50ms payment authorization as a procurement threshold.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Commitment | Secures allocation priority for inference-optimized silicon before automotive demand absorbs capacity. |
| EU AI Act Certification Investment | Creates vendor stickiness among German retail chains facing algorithmic transparency mandates. |
| Edge-First Architecture Development | Eliminates cloud round-trip latency for payment authorization in dense urban commercial zones. |
| Revenue-Share Contracting Capability | Matches United States large-format retailer procurement preferences for transaction-throughput alignment. |
| Sensor Module Assembly Integration | Reduces exposure to Chinese MEMS supply volatility and compresses per-shelf retrofit economics. |
Research Methodology
A standing panel of edge infrastructure CTOs, retail chain procurement directors, foundry account managers, and hospitality technology integrators provided ongoing calibration against secondary validation from SEC hyperscaler capex disclosures, FCC spectrum allocation filings, EU AI Act implementation guidance, and METI smart city subsidy program documentation. Bottom-up unit economics for smart shelf deployments were triangulated with top-down market sizing from sensor network hardware shipments.
Scenario-bracketing around edge computing cost curves and regulatory compliance timelines shaped projections across deployment architecture, solution type, application format, and end-user sector segmentation. CAGRs were derived from installed base growth rates and replacement cycle assumptions, with cross-validation against payment transaction volume elasticity and urban commercial density thresholds in tier-one city clusters.
Practitioners should monitor foundry capacity reallocation toward automotive AI accelerators and EU AI Act enforcement variance across member states for early signals of forecast deviation. Material shifts in United States export control scope for inference silicon or China's SAMR data localization enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.