
 Hungary E-Commerce Market | 2026-2036
Hungary E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary E-Commerce Market Outlook
Asset-light marketplace models and third-party logistics leasing are tilting competitive dynamics toward platforms that avoid fixed warehouse investments. eMAG leverages its regional fulfillment network to sustain cross-border inventory velocity. Alza.hu anchors its position through specialized electronics assortment depth and same-day delivery infrastructure in Budapest. Tesco competes by integrating grocery e-commerce with its established brick-and-click footprint across Hungarian counties.
Hungary e-commerce denotes digitally mediated transactions for goods and services conducted through web-based interfaces and mobile applications, relying on electronic payment settlement, automated order management, and last-mile distribution coordination. The sector functions as a retail infrastructure layer that reduces intermediation costs while expanding vendor reach beyond physical catchment areas. Electronics and fashion categories dominate transaction volume, with electronics commanding higher average order values and fashion driving repeat purchase frequency. Mobile apps represent the fastest-growing distribution channel, capturing time-fragmented consumer behavior through push-notification merchandising and one-tap checkout optimization. Business-to-business customer types yield superior margin pools due to negotiated contract terms and predictable replenishment cycles.
Hungary's e-commerce operators must navigate EU GDPR data governance, EU Digital Services Act content moderation obligations, and national consumer protection enforcement by the country's competition authority. These frameworks elevate compliance costs for cross-border sellers while creating certification barriers that favor established domestic platforms. Stakeholders should monitor forthcoming EU AI Act implementation timelines for automated product recommendation systems, as algorithmic transparency requirements could reshape customer acquisition economics.
Market Dynamics
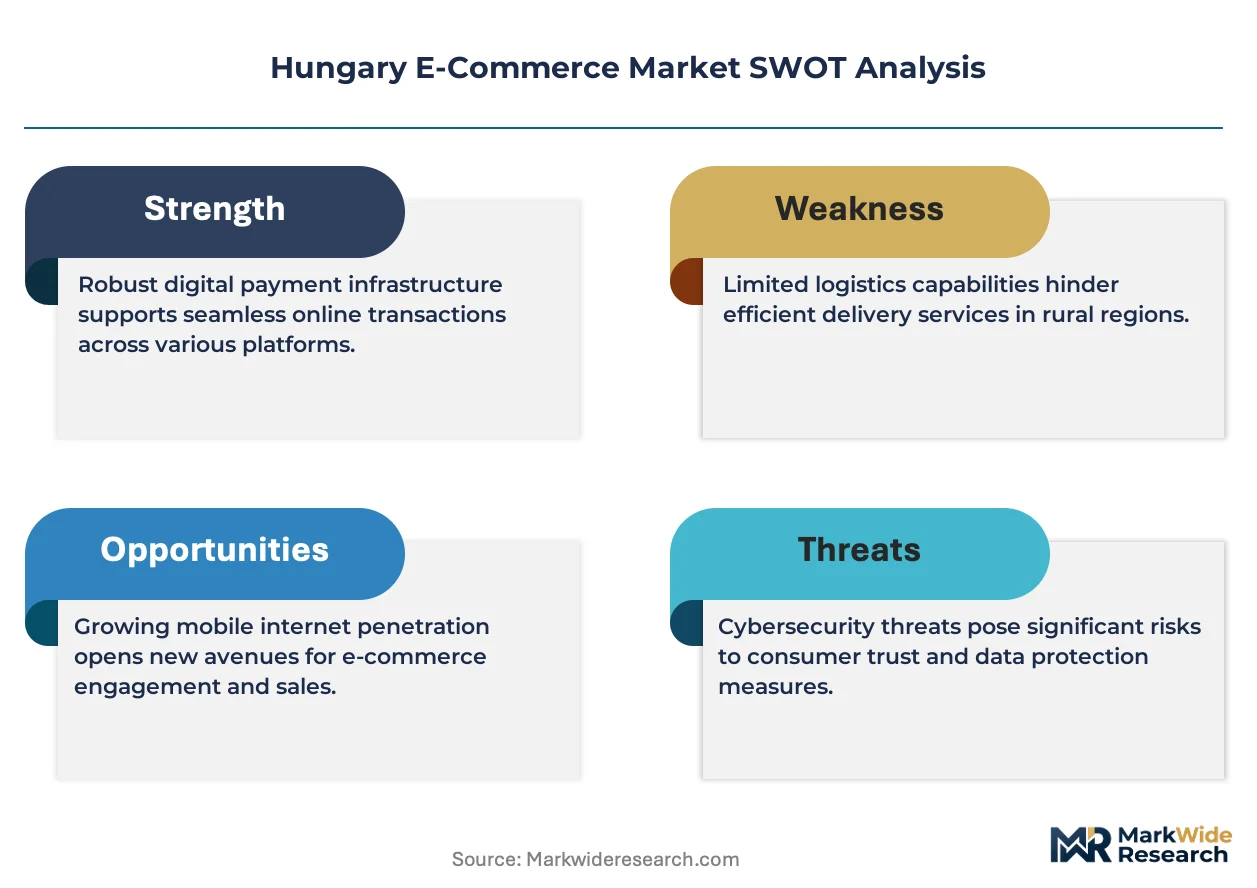
EU Digital Services Act compliance obligations are forcing Hungarian e-commerce platforms to restructure content moderation workflows and algorithmic transparency protocols, elevating operational costs for cross-border sellers while creating certification barriers that favor established domestic operators.
Growth Catalysts
- GDPR data governance frameworks:Harmonized EU privacy standards reduce legal fragmentation for Hungarian platforms expanding into neighboring member states, lowering cross-border compliance overhead.
- Mobile app distribution channels:Push-notification merchandising and one-tap checkout optimization capture time-fragmented consumer behavior among Budapest metropolitan corridor users.
- Business-to-Business contract structures:Negotiated replenishment cycles and predictable volume commitments yield superior margin pools compared to volatile consumer transactions.
Market Restraints
- Last-mile logistics density:Rural Hungarian counties outside Budapest and Pest regions suffer from sparse third-party delivery infrastructure, inflating per-order fulfillment costs.
- EU AI Act algorithmic transparency:Forthcoming automated product recommendation system requirements threaten to compress customer acquisition economics for personalization-dependent platforms.
- Electronics category concentration:High average order value dependence on consumer electronics creates vulnerability to semiconductor supply volatility and import duty fluctuations.
Strategic Opportunities
- Debrecen-Szeged corridor expansion:Secondary Hungarian cities with university populations and rising disposable income remain underpenetrated by same-day delivery networks.
- Grocery e-commerce integration:Brick-and-click infrastructure combining physical store footprints with digital ordering captures recurring household purchase frequency.
- EU Green Deal logistics incentives:Electric vehicle last-mile fleet subsidies and carbon footprint disclosure requirements favor early adopters of sustainable distribution models.
Industry Challenges
- Data science talent scarcity:Budapest's competitive technology labor market drives compensation inflation for machine learning engineers optimizing recommendation engines.
- Legacy warehouse management system integration:Established retailers face friction retrofitting automated order management protocols into aging inventory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary E-Commerce Market |
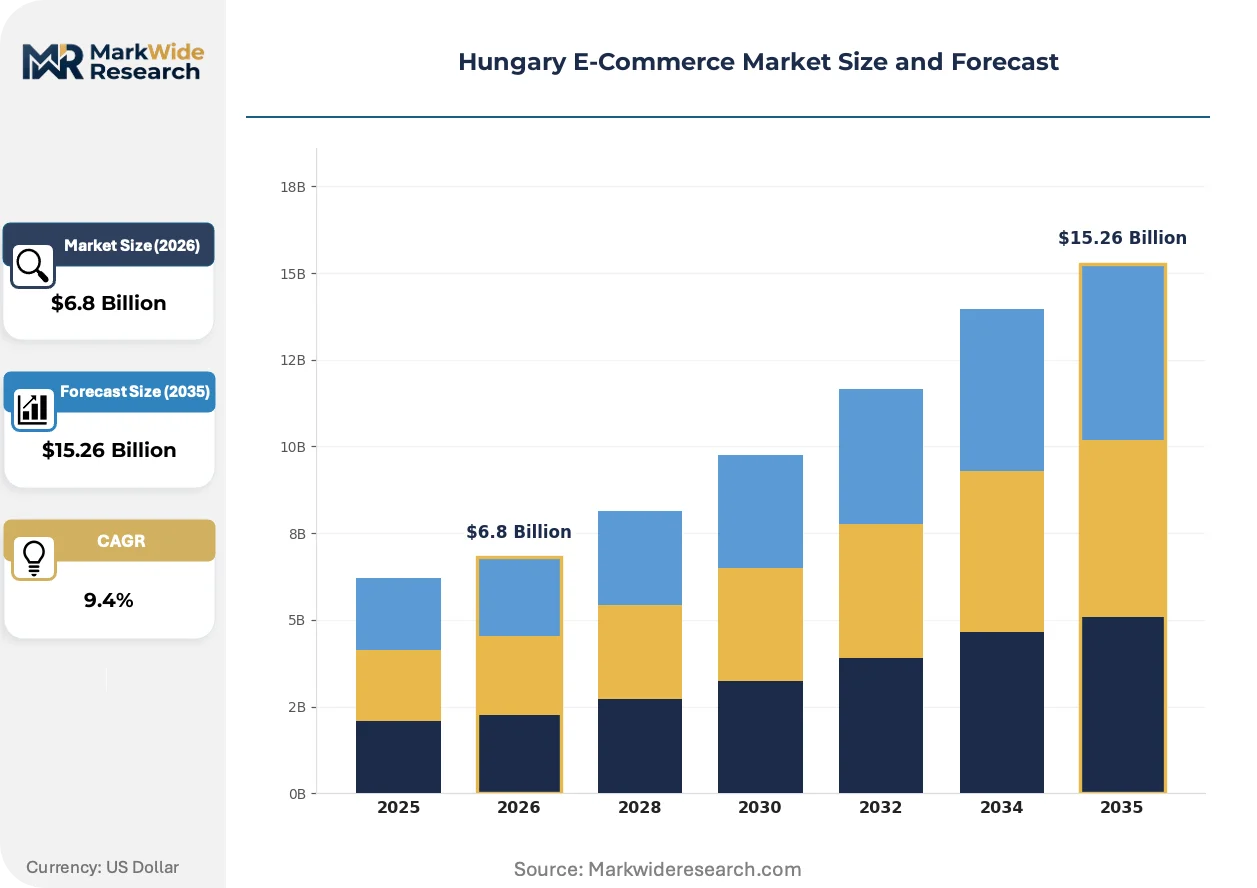
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Home Goods, Beauty Customer Type: Retail Consumers, Business-to-Business, Wholesale Buyers, Government Agencies Distribution Channel: Online Marketplaces, Company Websites, Social Media, Mobile Apps Payment Method: Credit Card, Digital Wallets, Bank Transfer, Cash on Delivery |
| Companies Covered | eMAG, Tesco, Alza.hu, iPon, Aqua, Kifli.hu, Euronics, Pepita, MediaMarkt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary E-Commerce Market Strategic Shifts
Asset-light marketplace architectures and third-party logistics leasing arrangements are compressing capital requirements for new market entrants, tilting competitive dynamics toward platforms that avoid fixed warehouse investments and prioritize inventory velocity over ownership.
Artificial intelligence-powered demand forecasting systems analyze real-time search behavior and seasonal pattern data to optimize procurement decisions. Mid-sized Hungarian fashion retailers deploy these tools to reduce overstock exposure. Traditional static inventory planning is rendering obsolete as predictive models compress working capital cycles.
EU Digital Services Act content moderation obligations require Hungarian platforms to maintain transparent complaint-handling mechanisms and risk assessment documentation. Smaller cross-border sellers face disproportionate compliance burdens. Domestic operators with established legal teams capture market share as foreign competitors retreat from enforcement-intensive jurisdictions.
Subscription-based replenishment models for household consumables displace one-time purchase behavior among Budapest metropolitan consumers. Grocery and personal care categories lead this shift. Younger demographics demonstrate highest conversion rates to automated recurring delivery schedules.
Hungary E-Commerce Market Segmentation
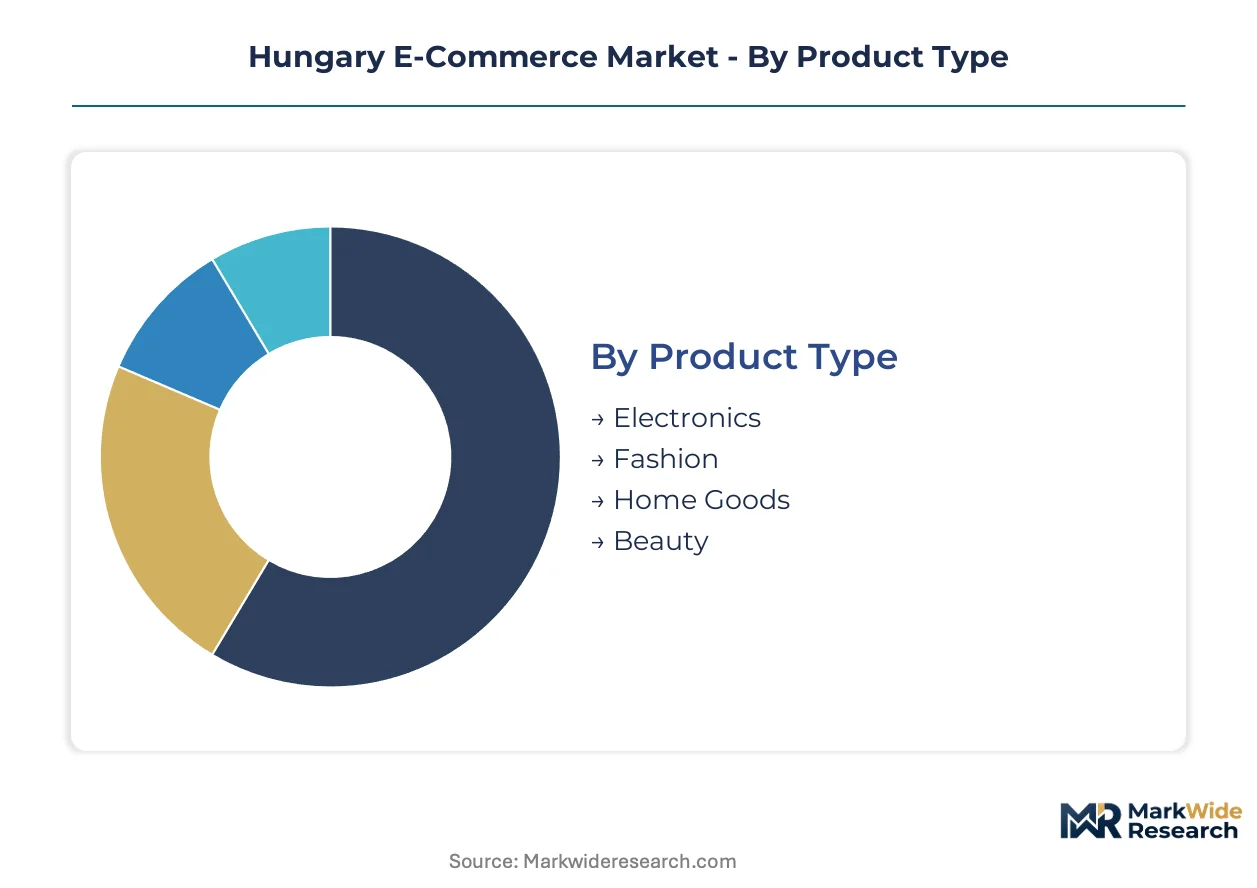
Segmentation in Hungary's e-commerce market reveals how divergent customer behaviors and channel preferences create distinct operational requirements. Platform operators must calibrate inventory depth, payment infrastructure, and fulfillment speed to match the specific demands of each slice.
Product Type:
Cost tier differentiation separates premium electronics from mass-market fashion, with each demanding unique logistics capabilities and return handling protocols.
- Electronics:High-value consumer devices and computing equipment require secure warehousing, extended warranty support, and specialized last-mile handling. Budapest metropolitan corridor buyers drive volume for smartphones and laptops, with semiconductor supply volatility creating inventory planning complexity.
- Fashion:Apparel and accessories generate elevated return rates due to sizing mismatches, necessitating reverse logistics infrastructure. Younger demographics in university cities accelerate adoption of mobile-first fashion discovery platforms.
- Home Goods:Furniture and household furnishings face bulky fulfillment constraints that favor brick-and-click retailers with existing store networks.
- Beauty:Cosmetics and personal care products depend on temperature-controlled storage and authenticity verification to combat counterfeit infiltration.
Electronics commands the established base. The steepest expansion runs through Fashion.
Customer Type:
Application context distinguishes household purchasing from institutional procurement, with contract structures and margin profiles diverging sharply across these use cases.
- Retail Consumers:Individual Hungarian households purchasing for personal use exhibit high price sensitivity and impulse-driven mobile conversion. Budapest and Pest county residents concentrate demand for same-day delivery options.
- Business-to-Business:Corporate buyers negotiate volume-based pricing and predictable replenishment cycles, yielding superior margin stability. IT equipment and office supplies dominate transaction flows.
- Wholesale Buyers:Reseller intermediaries purchasing in bulk for downstream distribution require flexible minimum order quantities and extended payment terms.
- Government Agencies:Public sector procurement follows EU public procurement directives with mandatory tender processes and transparency requirements that elongate sales cycles.
Retail Consumers anchors volume throughput. Business-to-Business delivers the strongest margin expansion trajectory.
Distribution Channel:
Volume concentration patterns reveal how mobile interfaces are capturing time-fragmented Hungarian consumer behavior away from traditional desktop experiences.
- Online Marketplaces:Multi-vendor platforms aggregate inventory breadth and leverage network effects to reduce customer acquisition costs. eMAG and regional competitors dominate this channel in Hungary.
- Company Websites:Direct-to-consumer branded sites retain customer data ownership and margin control but demand heavier marketing investment to drive traffic.
- Social Media:Instagram and TikTok commerce integrations enable discovery-based purchasing among younger Hungarian demographics, though conversion rates trail intent-driven channels.
- Mobile Apps:Native smartphone applications deliver push-notification merchandising and one-tap checkout optimization. Budapest metropolitan users show highest engagement frequency.
Online Marketplaces holds the dominant position. Mobile Apps is gaining share fastest among emerging channels.
Payment Method:
Maturity of digital financial infrastructure varies across Hungarian demographic segments, with cash persistence in rural counties contrasting Budapest's wallet adoption.
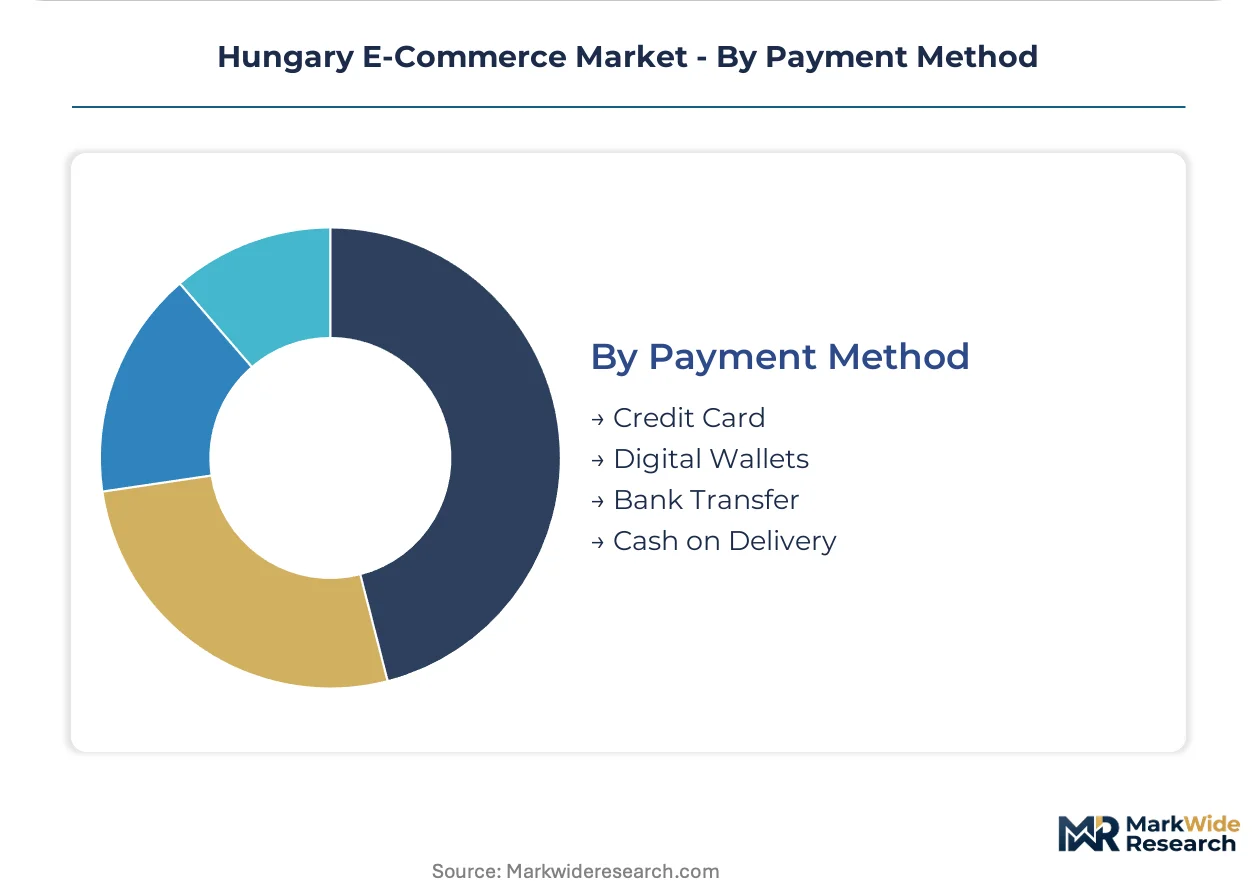
- Credit Card:Traditional card networks remain prevalent for high-value electronics purchases, with 3D Secure authentication adding friction to checkout flows.
- Digital Wallets:Apple Pay, Google Pay, and regional alternatives accelerate transaction velocity through biometric authentication. Younger Budapest consumers drive adoption curves.
- Bank Transfer:Direct account debits appeal to cost-conscious Hungarian buyers avoiding card fees, though settlement delays extend order processing windows.
- Cash on Delivery:Physical payment upon receipt persists in rural counties with lower banking penetration, inflating per-order handling costs and return risks.
Credit Card maintains the largest transaction base. Digital Wallets shows the steepest climb in adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hungary's e-commerce trade flows tilt toward import dependence, with cross-border purchases from EU neighbors and Asian manufacturing hubs outpacing domestic platform exports to adjacent Central European markets.
Budapest Metropolitan Corridor
Same-day delivery infrastructure and concentrated disposable income drive transaction density across Budapest and Pest county. GDPR harmonization with EU data standards reduces legal friction for platforms serving Austrian and Slovak buyers. The M0 ring logistics cluster hosts third-party fulfillment centers operated by eMAG and Alza.hu.
Debrecen-Szeged Axis
University populations in Hungary's second-tier cities generate fashion and electronics demand through mobile-first discovery platforms. National consumer protection enforcement by the competition authority creates certification hurdles for foreign marketplace entrants. Debrecen's emerging tech workforce supports localized customer service operations for regional e-commerce expansions.
Western Transdanubia
Proximity to Austrian and Slovenian borders positions Győr and Sopron as cross-border fulfillment nodes for EU-wide inventory distribution. EU Digital Services Act content moderation obligations elevate operational costs for platforms handling multilingual customer bases. Sopron's retail corridor attracts Austrian shoppers seeking price-differentiated electronics assortments.
Southern Great Plain
Agricultural supply chains and lower logistics density shape B2B procurement patterns for farm equipment and inputs. Hungary's alignment with EU Green Deal logistics incentives favors electric vehicle fleet pilots in Kecskemét distribution zones. Szeged's pharmaceutical manufacturing base sustains specialized B2B e-commerce for laboratory supplies.
Hungary E-Commerce Market Competitive Environment
On the supply side, the industry is consolidating around asset-light marketplace models that lease third-party logistics rather than owning fixed warehouse infrastructure. Three strategic archetypes dominate: regional fulfillment networks leveraging cross-border inventory velocity, specialized electronics retailers anchoring through assortment depth, and grocery-integrated brick-and-click operators capturing recurring purchase frequency. Competitive intensity manifests through same-day delivery network expansion and mobile app engagement optimization.
Among Hungary-based marketplace operators, eMAG exemplifies the regional network archetype through its fulfillment footprint spanning neighboring EU markets. Alza.hu occupies a specialist position in high-velocity electronics distribution, while Tesco anchors the grocery-integrated segment through county-level store network leverage. These three players represent distinct competitive vectors rather than overlapping strategic positions.
| Leading Market Players |
|---|
| eMAG |
| Tesco |
| Alza.hu |
| iPon |
| Aqua |
| Kifli.hu |
| Euronics |
| Pepita |
| MediaMarkt |
| Others |
Value Chain & Pricing Dynamics
Chinese electronics manufacturing clusters anchor Hungary's e-commerce cost structure, with semiconductor and consumer device imports concentrating margin pools in Budapest-based fulfillment operators and cross-border marketplace platforms that control last-mile delivery pricing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures in B2B e-commerce channels, while retail consumers face per-unit transactional pricing with premium-mid-economy differentiation driven by delivery speed tiers and brand certification levels. Price differentiation stems from same-day delivery premiums versus standard fulfillment windows, alongside volume scale discounts for enterprise procurement. Pricing pressure intensifies in electronics categories due to semiconductor supply volatility and import duty fluctuations. Small and medium enterprises demonstrate highest price sensitivity, while government agencies exhibit lowest sensitivity due to mandated tender compliance requirements.
Supply Chain Analysis
EU dual-use technology export controls and semiconductor manufacturing equipment restrictions limit flows from Dutch and Japanese suppliers into Chinese fabrication facilities, creating upstream bottlenecks that ripple through Hungarian electronics inventory planning. Geographic supply concentration centers on China for consumer electronics assembly, Germany for industrial automation components, and Taiwan for semiconductor wafers. Raw material dependencies span lithium-ion cells, display panels, and rare earth magnets. Single-source vulnerability in advanced chip sourcing represents the dominant structural risk. Distribution runs through Budapest metropolitan third-party logistics hubs with radial spoke networks into secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's e-commerce incumbents face substitution pressure from quick-commerce platforms and social media native checkout, requiring defensive positioning against impulse-purchase behavior migration away from traditional marketplace interfaces.
For Market Incumbents: Insulate core grocery and electronics categories through backward integration into private-label assortment development and captive same-day delivery fleet deployment. Deepen vertical control over Budapest M0 ring fulfillment nodes to preempt emerging platform entrants from securing logistics density. Counter quick-commerce substitution by embedding subscription replenishment workflows into household consumables purchasing patterns.
For New Entrants and Emerging Players: Debrecen and Szeged university corridor underpenetration by specialized fashion discovery platforms offers white-space entry with lower customer acquisition costs than saturated Budapest channels. Target B2B laboratory supplies and agricultural equipment procurement in Southern Great Plain counties where incumbent marketplace coverage remains thin. Deploy mobile-first social commerce integration as the primary go-to-market angle to capture younger demographic purchasing behavior.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional electronics specialists and grocery-integrated brick-and-click operators that have exhausted organic expansion trajectories. Five-to-ten year viability hinges on EU Digital Services Act compliance infrastructure and AI Act algorithmic transparency readiness. Acquisition target archetypes include mid-sized fashion retailers with predictive inventory systems and established reverse logistics capabilities. Monitor EU Green Deal logistics subsidy disbursement timing as inflection indicator for sustainable distribution model competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Same-Day Delivery Network Expansion | Captures Budapest metropolitan corridor demand concentration against quick-commerce substitutes. |
| Private-Label Electronics Development | Reduces semiconductor supply volatility exposure through controlled sourcing relationships. |
| Subscription Replenishment Platform Launch | Locks recurring household purchase frequency in grocery and personal care categories. |
| EU DSA Compliance Infrastructure Investment | Creates certification barriers favoring established domestic operators over cross-border sellers. |
| Electric Vehicle Fleet Pilot Program | Aligns with EU Green Deal subsidies while reducing last-mile carbon disclosure liability. |
Study Parameters
Cross-validation between executive interviews at e-commerce platform operators and customs trade data anchors the qualitative findings in observable transaction flows. Primary research incorporated discussions with marketplace logistics directors, category merchant managers, third-party fulfillment operators, and competition authority enforcement leads. Secondary sources included EU Digital Services Act implementation guidance, GDPR compliance documentation, national consumer protection enforcement records, and mobile app engagement analytics. Bottom-up channel volume estimates and top-down GDP-attribution approaches were reconciled to establish baseline market sizing.
Calibration against historical growth trajectories in comparable Central European markets informed the projection framework across the analysis window. Segmentation modeling incorporated product type tiers, customer contract structures, distribution channel formats, and payment method adoption curves. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines and logistics infrastructure deployment schedules. Forecast inputs included EU AI Act algorithmic transparency requirement phase-ins and electric vehicle subsidy program enrollment trajectories.
Practitioners should monitor EU AI Act enforcement commencement and semiconductor supply normalization indicators for early signals of forecast deviation. Material shifts in EU Digital Services Act content moderation cost structures or cross-border import duty regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Italy Dropshipping Market