
 Global Golf Rangefinders Market | 2026-2036
Global Golf Rangefinders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Golf Rangefinders Market Analysis
China is tilting toward expanded optical component manufacturing for golf rangefinders, with domestic suppliers scaling lens and laser diode capacity to serve assembly partners abroad. Bushnell Golf leverages its retail presence across North American pro shops and big-box sporting goods chains to sustain brand visibility. Nikon Corporation anchors its position through precision optics heritage that extends into tournament-grade measurement devices. Garmin Ltd. competes by integrating GPS rangefinders with broader wearable ecosystems that capture swing analytics and course mapping.
A golf rangefinder is an electro-optical instrument that calculates distance to a fixed target—typically a flagstick—using pulsed laser time-of-flight or satellite-positioning triangulation, with accuracy thresholds often rated within one yard at six hundred yards. Its primary commercial purpose is to provide golfers with precise yardage data that replaces manual estimation and speeds pace of play. Laser rangefinders dominate the product type mix due to superior accuracy on tree-lined courses where GPS signals degrade, while hybrid rangefinders that combine laser pinpointing with GPS hazard mapping represent the fastest-growing configuration as players seek multifunctionality. Bluetooth-enabled technology segments are expanding as smartphone-compatible devices allow shot tracking and course data synchronization through native apps.
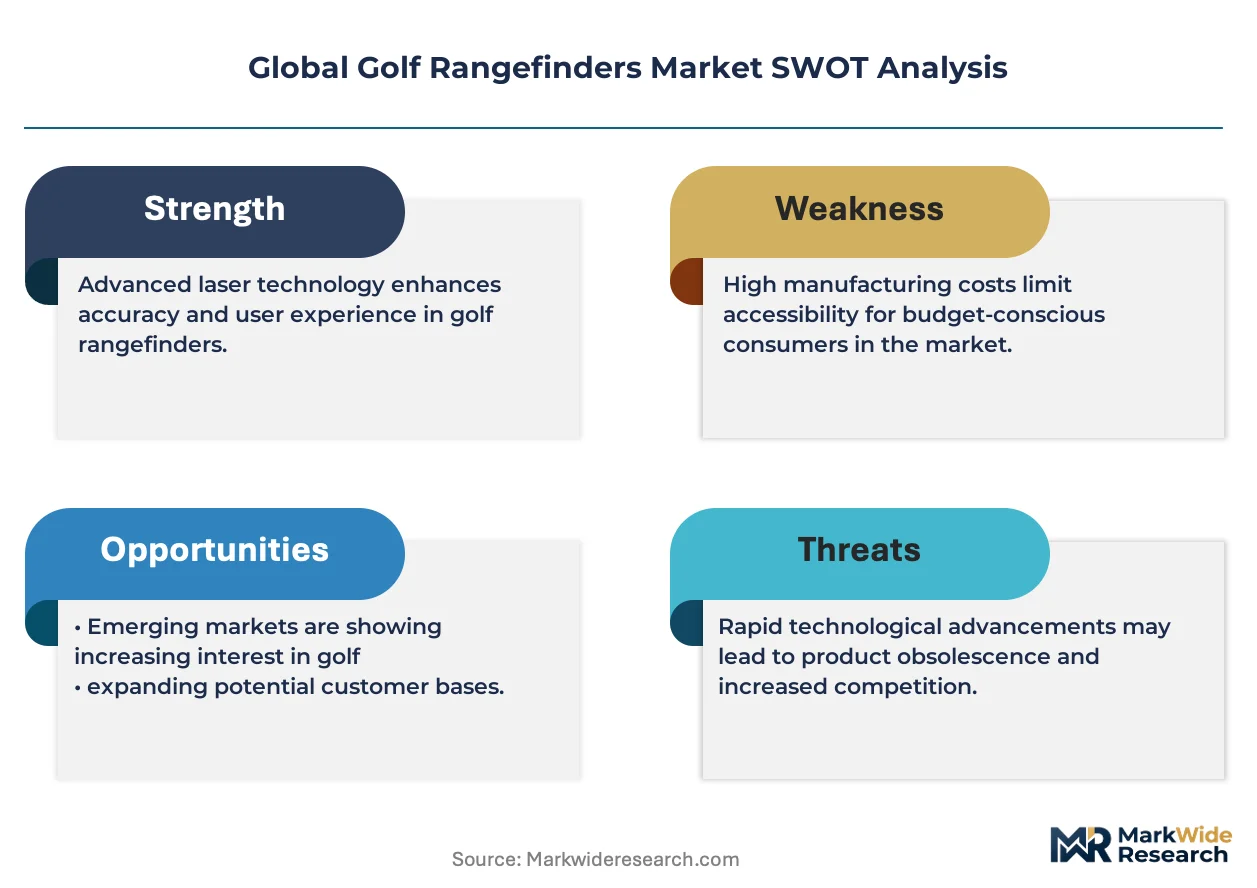
The USGA and R&A govern equipment conformance for tournament play, with their joint Distance Measuring Device rules permitting rangefinders only when slope compensation is disabled during competition, which shapes product design toward switchable tournament modes. The FCC regulates laser emission levels in the United States under 21 CFR 1040, while Japan's METI oversees electrical appliance safety certification for GPS units sold domestically. Stakeholders must monitor whether golf governing bodies tighten restrictions on real-time wind and elevation data, as such rulings would force hardware and software recalibration across installed device bases.
Market Dynamics
The USGA and R&A's joint Distance Measuring Device rules are forcing manufacturers to engineer switchable tournament modes that disable slope compensation, fundamentally altering hardware-software integration requirements across all product tiers.
Growth Catalysts
- USGA Equipment Conformance Rules:The governing body's allowance of rangefinders in amateur competition, provided slope features are disabled, has normalized device ownership across tournament players and recreational golfers alike.
- GPS-Laser Hybrid Technology:Multifunctional devices combining laser pinpointing with satellite-based hazard mapping are capturing players seeking single-instrument course management solutions.
- Japan Course Density:Concentrated golf infrastructure across the Japanese archipelago sustains replacement demand for precision measurement devices among club members and daily-fee players.
Market Restraints
- Laser Diode Supply Concentration:Dependence on Asian optical component foundries creates vulnerability to semiconductor fabrication bottlenecks and export licensing delays.
- FCC Laser Emission Limits:The 21 CFR 1040 regulatory ceiling on pulsed laser power constrains maximum effective range and measurement reliability in adverse weather conditions.
- Smartphone Substitution:Free GPS applications with course mapping functionality erode entry-level rangefinder demand among casual players who prioritize cost over optical precision.
Strategic Opportunities
- South Korea Amateur Tournaments:Expanding corporate-sponsored golf events and country club membership growth create untapped demand for tournament-legal measurement devices.
- Bluetooth Shot Tracking Integration:Smartphone synchronization enabling swing analytics and statistical performance monitoring opens subscription revenue streams beyond hardware sales.
- United States Big-Box Retail Penetration:Sporting goods chains and golf specialty retailers offer shelf space expansion for mid-tier products targeting gift purchasers and equipment upgraders.
Industry Challenges
- Optical Calibration Talent Scarcity:Precision lens alignment and laser path engineering expertise concentrates among aging specialists in Japanese and German optics traditions.
- METI Electrical Safety Certification:Japan's appliance safety approval timeline extends product launch schedules and requires dedicated domestic testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Golf Rangefinders Market |
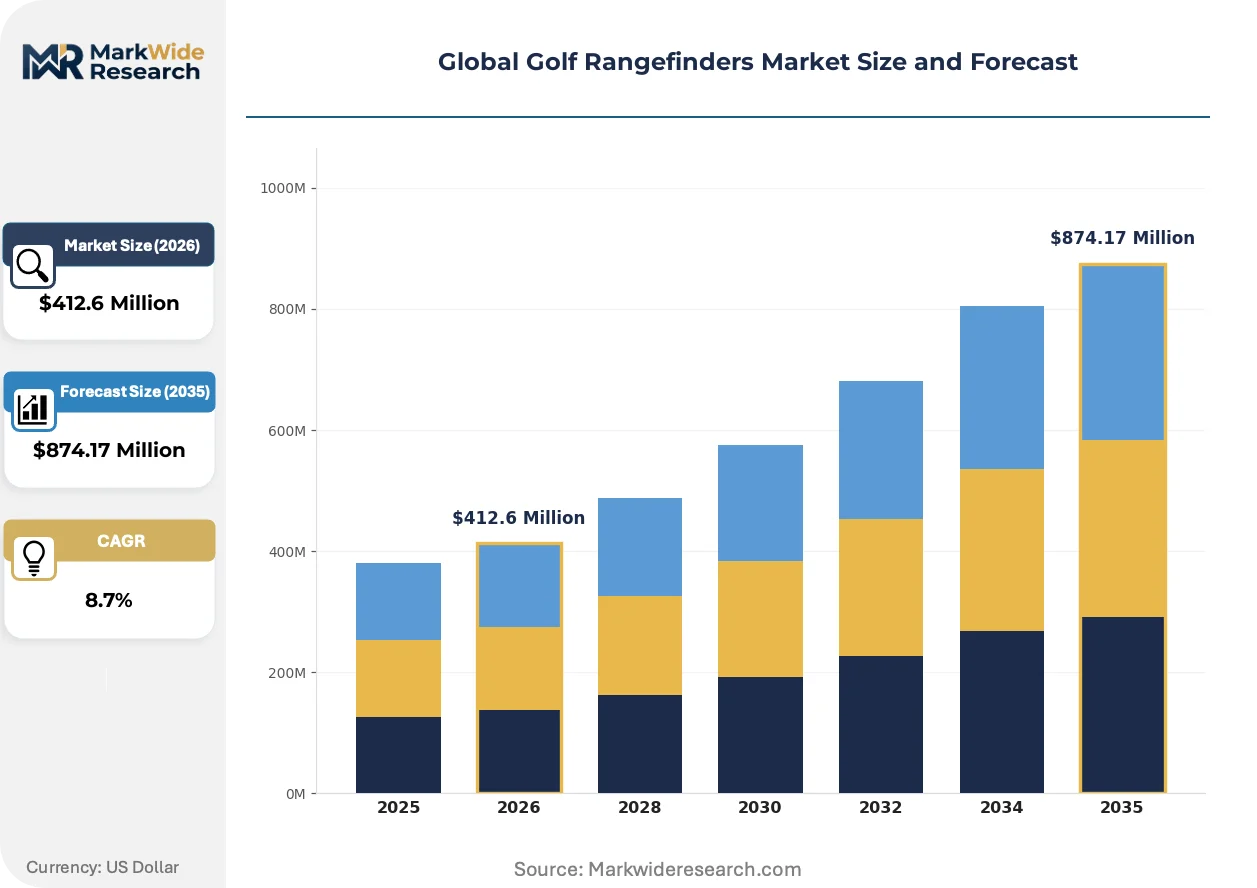
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Rangefinders, GPS Rangefinders, Optical Rangefinders, Hybrid Rangefinders Technology: Bluetooth, Smartphone-Compatible, LCD Display, Enhanced GPS End User: Avid Golfers, Professional Players, Casual Players, Golf Coaches Distribution Channel: Online Stores, Specialty Golf Shops, Sporting Goods Retailers, Direct Sales |
| Companies Covered | Bushnell Golf, Nikon Corporation, Garmin Ltd., Topgolf Callaway Brands, Leupold & Stevens, SkyHawke Technologies, Precision Pro Golf, Laser Link Golf, Voice Caddie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Golf Rangefinders Market Emerging Trajectories
Three interconnected developments are compressing product lifecycles and redrawing competitive boundaries across the rangefinder landscape: optical-sensor miniaturization, regulatory harmonization pressures, and shifting purchase channels.
Multilayer dielectric coating technology applied to laser receiver lenses is rendering obsolete earlier-generation devices that struggle with flagstick detection against cluttered backgrounds. Tournament players and low-handicap amateurs are upgrading to coated-optic models at accelerated replacement cycles. This optical advancement is compressing the viable sales window for uncoated legacy inventory.
Japan's METI electrical appliance safety standards are tightening documentation requirements for GPS-integrated rangefinders sold domestically. Manufacturers must now submit expanded electromagnetic compatibility testing data before market authorization. GPS-hybrid product lines face the longest approval timelines, forcing staggered launch sequences between Japanese and North American markets.
Pro shop direct purchasing is losing ground to online equipment retailers and manufacturer-direct storefronts among replacement buyers. Big-box sporting goods chains and specialized golf e-commerce platforms now capture the majority of non-gift transactions. South Korea and the United States exhibit the most pronounced channel migration, with younger players rarely visiting physical retail before purchase decision.
Global Golf Rangefinders Market Segmentation
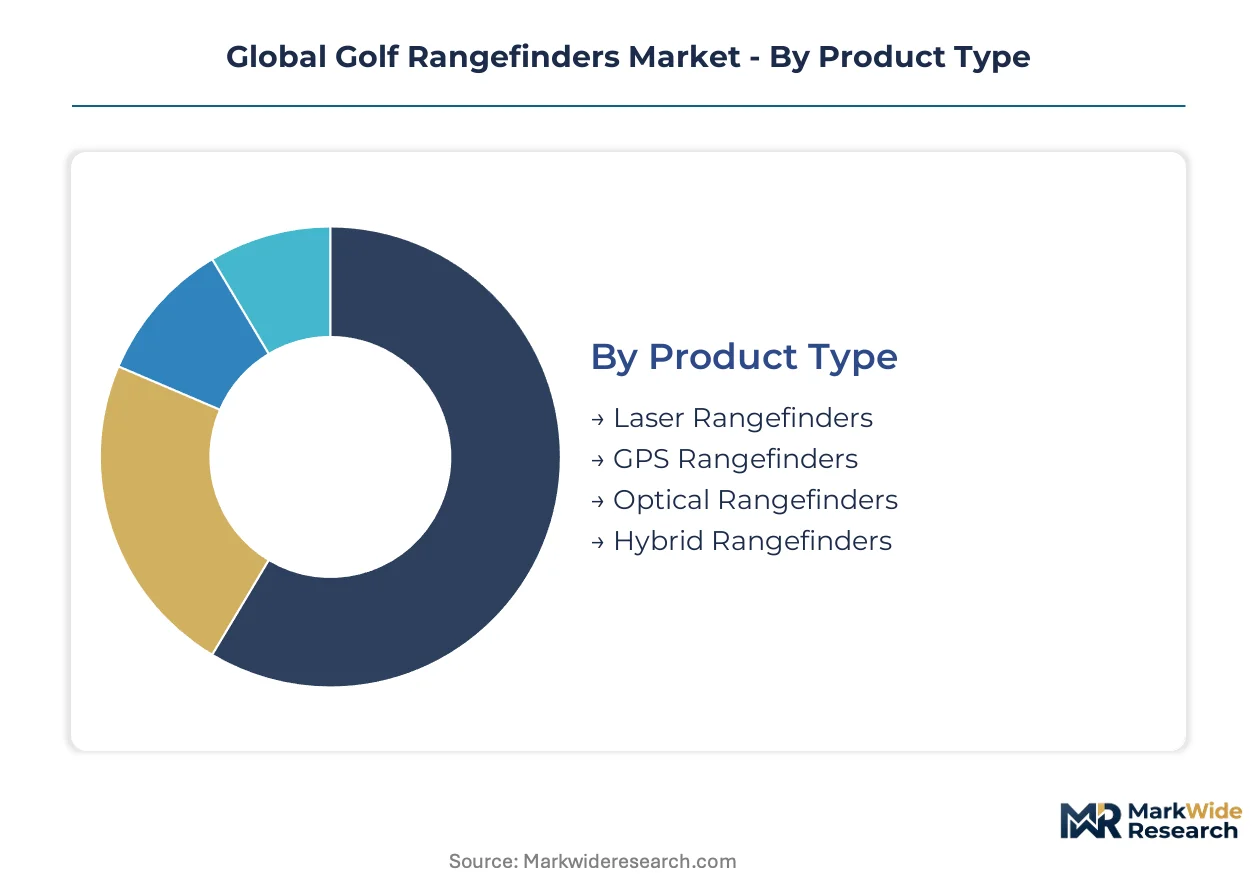
Segmentation in golf rangefinders reveals how technology adoption curves diverge across player commitment levels and purchase contexts. Understanding these splits helps manufacturers align R&D investment with replacement cycles that range from annual upgrades among professionals to decade-long holds among casual players.
Product Type:
Laser units turn over fastest among tournament competitors seeking marginal accuracy gains, while optical models persist longest in occasional-use households.
- Laser Rangefinders:Pulsed time-of-flight measurement systems deliver sub-yard precision at six hundred yards, dominating tree-lined courses where GPS signals attenuate. Demand concentrates in the United States and Japan, where club championships and amateur tournaments normalize annual equipment refreshes.
- Hybrid Rangefinders:Dual-mode instruments fuse laser pinpointing with satellite hazard mapping, commanding premium positioning as players seek single-device course management. South Korea's corporate-sponsored tournament circuit drives steepest adoption, with country club members upgrading at compressed cycles to access integrated features.
- GPS Rangefinders:Satellite-triangulation devices provide pre-mapped hazard distances without line-of-sight requirements, appealing to walkers and players on open links layouts.
- Optical Rangefinders:Reticle-based mechanical ranging through calibrated lenses persists among purists and budget-conscious beginners, though volume share erodes annually.
Laser rangefinders anchor the volume base while hybrid rangefinders gain share at the steepest rate.
Technology:
Cost tiers separate entry-level LCD units from subscription-linked Bluetooth ecosystems that monetize beyond hardware.
- Bluetooth:Wireless protocol integration enables real-time shot logging and statistical synchronization with native smartphone applications. Avid golfers in the United States drive replacement demand, treating connected analytics as essential to handicap improvement.
- Smartphone-Compatible:Devices engineered for seamless app pairing capture younger demographics who prioritize data portability over standalone operation. South Korean amateur tournaments normalize such connectivity, pressuring laggards to upgrade.
- LCD Display:Monochrome and color liquid-crystal readouts remain standard across mid-tier price bands, with readability in direct sunlight determining competitive positioning.
- Enhanced GPS:Multi-constellation satellite reception and differential correction algorithms improve accuracy in urban canyon environments and dense tree cover.
LCD displays anchor the volume base while Bluetooth-enabled units climb the fastest.
End User:
Application intensity varies dramatically, with professionals treating rangefinders as perishable competition tools and casual players viewing them as durable accessories.
- Avid Golfers:Handicap-focused players maintaining sub-ten indexes drive premium segment demand, replacing devices every two to three seasons to access improved optics and tournament-legal slope switching. Japan's dense course infrastructure sustains concentrated replacement waves among this cohort.
- Professional Players:Tournament competitors require USGA-conforming devices with hardware-disabled slope compensation, creating specialized procurement relationships with manufacturers seeking equipment validation. South Korea's KPGA Tour and Japan's JGTO circuit normalize such relationships.
- Casual Players:Infrequent golfers prioritize price accessibility over specification sophistication, extending replacement cycles beyond five years and gravitating toward gift-purchase occasions.
- Golf Coaches:Instructors utilize rangefinders for distance verification during lessons, with institutional procurement through academies and country clubs driving volume in training-centric markets.
Avid golfers anchor the volume base while professional players command the steepest technology adoption trajectory.
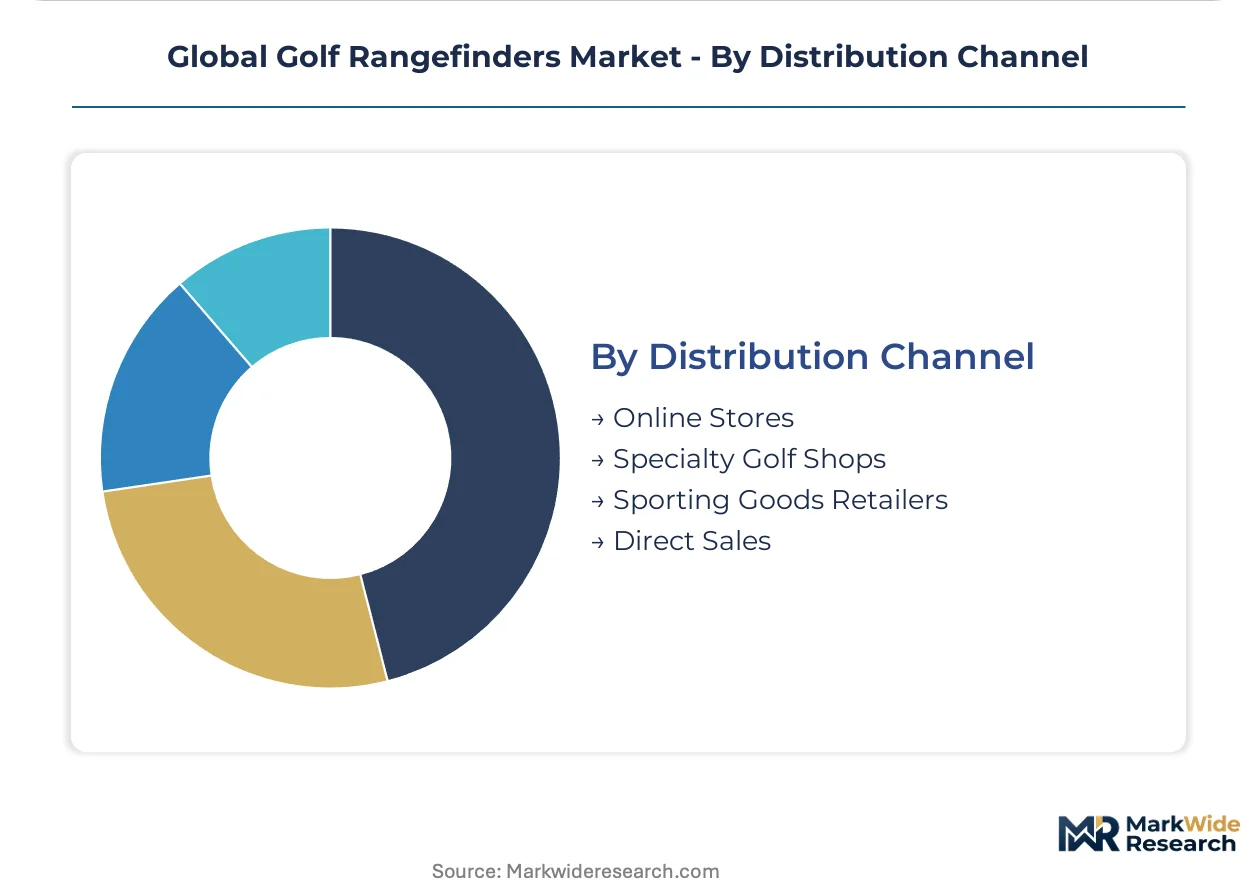
Distribution Channel:
Channel migration toward digital fulfillment is compressing specialty retail margins while expanding manufacturer-direct relationships.
- Online Stores:E-commerce platforms capture majority share among replacement buyers under forty, with detailed specification comparison and user-generated review content reducing purchase friction. South Korea and the United States exhibit the most pronounced channel shift.
- Specialty Golf Shops:Pro shop and dedicated retailer networks retain gift-purchase dominance and high-touch fitting services, though foot traffic declines accelerate post-pandemic.
- Sporting Goods Retailers:Big-box chains including Dick's Sporting Goods and Golf Galaxy sustain brand visibility through seasonal promotional cycles and impulse placement near checkout.
- Direct Sales:Manufacturer-owned storefronts and subscription-model hardware deployments capture lifetime value through attached service revenue, particularly for Bluetooth-integrated product lines.
Specialty golf shops anchor the volume base while online stores expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution for finished rangefinder units bound from Asian assembly plants to North American retail channels, while Japan's Port of Yokohama handles precision optical component imports that feed domestic manufacturing clusters.
United States
Amateur tournament participation and pro shop density in Florida, Arizona, and California sustain replacement demand for slope-adjusted devices. The FCC regulates laser emission under 21 CFR 1040, capping pulse power and constraining effective range specifications. Dallas-Fort Worth hosts fulfillment infrastructure for big-box sporting goods distribution networks.
Japan
Concentrated golf course infrastructure across Honshu island drives premium device turnover among club members. METI electrical appliance safety certification mandates expanded electromagnetic compatibility documentation for GPS-hybrid units, extending approval timelines. Osaka-Kobe manufacturing corridors concentrate precision lens grinding and laser diode assembly operations.
South Korea
Corporate-sponsored amateur tournaments and country club membership expansion in Seoul Capital Area and Busan-Ulsan corridor create demand for tournament-legal measurement devices. The MFDS oversees electrical safety standards for GPS-integrated consumer electronics. Gyeonggi Province hosts assembly partnerships linking domestic brands with Chinese optical component suppliers.
China
Domestic suppliers in Shenzhen and Dongguan scale multilayer dielectric coating capacity and laser diode foundry output to serve foreign assembly partners. SAMR product quality supervision applies to consumer electronics exports, with GB standards governing laser safety classifications. Yangtze River Delta clusters concentrate optical component manufacturing for re-export to Japanese and North American brands.
Germany
Precision optics heritage in Baden-Württemberg and Bavaria supports engineering consulting for rangefinder calibration and lens alignment systems. CE marking requirements under EU machinery directives govern laser device market access. Stuttgart industrial corridor hosts metrology equipment suppliers serving rangefinder quality control workflows.
Global Golf Rangefinders Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical subassemblies and laser modules. The vendor base stratifies across three tiers: heritage optics houses with tournament validation relationships, consumer electronics platforms integrating rangefinders into wearable ecosystems, and specialist brands focused exclusively on golf measurement. Competitive moves concentrate on sensor miniaturization R&D partnerships and direct-to-consumer channel buildouts that bypass traditional pro shop networks.
Within the heritage optics tier, Bushnell Golf and Nikon Corporation occupy positions anchored by retail presence and precision manufacturing lineage respectively. Garmin Ltd. represents the platform-integrator archetype, embedding rangefinder functionality within broader location-aware device ecosystems. These three entities exemplify divergent strategic postures: optical specialization, retail scale, and ecosystem convergence.
| Leading Market Players |
|---|
| Bushnell Golf |
| Nikon Corporation |
| Garmin Ltd. |
| Topgolf Callaway Brands |
| Leupold & Stevens |
| SkyHawke Technologies |
| Precision Pro Golf |
| Laser Link Golf |
| Voice Caddie |
| Others |
Supply Flow & Price Mechanics
The Port of Los Angeles freight corridor absorbs trans-Pacific shipping cost volatility that compresses margins for finished rangefinder units, while Shenzhen optical component clusters concentrate supply power among lens and laser diode suppliers who tier pricing by volume commitment and certification grade.
Pricing Analysis
Volume-discount tiering structures separate premium hybrid units with METI certification and tournament validation from standard laser devices and economy optical models. Price differentiation rests on FCC emission compliance grade and Bluetooth ecosystem integration depth. Pricing pressure stems from smartphone GPS substitution eroding entry-tier demand. Casual gift purchasers exhibit highest price sensitivity; avid tournament players show lowest sensitivity to specification premiums.
Supply Chain Analysis
Contract-manufacturing concentration centers on Shenzhen and Dongguan EMS providers assembling precision optical subsystems for Japanese and North American brands. Supply draws from Chinese laser diode foundries, Japanese multilayer coating specialists, and Taiwanese GPS module fabricators. Single-source vulnerability concentrates in pulsed laser emitter supply. Distribution runs through Los Angeles and Yokohama port complexes into big-box retail and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as GPS-laser hybrid penetration accelerates among amateur tournament participants seeking single-device course management solutions.
For Market Incumbents: Entrench tournament validation relationships with USGA and R&A to maintain slope-mode switching as a compliance barrier. Deepen backward integration into optical coating capacity to defend margin position against Chinese component cost compression. Control pro shop channel shelf space before direct-to-consumer migration accelerates.
For New Entrants and Emerging Players: South Korea's corporate-sponsored amateur circuit offers underpenetrated white space for tournament-legal devices without heritage brand baggage. Target Bluetooth-enabled shot tracking as the most penetrable feature tier among younger handicap-focused players. Pursue subscription-model hardware deployments to monetize beyond unit economics.
For Investors and Strategic Acquirers: Specialist rangefinder brands with validated METI certification pipelines and compressed Japanese approval timelines present acquisition target archetypes with defensive moats. Long-term viability hinges on ecosystem integration rather than standalone hardware margins. Monitor FCC emission limit enforcement intensity as inflection signal for product redesign cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Tournament Validation Partnership | USGA equipment conformance relationships lock in slope-mode switching as competitive barrier. |
| Optical Component Backward Integration | In-house multilayer dielectric coating capacity defends margins against Shenzhen supplier pricing power. |
| Bluetooth Ecosystem Integration | Shot tracking synchronization with Garmin and Apple Health platforms monetizes subscription revenue streams. |
| Direct-to-Consumer Channel Buildout | Manufacturer storefronts bypass declining pro shop foot traffic in South Korea and United States markets. |
| METI Certification Pipeline Investment | Accelerated Japanese electrical safety approval timelines create staggered launch advantages over competitors. |
Methodological Framework
Desk research of FCC laser emission filings, METI electrical safety databases, and USGA equipment conformance rulings preceded structured interviews with product managers at heritage optics houses, procurement directors at big-box sporting goods chains, and tournament equipment officials at amateur golf associations. Secondary validation drew from customs trade records, SEC 10-K optical segment disclosures, and golf retail audit data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type and technology segments.
Assumptions held USGA and R&A equipment rules stable while varying Bluetooth adoption curves and hybrid device penetration rates across the analysis window. Segmentation modeling incorporated product type, technology tier, end-user commitment level, and distribution channel migration patterns. CAGRs derived from fitted adoption curves calibrated to replacement cycle data and tournament participation growth. Industry-specific inputs included laser diode foundry capacity utilization and METI approval timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem convergence moves by platform-integrators or sudden FCC emission limit tightening would shift outcomes materially. Quarterly review of amateur tournament rule changes, optical component customs volumes, and direct-to-consumer channel share is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tennis Racquet Market
Sports Equipment
Ice Cleat Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Hydration Belt Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Golf Club Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Football Equipment Market
Sports Equipment
Tetherball Market
Sports Equipment
Trampoline Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
PE Sports Turf Market