
 Tetherball Market | 2026-2036
Tetherball Market Size, Share, and Industry Trends Forecast 2026-2036
Tetherball Market Analytics
Rotomolded polymer construction is reconfiguring how tetherball equipment manufacturers achieve weather resistance and structural longevity at scale. Franklin Sports leverages vertical integration across its sporting goods portfolio to control raw material costs and distribution reach. Baden Sports anchors its competitive stance through specialized rubber compounding expertise that extends product lifespan in high-traffic institutional settings. Park & Sun Sports differentiates via modular pole systems that simplify installation for parks departments with limited maintenance crews.
Tetherball refers to a pole-mounted recreational apparatus comprising a stationary vertical post, attached rope or cord, and inflated ball, typically constructed from rubber or synthetic leather with an internal butyl bladder, designed for two-player striking games in outdoor environments. The equipment serves primary commercial purposes across school playgrounds, municipal parks, and residential backyards where durable, low-maintenance activity infrastructure is prioritized. Residential tetherballs currently occupy the largest volume share as backyard recreation investment persists, while commercial tetherballs command stronger margin pools due to institutional procurement specifications for impact-resistant poles and tamper-proof hardware. Material segmentation shows rubber dominating professional and school-grade installations for grip and rebound consistency, whereas PVC variants gain traction in budget-conscious consumer channels through lighter weight and corrosion immunity.
ASTM International F1487 standards govern playground equipment impact attenuation and entrapment hazards, directly shaping tetherball pole padding requirements and ball tether length specifications in the United States. The Consumer Product Safety Commission monitors injury reporting databases to inform recall protocols and design guidance for outdoor recreational fixtures. ISO 8124 toy safety standards apply to residential-grade tetherball sets sold through international retail channels, creating compliance layering for manufacturers with cross-border distribution. Stakeholders must monitor evolving municipal procurement criteria that increasingly mandate recycled content thresholds and extended warranty terms as conditions for contract eligibility.
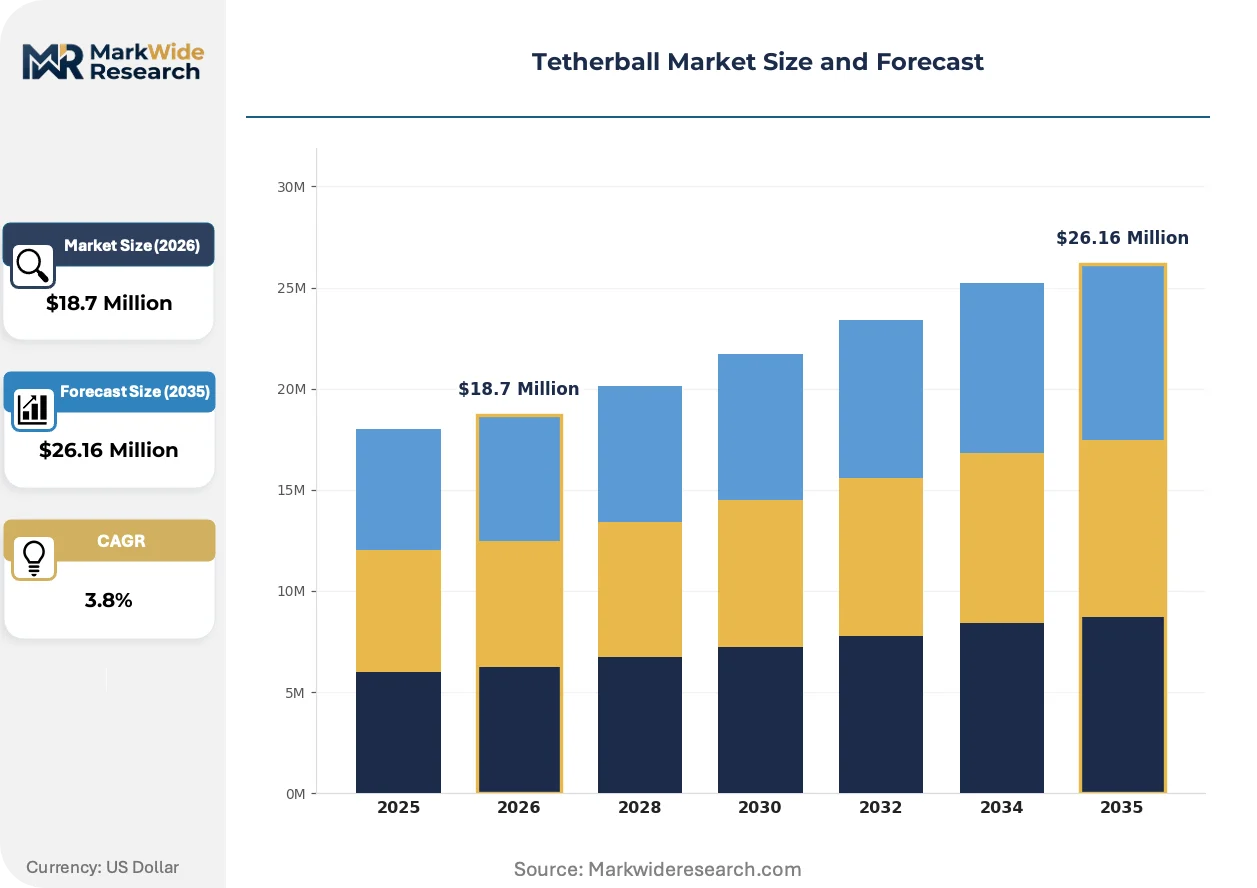
Market Dynamics
ASTM International's tightening F1487 standards for impact attenuation and entrapment hazards are forcing tetherball manufacturers to redesign pole padding systems and tether length specifications, compressing margins for legacy product lines while creating compliance premiums for certified suppliers.
Growth Catalysts
- Municipal procurement programs:North American school districts are expanding durable outdoor equipment budgets under post-pandemic infrastructure renewal initiatives, prioritizing low-maintenance apparatus with extended warranty terms.
- REACH material compliance:European chemical safety standards are accelerating adoption of recycled polymer feedstocks in rotomolded pole construction, opening contract eligibility for sustainable product lines.
- Rotomolded polymer technology:This manufacturing process delivers weather-resistant, seamless construction that outperforms welded steel in coastal and freeze-thaw environments, capturing institutional specification share.
Market Restraints
- Butyl rubber price volatility:Ball bladder material costs fluctuate with petrochemical feedstock markets, squeezing margin stability for manufacturers without captive rubber compounding capabilities.
- Chinese steel supply concentration:Pole and anchor hardware fabrication relies heavily on East Asian metalworking capacity, exposing procurement timelines to shipping bottlenecks and tariff uncertainty.
- ASTM F1487 compliance friction:The standard's evolving entrapment hazard definitions create retesting burdens for existing product lines, delaying inventory refresh cycles.
Strategic Opportunities
- Underpenetrated Canadian park systems:Municipal recreation departments across Ontario and British Columbia are expanding playground modernization budgets with sustainability-weighted scoring criteria.
- Modular installation systems:Quick-anchor pole bases that reduce labor hours for maintenance-constrained parks departments represent an unexploited specification advantage.
- IRA green infrastructure incentives:US federal tax credits for sustainable municipal projects are creating procurement preference for equipment with verified recycled content thresholds.
Industry Challenges
- Certification timeline compression:ASTM and ISO parallel testing requirements for cross-border product lines extend time-to-market by 8-14 months, straining R&D amortization schedules.
- Legacy hardware integration:Parks departments with existing in-ground anchor infrastructure face compatibility constraints when upgrading to new pole diameter standards, complicating retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetherball Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $26.16 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Tetherballs, Commercial Tetherballs, Professional Tetherballs, Custom Tetherballs Material: Rubber, PVC, Nylon, Cotton Use Case: School Playgrounds, Parks, Backyards, Sports Clubs Distribution Channel: Online Retailers, Sporting Goods Stores, Wholesale Distributors, Specialty Shops |
| Companies Covered | Franklin Sports, Baden Sports, Park & Sun Sports, Lifetime Products, Gosports, Sterling Sunnywood Sports, Spalding Sports Worldwide, Wright & Ditson, Regent Sports Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetherball Market Evolving Landscape
Material science advances and procurement digitization are restructuring how tetherball equipment is specified, manufactured, and distributed across institutional channels. Three developments warrant particular attention.
Rotomolded polyethylene pole construction is rendering obsolete traditional welded steel fabrication for high-traffic institutional installations. Parks departments in coastal Florida and Pacific Northwest municipalities are specifying seamless polymer systems exclusively. The technology eliminates corrosion failure modes and reduces lifetime maintenance costs by half.
ASTM International's proposed updates to F1487 entrapment hazard definitions are tightening ball-tether length tolerances and mandating quick-release hardware. Equipment specifiers in Texas and California school districts are pre-emptively requiring compliant designs ahead of formal adoption. Manufacturers with existing certified lines are capturing specification lock-in.
Aggregated municipal procurement platforms are consolidating purchasing authority previously dispersed across individual school districts and parks departments. Cooperative buying organizations in the US Mountain West and Midwest regions are standardizing on pre-qualified vendor lists. Smaller manufacturers without digital catalog integration are losing specification access.
Tetherball Market Segmentation
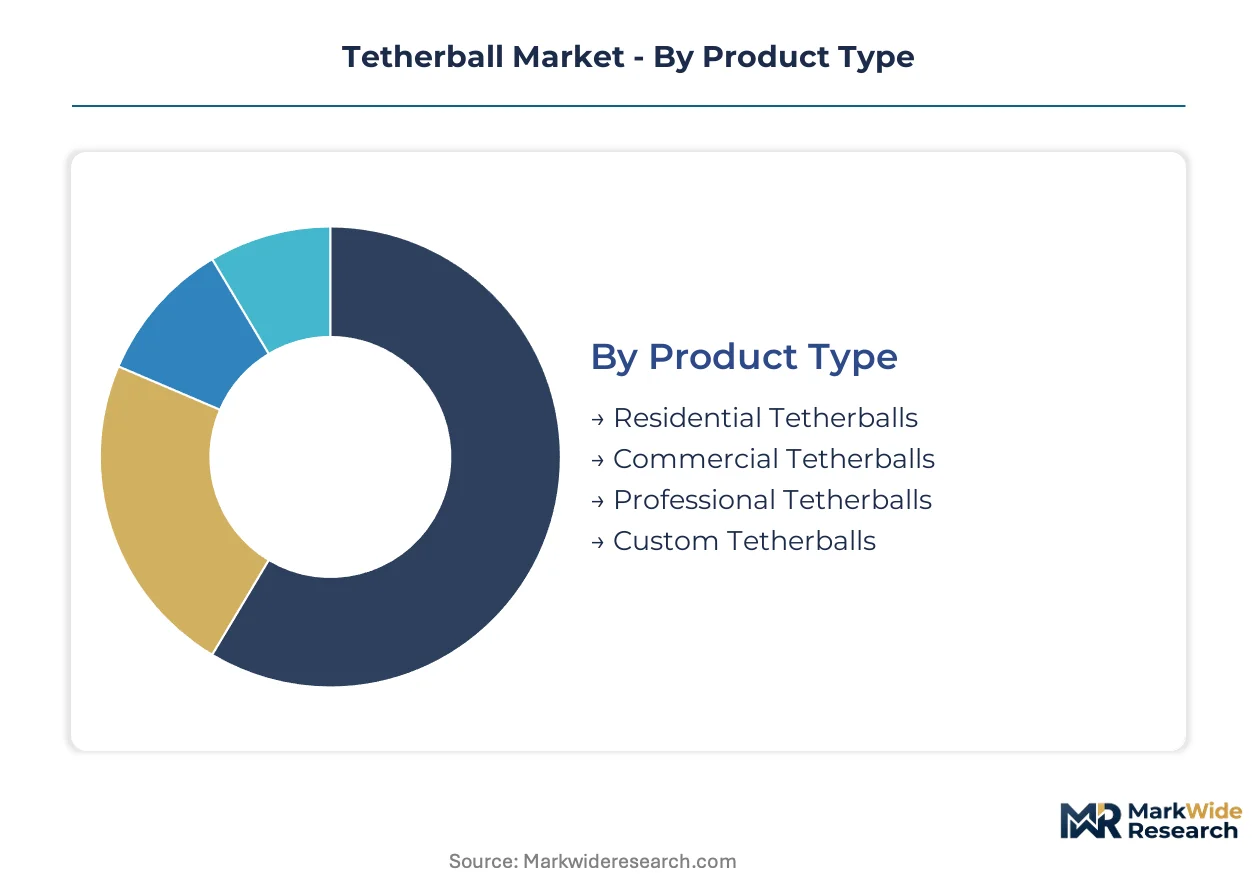
Tetherball equipment segments diverge sharply in replacement cycles, with institutional installations running 8-12 years versus 2-3 year turnover for consumer-grade backyard sets. Understanding these velocity differentials helps manufacturers align inventory planning with procurement calendars across municipal, educational, and residential channels.
Product Type:
Replacement cycles stretch from seasonal consumer refreshes to decade-long institutional capital programs, creating distinct revenue recognition patterns across the four product tiers.
- Commercial Tetherballs:Engineered with rotomolded polyethylene poles, tamper-proof hardware, and reinforced butyl bladders rated for 50,000+ impact cycles. School districts in Texas and Florida specify these exclusively under multi-year procurement contracts that bundle installation with 10-year warranty terms.
- Residential Tetherballs:Lightweight PVC or steel pole systems with standard rubber balls, designed for tool-free assembly and seasonal storage. Suburban households in the US Sun Belt drive volume through spring renovation spending, though margin compression is severe due to big-box retail pricing power.
- Professional Tetherballs:Tournament-grade specifications with calibrated ball rebound, standardized tether length, and anchored steel poles meeting competitive federation standards.
- Custom Tetherballs:Branded or themed configurations for corporate campuses, resorts, and private clubs requiring non-standard colors or logo integration.
Commercial tetherballs dominate installed base value. Residential tetherballs are where volume expansion concentrates.
Material:
Raw material selection locks in performance profiles across climate resilience, grip texture, and cost structure, with procurement specifications increasingly weighting recycled content thresholds.
- Rubber:Natural and synthetic compounds deliver superior grip consistency and weather aging resistance for institutional installations. ASTM F1487 compliance testing favors rubber ball construction for impact attenuation validation, cementing specification preference in US school procurement.
- PVC:Thermoplastic formulations offer corrosion immunity and lighter shipping weights, penetrating budget-conscious consumer channels and coastal municipalities where salt exposure degrades metal components.
- Nylon:High-tenacity synthetic fibers in tether cords provide UV resistance and abrasion durability for high-traffic settings.
- Cotton:Traditional woven covers for recreational-grade balls, limited to low-use residential applications where tactile preference outweighs longevity requirements.
Rubber commands specification authority in institutional channels. PVC is climbing the fastest in municipal procurement due to lifecycle cost advantages.
Use Case:
End-use environments dictate durability specifications, installation complexity, and maintenance burden, with each channel presenting distinct vendor qualification barriers.
- School Playgrounds:Heavy-duty pole systems with impact-absorbing padding, tamper-resistant fasteners, and ball retention hardware designed for unsupervised use. California and Texas districts lead procurement volume under post-pandemic infrastructure renewal allocations.
- Parks:Vandal-resistant designs with concrete-anchored or surface-mounted bases for public spaces with limited maintenance staffing. Municipal procurement platforms in the US Midwest consolidate purchasing authority across multiple park systems.
- Backyards:Portable or semi-permanent installations prioritizing aesthetic integration with residential landscaping and minimal site preparation.
- Sports Clubs:Competition-caliber equipment with standardized dimensions for tournament hosting and athlete training protocols.
School playgrounds anchor specification-driven revenue. Parks represent the steepest expansion trajectory as municipal modernization budgets accelerate.
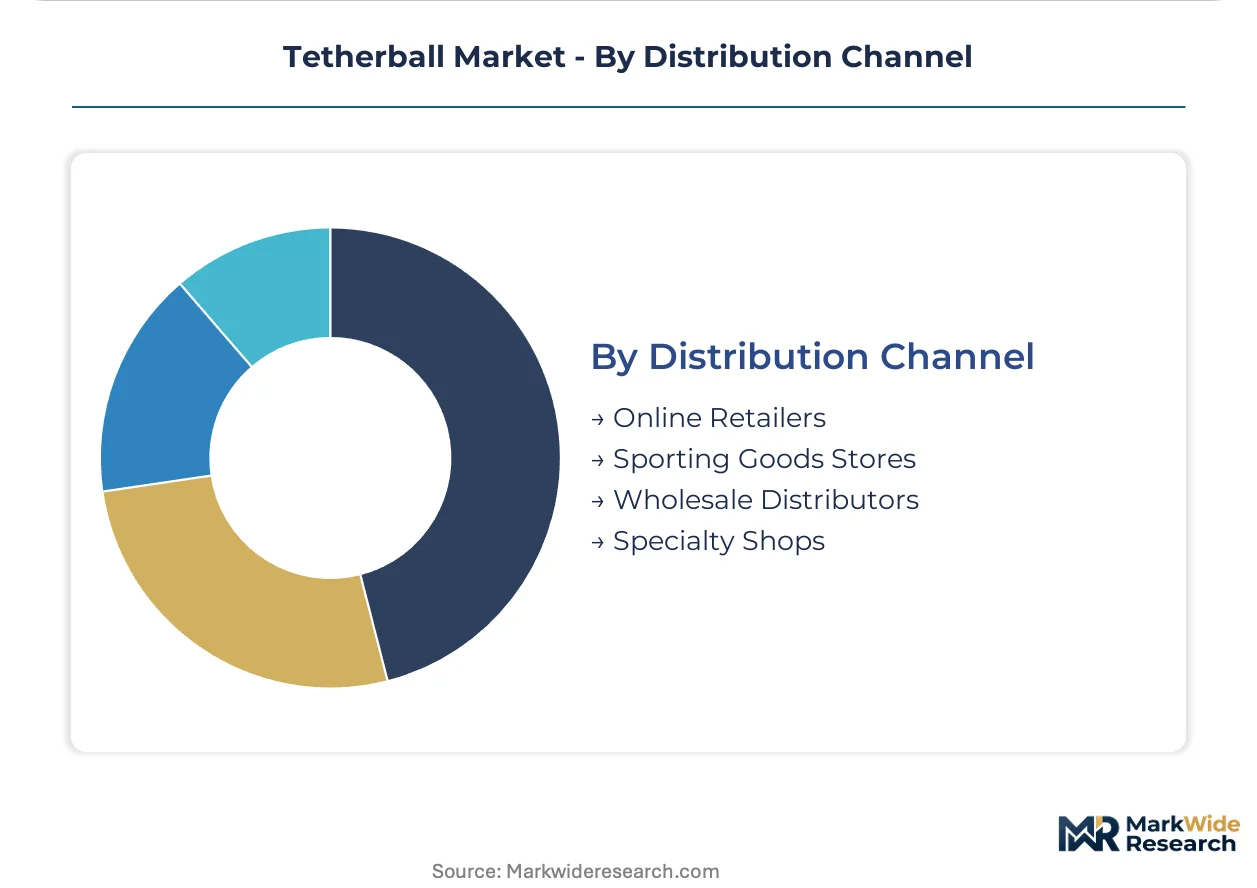
Distribution Channel:
Channel structure determines margin capture, with direct institutional contracts yielding superior economics against retail intermediation that erodes pricing power.
- Wholesale Distributors:Regional warehousing networks serving school districts and parks departments with consolidated logistics, installation coordination, and extended payment terms. Distributors in the US Southeast and Mountain West control access to aggregated municipal procurement platforms.
- Online Retailers:E-commerce platforms capturing residential demand through search-optimized listings and seasonal promotional calendars, though fulfillment costs compress net margins.
- Sporting Goods Stores:Brick-and-mortar retail with seasonal floor space allocation and staff-assisted selection for consumer-grade equipment.
- Specialty Shops:Niche providers focusing on institutional specification expertise and custom fabrication capabilities.
Wholesale distributors dominate institutional contract flow. Online retailers are gaining share fastest in residential replenishment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments and school district facilities managers constitute the dominant buyer archetype, concentrating demand in suburban districts with post-pandemic infrastructure renewal budgets. Their specification requirements for extended warranties and recycled content thresholds are reshaping vendor qualification criteria across North American markets.
United States
Texas and California school districts lead procurement volume under state-level facility modernization allocations. ASTM International F1487 standards govern impact attenuation and entrapment hazard specifications, forcing redesigns of pole padding systems. The Dallas-Fort Worth metroplex anchors institutional specification activity, with parks departments specifying rotomolded polymer systems exclusively for coastal resilience.
Canada
Ontario and British Columbia municipal recreation departments are expanding playground modernization budgets with sustainability-weighted scoring criteria. Health Canada monitors injury reporting databases to inform safety guidance for outdoor recreational fixtures. The Greater Toronto Area concentrates specification-driven demand, with procurement platforms consolidating purchasing authority across multiple park systems.
Germany
Municipal procurement programs prioritize REACH-compliant material specifications for outdoor equipment in high-traffic public spaces. ECHA chemical safety standards accelerate adoption of recycled polymer feedstocks in rotomolded construction. The Ruhr Valley industrial corridor hosts fabrication capacity serving Central European institutional contracts.
United Kingdom
Local authority leisure services departments are standardizing on extended warranty terms as mandatory contract conditions. CE marking requirements apply to playground apparatus sold through retail and institutional channels. The West Midlands concentrates distribution infrastructure serving consolidated municipal buying cooperatives.
Australia
State education departments in New South Wales and Victoria are expanding durable outdoor equipment budgets under school infrastructure renewal initiatives. Standards Australia AS 4685 governs playground equipment safety, creating compliance layering for imported product lines. The Sydney metropolitan area anchors specification activity for coastal-grade corrosion-resistant systems.
Tetherball Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement touchpoints. The vendor base clusters around three strategic archetypes: sporting goods conglomerates with portfolio breadth, dedicated outdoor recreation fabricators with institutional specification expertise, and private-label suppliers serving price-sensitive retail channels. Consolidation pressure is mounting through cooperative buying organization pre-qualification requirements and digital catalog integration mandates.
Within the sporting goods conglomerate tier, Franklin Sports and Spalding Sports Worldwide exemplify portfolio-diversified players leveraging cross-category distribution infrastructure. Park & Sun Sports occupies a position among specialized outdoor recreation fabricators focused on modular installation systems. These archetypes represent contrasting strategic bets on specification depth versus channel breadth.
| Leading Market Players |
|---|
| Franklin Sports |
| Baden Sports |
| Park & Sun Sports |
| Lifetime Products |
| Gosports |
| Sterling Sunnywood Sports |
| Spalding Sports Worldwide |
| Wright & Ditson |
| Regent Sports Corporation |
| Others |
Value Network & Pricing Analysis
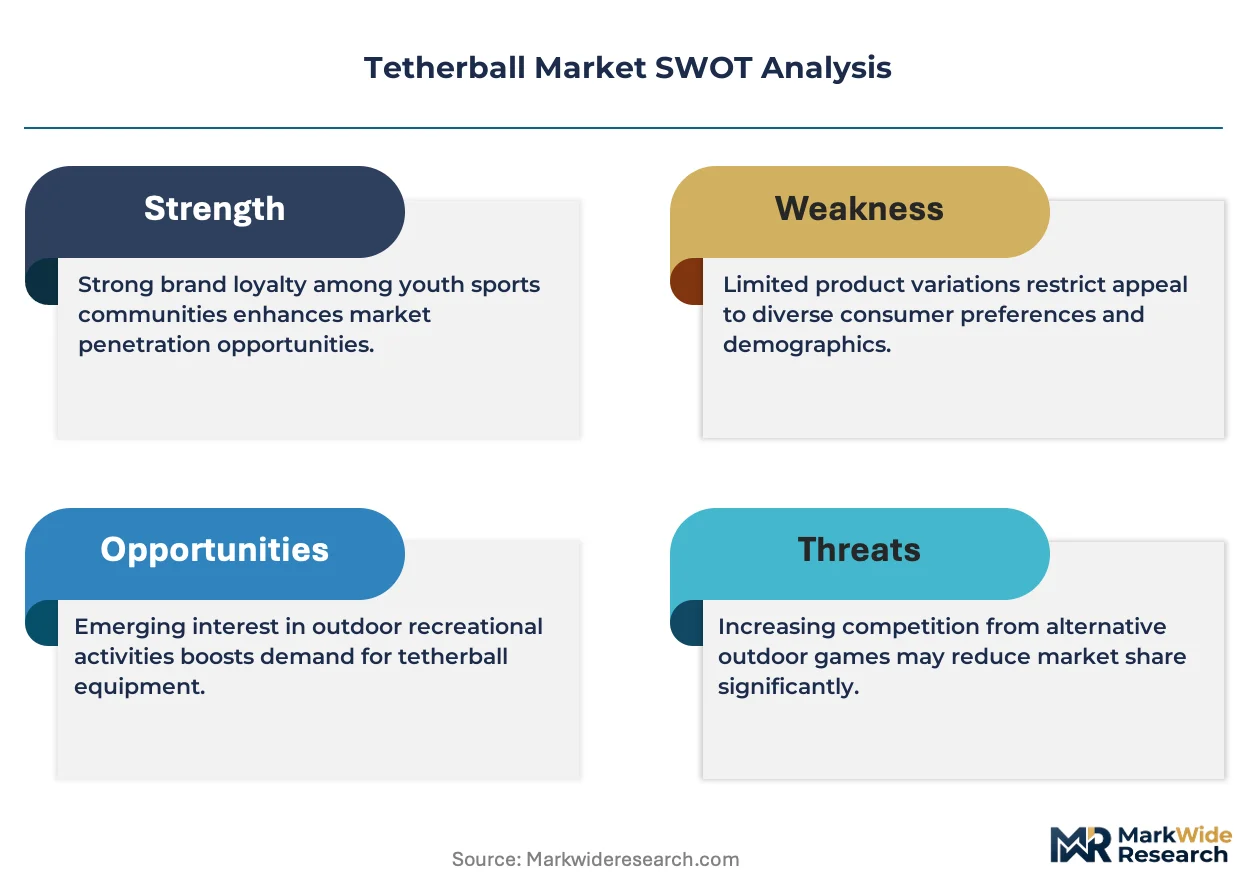
Chinese steel supply concentration determines both pricing tier spreads and supply chain shape in tetherball equipment manufacturing, compressing margins on metal-dependent standard-grade products while forcing premium suppliers toward polymer substitution strategies. Tariff exposure on East Asian metalworking capacity feeds directly into municipal procurement scoring, where extended warranty terms and recycled content thresholds now outweigh unit price in contract eligibility.
Pricing Analysis
Cost-plus contracts with butyl rubber indexation dominate institutional procurement, linking final equipment pricing to petrochemical feedstock volatility. Price differentiation separates ASTM F1487-certified commercial installations from uncertified residential sets, with certification tier and volume scale driving tiered spreads. Pricing pressure intensifies in the residential channel due to big-box retail consolidation, while school districts exhibit lowest price sensitivity as total cost of ownership calculations favor durability premiums.
Supply Chain Analysis
Export-control friction on advanced polymer compounding equipment limits rotomolded pole technology transfer to Chinese fabricators, constraining capacity expansion in the dominant manufacturing region. Raw material flows draw from Saudi butyl rubber feedstocks, Taiwanese steel processing, and domestic polyethylene resin production. Single-source vulnerability concentrates in East Asian metalworking for pole and anchor hardware. Distribution runs through regional wholesale distributors serving consolidated municipal procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rotomolding expertise and ASTM certification infrastructure represent scarce capabilities that constrain competitive entry, with incumbent manufacturers holding irreplaceable institutional specification relationships built through decade-long warranty performance records.
For Market Incumbents: Harden specification lock-in through captive polymer compounding investments that insulate margin structures from butyl rubber volatility. Deepen ASTM F1487 pre-certification of next-generation entrapment-compliant designs ahead of formal standard adoption. Prioritize digital catalog integration with cooperative buying organizations to defend channel access against emerging competitors lacking platform connectivity. For New Entrants and Emerging Players: Canadian municipal recreation departments in Ontario and British Columbia present underpenetrated procurement volume with sustainability-weighted scoring criteria that favor recycled polymer offerings. Target quick-anchor modular installation systems as specification wedge against maintenance-constrained parks departments. Pursue direct sales relationships with aggregated municipal procurement platforms rather than distributor intermediation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized fabricators with institutional specification expertise over portfolio-diversified sporting goods conglomerates. Acquisition targets should demonstrate proven rotomolded polymer production capabilities and existing ASTM certification infrastructure. Watch for IRA green infrastructure incentive rulemaking as signal for sustainable product line premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Rotomolded Polymer Capacity Expansion | Captures specification share from corrosion-vulnerable steel installations in coastal Florida and Pacific Northwest municipalities. |
| ASTM F1487 Pre-Certification Investment | Locks in school district procurement ahead of entrapment hazard definition updates in Texas and California. |
| Recycled Content Threshold Compliance | Qualifies for IRA green infrastructure tax credits and REACH-compliant European municipal contracts. |
| Cooperative Buying Organization Integration | Secures access to consolidated procurement platforms in US Mountain West and Midwest regions. |
| Quick-Anchor Modular System Development | Reduces installation labor hours for maintenance-constrained parks departments in Ontario and British Columbia. |
Research Methodology
A standing panel of municipal parks directors, school district facilities managers, rotomolded polymer engineers, and wholesale distribution executives provided ongoing calibration across primary fieldwork. Secondary validation drew from ASTM International standard revision dockets, Consumer Product Safety Commission injury reporting databases, municipal procurement platform contract awards, and SEC filings of sporting goods conglomerates. Bottom-up equipment shipment data triangulated against top-down infrastructure budget allocations across North American school districts.
Scenario-bracketing around butyl rubber price volatility, tariff regime uncertainty, and ASTM F1487 adoption timelines shaped projection outputs across the analysis window. Segmentation modeling captured product type tiers, material grade specifications, use case environments, and distribution channel structures. CAGRs derived from replacement cycle velocity differentials between institutional capital programs and residential seasonal refreshes, with municipal procurement calendar phasing and polymer technology substitution curves as key inputs.
Practitioners should monitor ASTM F1487 revision adoption schedules, IRA green infrastructure incentive rulemaking, and cooperative buying organization vendor pre-qualification criteria for early signals of forecast deviation. Material shifts in Chinese steel tariff exposure or REACH recycled content threshold enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
France Artificial Turf Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Surfboard Market
Sports Equipment
Trampoline Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Power Sports Aftermarket Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Ladderball Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Rubber Fitness Flooring Market