
 Renewable Solvent Market | 2026-2036
Renewable Solvent Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Solvent Market Intelligence
A shift from single-source petrochemical supply toward multi-source biorefinery partnerships is realigning procurement strategies across the value chain. BASF SE leverages its integrated biotechnology platforms to secure feedstock flexibility across European operations. Cargill Incorporated anchors North American ethanol supply through corn-processing infrastructure that competitors struggle to replicate. Neste competes on renewable hydrocarbon technology leadership, extending its Singapore refinery footprint into solvent-grade output.
Renewable solvents comprise biologically derived liquids—primarily C2-C6 alcohols, esters, and terpenes with flash points between 12°C and 60°C—engineered to dissolve, disperse, or extract materials without fossil-carbon content. Their industrial purpose centers on replacing petroleum-derived solvents in volatile organic compound-sensitive processes where thermal stability and polarity matching remain critical. Bio-based solvents and ethanol dominate current volume given established fermentation infrastructure and compatibility with existing coating equipment. Glycerol occupies a narrower but higher-margin position in pharmaceutical and cosmetics applications where USP-grade purity commands premium positioning. Acetone trails in adoption due to supply constraints in biogenic acetone production pathways.
EPA volatile organic compound rules, REACH authorization requirements, and China's MEE emission standards collectively restrict conventional solvent use in manufacturing facilities across three continents. FDA guidance on residual solvent limits in pharmaceutical excipients further steers formulators toward ethanol and glycerol grades that meet ICH Q3C safety thresholds. Stakeholders must monitor biorefinery capacity announcements against regional regulatory enforcement timelines to avoid feedstock-commitment mismatches.
Market Dynamics
REACH authorization requirements and China's MEE emission standards are compressing petrochemical solvent availability, forcing coatings and pharmaceutical manufacturers to requalify supply chains around bio-based alternatives with equivalent thermal stability profiles.
Growth Catalysts
- REACH Authorization:ECHA's sunset date enforcement for toluene and xylene derivatives is compelling German automotive coaters to switch to bio-based esters.
- Pharmaceutical Processing:FDA residual solvent limits under ICH Q3C are steering excipient formulators toward USP-grade ethanol and glycerol grades.
- Fermentation Infrastructure:Corn-processing biorefineries in the US Midwest are expanding ethanol capacity dedicated to solvent-grade output.
Market Restraints
- Feedstock Price Volatility:Corn and sugarcane commodity swings directly compress biorefinery margins and solvent pricing predictability.
- Biogenic Acetone Supply:Limited fermentation pathways for acetone production constrain availability of this ketone solvent for coatings applications.
- Polarity Matching Limitations:Terpene solvents exhibit inferior solvency for certain high-molecular-weight resins versus aromatic hydrocarbons.
Strategic Opportunities
- Brazilian Sugarcane Biorefineries:ANVISA regulatory alignment with FDA standards creates export-ready ethanol supply for North American pharmaceutical buyers.
- Supercritical CO2 Convergence:Integration of bio-solvent extraction with supercritical fluid processing is opening pharmaceutical API purification applications.
- Direct Procurement Contracts:Coatings manufacturers are bypassing distributors to contract directly with biorefinery operators for volume certainty.
Industry Challenges
- Bioprocess Engineering Talent:Scarcity of fermentation-scale-up specialists is delaying biorefinery commissioning timelines.
- Equipment Requalification:Pharmaceutical manufacturers face 18-24 month validation cycles to switch solvent grades in cGMP facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Solvent Market |
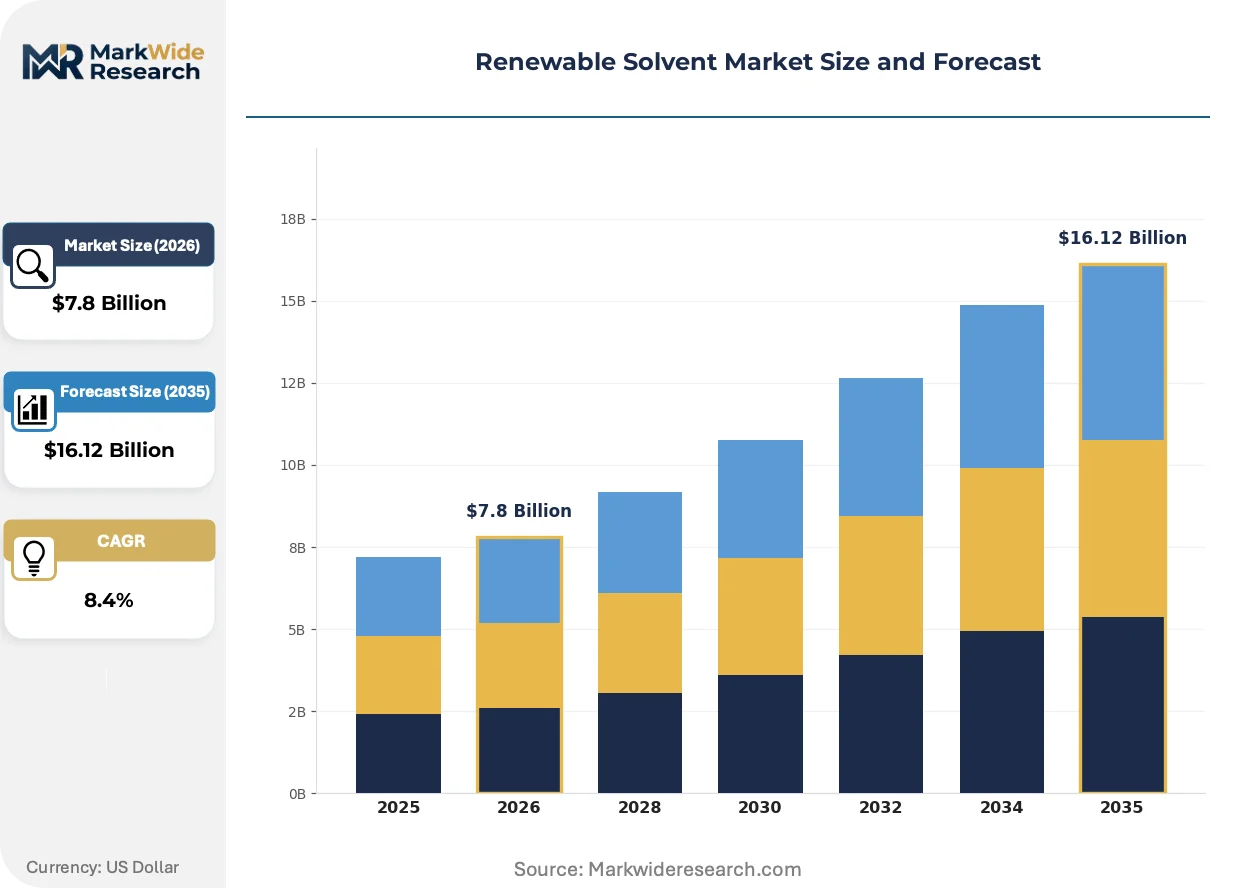
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Solvents, Ethanol, Acetone, Glycerol Application: Coatings, Adhesives, Cleaning Agents, Paint Thinners End Use Industry: Automotive, Pharmaceuticals, Cosmetics, Food Processing Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Archer Daniels Midland Company, Vertec BioSolvents, Neste, Cremer Oleo GmbH & Co. KG, InKemia Green Chemicals, Inc., BASF SE, Cargill Incorporated, LyondellBasell Industries Holdings B.V., Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Solvent Market Strategic Shifts & Innovations
Process intensification and feedstock diversification are compressing production economics for bio-based solvents while regulatory harmonization accelerates cross-border qualification protocols.
Second-generation lignocellulosic ethanol is overtaking first-generation corn ethanol in industrial solvent applications. Brazilian biorefineries are deploying enzymatic hydrolysis platforms to convert sugarcane bagasse into C5-C6 alcohol streams. Coatings formulators in São Paulo industrial corridors are qualifying these cellulosic grades for high-solids coating systems, overtaking petroleum-derived butanol in viscosity-reduction applications.
China's dual carbon goals and MEE emission standards are tightening VOC limits in manufacturing facilities across Jiangsu and Zhejiang provinces. Provincial environmental bureaus are enforcing phased reductions in aromatic solvent use for automotive refinishing operations. Domestic coatings producers are responding by retrofitting spray booths and reformulating with bio-based esters to maintain operating licenses.
Pharmaceutical buyers are consolidating solvent procurement through qualified supplier programs rather than spot-market purchasing. Large-scale API manufacturers in India and Germany are awarding multi-year contracts to biorefineries with dedicated pharmaceutical-grade production lines. This concentration is most pronounced in Hyderabad's pharmaceutical cluster, where CDMOs are requiring solvent suppliers to maintain redundant manufacturing sites for supply security.
Renewable Solvent Market Segmentation
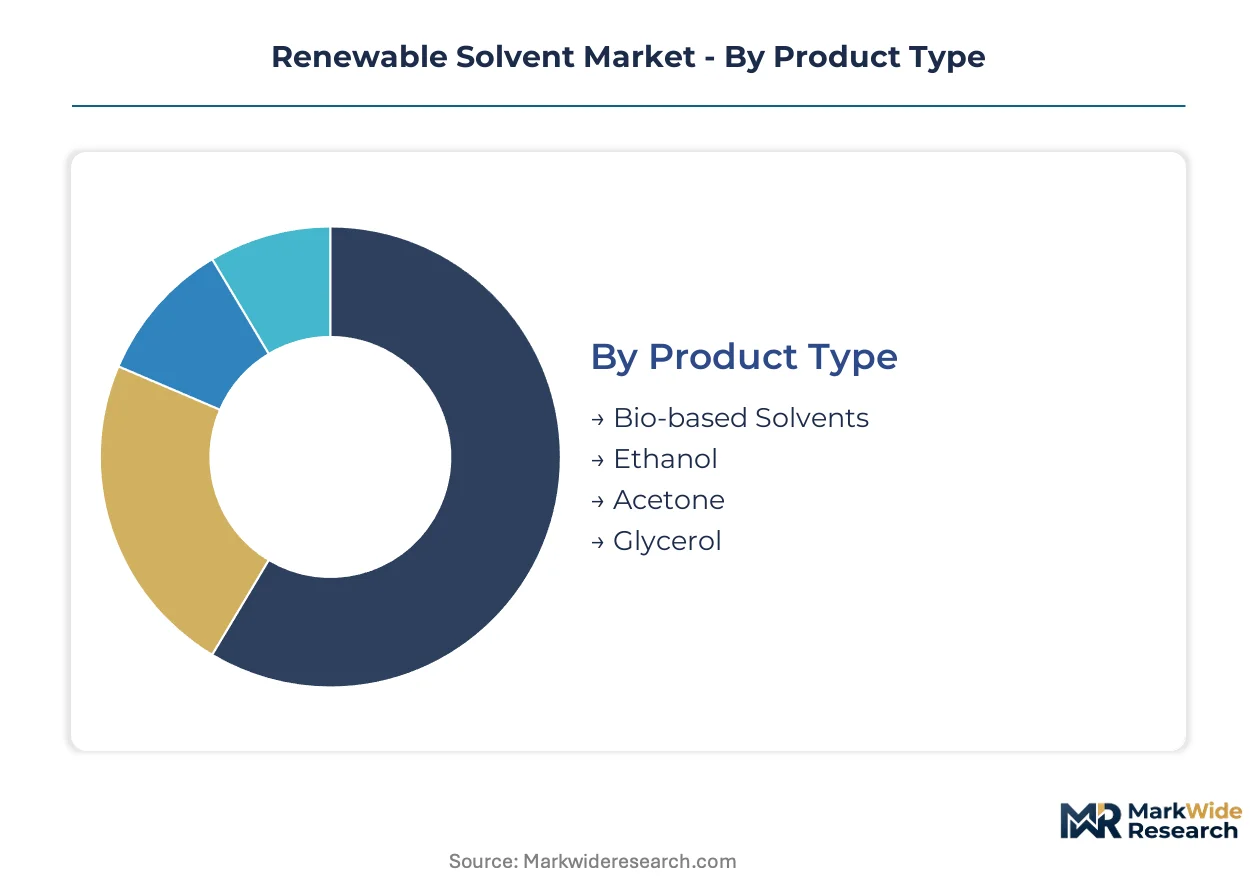
Renewable solvent procurement strategies diverge sharply across product chemistries and end-use specifications. Manufacturers must align feedstock sourcing with application-specific purity requirements and regional regulatory thresholds.
Product Type:
Technical specifications around flash point, polarity, and biogenic carbon content define competitive positioning across solvent categories.
- Bio-based Solvents:C2-C6 alcohols, esters, and terpenes engineered for VOC-sensitive industrial processes. German automotive coaters are requalifying supply chains around bio-based esters as ECHA enforces REACH sunset dates for aromatic hydrocarbons.
- Ethanol:Fermentation-derived C2 alcohol with established infrastructure across corn-processing biorefineries. US Midwest capacity expansions are dedicating solvent-grade output to pharmaceutical excipient manufacturers facing FDA residual solvent limits under ICH Q3C.
- Acetone:Biogenic ketone with constrained fermentation pathways limiting commercial availability. Coatings formulators in São Paulo are experiencing supply bottlenecks for high-solids viscosity reduction applications.
- Glycerol:C3 polyol occupying premium positioning in pharmaceutical and cosmetics segments. USP-grade purity commands price premiums from excipient manufacturers requiring compliance with FDA safety thresholds.
Ethanol leads on scale; bio-based solvents lead on momentum.
Application:
End-use performance requirements around thermal stability and resin compatibility shape formulation decisions.
- Coatings:Automotive refinishing and industrial protective coatings demanding low-VOC alternatives with equivalent drying characteristics. China's MEE emission standards are forcing Jiangsu province manufacturers to retrofit spray booths with bio-based ester formulations.
- Adhesives:Pressure-sensitive and structural bonding applications requiring controlled evaporation rates. Brazilian sugarcane-derived ethanol is penetrating packaging adhesive segments as ANVISA aligns with FDA pharmaceutical standards.
- Cleaning Agents:Precision electronics and industrial degreasing applications where residue-free performance is critical. Hyderabad pharmaceutical CDMOs are consolidating procurement through qualified supplier programs with redundant manufacturing requirements.
- Paint Thinners:Architectural and decorative coating viscosity modification with flash point compliance for retail distribution. Terpene-based alternatives are displacing aromatic hydrocarbons in DIY segments across European markets.
Coatings dominates volume; cleaning agents shows steepest expansion trajectory.
End Use Industry:
Regulatory stringency and certification requirements create tiered demand patterns across customer verticals.
- Automotive:OEM and refinishing operations subject to stringent VOC regulations. German KBA vehicle certification requirements are accelerating bio-based solvent adoption in electrocoat primer applications.
- Pharmaceuticals:API manufacturing and excipient formulation with ICH Q3C residual solvent compliance. Multi-year direct procurement contracts are replacing spot-market purchasing among large-scale manufacturers in India and Germany.
- Cosmetics:Personal care formulation requiring USP or cosmetic-grade purity certifications. Glycerol demand concentrates in premium positioning segments where biogenic sourcing supports clean-label marketing claims.
- Food Processing:Extraction and processing aids subject to food-contact regulatory limits. Supercritical CO2 convergence with bio-solvent extraction is opening pharmaceutical API purification crossover applications.
Pharmaceuticals leads on margin; automotive leads on volume velocity.
Distribution Channel:
Supply chain configuration reflects customer scale, certification requirements, and volume certainty needs.
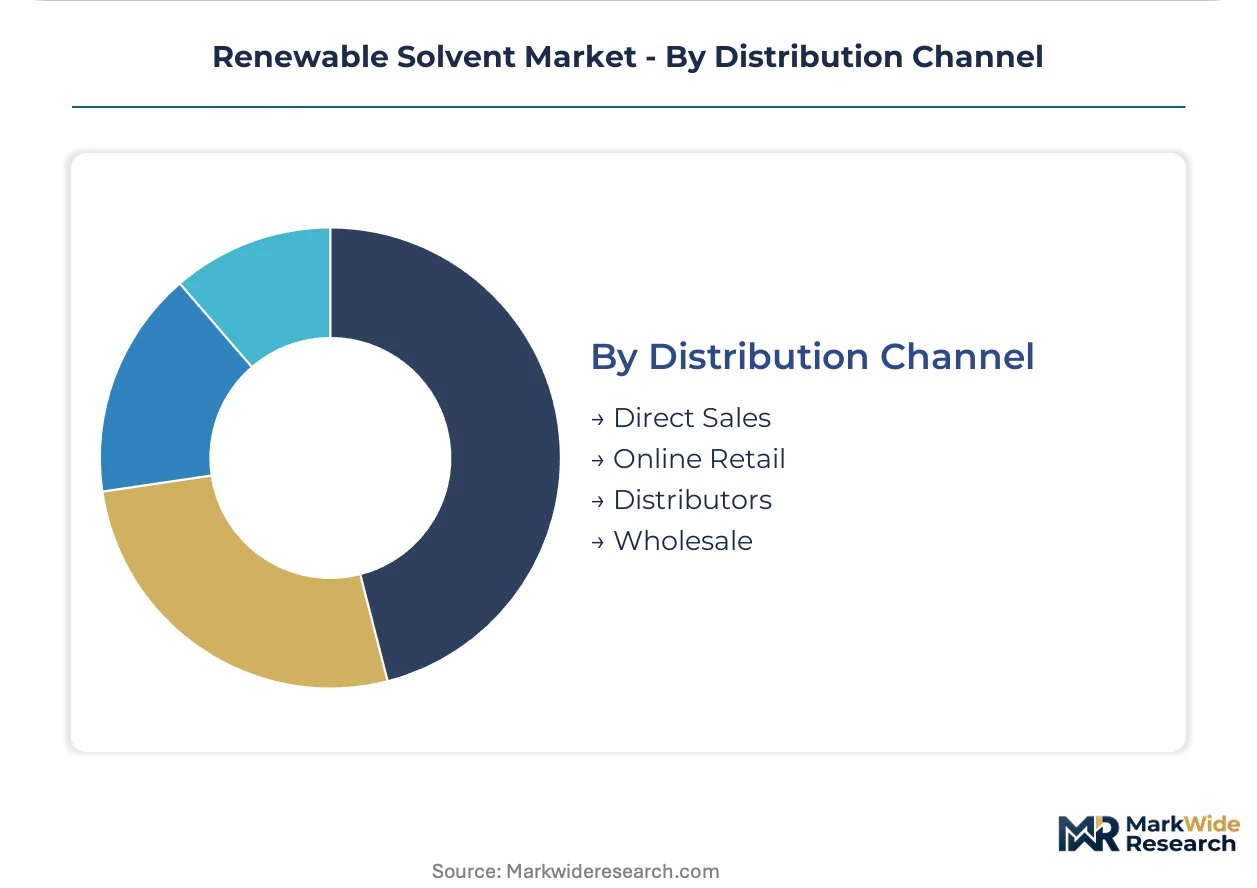
- Direct Sales:Biorefinery-to-manufacturer contracts bypassing distributor markups for volume certainty. Coatings manufacturers are negotiating direct procurement agreements with corn-processing operators in the US Midwest.
- Online Retail:Small-volume specialty solvent distribution for laboratory and pilot-scale applications. Limited penetration in pharmaceutical-grade segments where chain-of-custody documentation is mandatory.
- Distributors:Regional inventory positioning for multi-product procurement efficiency. Facing displacement as qualified supplier programs consolidate procurement through direct channels.
- Wholesale:Bulk terminal operations serving commodity-grade ethanol and solvent blends. Margin compression from feedstock price volatility is driving consolidation among regional wholesalers.
Direct sales gains share fastest; distributors retain relevance in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive coaters in Stuttgart and Wolfsburg industrial corridors are requalifying supply chains around bio-based esters as ECHA enforces REACH sunset dates for aromatic hydrocarbons.
United States
Corn-processing biorefineries across Iowa and Illinois are expanding dedicated solvent-grade ethanol capacity for pharmaceutical excipient manufacturers. EPA volatile organic compound rules are compressing petrochemical solvent availability in manufacturing facilities. Midwest fermentation infrastructure anchors North American supply security for coatings and pharmaceutical processing hubs.
Germany
REACH authorization requirements are compelling automotive OEMs and industrial coaters to switch from toluene and xylene derivatives. ECHA sunset date enforcement is tightening petrochemical restrictions across Baden-Württemberg and North Rhine-Westphalia. BASF SE leverages integrated biotechnology platforms in Ludwigshafen to secure feedstock flexibility for European operations.
China
Dual carbon goals and MEE emission standards are forcing coatings manufacturers in Jiangsu and Zhejiang provinces to retrofit spray booths with bio-based formulations. Provincial environmental bureaus enforce phased VOC reductions in automotive refinishing operations. Domestic producers in Shanghai industrial corridors are reformulating with bio-based esters to maintain operating licenses.
Brazil
Sugarcane biorefineries in São Paulo state are deploying enzymatic hydrolysis platforms to convert bagasse into C5-C6 alcohol streams. ANVISA regulatory alignment with FDA standards creates export-ready ethanol supply for North American pharmaceutical buyers. Coatings formulators in São Paulo industrial corridors are qualifying cellulosic grades for high-solids coating systems.
India
Pharmaceutical API manufacturers in Hyderabad's cluster are consolidating solvent procurement through qualified supplier programs with redundant manufacturing requirements. CDSCO oversight of residual solvent limits steers formulators toward USP-grade ethanol and glycerol grades. Large-scale manufacturers are awarding multi-year direct contracts to biorefineries with dedicated pharmaceutical-grade production lines.
Renewable Solvent Market Key Industry Players
Global majors compete with regional champions across feedstock security and fermentation scale. The vendor base organizes around three tiers: integrated petrochemical diversifiers with biorefinery investments, agricultural processors leveraging captive corn and sugarcane supply, and specialty biotechnology platforms focused on pharmaceutical-grade purity. Competitive moves concentrate on backward integration into feedstock production and direct procurement contracts that bypass traditional distribution channels.
Within the agricultural processor tier, Archer Daniels Midland Company and Cargill Incorporated exemplify scale advantages through Midwest corn-processing infrastructure that competitors struggle to replicate. BASF SE anchors the integrated diversifier archetype with biotechnology platforms spanning European operations. Neste occupies a distinctive position on renewable hydrocarbon technology leadership, extending refinery footprint into solvent-grade output.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Vertec BioSolvents |
| Neste |
| Cremer Oleo GmbH & Co. KG |
| InKemia Green Chemicals, Inc. |
| BASF SE |
| Cargill Incorporated |
| LyondellBasell Industries Holdings B.V. |
| Dow |
| Others |
Cost & Logistics Intelligence
Corn feedstock costs cascade through US Midwest biorefineries into three distinct pricing tiers for solvent-grade ethanol, with pharmaceutical-grade purity commanding substantial premiums over industrial coating grades as FDA residual solvent limits tighten.
Pricing Analysis
Input-cost pass-through from commodity corn and sugarcane directly shapes contract-based long-term offtake structures dominating pharmaceutical procurement. Price differentiation separates USP-certified ethanol for excipient manufacturers from technical grades for coatings formulators, with certification level and volume scale as primary drivers. Pricing pressure stems from feedstock commodity swings compressing biorefinery margins. Coatings manufacturers exhibit highest price sensitivity due to thinner formulation economics, while pharmaceutical buyers prioritize supply security over unit cost.
Supply Chain Analysis
Logistics and freight costs from Brazilian sugarcane belt terminals to North Atlantic pharmaceutical hubs add substantial landed cost differentials versus US Midwest rail shipments. Supply concentrates in the United States, Brazil, and Germany as primary production geographies. Raw material dependencies center on corn, sugarcane, and lignocellulosic feedstocks. Single-source vulnerability risks emerge where biorefineries lack redundant fermentation trains. Distribution runs through direct procurement contracts bypassing traditional distributor networks as coatings manufacturers seek volume certainty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as REACH authorization timelines and China's MEE emission standards structurally displace petrochemical alternatives across three continents.
For Market Incumbents: Anticipate fermentation-scale-up talent scarcity delaying competitor biorefinery commissioning by 12-18 months. Secure backward integration into dedicated corn-processing infrastructure in Iowa and Illinois to defend feedstock cost positions. Invest in redundant pharmaceutical-grade production lines to meet Hyderabad CDMO supplier qualification requirements. For New Entrants and Emerging Players: REACH authorization in Germany opens a window for bio-based ester supply to Stuttgart automotive coaters facing ECHA sunset date enforcement. Target Brazilian sugarcane bagasse-to-C5-alcohol platforms as the most penetrable white space, where enzymatic hydrolysis technology gaps limit incumbent scale. Pursue ANVISA-aligned export certification as the fastest go-to-market pathway for North American pharmaceutical buyers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap agricultural processors lack captive fermentation infrastructure to compete with ADM and Cargill scale advantages. Frame long-term viability around 5-10 year regulatory displacement curves rather than commodity margin cyclicality. Prioritize acquisition targets with established pharmaceutical-grade certification and redundant manufacturing sites. Watch ECHA enforcement acceleration in Baden-Württemberg as the key inflection signal for European demand step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | ADM and Cargill replicate their Midwest captive supply advantages that competitors cannot match. |
| Pharmaceutical-Grade Certification Investment | USP-grade purity unlocks premium positioning in Hyderabad and German API manufacturing clusters. |
| Long-term Supply Agreement with Coatings OEMs | Direct procurement contracts with German automotive coaters bypass distributor markups entirely. |
| Joint Venture with Brazilian Bagasse Platforms | Enzymatic hydrolysis partnerships in São Paulo state secure cellulosic C5-C6 alcohol feedstocks. |
| Green Manufacturing Transition | Dual carbon alignment in Jiangsu province maintains operating licenses under tightening MEE standards. |
Research Approach
Direct dialogue with biorefinery plant managers, coatings procurement leads at German automotive OEMs, pharmaceutical excipient formulators, and distribution channel partners grounded qualitative findings. Secondary validation drew from ECHA authorization databases, FDA residual solvent guidance documents, US EPA VOC rulemakings, and ANVISA regulatory alignment notices. Customs and trade flow data from USITC and Eurostat complemented SEC filings from agricultural processors. Bottom-up capacity assessments triangulated against top-down demand modeling across end-use segments.
Bottom-up modeling of fermentation capacity expansions and top-down regulatory displacement curves converged across the projection horizon. Segmentation dimensions included product chemistry grade, end-use application, purity certification tier, and regional production hub. CAGRs derived from weighted average of feedstock cost trajectories, regulatory enforcement timelines, and substitution elasticity estimates for aromatic hydrocarbon displacement. Industry-specific inputs incorporated ECHA sunset date schedules and MEE provincial enforcement phases.
Revisions become necessary when ECHA accelerates REACH authorization timelines, MEE tightens VOC limits beyond current phased reductions, or corn-sugar price spreads invert feedstock economics. Forecasts reflect documented assumptions about regulatory enforcement consistency and biorefinery commissioning schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Bio-Based Ethylene Market