
 Food and Beverage Protective Cultures Market | 2026-2036
Food and Beverage Protective Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Protective Cultures Market Foresight
Subscription-based technical support for culture rotation and shelf-life validation is recalibrating how protective culture suppliers monetize relationships beyond bulk ingredient sales. Chr. Hansen Holding A/S leverages its strain collection depth to anchor premium positioning in dairy applications. DSM-Firmenich AG sustains competitive separation through integrated enzyme-culture formulations. Lallemand Inc. dominates yeast and bacteria strain manufacturing across North American fermentation facilities.
Food and beverage protective cultures comprise live, food-grade microorganisms—primarily lactic acid bacteria, bacteriocin producers, and propionic acid strains—delivered in freeze-dried or frozen concentrate forms at defined colony-forming-unit counts per gram, functioning to outcompete spoilage organisms and pathogens through pH reduction, antimicrobial peptide secretion, and nutrient competition. Their primary commercial purpose is to replace or reduce chemical preservatives while maintaining microbiological safety and sensory quality in perishable foods. Lactic acid bacteria occupies the largest margin pool due to decades of regulatory familiarity and dairy industry integration, while bacteriocins represent the fastest-expanding category as processors seek targeted inhibition of listeria and clostridia without label penalties. Plant-based foods application is accelerating fastest among end-use segments as vegan cheese and fermented analogues require tailored culture systems absent traditional dairy matrices.
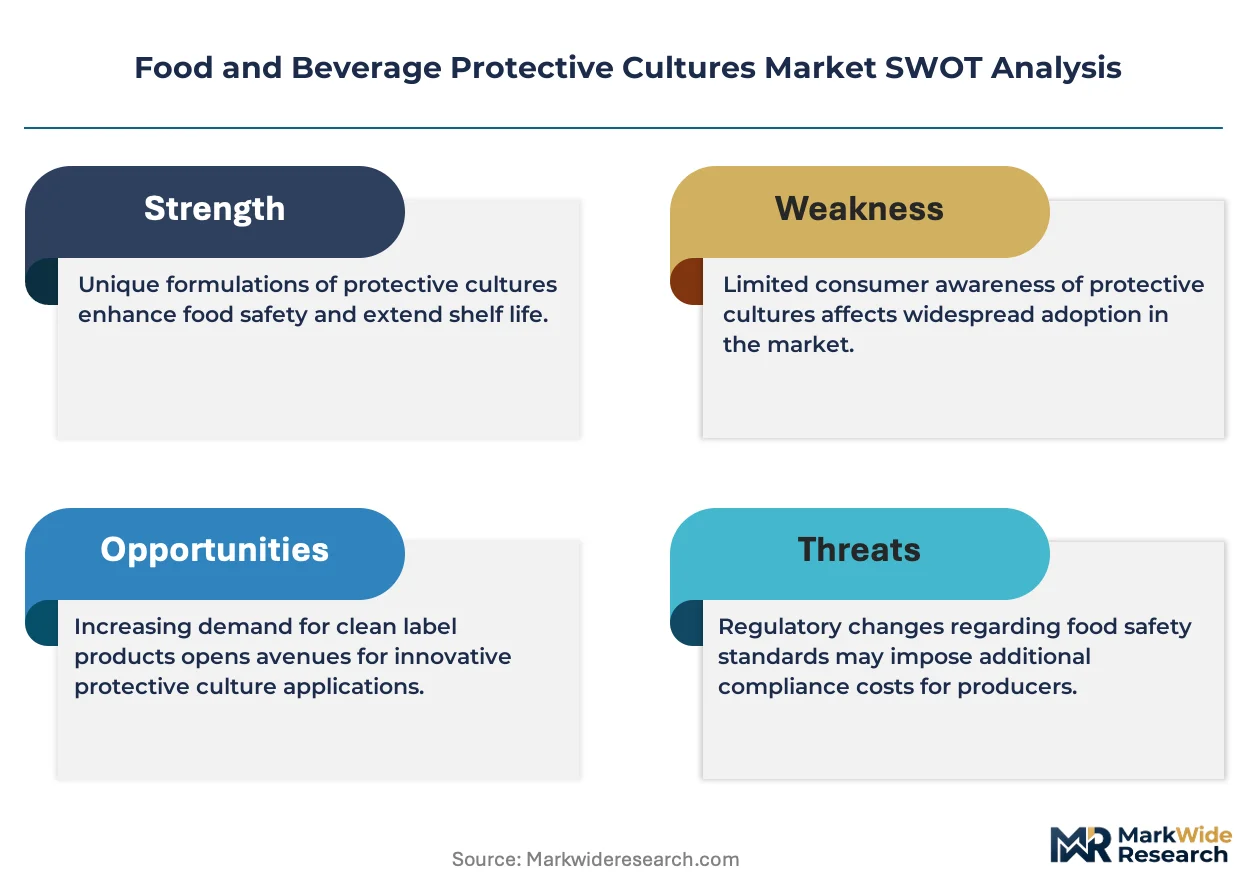
EFSA evaluates novel culture strains for qualified presumption of safety status, while the EU Green Deal drives substitution mandates for synthetic preservatives across member state food codes. FDA generally recognizes traditional lactic acid bacteria as safe, though new bacteriocin-expressing strains trigger GRAS notification requirements that shape market entry timelines. Stakeholders must monitor evolving strain-level transparency demands from EFSA and FDA as whole-genome sequencing becomes standard for culture safety verification.
Market Dynamics
The EU Green Deal's synthetic preservative substitution mandates are restructuring competitive advantage toward live culture suppliers with qualified presumption of safety dossiers and rapid strain validation pipelines.
Growth Catalysts
- REACH compliance deadlines:Chemical preservative phase-out timelines across EU member states are forcing reformulation toward bacteriocin-producing and propionic acid strains in processed meats and ready-to-eat meals.
- Clean-label dairy expansion:German, French, and Danish processors are integrating protective cultures into extended-shelf-life milk and cheese applications to satisfy retailer label-score requirements.
- Fermentation biotechnology clusters:Copenhagen, Delft, and Lyon host concentrated strain development infrastructure that accelerates commercial scale-up for novel protective culture systems.
Market Restraints
- Strain validation cost structure:EFSA qualified presumption of safety dossiers require whole-genome sequencing and toxicology studies that burden mid-tier suppliers with six-figure compliance investments per novel strain.
- Freeze-dried concentrate supply concentration:North American contract manufacturing facilities control bulk lyophilization capacity, creating geographic dependency for European culture suppliers seeking toll production.
- Bacteriocin stability limitations:Nisin and pediocin activity degrades across thermal processing steps, restricting application in UHT-treated beverages and retorted soups.
Strategic Opportunities
- Plant-based analogues:Vegan cheese and fermented oat yogurt manufacturers in Sweden and Netherlands require tailored culture systems absent traditional dairy matrices, opening formulation partnerships.
- Subscription technical support:Culture rotation advisory and shelf-life validation services create recurring revenue streams beyond bulk ingredient transactions.
- Dual-use enzyme-culture convergence:Integrated formulations combining proteolytic enzymes with protective strains address texture defects in reduced-sodium fermented products.
Industry Challenges
- Strain banking and IP fragmentation:Culture collections at DSM-Firmenich, Chr. Hansen, and public repositories maintain overlapping proprietary claims, complicating licensing for multi-strain formulations.
- Legacy dairy equipment incompatibility:Existing CIP protocols and tank designs in smaller processing plants require retrofitting to maintain live culture viability through production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Protective Cultures Market |
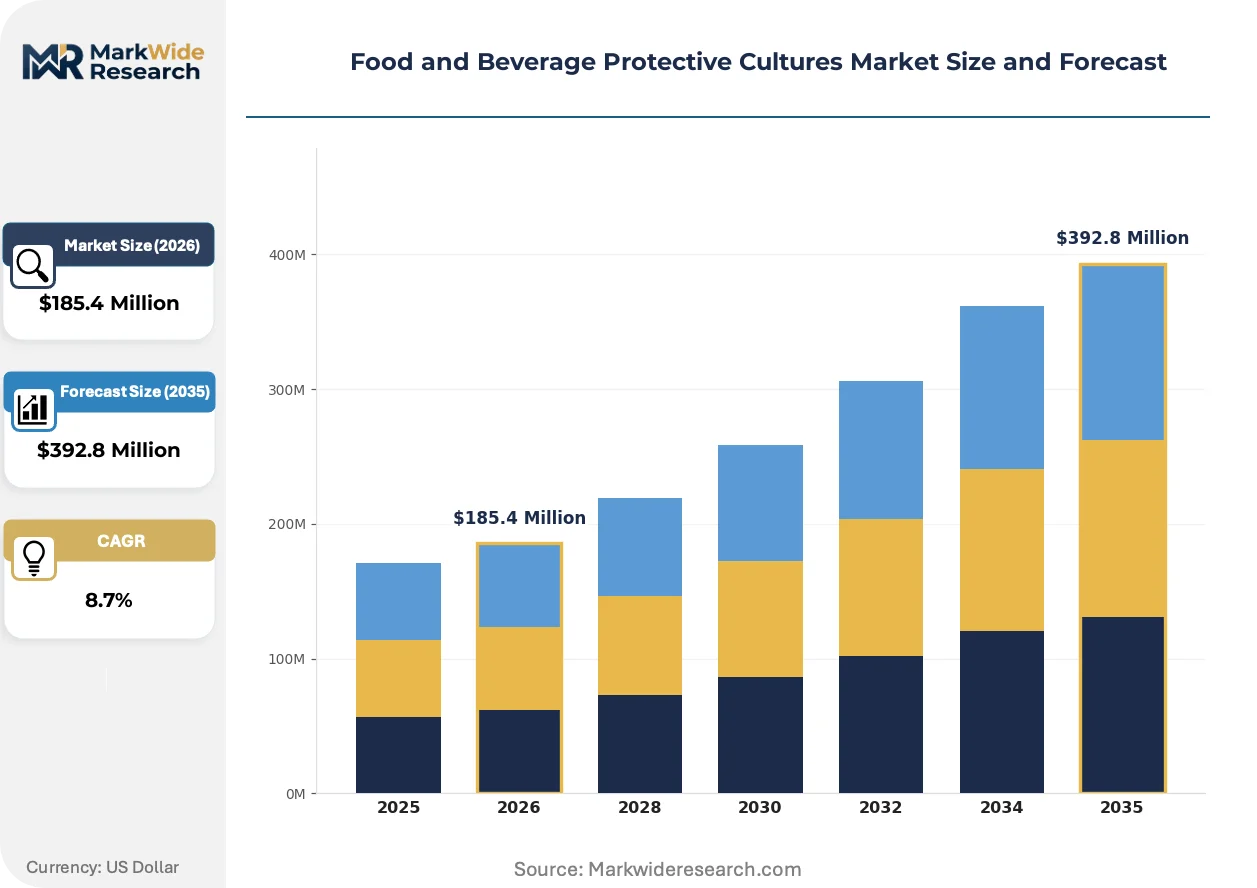
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactic Acid Bacteria, Bacteriocins, Propionic Acid Bacteria, Yeasts, Molds Application: Dairy Products, Meat Processing, Bakery Products, Fermented Beverages, Plant-Based Foods End User: Food Processing Plants, Beverage Manufacturers, Artisan Producers, Contract Packagers Packaging Type: Vacuum Packs, Modified Atmosphere Packaging, Aseptic Packaging, Bulk Containers |
| Companies Covered | Chr. Hansen Holding A/S, International Flavors & Fragrances Inc., DSM-Firmenich AG, Lallemand Inc., Sacco System, CSK Food Enrichment B.V., Bioprox, THT S.A., Biochem S.R.L, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Protective Cultures Market Shifts & Advancements
Whole-genome sequencing is compressing strain safety verification timelines while reshaping how suppliers document antimicrobial peptide expression and horizontal gene transfer risks.
CRISPR-edited bacteriocin hyperproducers are absorbing regulatory scrutiny as EFSA and FDA diverge on gene-edited organism classification. Dairy processors in Denmark and Netherlands are piloting these strains for listeria-targeted inhibition. The technology is absorbing capital allocation from traditional mutagenesis programs as genome editing precision reduces off-target effects.
REACH authorization requirements for benzoates and sorbates are accelerating chemical preservative substitution timelines. Processed meat and chilled ready-meal manufacturers face 2027 compliance deadlines that compress reformulation windows. Plant-based food startups in Germany and France are bypassing chemical preservatives entirely by designing protective cultures into initial formulations.
Buyers are consolidating culture procurement around integrated enzyme-culture suppliers capable of co-developing texture and shelf-life solutions. Mid-sized dairy cooperatives in France are abandoning multi-vendor sourcing in favor of single-partner formulation partnerships. This concentration is most visible in Normandy and Brittany, where cooperative processing plants now specify bundled technical service contracts.
Food and Beverage Protective Cultures Market Segmentation
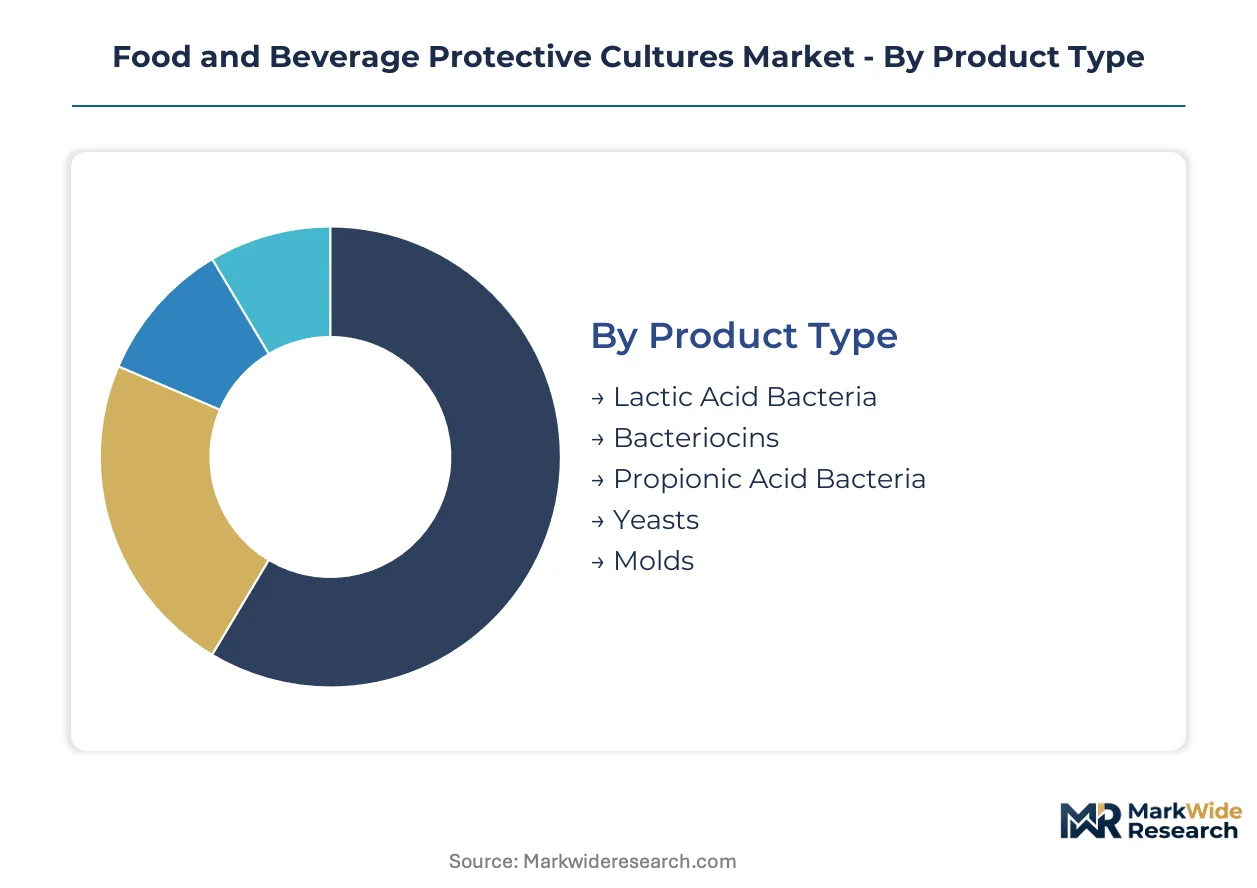
Protective culture suppliers calibrate strain portfolios and formulation services against distinct technical requirements across product categories, applications, and packaging modalities. Segmentation reveals where margin pools concentrate and which customer configurations justify dedicated technical support investments.
Product Type:
Reformulation cycles accelerate as chemical preservative phase-out deadlines force processors to validate live culture alternatives against legacy shelf-life benchmarks.
- Lactic Acid Bacteria:Freeze-dried concentrates of Lactobacillus, Lactococcus, and Streptococcus species deliver pH reduction through homofermentative and heterofermentative pathways. German and French dairy processors anchor volume demand for clean-label yogurt and cheese applications under retailer label-score pressure.
- Bacteriocins:Purified antimicrobial peptides—primarily nisin from Lactococcus lactis and pediocin from Pediococcus species—provide targeted inhibition of Listeria monocytogenes and Clostridium botulinum. Danish processed meat manufacturers absorb supply for ready-to-eat reformulations ahead of REACH authorization deadlines.
- Propionic Acid Bacteria:Strains of Propionibacterium freudenreichii generate propionic and acetic acids for mold inhibition in baked goods.
- Yeasts:Debaryomyces hansenii and Kluyveromyces marxianus strains compete for nutrient access against spoilage fungi in fermented beverages.
- Molds:Penicillium species serve as protective surface cultures in traditional cheese aging, though regulatory scrutiny constrains novel strain introduction.
Volume placements concentrate in Lactic Acid Bacteria; the faster expansion belongs to Bacteriocins.
Application:
Cost tier differentiation separates commodity bulk culture supply from premium co-development partnerships with integrated technical service obligations.
- Dairy Products:Milk, cheese, and fermented dairy applications require strain systems compatible with existing CIP protocols and vat fermentation infrastructure. Normandy and Brittany cooperative processors specify bundled enzyme-culture formulations for texture and shelf-life optimization in reduced-sodium recipes.
- Plant-Based Foods:Vegan cheese and fermented oat yogurt manufacturers in Sweden and Netherlands demand tailored culture systems absent traditional dairy matrices, opening formulation partnerships with strain suppliers capable of rapid adaptation.
- Meat Processing:Fermented and dried meat applications utilize bacteriocin-producing cultures for pathogen control in shelf-stable products.
- Bakery Products:Propionic acid strains extend mold-free shelf life in packaged bread and crumpet applications.
- Fermented Beverages:Kombucha, kefir, and functional drink producers integrate protective yeasts and bacteria for microbial stability through distribution.
Revenue concentrates in Dairy Products; Plant-Based Foods climb the fastest.
End User:
Customer scale determines technical engagement intensity, from commodity concentrate supply to embedded R&D partnerships.
- Food Processing Plants:Large-scale dairy, meat, and bakery facilities purchase freeze-dried concentrates in bulk quantities with strain rotation advisory services. Multi-site operators in Germany negotiate enterprise pricing tied to volume commitments and technical support subscriptions.
- Artisan Producers:Small-batch cheese makers and craft fermenters require smaller packaging formats with educational support on culture handling and viability maintenance.
- Beverage Manufacturers:Kombucha and functional drink producers source specialized yeast-bacteria consortia for consistent fermentation outcomes.
- Contract Packagers:Toll manufacturers serving private-label brands demand flexible strain supply with rapid formulation turnaround for multiple client specifications.
Procurement volume pools with Food Processing Plants; Artisan Producers expand most quickly.
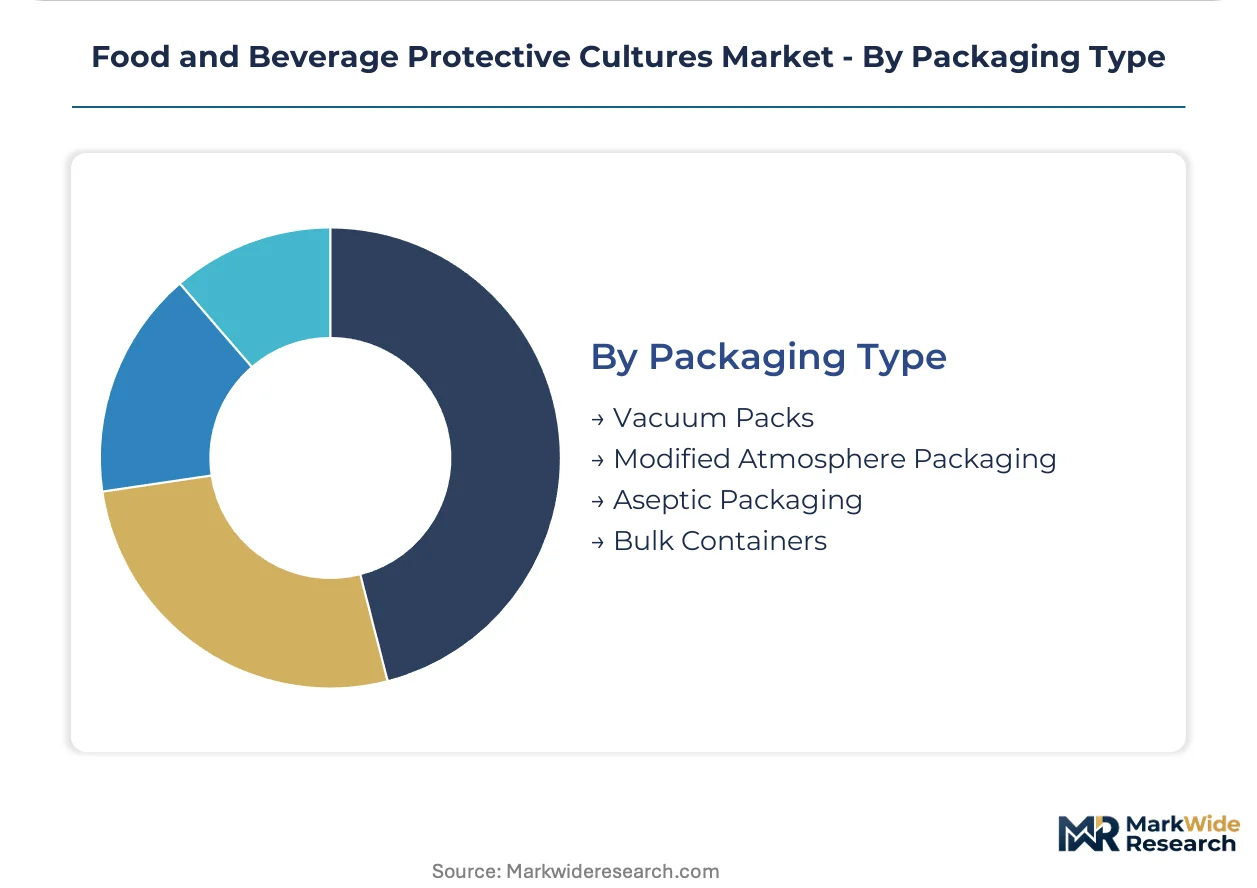
Packaging Type:
Packaging modality dictates culture viability requirements through distribution and shelf-life validation protocols.
- Vacuum Packs:Oxygen-depleted barrier films support anaerobic culture stability in retail cheese and processed meat applications, dominating European chilled distribution.
- Modified Atmosphere Packaging:Controlled gas mixtures extend culture viability in fresh pasta and ready-to-eat meal segments.
- Aseptic Packaging:Sterile filling conditions accommodate thermally sensitive live cultures in extended-shelf-life liquid products.
- Bulk Containers:Industrial totes and drums serve food processing plants with high-throughput culture reconstitution systems.
Shipment volumes concentrate in Vacuum Packs; Modified Atmosphere Packaging gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European fermentation biotechnology clusters, while consumption spreads across dairy and plant-based processing centers in Germany, France, and Scandinavia. Denmark and the Netherlands export culture concentrates to North American toll manufacturers, creating transatlantic supply dependencies.
Germany
Dairy cooperatives in Bavaria and North Rhine-Westphalia integrate protective cultures into extended-shelf-life milk for retailer label-score compliance. REACH authorization deadlines for benzoates and sorbates force reformulation in processed meat facilities by 2027. The Munich biotech corridor hosts strain development infrastructure serving Central European dairy processors.
France
Normandy and Brittany cooperative processors specify bundled enzyme-culture formulations for reduced-sodium cheese recipes. ANSM and DGCCRF enforce strain-level documentation requirements under EU food code harmonization. Lyon maintains fermentation research facilities accelerating commercial scale-up for novel protective systems.
Denmark
Danish processed meat manufacturers absorb bacteriocin supply for listeria-targeted inhibition in ready-to-eat reformulations. EFSA qualified presumption of safety dossiers from Copenhagen-based strain collections anchor regulatory positioning for export markets. The Copenhagen-Delft biotechnology corridor concentrates cryopreservation and lyophilization expertise.
Netherlands
Vegan cheese and fermented oat yogurt startups in Amsterdam and Rotterdam demand tailored culture systems absent dairy matrices. Dutch food safety authority NVWA coordinates with EFSA on whole-genome sequencing standards for novel strain introduction. Wageningen University anchors public-private partnerships for plant-based fermentation optimization.
United States
North American contract manufacturing facilities control bulk lyophilization capacity, creating geographic dependency for European culture suppliers seeking toll production. FDA GRAS notification requirements for new bacteriocin-expressing strains shape market entry timelines. Wisconsin and California dairy processors pilot integrated enzyme-culture formulations for clean-label positioning.
Food and Beverage Protective Cultures Market Competitive Landscape
Top-tier vendors anchor premium formulation services, while mid-tier suppliers compete on bulk concentrate pricing and regional distribution reach. The vendor base stratifies across integrated biotechnology conglomerates, specialized fermentation houses, and toll manufacturers controlling lyophilization infrastructure. Two strategic archetypes dominate: strain collection owners leveraging proprietary biodiversity, and enzyme-culture integrators bundling texture and shelf-life solutions. Competitive moves concentrate on M&A for strain banking assets and geographic expansion through toll manufacturing partnerships.
Within the integrated biotechnology tier, Chr. Hansen Holding A/S and DSM-Firmenich AG exemplify divergent positioning strategies. Chr. Hansen represents the strain collection depth archetype, while DSM-Firmenich occupies the enzyme-culture convergence position. Lallemand Inc. anchors the specialized fermentation house category with North American manufacturing scale.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich AG |
| Lallemand Inc. |
| Sacco System |
| CSK Food Enrichment B.V. |
| Bioprox |
| THT S.A. |
| Biochem S.R.L |
| Others |
Supply & Pricing Matrix
REACH-driven chemical preservative substitution timelines in processed meat and ready-to-eat meal manufacturing are compressing reformulation windows, forcing European culture suppliers to secure North American lyophilization capacity at premium rates while mid-tier buyers absorb six-figure strain validation costs.
Pricing Analysis
Cost compression in bacteriocin concentrates accelerates as Danish and German processed meat manufacturers consolidate procurement around integrated enzyme-culture suppliers capable of bundling texture and shelf-life solutions. Pricing stratifies across premium co-development partnerships, standard bulk concentrate supply, and economy-tier commodity strains with limited technical support. Quality grade and certification level—specifically EFSA qualified presumption of safety status—drive price differentiation. Margins are tightening for mid-tier suppliers unable to amortize whole-genome sequencing investments across strain portfolios. Food processing plants exhibit highest price sensitivity due to volume procurement leverage, while artisan producers accept premium pricing for educational support and smaller packaging formats.
Supply Chain Analysis
Cross-Atlantic freight costs for frozen culture concentrates have restructured sourcing decisions as European suppliers seek toll production partnerships with North American lyophilization facilities. Supply concentrates in Denmark, the Netherlands, and France, where Copenhagen-Delft and Lyon fermentation biotechnology clusters anchor strain development infrastructure. Raw material dependencies include cryopreservation media, specialized fermentation substrates, and pharmaceutical-grade freeze-drying excipients. Single-source vulnerability concentrates in North American contract manufacturing facilities controlling bulk lyophilization capacity. Distribution runs through temperature-controlled logistics networks serving dairy cooperatives in Normandy and Brittany, processed meat facilities in Denmark, and plant-based startups in Amsterdam and Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA qualified presumption of safety dossier requirements and whole-genome sequencing mandates are consolidating competitive advantage around strain collection owners with regulatory validation pipelines, forcing mid-tier suppliers toward acquisition or toll manufacturing partnerships.
For Market Incumbents: Anticipate margin pressure from CRISPR-edited bacteriocin hyperproducers by deepening proprietary strain banking through targeted acquisitions of public repository licenses. Vertical integration into cryopreservation and lyophilization infrastructure defends against North American toll manufacturing dependency. Prioritize subscription-based technical support offerings to lock in multi-year revenue streams beyond bulk concentrate transactions. For New Entrants and Emerging Players: CRISPR-edited strain development capabilities open formulation partnerships with Swedish and Dutch plant-based food manufacturers seeking tailored culture systems absent dairy matrices. White-space concentration sits in vegan cheese and fermented oat yogurt applications where incumbent dairy-focused suppliers lack rapid adaptation capacity. Target co-development contracts with Amsterdam and Rotterdam startups bypassing chemical preservatives in initial formulations. For Investors and Strategic Acquirers: The window for entry favors specialized fermentation houses with proprietary strain collections and existing EFSA dossiers. Long-term viability hinges on regulatory positioning as whole-genome sequencing becomes standard for culture safety verification. Watch for EFSA-FDA divergence on gene-edited organism classification as inflection indicator for CRISPR-edited strain commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Collection Acquisition | Proprietary biodiversity anchors premium positioning in EFSA qualified presumption of safety dossier submissions. |
| Integrated Enzyme-Culture Formulation Partnership | Bundled texture and shelf-life solutions capture procurement consolidation among Normandy and Brittany dairy cooperatives. |
| Subscription Technical Support Launch | Recurring revenue from culture rotation advisory and shelf-life validation services displaces transactional bulk concentrate sales. |
| North American Toll Manufacturing Partnership | Lyophilization capacity access mitigates geographic dependency risk for European culture suppliers. |
| Plant-Based Application Co-Development | Formulation partnerships with Swedish and Dutch vegan cheese manufacturers open fastest-expanding end-use segment. |
Research Methodology
Multi-period observation of strain validation timelines, REACH compliance deadlines, and procurement consolidation patterns anchored the trend analysis, supplemented by interviews with fermentation biotechnology R&D directors, dairy cooperative procurement managers, plant-based food startup founders, EFSA regulatory affairs specialists, and North American toll manufacturing facility operators. Secondary validation drew from EFSA qualified presumption of safety dossier databases, EU Green Deal implementation progress reports, FDA GRAS notification filings, and customs records of culture concentrate trade flows. Bottom-up strain-level demand modeling triangulated against top-down segment value allocation.
The input-output matrix framed projections across the analysis window, modeling protective culture demand by product type, application, end-user scale, and packaging modality. CAGRs derived from segment-level growth rate reconciliation against macro drivers including chemical preservative substitution mandates and clean-label retailer requirements. Industry-specific forecast inputs incorporated EFSA dossier approval timelines and CRISPR-edited strain regulatory classification uncertainty.
Several conditions sit outside the modeled scope, including specific strain-level toxicology study outcomes, individual member state transposition of EU Green Deal mandates, and FDA enforcement discretion on gene-edited organism classification. Forecasts reflect assumptions about regulatory trajectory and technology adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Food Tester Market