
 Water Activity Instrumentation Market | 2026-2036
Water Activity Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Water Activity Instrumentation Market Analytics
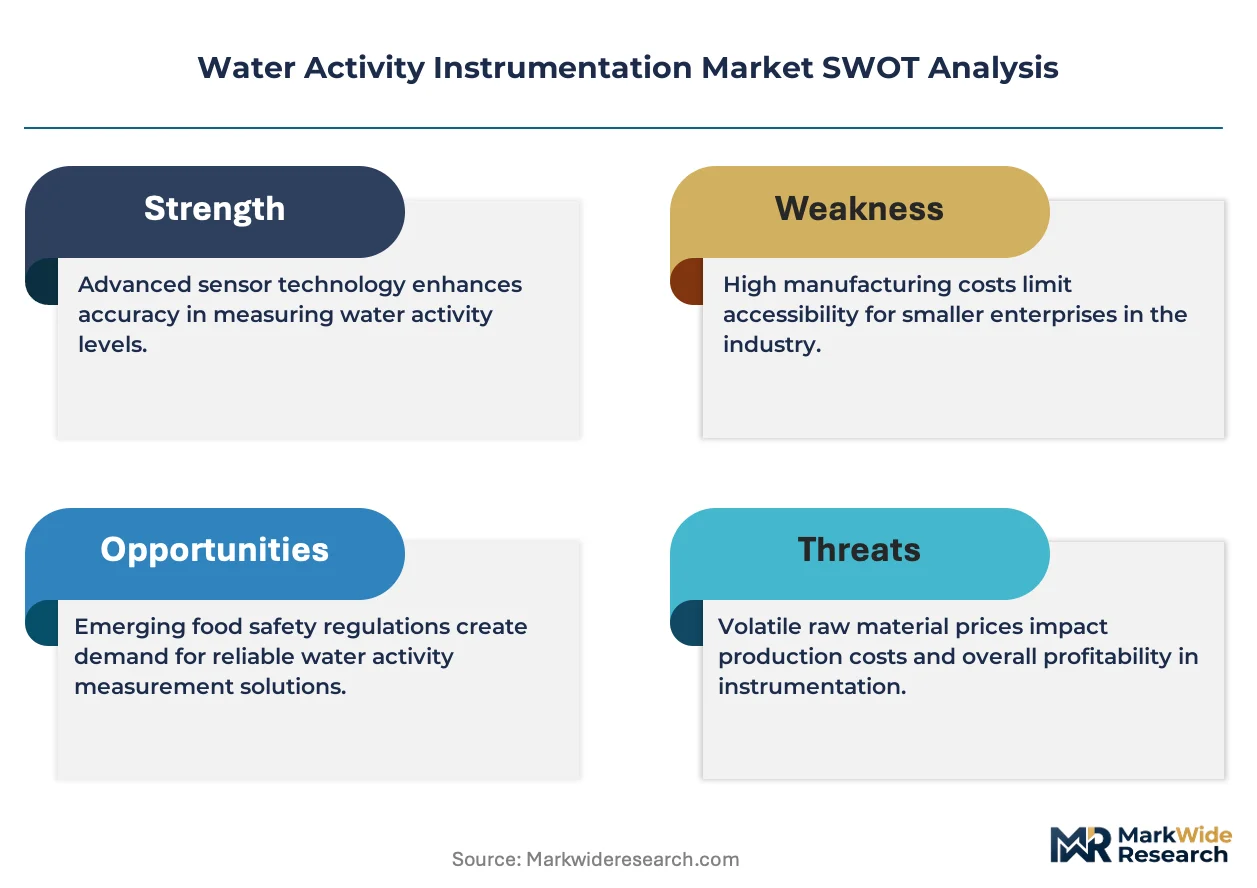
Modular sensor configurations paired with cloud-connected data logging is expanding buyer choice across price tiers. METER Group leverages its chilled-mirror dew point technology to anchor premium positioning in pharmaceutical compliance testing. AQUALAB competes through simplified calibration protocols that reduce technician training burdens in food manufacturing plants. Novasina AG specializes in resistance-based instruments for high-humidity environments where capacitance sensors drift.
Water activity instrumentation measures the equilibrium relative humidity of a sample to predict microbial growth, chemical stability, and shelf life, typically operating across ranges from 0.030 to 1.000 aw with resolution to 0.001 aw. The devices employ chilled-mirror dew point, capacitance, or resistance sensors to detect vapor pressure equilibrium between sample headspace and a calibrated detection surface. Bench-top analyzers dominate margin pools in pharmaceutical quality control where 21 CFR Part 11 compliance commands premium pricing. Portable meters represent the fastest-growing configuration as food processors deploy handheld units for at-line testing to cut laboratory turnaround times. Capacitance technology leads new installations due to faster equilibration speeds and reduced maintenance versus chilled-mirror systems.
The FDA enforces moisture specifications through ICH Q1A stability guidelines and process validation requirements that mandate documented water activity controls for moisture-sensitive drug products. EMA's EU GMP Annex 15 and ICH Q2(R1) validation standards compel European pharmaceutical manufacturers to maintain calibrated instrumentation with full audit trails. ISO 21807 for food microbiology and AOAC Official Methods further standardize measurement protocols across international trade. Stakeholders must weigh sensor technology investments against evolving data-integrity mandates that favor systems with embedded electronic records and automated calibration tracking.
Market Dynamics
Capacitance sensor technology is compressing equilibration times from hours to minutes, forcing recalibration of capital deployment strategies across pharmaceutical quality control departments and contract testing laboratories.
Growth Catalysts
- 21 CFR Part 11 Compliance Mandates:FDA audit trail requirements for electronic records in pharmaceutical stability testing are compelling replacement of legacy analog systems with validated digital platforms.
- Bench-top Analyzer Deployment:Generic drug manufacturers in Germany are accelerating instrument procurement to meet tightened EU GMP Annex 15 moisture control specifications for sterile injectables.
- At-line Testing Migration:Food processors are shifting from central laboratory models to handheld portable meters, eliminating sample transport delays and reducing batch release cycle times.
Market Restraints
- Chilled-mirror Maintenance Burden:Dew point systems require frequent mirror cleaning and desiccant replacement, elevating total cost of ownership versus capacitance alternatives.
- Sensor Drift in High-humidity Environments:Capacitance technology exhibits measurement instability above 0.90 aw, forcing dual-technology investments in tropical climate zones.
- Calibration Standard Supply Concentration:Certified reference materials for water activity verification are sourced from limited accredited laboratories, creating lead time vulnerability.
Strategic Opportunities
- Cloud-connected Data Architectures:Modular sensor configurations with embedded electronic records are opening premium pricing tiers for multi-site pharmaceutical networks requiring centralized compliance dashboards.
- Resistance Sensor Niche Defense:High-humidity industrial environments above 0.95 aw remain underserved by capacitance technology, preserving addressable market for specialized resistance-based instruments.
- Contract Laboratory Consolidation:Third-party testing providers serving generic drug makers are standardizing on single-vendor platforms to reduce technician training overhead and spare parts complexity.
Industry Challenges
- Metrology Skill Scarcity:Technician proficiency in gravimetric calibration verification and sensor drift correction is thinning as experienced operators exit the workforce.
- Legacy System Integration Friction:Pharmaceutical manufacturers with validated LIMS environments face protocol revalidation costs when migrating to cloud-connected instrumentation.
- Multi-site Standardization Complexity:Enterprises with geographically distributed manufacturing must harmonize measurement protocols across facilities with varying ambient humidity conditions and local regulatory interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Activity Instrumentation Market |
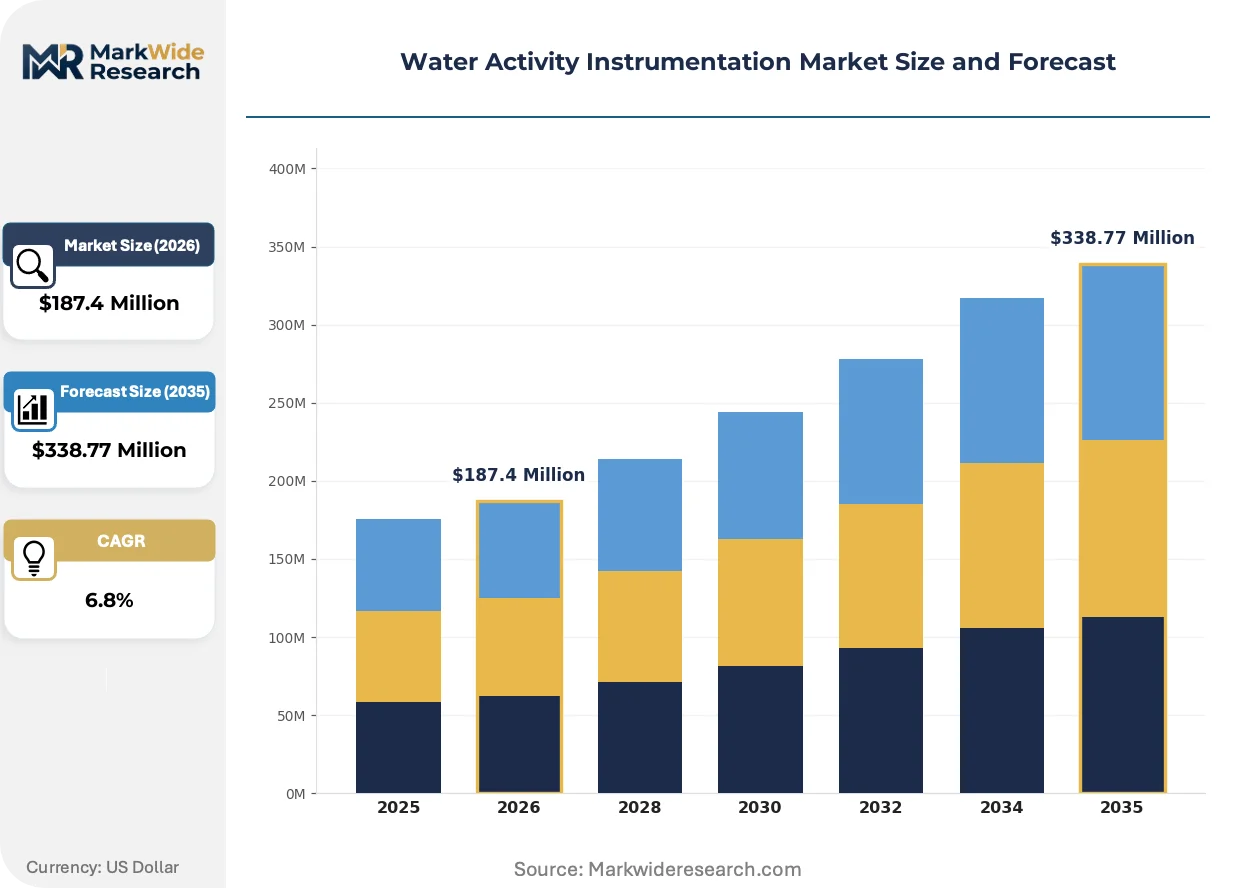
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Bench-top Analyzers, Digital Scanners, Moisture Meters End User: Food Industry, Pharmaceuticals, Cosmetics, Research Laboratories Technology: Capacitance, Resistance, Viscosimetric, Infrared Application: Quality Control, Product Development, Shelf Life Testing, Compliance Testing |
| Companies Covered | METER Group, AQUALAB, Rotronic AG, Novasina AG, Addis Instruments, Elab Analytical, Kett Electric Laboratory, Freund Corporation, Neu-tec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Activity Instrumentation Market Evolving Landscape
Sensor miniaturization and wireless data transmission are collapsing the boundary between laboratory precision and production floor accessibility, enabling real-time moisture monitoring at points previously reserved for offline sampling.
Chilled-mirror dew point technology is electrifying competitive positioning in pharmaceutical compliance testing by delivering reference-grade accuracy that anchors premium pricing tiers against faster but less precise capacitance alternatives. METER Group has anchored its market position on this technology, capturing stability testing contracts where FDA validation requirements tolerate no measurement uncertainty. The structural consequence is a bifurcated vendor landscape separating reference-laboratory suppliers from at-line commodity providers.
EMA's EU GMP Annex 15 revisions are tightening moisture control documentation requirements across sterile product lines, compelling manufacturers to retire unvalidated legacy instruments ahead of scheduled replacement cycles. German contract laboratories serving generic drug makers are responding with accelerated procurement of 21 CFR Part 11 compliant systems. This regulatory compression is concentrating demand timing and amplifying price competition among validated platform suppliers.
Buyer preference is gravitating toward simplified calibration protocols that reduce technician training burdens and minimize procedural deviation risks during shift changes. Food manufacturing plants are displacing complex chilled-mirror systems with capacitance-based units featuring automated internal standards verification. This behavioral shift is most visible in North American meat and dairy processing facilities where labor turnover elevates operational risk from procedure-dependent instrumentation.
Water Activity Instrumentation Market Segmentation
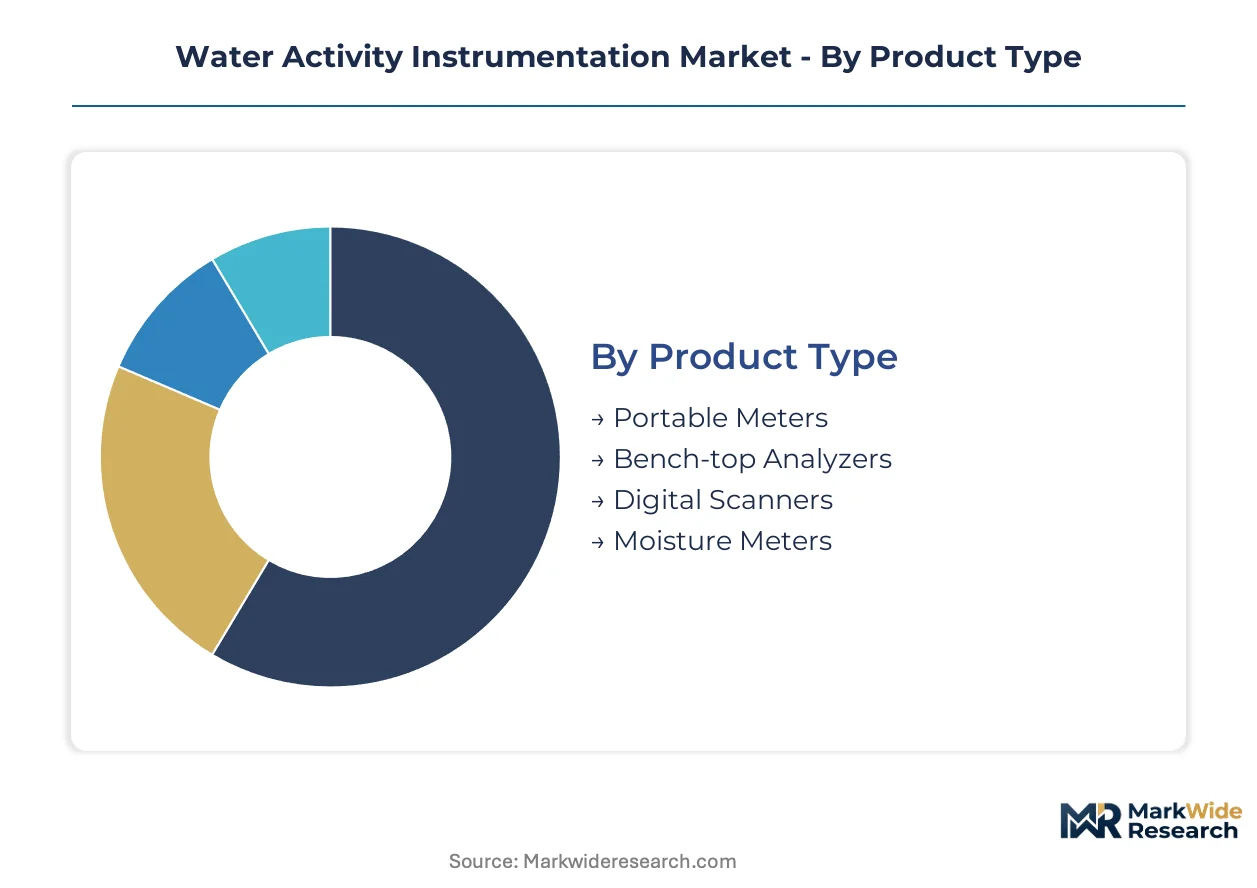
Water activity instrumentation segments diverge sharply across precision requirements, regulatory compliance burdens, and deployment environments. Buyers prioritize sensor technology and form factor based on whether measurements anchor FDA submissions or accelerate at-line food safety decisions.
Product Type:
Replacement cycles accelerate as pharmaceutical manufacturers retire analog systems ahead of EU GMP Annex 15 enforcement deadlines.
- Bench-top Analyzers:Laboratory-grade units deliver 0.001 aw resolution with 21 CFR Part 11 compliant electronic records. Demand clusters in German contract laboratories serving generic drug makers replacing resistance-based legacy systems.
- Portable Meters:Handheld configurations enable at-line testing with wireless data transmission to plant floor networks. Food processors in North American meat and dairy facilities deploy these units to eliminate sample transport delays and compress batch release cycles.
- Digital Scanners:Rapid-scan devices integrate barcode reading with automated sample logging for high-throughput environments.
- Moisture Meters:Hybrid instruments combine water activity with gravimetric moisture content for dual-parameter quality control in grain handling operations.
Volume placements concentrate in portable meters; the faster expansion belongs to bench-top analyzers.
End User:
Regulatory intensity varies dramatically across sectors, with compliance testing requirements reshaping procurement priorities.
- Pharmaceuticals:Sterile injectable manufacturers face FDA process validation mandates and ICH Q1A stability guidelines demanding documented water activity controls. Moisture-sensitive drug products require calibrated instrumentation with full audit trails.
- Food Industry:Processors operate under ISO 21807 microbiology standards and AOAC Official Methods for international trade compliance. At-line deployment dominates as facilities shift from central laboratory models to distributed testing.
- Cosmetics:Formulation stability testing drives demand for mid-range capacitance systems in personal care manufacturing.
- Research Laboratories:Academic and government facilities prioritize reference-grade chilled-mirror dew point technology for method development and standardization work.
Procurement volumes favor food industry deployments; pharmaceuticals command the steepest expansion trajectory.
Technology:
Sensor selection hinges on equilibration speed demands and humidity range constraints specific to each operating environment.
- Capacitance:Solid-state sensors achieve minute-scale equilibration with reduced maintenance versus chilled-mirror alternatives. New installations favor this technology for pharmaceutical quality control and food at-line testing where throughput dominates absolute accuracy.
- Resistance:Electrolytic sensors maintain stability above 0.90 aw where capacitance technology exhibits measurement drift. Tropical climate zones and high-humidity industrial environments preserve demand for specialized resistance-based instruments.
- Viscosimetric:Alternative detection methods serve niche applications in polymer and coating formulation laboratories.
- Infrared:Non-contact vapor detection enables continuous monitoring in process streams where sample extraction is impractical.
Capacitance systems dominate new placements; resistance technology defends its position in high-humidity niches.
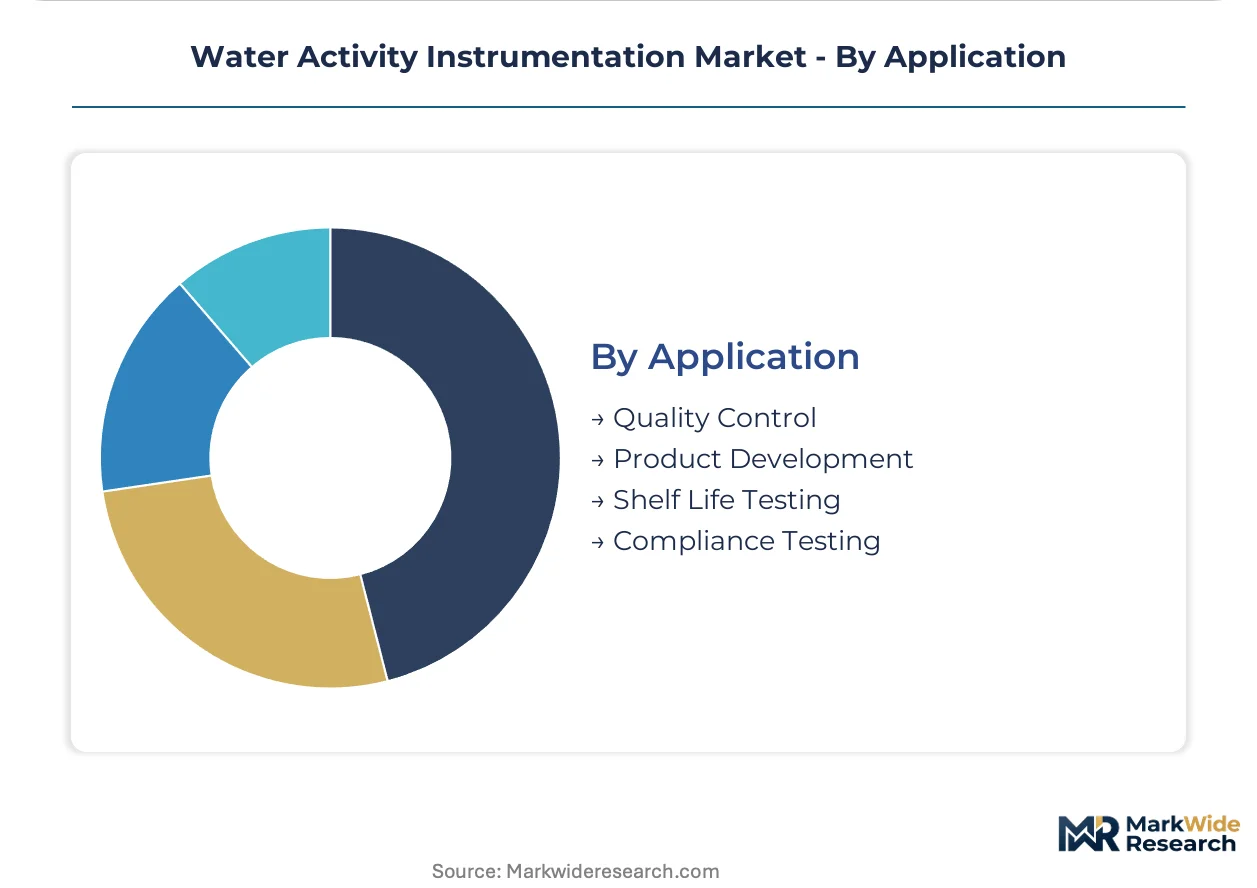
Application:
Use case specificity determines instrument specification, with compliance documentation requirements separating premium from standard tiers.
- Compliance Testing:Regulatory submission support demands validated platforms with embedded electronic records and automated calibration tracking. FDA and EMA audit trail requirements command premium pricing for pharmaceutical stability programs.
- Quality Control:Routine batch release testing drives volume procurement across food and pharmaceutical manufacturing, with simplified protocols reducing technician training burdens.
- Shelf Life Testing:Accelerated aging studies require precise humidity control and long-term data logging capabilities.
- Product Development:Formulation scientists prioritize flexibility and rapid turnaround over regulatory documentation features.
Quality control absorbs the highest unit volumes; compliance testing generates the fastest growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in sensor technology hubs while consumption clusters in pharmaceutical and food processing centers. Germany manufactures precision instrumentation for export while the United States and China absorb the highest absolute demand volumes.
Germany
Contract laboratories serving generic drug makers are replacing legacy resistance-based systems with capacitance technology. EMA's EU GMP Annex 15 revisions tighten moisture control documentation requirements for sterile injectables. The Rhine-Main cluster around Frankfurt hosts concentrated instrument procurement activity from third-party testing providers.
United States
FDA process validation mandates and 21 CFR Part 11 compliance requirements drive pharmaceutical stability testing instrument replacement cycles. The agency's updated guidelines for moisture-sensitive drug products mandate documented water activity controls with full audit trails. Boston-Cambridge biopharma corridor and New Jersey's pharmaceutical manufacturing belt generate concentrated demand for bench-top analyzers.
China
Domestic food processors are deploying handheld portable meters for at-line testing to compress batch release timelines. NMPA alignment with ICH Q1A stability guidelines elevates calibration and documentation standards for pharmaceutical manufacturers. Yangtze River Delta pharmaceutical zones and Shandong food processing hubs represent the fastest-growing regional demand pockets.
Japan
PMDA enforcement of ICH Q2(R1) validation standards compels pharmaceutical manufacturers to maintain calibrated instrumentation with automated calibration tracking. METI industrial standards for food microbiology testing expand addressable market for portable meter deployments. Osaka-Kobe pharmaceutical manufacturing corridor and Chubu region food technology centers concentrate procurement activity.
India
CDSCO harmonization with international stability guidelines accelerates instrument upgrades in domestic generic drug manufacturing. FSSAI implementation of ISO 21807 for food microbiology standardizes measurement protocols across export-oriented processing facilities. Maharashtra's pharmaceutical clusters and Gujarat's food processing zones drive regional demand concentration.
Water Activity Instrumentation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base separates into three strategic archetypes: precision sensor technology developers, compliance-focused platform providers, and cost-optimized commodity suppliers. Consolidation pressure intensifies as pharmaceutical buyers standardize on single-vendor platforms to reduce training overhead. Strategic moves center on technology licensing partnerships and geographic distribution expansion rather than vertical integration.
Within the precision sensor tier, METER Group and Novasina AG exemplify divergent technology bets—chilled-mirror dew point versus resistance-based specialization. AQUALAB occupies a position emphasizing simplified calibration protocols that reduce technician training burdens. These three anchors illustrate how competitive positioning fragments across accuracy-versus-speed trade-offs and maintenance-burden differentiation rather than converging on a single dominant design.
| Leading Market Players |
|---|
| METER Group |
| AQUALAB |
| Rotronic AG |
| Novasina AG |
| Addis Instruments |
| Elab Analytical |
| Kett Electric Laboratory |
| Freund Corporation |
| Neu-tec Group |
| Others |
Value Network & Pricing Analysis
Metrology technician scarcity in Germany's Rhine-Main corridor widens labor-cost spreads between premium validated systems and economy-tier alternatives, compressing mid-market positioning as buyers bifurcate toward compliance-grade or cost-optimized procurement.
Pricing Analysis
Margin tightening in mid-range bench-top units reflects capacitance sensor commoditization as Novasina AG and AQUALAB compete on calibration simplicity. Three-tier pricing structure across premium chilled-mirror, standard capacitance, and economy resistance-based levels separates FDA-validated pharmaceutical systems from food-grade portable meters. Cost-down pressure on portable configurations accelerates as Chinese manufacturers enter at-line testing segments with wireless-enabled handheld units. Generic drug manufacturers in Germany exhibit highest price sensitivity due to EU GMP Annex 15 compliance mandates forcing unbudgeted replacement cycles, while sterile injectable producers accept premium pricing for 21 CFR Part 11 embedded electronic records.
Supply Chain Analysis
Freight cost volatility from Swiss and German precision sensor manufacturers to North American pharmaceutical corridors elevates landed costs for chilled-mirror dew point assemblies. Production gravity centers on Germany, Switzerland, and the United States for reference-grade instrumentation, while China and South Korea supply capacitance sensor substrates and wireless communication modules. Raw material dependencies span precision-machined aluminum enclosures, certified reference salt standards from limited accredited laboratories, and specialty desiccants for mirror maintenance. Single-source vulnerability concentrates in NIST-traceable calibration standard supply, where lead times extend unpredictably. Distribution runs through authorized distributor networks with factory-trained service capabilities, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water activity instrumentation functions as a cost-of-compliance market where FDA 21 CFR Part 11 validation requirements erect structural barriers protecting incumbent positions from unvalidated low-cost entrants.
For Market Incumbents: Anticipate regulatory compression accelerating replacement cycles by maintaining excess calibration standard inventory and pre-positioning validated cloud-connected platforms ahead of EU GMP Annex 15 enforcement waves. Consolidation opportunities concentrate in German contract laboratory networks seeking single-vendor standardization to reduce technician training overhead. Backward integration into certified reference material production mitigates supply concentration risk. For New Entrants and Emerging Players: Contract laboratory networks serving generic drug makers represent the most penetrable channel, as these buyers prioritize simplified calibration protocols over absolute accuracy and lack loyalty to legacy chilled-mirror suppliers. Resistance-based specialization for tropical climate zones above 0.95 aw remains defensible white space where capacitance technology drifts. Go-to-market positioning should emphasize automated internal standards verification that reduces procedural deviation risks during shift changes. For Investors and Strategic Acquirers: The window for entry favors precision sensor technology developers with captive chilled-mirror intellectual property, as pharmaceutical compliance testing tolerates no measurement uncertainty and sustains premium pricing. Long-term viability hinges on cloud-connected data architectures enabling multi-site pharmaceutical network consolidation. Monitor NMPA alignment with ICH stability guidelines in China as inflection signal for accelerated instrument upgrade demand in domestic generic manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Platform Launch | Embedded electronic records satisfy FDA 21 CFR Part 11 audit trail mandates for pharmaceutical stability testing. |
| Calibration Standard Backward Integration | In-house production of NIST-traceable salts reduces lead time vulnerability from limited accredited laboratory supply. |
| Resistance Sensor Niche Defense | Specialized high-humidity instruments above 0.95 aw preserve addressable market where capacitance technology drifts. |
| Contract Laboratory Partnership | Single-vendor standardization agreements reduce technician training overhead and spare parts complexity for generic drug makers. |
| Wireless Portable Meter Expansion | Handheld at-line testing configurations capture food processor demand for compressed batch release cycle times. |
Research Methodology
Document review covered FDA 21 CFR Part 11 guidance documents, EMA EU GMP Annex 15 revisions, ISO 21807 food microbiology standards, and AOAC Official Methods, complemented by interviews with pharmaceutical quality control directors, contract laboratory operations managers, food safety compliance officers, and instrument calibration technicians. Secondary validation drew from SEC filings of diversified measurement technology conglomerates, customs trade data for precision instrument imports, and industry association technical publications. Bottom-up demand modeling from end-user procurement patterns was cross-referenced against top-down market sizing from sensor technology shipment data.
Historical capacity utilization and pricing trajectories were cross-referenced against expert panel assessments of regulatory enforcement intensity and technology substitution rates. Segmentation modeling spanned product type, sensor technology, end-use industry, compliance tier, and regional regulatory cluster. CAGRs were derived from slope analysis of replacement cycle acceleration and new installation demand. Industry-specific forecast inputs included EMA enforcement timeline projections for EU GMP Annex 15 and NMPA harmonization progress with ICH Q1A stability guidelines.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, abrupt trade restriction implementations affecting sensor component flows, and disruptive non-contact detection technology breakthroughs. Forecasts reflect assumptions about continued pharmaceutical compliance spending prioritization and food processor at-line testing migration. Stakeholders should weight assumptions against their own operating context and regulatory inspection history.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Mercury Testing Service Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Bottled Water Testing Equipment Market