
 North America Food Safety Testing Market | 2026-2036
North America Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Safety Testing Market Analytics
Contract testing laboratories serving food manufacturers is bifurcating away from in-house quality departments at processing plants. Eurofins Scientific leverages its North American laboratory network to anchor high-throughput pathogen screening for protein processors. Bureau Veritas competes through specialized audit and certification bundles that extend beyond analytical results into supply chain verification.
Food safety testing encompasses analytical methods and diagnostic protocols that detect biological, chemical, and physical hazards in consumable products, employing technologies such as polymerase chain reaction with detection thresholds reaching single colony-forming units per gram. Its primary commercial purpose is to verify compliance with maximum residue limits and microbial performance standards before products enter distribution. PCR-based microbial screening leads technology adoption due to specificity advantages over culture-based alternatives, while rapid testing formats capture the fastest expansion as processors seek same-shift release decisions. Dairy and meat applications concentrate margin pools because these categories face the most stringent pathogen monitoring requirements under federal rules.
The FDA enforces preventive controls through FSMA mandates that require hazard analysis and verified corrective actions, while the USDA Food Safety and Inspection Service maintains zero-tolerance standards for Salmonella and Listeria in ready-to-eat products. These frameworks shape demand by mandating documented testing frequencies that laboratories must satisfy to keep processors compliant. Stakeholders should monitor how whole-genome sequencing integration by federal agencies alters outbreak traceback expectations and testing scope requirements.
Market Dynamics
Contract testing laboratories are displacing in-house quality departments as the dominant service delivery model, driven by FSMA preventive control mandates that require documented third-party verification for hazard analysis and corrective action protocols.
Growth Catalysts
- FSMA Preventive Controls Rule:The FDA's mandate for documented hazard analysis and verified corrective actions forces processors to maintain rigorous testing schedules, expanding laboratory service contracts.
- Protein processing clusters:Concentrated meat and dairy operations across the US Midwest generate sustained pathogen screening volume that anchors regional laboratory capacity expansion.
- PCR-based microbial screening:Polymerase chain reaction methods deliver single colony-forming unit detection thresholds that satisfy zero-tolerance standards for Salmonella and Listeria in ready-to-eat products.
Market Restraints
- Reference material costs:Certified pathogen strains and control standards face supply volatility from limited domestic producers, compressing laboratory margin structures.
- Equipment concentration:High-throughput sequencing and mass spectrometry platforms concentrate among three metropolitan laboratory hubs, creating geographic access barriers for remote processors.
- Culture-based method persistence:USDA FSIS maintains gold-standard culture protocols for enforcement actions, forcing laboratories to run parallel analytical workflows and duplicate resource allocation.
Strategic Opportunities
- Canadian regulatory alignment:Health Canada's Safe Food for Canadians Regulations create parallel compliance obligations that favor laboratories with cross-border accreditation and unified reporting systems.
- Whole-genome sequencing integration:Federal agencies are expanding outbreak traceback capabilities, creating demand for genomic characterization services beyond standard pathogen detection.
- Same-shift release formats:Rapid testing technologies that compress analytical turnaround from days to hours enable processors to hold and release product within single production shifts.
Industry Challenges
- Microbiologist workforce scarcity:Specialized laboratory personnel with pathogen handling certification face recruitment competition from pharmaceutical and clinical diagnostics sectors.
- Multi-jurisdictional accreditation:Laboratories serving both FDA-regulated and USDA-inspected facilities must maintain separate quality systems and audit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Safety Testing Market |
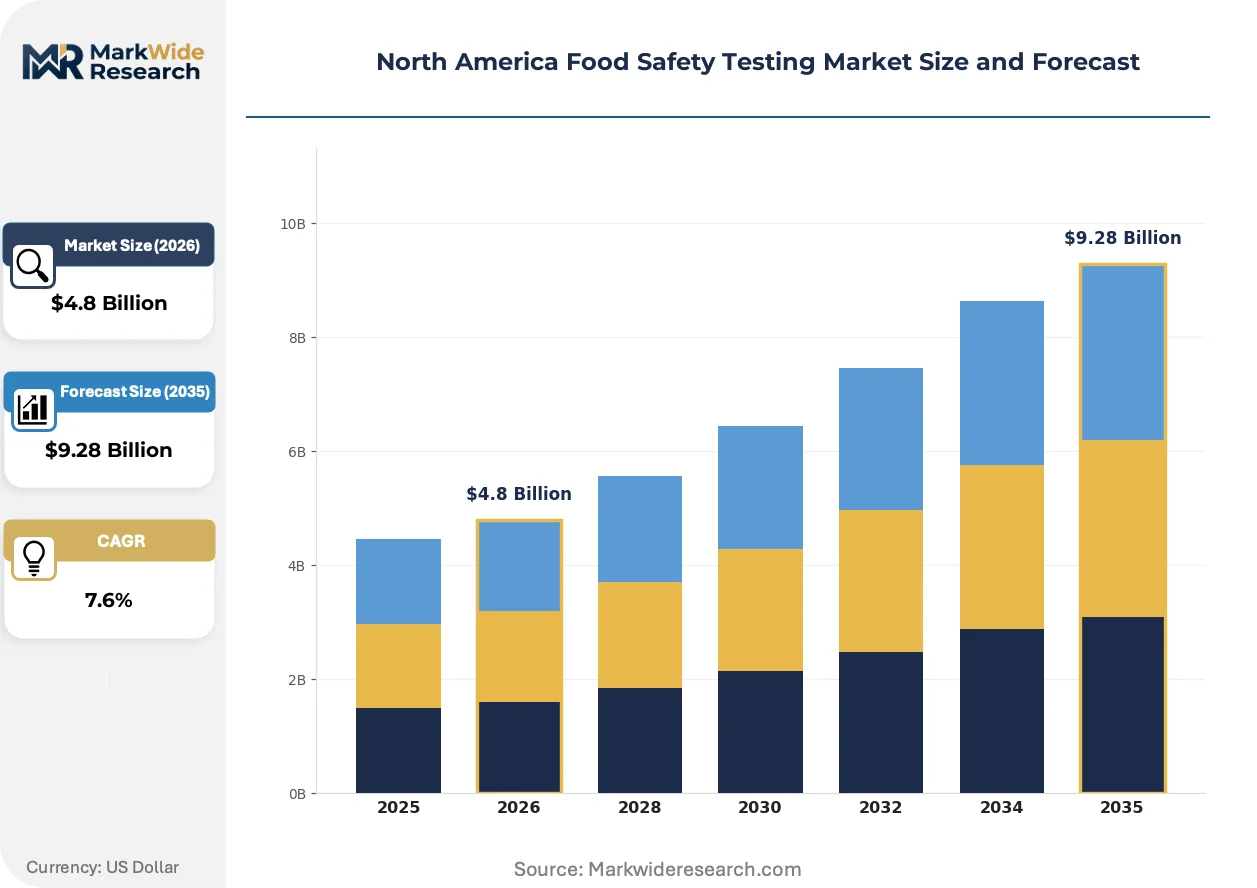
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Microbial, Chemical, Allergen, Nutritional End User: Food Manufacturers, Retailers, Laboratories, Government Agencies Technology: PCR, ELISA, Chromatography, Rapid Testing Application: Dairy, Meat, Seafood, Grains |
| Companies Covered | SGS SA, Eurofins Scientific, Bureau Veritas, Intertek Group PLC, ALS Limited, Mérieux NutriSciences, NSF International, Neogen Corporation, Laboratory Corporation of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Safety Testing Market Evolving Landscape
Portable diagnostic platforms are compressing the distance between production lines and analytical confirmation, enabling real-time release decisions that reshape traditional laboratory-processor relationships.
Loop-mediated isothermal amplification (LAMP) devices perform nucleic acid detection without thermal cycling equipment, enabling deployment directly at processing facilities. Mid-size protein processors in the US Great Plains are adopting these systems to reduce sample transport delays. The technology is miniaturizing pathogen screening from centralized laboratories to point-of-production verification, compressing the analytical service chain.
The FDA's New Era of Smarter Food Safety blueprint mandates enhanced traceability requirements for high-risk foods, compelling processors to integrate testing data with supply chain documentation systems. This regulatory pressure accelerates digital platform adoption for laboratory information management. Dairy operations face the most immediate compliance deadlines, driving investment in automated data capture and reporting infrastructure.
Processors are consolidating testing contracts with multi-service providers that bundle analytical work with audit and certification services, reducing vendor management overhead. This procurement consolidation favors laboratories with integrated service portfolios over specialized analytical-only competitors. The pattern is most pronounced among national meatpacking operations seeking unified compliance documentation across multiple facility locations.
North America Food Safety Testing Market Segmentation
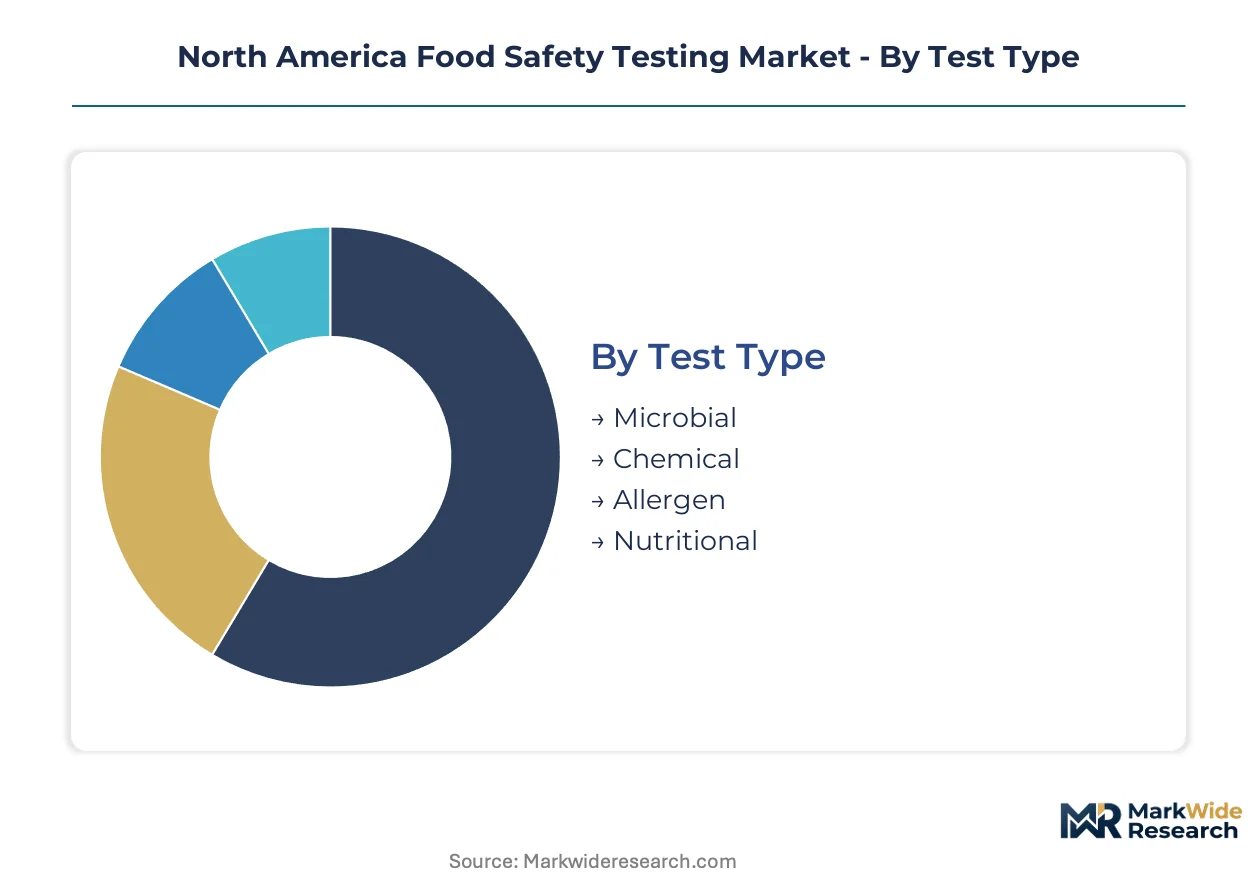
Food safety testing demand fragments across multiple analytical dimensions that determine pricing power and service configuration. Test type and technology choices drive capital intensity, while end-user structure shapes contract duration and geographic coverage requirements.
Test Type:
Microbial screening faces the strongest substitution pressure as rapid molecular methods displace culture-based protocols that USDA FSIS still mandates for enforcement actions.
- Microbial:Detects pathogenic bacteria including Salmonella, Listeria monocytogenes, and E. coli O157:H7 through culture isolation or nucleic acid amplification. Meat processors across the US Midwest generate concentrated demand as USDA zero-tolerance standards force continuous lot verification before distribution release.
- Chemical:Quantifies pesticide residues, veterinary drug metabolites, and environmental contaminants against EPA and FDA maximum residue limits. Grain elevators and oilseed processors in the Dakotas and Kansas anchor regional laboratory capacity for mycotoxin and herbicide screening.
- Allergen:Verifies absence of undeclared proteins including peanuts, tree nuts, milk, eggs, wheat, soy, fish, and shellfish through ELISA or lateral flow devices. Bakery and confectionery operations deploy these tests to prevent cross-contact incidents that trigger FDA Class I recalls.
- Nutritional:Determines macronutrient profiles, vitamin content, and mineral composition for label compliance and fortification verification. Contract laboratories serving packaged food manufacturers perform these analyses to substantiate nutrient content claims.
Microbial testing anchors the volume base while allergen screening gains share at the steepest rate as undeclared allergen recalls outpace pathogen events in FDA enforcement data.
End User:
Procurement consolidation among multi-facility operators is compressing vendor counts and favoring service providers with unified data platforms.
- Food Manufacturers:Protein processors, dairy cooperatives, and grain millers maintain internal quality laboratories or outsource to contract service providers. FSMA preventive controls mandate documented verification testing that expands external laboratory relationships.
- Retailers:Supermarket chains and foodservice distributors perform incoming inspection testing or audit supplier certificates of analysis. Private label program growth drives investment in supplier verification systems.
- Laboratories:Third-party analytical service providers including Eurofins Scientific and Bureau Veritas perform pathogen screening, chemical residue quantification, and audit services for processor clients. These entities capture expanding share as in-house quality departments face microbiologist recruitment constraints.
- Government Agencies:FDA field laboratories, USDA FSIS service labs, and state agriculture departments conduct surveillance sampling, outbreak investigation, and regulatory compliance verification. Federal whole-genome sequencing initiatives expand genomic characterization demand beyond routine pathogen detection.
Laboratories command the steepest expansion trajectory while government agencies maintain the most stable contract structures despite budget cycle volatility.
Technology:
Platform selection determines detection sensitivity, turnaround time, and capital requirements that stratify laboratory competitive positioning.
- PCR:Polymerase chain reaction amplifies target DNA sequences to detect pathogens at single colony-forming unit thresholds within hours. High-throughput thermal cyclers anchor centralized laboratory capacity for protein processors requiring same-shift release decisions.
- ELISA:Enzyme-linked immunosorbent assays use antibody-antigen binding for allergen and toxin detection with moderate sensitivity and lower equipment costs. Grain elevators and smaller processors deploy these systems for mycotoxin screening where rapid turnaround outweighs genomic specificity.
- Chromatography:Liquid and gas chromatography coupled with mass spectrometry separates and identifies chemical residues at parts-per-billion detection limits. Multi-residue pesticide panels and veterinary drug verification rely on these capital-intensive platforms concentrated in metropolitan laboratory hubs.
- Rapid Testing:Lateral flow immunoassays and isothermal amplification devices compress analytical turnaround from days to hours without thermal cycling equipment. Mid-size protein processors in the Great Plains adopt point-of-production formats to eliminate sample transport delays.
PCR anchors the revenue base while rapid testing formats expand most quickly as processors seek production-line integration and real-time release capability.
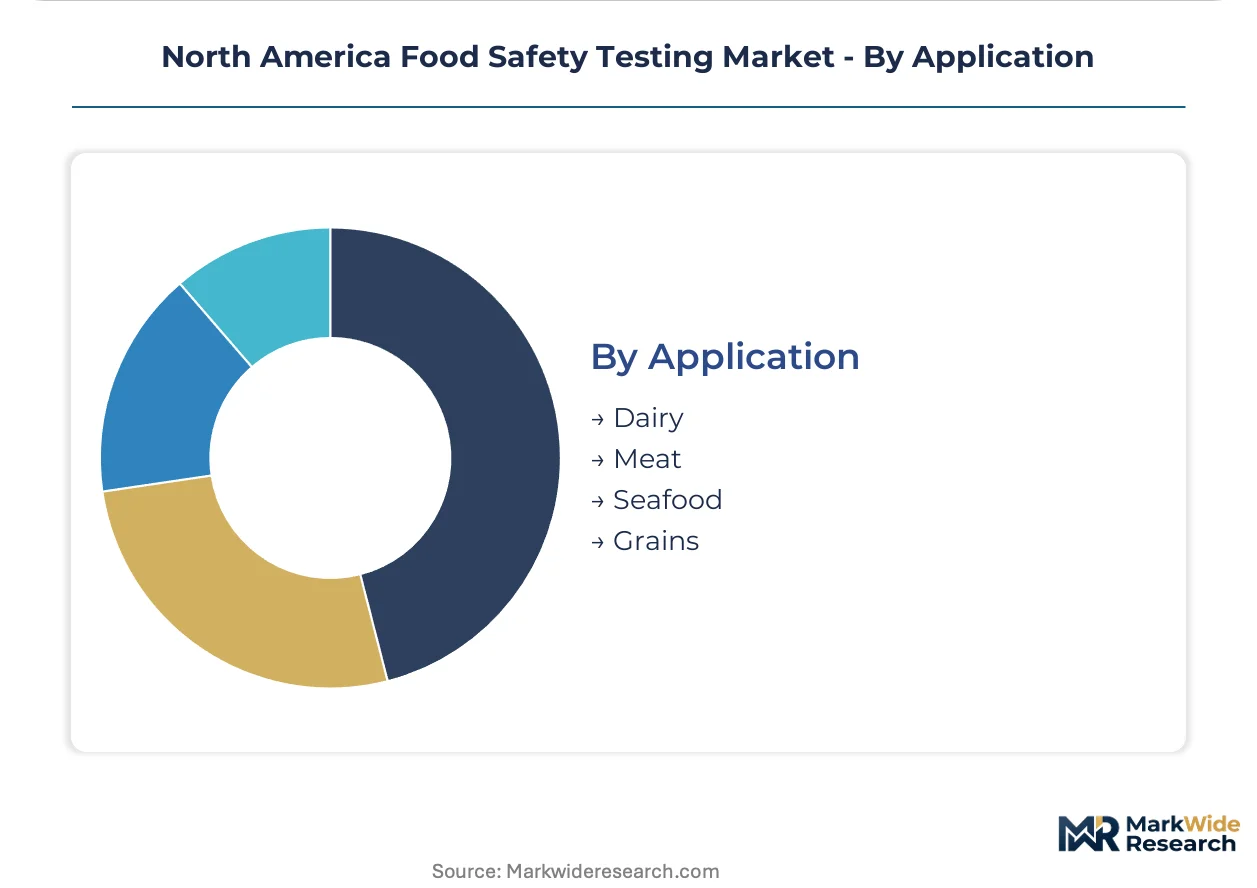
Application:
Regulatory stringency and perishability combine to concentrate margin pools in categories with the most intensive pathogen monitoring requirements.
- Dairy:Fluid milk, cheese, and yogurt operations face FDA Grade A standards and state regulatory programs that mandate somatic cell counts, antibiotic residue screening, and pathogen verification. Large cooperatives in Wisconsin and California generate sustained laboratory volume.
- Meat:Beef, pork, and poultry slaughter and further processing operations operate under USDA FSIS inspection with zero-tolerance standards for Salmonella and Listeria in ready-to-eat products. Midwest packing plants drive regional pathogen screening demand.
- Seafood:Finfish and shellfish processors confront FDA Hazard Analysis Critical Control Point regulations and state shellfish sanitation programs. Import verification requirements for aquaculture products expand contract laboratory relationships.
- Grains:Wheat, corn, and soybean handling facilities perform mycotoxin screening and genetically modified organism detection for domestic and export markets. Elevator networks across the Plains states anchor regional analytical capacity.
Meat applications command the largest revenue share while dairy testing climbs fastest as fluid milk processors confront enhanced FDA traceability deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports agricultural commodities and processed foods to United States buyers, creating cross-border testing demand that laboratories with dual accreditation capture. Mexico ships fresh produce and protein products northward, requiring verification protocols that satisfy both domestic COFEPRIS standards and US FDA import requirements.
United States
The US Midwest agricultural belt concentrates meat and grain processing operations that generate sustained pathogen screening volume. FDA FSMA preventive controls mandate documented hazard analysis and verified corrective actions, expanding third-party laboratory contracts. Wisconsin and California dairy cooperatives anchor regional analytical capacity for fluid milk and cheese verification.
Canada
Health Canada's Safe Food for Canadians Regulations create parallel compliance obligations that favor laboratories with cross-border accreditation. Prairie grain elevators in Alberta and Saskatchewan perform mycotoxin screening for export markets. Toronto and Vancouver metropolitan areas concentrate multi-service testing providers serving protein processors and import verification programs.
Mexico
COFEPRIS regulatory modernization aligns with US FDA frameworks for fresh produce and seafood exports to American markets. Jalisco and Sinaloa agricultural clusters drive demand for pesticide residue and microbiological verification. Mexico City metropolitan laboratories serve domestic processors while border-state facilities specialize in US-bound export certification.
North America Food Safety Testing Market Competitive Landscape
Player mix skews toward diversified testing conglomerates with multi-jurisdictional accreditation capabilities. Market structure concentrates among ten to twelve service providers with North American laboratory networks. Two strategic archetypes dominate: integrated multi-service providers bundling analytical work with audit and certification, and specialized pathogen screening laboratories focused on protein processors. Competitive moves center on procurement consolidation wins from national meatpacking operations and point-of-production technology partnerships with mid-size processors.
Within the integrated multi-service tier, SGS SA, Bureau Veritas, and Intertek Group PLC exemplify providers that extend beyond analytical results into supply chain verification and unified compliance documentation. These entities occupy positions where national meatpacking operations seek consolidated vendor relationships across multiple facility locations. Eurofins Scientific represents the high-throughput screening archetype, anchoring capacity expansion in protein processing clusters where same-shift release decisions command premium positioning.
| Leading Market Players |
|---|
| SGS SA |
| Eurofins Scientific |
| Bureau Veritas |
| Intertek Group PLC |
| ALS Limited |
| Mérieux NutriSciences |
| NSF International |
| Neogen Corporation |
| Laboratory Corporation of America Holdings |
| Others |
Value Network & Pricing Analysis
High-throughput thermal cycler capacity utilization in US Midwest laboratory clusters anchors regional price floors, as fixed-cost amortization across large pathogen screening volumes enables aggressive per-test pricing that smaller metropolitan facilities cannot match. This scale concentration compresses margins for mid-size processors seeking same-shift release decisions while reinforcing the procurement consolidation trend toward national contract laboratory networks.
Pricing Analysis
Prior-generation culture-based protocols command commodity pricing as USDA FSIS enforcement requirements sustain parallel workflow demand, while current-generation PCR thermal cyclers capture premium positioning through single colony-forming unit detection thresholds. Next-generation LAMP and isothermal amplification devices are compressing price points through point-of-production deployment that eliminates sample transport logistics. Pricing stratifies across rapid-turnaround premium tiers, standard overnight batch processing, and economy deferred-schedule options. Cost compression in the economy tier is intensifying because reference material supply volatility from limited domestic producers squeezes laboratory margin structures. Mid-size protein processors in the Great Plains exhibit the highest price sensitivity, while national meatpacking operations prioritize unified compliance documentation over per-test cost minimization.
Supply Chain Analysis
The United States anchors high-throughput sequencing and mass spectrometry platform manufacturing, while Germany and Japan supply precision thermal cycling and chromatography components that feed North American laboratory buildouts. Certified pathogen strains and control standards draw from limited domestic producers, creating single-source vulnerability for reference materials that laboratories cannot easily substitute. Distribution runs through metropolitan laboratory hubs that concentrate equipment servicing and technical support, leaving remote processors dependent on sample logistics networks for timely analytical confirmation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract testing laboratories face substitution pressure from point-of-production diagnostic platforms that compress analytical service chains, requiring incumbents to defend integrated service bundling against technology disintermediation.
For Market Incumbents: Fortify multi-service positioning by deepening audit and certification integration with pathogen screening results, creating switching costs that standalone analytical competitors cannot replicate. Expand cross-border accreditation capacity to capture Canadian regulatory alignment demand under Health Canada's Safe Food for Canadians Regulations. Priority investment in automated data capture infrastructure addresses FDA traceability mandates that processors must satisfy within compressed compliance deadlines. For New Entrants and Emerging Players: Differentiate on rapid-turnaround specialization for mid-size dairy cooperatives confronting enhanced FDA traceability requirements, a segment where procurement consolidation has not yet concentrated vendor relationships. Target regional grain elevator networks across the Dakotas and Kansas for mycotoxin screening services, leveraging lower capital intensity ELISA platforms against metropolitan chromatography hubs. Go-to-market positioning as compliance documentation specialists rather than analytical-only providers unlocks multi-year service contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among laboratories with integrated audit and certification portfolios that extend contractual relationships beyond transactional testing volumes. Long-term viability hinges on genomic characterization service expansion as federal whole-genome sequencing initiatives reshape outbreak traceback expectations. Acquisition targets should demonstrate cross-border accreditation depth and point-of-production technology partnerships. The signal to watch is USDA FSIS protocol evolution that could accelerate molecular method substitution and displace culture-based workflow investments.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Production Technology Partnership | LAMP device deployment at Great Plains protein processors eliminates sample transport delays and anchors recurring consumable revenue. |
| Cross-Border Accreditation Expansion | Dual US-Canada laboratory certification captures Health Canada Safe Food for Canadians Regulations compliance demand. |
| Automated Data Capture Infrastructure | FDA New Era of Smarter Food Safety traceability mandates drive investment in laboratory information management system integration. |
| Genomic Characterization Service Buildout | Federal whole-genome sequencing initiatives expand testing scope beyond routine pathogen detection into outbreak traceback. |
| Multi-Service Provider Consolidation | National meatpacking operations seek unified compliance documentation across multiple facility locations. |
Research Methodology
Operator-level perspectives from laboratory operations directors, quality assurance managers at protein processing facilities, regulatory affairs specialists, and third-party certification auditors anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA FSMA guidance documents, USDA FSIS enforcement data, Health Canada regulatory filings, and state agriculture department surveillance reports. Bottom-up testing volume estimates across Midwest processing clusters triangulated against top-down market sizing from laboratory capacity expansion announcements.
Sensitivity analysis examined alternative adoption trajectories for rapid molecular methods and point-of-production diagnostic platforms across the projection horizon. Segmentation dimensions modeled include test type, end-user structure, technology platform, and application category, with additional granularity on regulatory jurisdiction clusters. CAGRs derived from weighted scenario outcomes reflecting equipment replacement cycles and compliance deadline timing. Industry-specific forecast inputs incorporated reference material supply constraints and microbiologist workforce availability trends.
Material uncertainties — regulatory protocol evolution, reference material supply disruptions, and point-of-production technology substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about FSMA enforcement consistency and USDA culture-based method persistence that regulatory shifts could revise. Recalibration cycles align with material shifts in federal sequencing initiative funding and cross-border accreditation harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market