
 Europe Amusement Parks Market | 2026-2036
Europe Amusement Parks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Amusement Parks Market Insights
The gap between immersive destination parks and seasonal fairground-style operators is realigning investment priorities across the continent. Europa-Park GmbH & Co Mack KG anchors its position through deep in-house manufacturing of custom coasters and themed hotels. Merlin Entertainments leverages its multi-brand portfolio to dominate mid-market family segments with standardized attraction formats. Puy du Fou differentiates through historical spectacle and live performance rather than mechanical rides.
Europe amusement parks are large-scale entertainment complexes combining mechanical rides, live shows, themed environments, and hospitality services, typically requiring between 50 and 500 hectares of developed land with daily visitor capacities ranging from 5,000 to 60,000 guests. These facilities generate revenue through admission tickets, in-park food and beverage, merchandise, and accommodation, serving primarily as leisure destinations for domestic and international tourists. Theme parks capture the dominant share of capital investment due to their high theming costs and extended visitor dwell times, while water parks represent the fastest-expanding park type as operators add second-gate aquatic facilities to extend seasonal operating calendars. Chain parks under centralized ownership concentrate margin pools through procurement scale and cross-promotional ticketing, whereas independent parks compete on localized theming and regional cultural narratives.
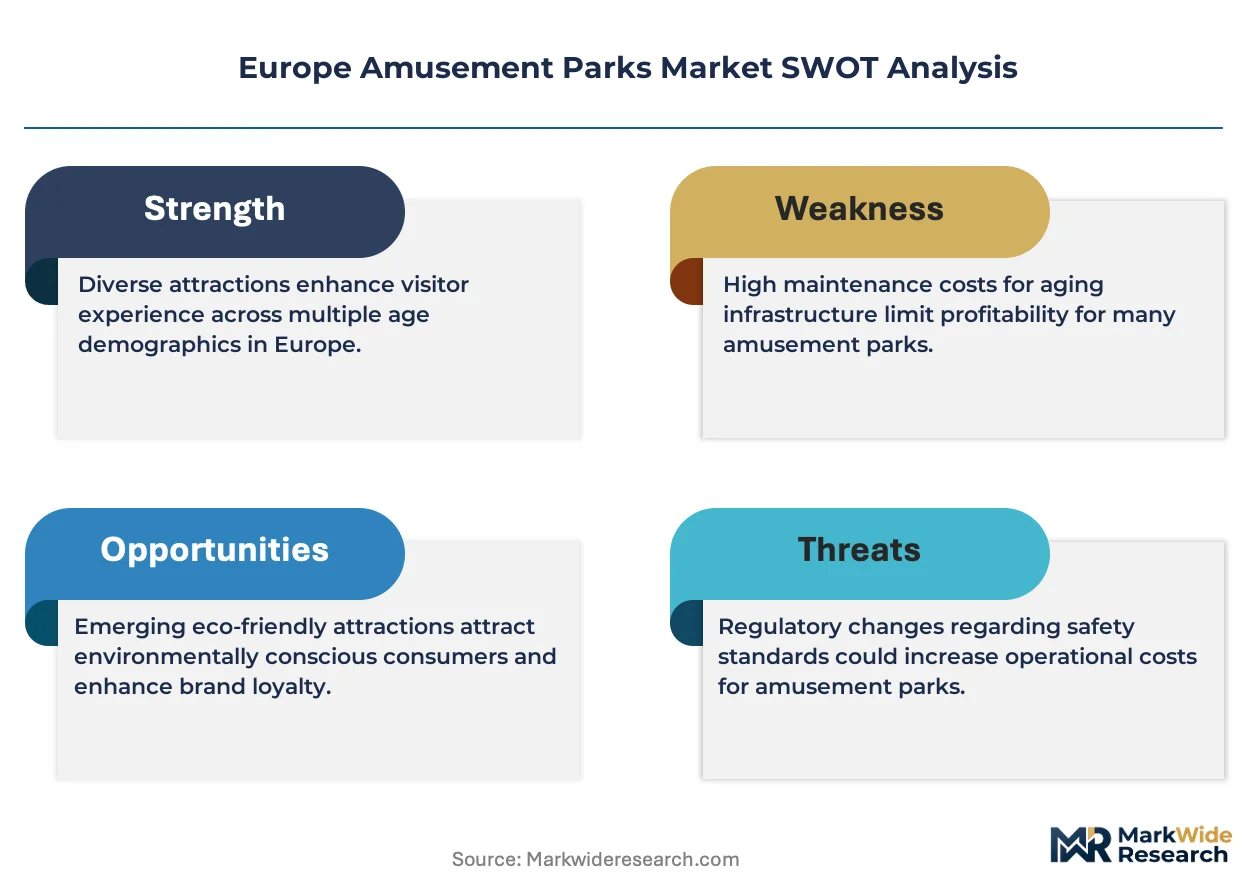
The EU Green Deal and national building codes in Germany, France, and Spain mandate energy audits and renewable integration for large leisure facilities, directly shaping capex planning for new attractions. CE marking requirements under the EU Machinery Directive govern ride safety certification and periodic inspection protocols, creating compliance barriers for non-European equipment suppliers. Operators must monitor evolving national minimum wage regulations and seasonal worker visa policies, as labor represents the largest variable cost in park operations. Stakeholders should track which park groups secure favorable renewable energy supply contracts, as electricity cost management is becoming a decisive competitive variable.
Market Dynamics
The EU Green Deal is compressing capex timelines for European amusement parks, forcing operators to front-load renewable energy infrastructure and carbon-neutral ride systems ahead of 2030 compliance deadlines. This regulatory pressure is redrawing competitive boundaries between capital-rich chains and independent seasonal operators.
Growth Catalysts
- Cross-border tourism concentration:Established park clusters in Germany, France, and Spain draw visitors from neighboring markets, extending effective catchment areas beyond domestic populations.
- EU Machinery Directive CE marking:Standardized safety certification protocols reduce regulatory friction for intra-European equipment trade, accelerating attraction deployment cycles.
- Second-gate water park expansion:Operators are adding aquatic facilities to extend seasonal operating calendars and capture incremental per-capita spending from existing visitors.
Market Restraints
- Electricity cost volatility:Grid-dependent parks face margin compression as renewable transition costs pass through to commercial tariffs before self-generation assets mature.
- Specialized ride manufacturing concentration:Custom coaster fabrication relies on a limited supplier base concentrated in Central Europe, creating bottlenecks for large-scale expansion projects.
- Seasonal labor visa constraints:National immigration policies in France and Germany restrict access to temporary hospitality workers during peak summer demand windows.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show developing middle-class leisure spending without established destination park infrastructure, offering first-mover positioning.
- EU renewable supply contract auctions:Parks securing long-term power purchase agreements gain cost predictability against volatile spot markets.
- Historical spectacle convergence:Live performance formats blending theatrical narrative with limited mechanical infrastructure reduce capex intensity while extending visitor dwell time.
Industry Challenges
- Attraction engineer scarcity:Specialized mechatronics talent for ride maintenance and safety inspection remains concentrated with legacy manufacturers rather than park operators.
- Building code compliance timelines:German and French national codes mandate extended permitting periods for new themed structures, delaying revenue realization on expansion investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Amusement Parks Market |
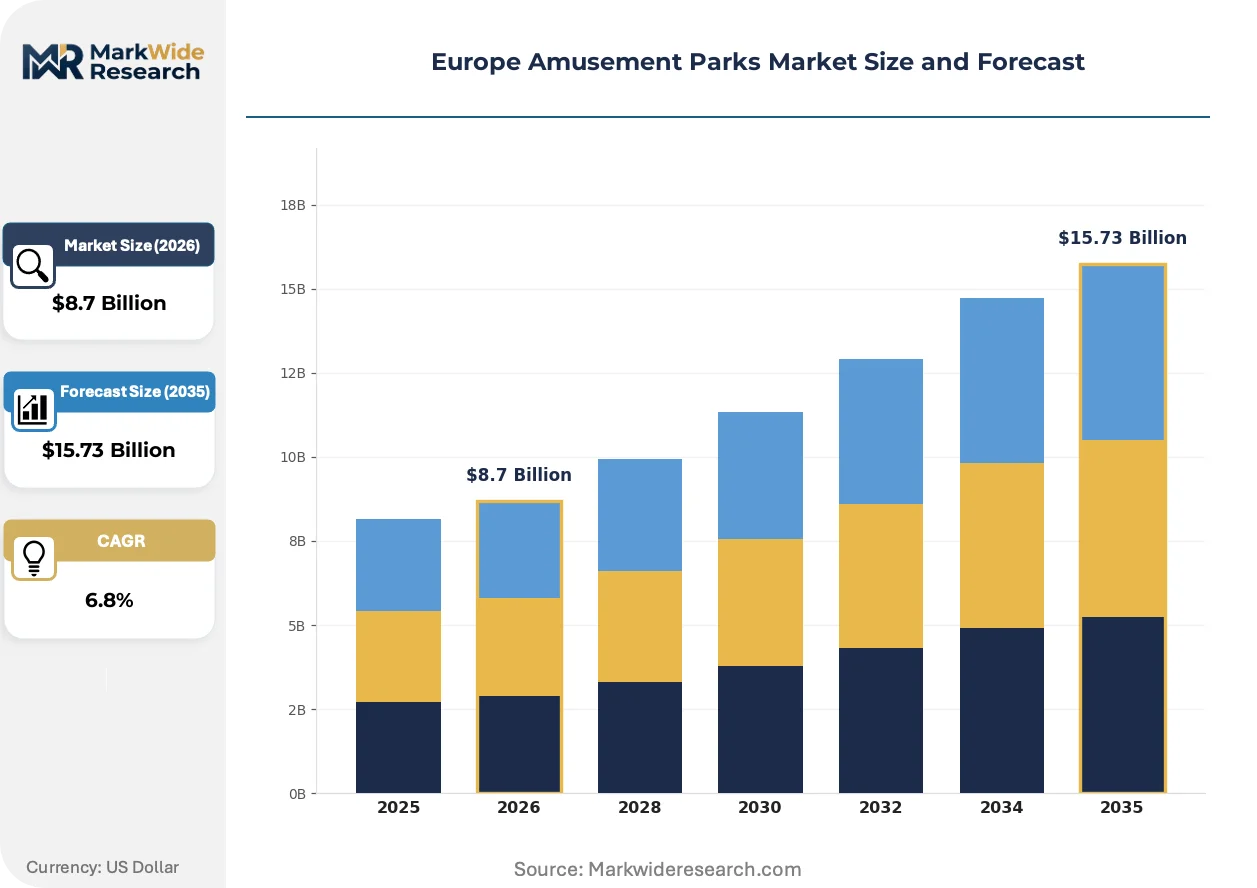
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Park Type: Theme Parks, Water Parks, Amusement Parks, Adventure Parks Target Audience: Families, Teens, Tourists, Young Adults Operating Model: Independent Parks, Franchise Parks, Chain Parks, Seasonal Parks Attraction Type: Rides, Shows, Exhibits, Games |
| Companies Covered | Europa-Park GmbH & Co Mack KG, Efteling, Merlin Entertainments, PortAventura World, Puy du Fou, Parques Reunidos, Looping Group, Aspro Parks, Compagnie des Alpes, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Amusement Parks Market Trends and Innovations
Immersive storytelling systems and energy infrastructure are rewriting the operational model for European parks, compressing the gap between mechanical thrill and environmental compliance.
Dark ride projection mapping and real-time media synchronization is rewriting how parks sequence visitor flow through narrative environments. Major destination operators in France and Germany are retrofitting legacy attractions with spatial audio and responsive LED surfaces. This convergence of theatrical technology and ride hardware is enabling higher throughput per square meter while reducing physical set construction costs.
France's national building codes and Germany's KBA safety protocols are tightening inspection intervals for steel coaster structures, accelerating predictive maintenance adoption. Operators must now integrate continuous structural monitoring sensors to satisfy reduced recertification cycles. The hardware retrofit burden falls heaviest on independent parks with aging steel inventories, forcing capital allocation trade-offs against new attraction development.
Visitor booking behavior is fragmenting across direct-to-consumer apps and experience bundling platforms, disintermediating traditional travel agency channels. German and Spanish parks report rising share of short-fuse mobile purchases within 48 hours of visit. This compression of planning horizons is forcing revenue management teams to abandon static seasonal pricing for dynamic yield optimization.
Europe Amusement Parks Market Segmentation
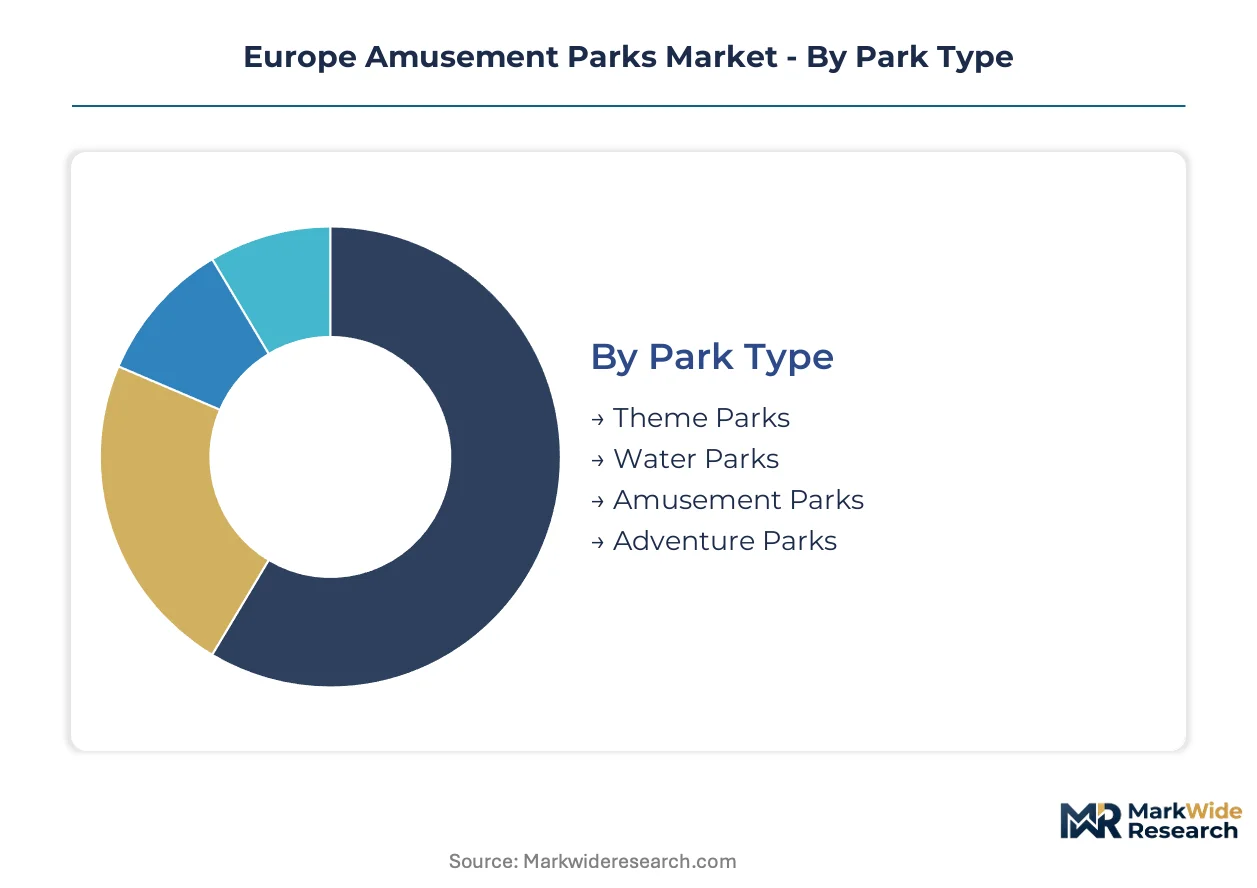
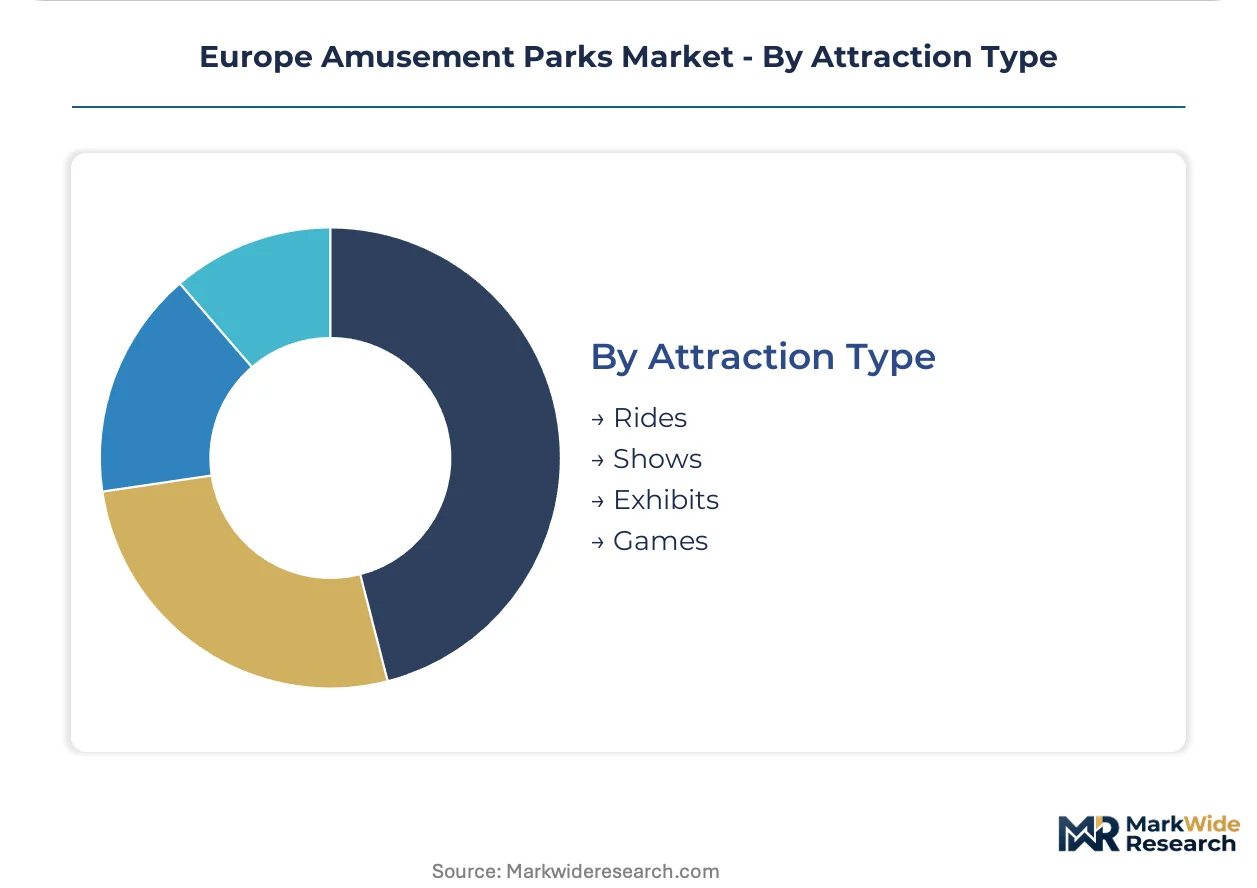
Segmentation in the Europe amusement parks market reveals how capital deployment, visitor behavior, and regulatory exposure vary across operational models. Operators configure their attraction mix and energy infrastructure differently depending on which segments they target.
Park Type:
Standalone destination complexes operate as embedded leisure ecosystems, while seasonal fairgrounds function as standalone entertainment without hospitality integration.
- Theme Parks:These facilities combine immersive theming with on-site hotels and extended dwell-time programming. German and French operators dominate this segment, driven by cross-border tourism flows and EU Green Deal compliance investments in renewable energy systems.
- Water Parks:Aquatic facilities extend seasonal calendars and capture incremental per-capita spending. Spain's Mediterranean climate supports year-round operations, though most European water parks operate as second-gate additions to existing destination complexes rather than standalone investments.
- Amusement Parks:Traditional ride-based parks with limited theming serve regional catchments through mechanical attraction density. These facilities face margin pressure from electricity cost volatility and aging steel coaster maintenance burdens.
- Adventure Parks:Rope courses, zip lines, and nature-based activities occupy forested terrain with lower capex intensity. Polish and Romanian operators are developing this format to serve emerging middle-class leisure demand without major infrastructure requirements.
Theme parks lead volumes today; water parks are gaining share fastest.
Target Audience:
Visitor composition determines pricing architecture, merchandise strategy, and seasonal staffing models across European facilities.
- Families:Multi-generational groups generate the highest per-capita spending through accommodation, dining, and souvenir purchases. Merlin Entertainments targets this segment with standardized mid-market formats across its UK, German, and French properties.
- Tourists:International visitors extend effective catchment areas beyond domestic populations and tolerate premium pricing. Europa-Park in Germany and Puy du Fou in France compete aggressively for this high-yield segment through multilingual programming.
- Teens:Thrill-seeking adolescents drive repeat visitation through social media amplification and seasonal pass sales. Parks configure coaster density and queue entertainment specifically for this demographic's attention patterns.
- Young Adults:Adult couples and friend groups without children concentrate spending on food and beverage and evening events. This segment shows highest sensitivity to dynamic pricing and last-minute mobile booking channels.
Families dominate revenue contribution today; young adults are expanding fastest through experience-bundling platforms.
Operating Model:
Ownership structure shapes procurement scale, compliance burden distribution, and capital access for energy transition investments.
- Chain Parks:Centralized ownership concentrates margin pools through group purchasing and cross-promotional ticketing. These operators front-load renewable infrastructure investments to satisfy EU Green Deal timelines across multiple properties.
- Independent Parks:Family-owned or single-site operators compete on localized theming and regional cultural narratives. German and French independents struggle with predictive maintenance sensor retrofits for aging steel coasters under tightened KBA inspection protocols.
- Franchise Parks:Licensed formats from international brands operate with standardized attraction packages and operational procedures. This model accelerates deployment in Eastern European markets lacking indigenous park development expertise.
- Seasonal Parks:Fairground-style operators with temporary infrastructure and limited fixed costs. These facilities face acute labor constraints from French and German seasonal visa restrictions during peak summer demand windows.
Chain parks command investment capacity today; independent parks are consolidating fastest through acquisition.
Attraction Type:
The mix of mechanical, theatrical, and interactive programming determines capex intensity and energy consumption profiles.
- Rides:Steel and wooden coasters, flat rides, and transport systems consume the largest share of maintenance budgets and electricity loads. CE marking requirements under the EU Machinery Directive govern safety certification and create compliance barriers for non-European equipment suppliers.
- Shows:Live performance and theatrical spectacle reduce physical infrastructure requirements while extending visitor dwell time. Puy du Fou has built competitive differentiation entirely through historical reenactment formats without major mechanical ride investment.
- Exhibits:Walk-through environments and educational displays serve school groups and family segments during off-peak periods. These attractions carry lower energy intensity and staffing requirements than operational rides.
- Games:Carnival-style skill and chance attractions generate high-margin incremental revenue with minimal fixed asset deployment. Digital payment integration is transforming this segment's yield management capabilities.
Rides absorb the largest capital allocation today; shows are climbing fastest as operators reduce energy exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ride engineers and theatrical talent concentrate in Germany's Rust region and France's western Loire Valley, anchoring the continent's highest-capacity destination park clusters. These workforce pools draw cross-border visitors from neighboring markets while supplying technical expertise for EU Green Deal compliance projects.
Germany
Family-oriented domestic demand and Dutch cross-border tourism sustain year-round operations at major complexes. KBA safety protocols mandate predictive maintenance sensors on steel coaster structures, tightening compliance timelines for aging ride inventories. The Rust-Europa-Park cluster anchors manufacturing integration through in-house coaster fabrication and themed hotel development.
France
Historical spectacle formats and live performance programming attract international visitors seeking narrative immersion over mechanical thrill. National building codes extend permitting timelines for new themed structures, delaying revenue realization on expansion investments. The Puy du Fou concentration in Les Epesses demonstrates viable differentiation through theatrical spectacle without major ride infrastructure.
Spain
Mediterranean climate conditions support extended water park operating calendars and second-gate aquatic facility economics. CE marking requirements under the EU Machinery Directive govern ride safety certification for equipment imports from non-European suppliers. The PortAventura cluster near Tarragona captures incremental per-capita spending through integrated resort hospitality.
United Kingdom
Mid-market family segments drive standardized attraction formats across multi-property portfolios. Seasonal labor visa constraints restrict access to temporary hospitality workers during peak summer demand windows. The Merlin Entertainments concentration across Staffordshire and Windsor leverages group purchasing scale for procurement efficiency.
Poland
Emerging middle-class leisure spending outpaces established destination park infrastructure in Warsaw and Kraków catchments. EU renewable supply contract auctions offer cost predictability for operators securing long-term power purchase agreements. Adventure park formats occupy forested terrain with lower capex intensity than mechanical ride investments.
Europe Amusement Parks Market Competitive Landscape
Top-tier vendors anchor destination resort complexes with integrated hospitality, while mid-market operators compete through standardized formats and seasonal fairgrounds survive on temporary infrastructure. The vendor base stratifies across three strategic archetypes: manufacturing-integrated destination developers, multi-brand portfolio operators, and performance-centric theatrical specialists. Competitive moves concentrate on renewable energy infrastructure front-loading and second-gate water park additions to extend operating calendars.
Among German manufacturing-integrated developers, Europa-Park GmbH & Co Mack KG anchors the premium tier through captive coaster production capabilities. Merlin Entertainments occupies a position exemplifying multi-brand portfolio scale across UK, German, and French properties. Puy du Fou represents the theatrical specialist archetype, demonstrating viable market positioning through historical spectacle formats without major mechanical ride capital deployment.
| Leading Market Players |
|---|
| Europa-Park GmbH & Co Mack KG |
| Efteling |
| Merlin Entertainments |
| PortAventura World |
| Puy du Fou |
| Parques Reunidos |
| Looping Group |
| Aspro Parks |
| Compagnie des Alpes |
| Others |
Pricing and Supply Chain Analysis
Captive in-house manufacturing of custom coasters at German destination parks anchors both supply security and premium pricing power against independent operators dependent on external fabrication. This backward integration insulates integrated developers from supplier bottlenecks while enabling bundled resort pricing that independents cannot match.
Pricing Analysis
Bundled admission-accommodation packages at destination parks command substantial premiums over unbundled day-ticket pricing at seasonal fairgrounds. Three-tier pricing structure across premium, standard, and economy levels segments visitors by dwell time and ancillary spend commitment. Pricing pressure stems from electricity cost volatility as renewable transition costs pass through to commercial tariffs before self-generation assets mature. Young adult visitor segments show highest price sensitivity through last-minute mobile booking channels, while international tourists tolerate premium positioning.
Supply Chain Analysis
Direct-to-park channels from specialized German and Swiss engineering firms handle custom coaster demand from major destination developers. Steel fabrication concentrates in Germany, Switzerland, and the Netherlands, with specialized welding and track-forming expertise tethered to legacy manufacturing clusters. Raw material dependencies include high-grade structural steel, precision bearings, and rare-earth magnetic components for launch systems. Single-source vulnerability runs through the limited base of certified ride engineers capable of CE marking compliance under the EU Machinery Directive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as visitor demand shifts toward immersive destination experiences with integrated hospitality over transactional day-visit formats. Premium specifications now center on renewable energy credentials and predictive maintenance transparency.
For Market Incumbents: Hedge against electricity cost volatility through long-term renewable supply contract auctions before spot market exposure hardens. Prioritize predictive maintenance sensor retrofits on aging steel coaster inventories to satisfy tightened KBA inspection protocols in Germany. Defensive consolidation of independent parks with distressed maintenance backlogs offers capacity expansion without greenfield permitting delays. For New Entrants and Emerging Players: The mid-market pricing gap between premium destination resorts and economy fairgrounds offers viable positioning for theatrical spectacle formats with limited mechanical infrastructure. Poland and Romania present the most penetrable geographies with developing middle-class leisure demand and underdeveloped destination park infrastructure. A go-to-market angle anchored in EU Green Deal compliance narratives attracts public co-financing for renewable energy integration. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale independent parks because fragmented ownership concentrates procurement inefficiencies and compliance cost burdens that centralized operations can eliminate. Acquisition targets should show established visitor bases with unrealized ancillary revenue potential through hospitality integration. The signal to watch is which park groups secure favorable renewable energy supply contracts, as electricity cost management is becoming a decisive competitive variable.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Infrastructure Investment | Front-loading solar and battery assets satisfies EU Green Deal compliance timelines ahead of 2030 deadlines. |
| Second-Gate Water Park Addition | Extends seasonal operating calendars and captures incremental per-capita spending from existing visitor bases. |
| Predictive Maintenance Technology Deployment | Continuous structural monitoring sensors satisfy tightened KBA and French national building code inspection cycles. |
| Historical Spectacle Format Development | Theatrical programming reduces capex intensity while extending dwell time without major mechanical ride investment. |
| Eastern European Geographic Expansion | Poland and Romania offer first-mover positioning in underpenetrated markets with emerging middle-class leisure demand. |
Research Methodology
Coverage spans Germany, France, Spain, the United Kingdom, and Poland, with primary inputs from each market cluster. The research combines structured interviews with park operations directors, ride maintenance engineers, hospitality revenue managers, and regulatory compliance officers with secondary validation from EU Machinery Directive filings, national building code databases, and renewable energy auction results. Bottom-up property-level capacity modeling and top-down regional tourism flow analysis provide cross-verification.
Granularity-level framing applies country-specific regulatory cluster modeling and park-type segmentation across theme parks, water parks, and adventure formats. CAGRs derive from visitor volume projections, per-capita spend trajectories, and energy cost scenario modeling across the analysis window. Industry-specific forecast inputs include cross-border tourism elasticity coefficients and seasonal labor visa policy sensitivity.
Caveats apply where electricity tariff restructuring or accelerated EU Green Deal enforcement could materially shift the outlook for capital-intensive expansion projects. Forecasts reflect assumptions about renewable energy cost curves and visitor preference stability that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Smart Tourism Market
Destination Management and Attractions
Thailand Sustainable Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Safari Tourism Market
Destination Management and Attractions
Alternative Tourism Market