
 Australia Adventure Tourism Market | 2026-2036
Australia Adventure Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Adventure Tourism Market Insights
Adventure guide certification capacity is rotating toward marine and alpine specializations as operators expand Great Barrier Reef and Tasmanian wilderness offerings. Intrepid Travel leverages its global small-group model to sustain year-round departures across the Red Centre and Kimberley. AAT Kings Tours Limited anchors premium coach-based adventure circuits through Uluru and Kakadu, while Ultimate Adventure Travel Pty Ltd competes on self-guided 4WD and multi-day hiking logistics.
Australia adventure tourism encompasses guided and independent travel experiences characterized by physical exertion, environmental immersion, and managed risk exposure across remote terrestrial and marine ecosystems, typically requiring specialized equipment, local permits, and accredited safety protocols. The sector serves both domestic experience-seekers and international visitors pursuing distinctive biogeographic encounters unavailable in their home markets. Hiking and surfing activity types dominate booking volumes due to low barrier-to-entry and established infrastructure along the east and west coasts, though rock climbing is gaining traction as crag development accelerates in the Grampians and Blue Mountains. Solo travelers and eco-tourists represent the fastest-expanding tourism segments, with operators repositioning inventory toward low-impact, education-intensive itineraries that command extended length-of-stay.
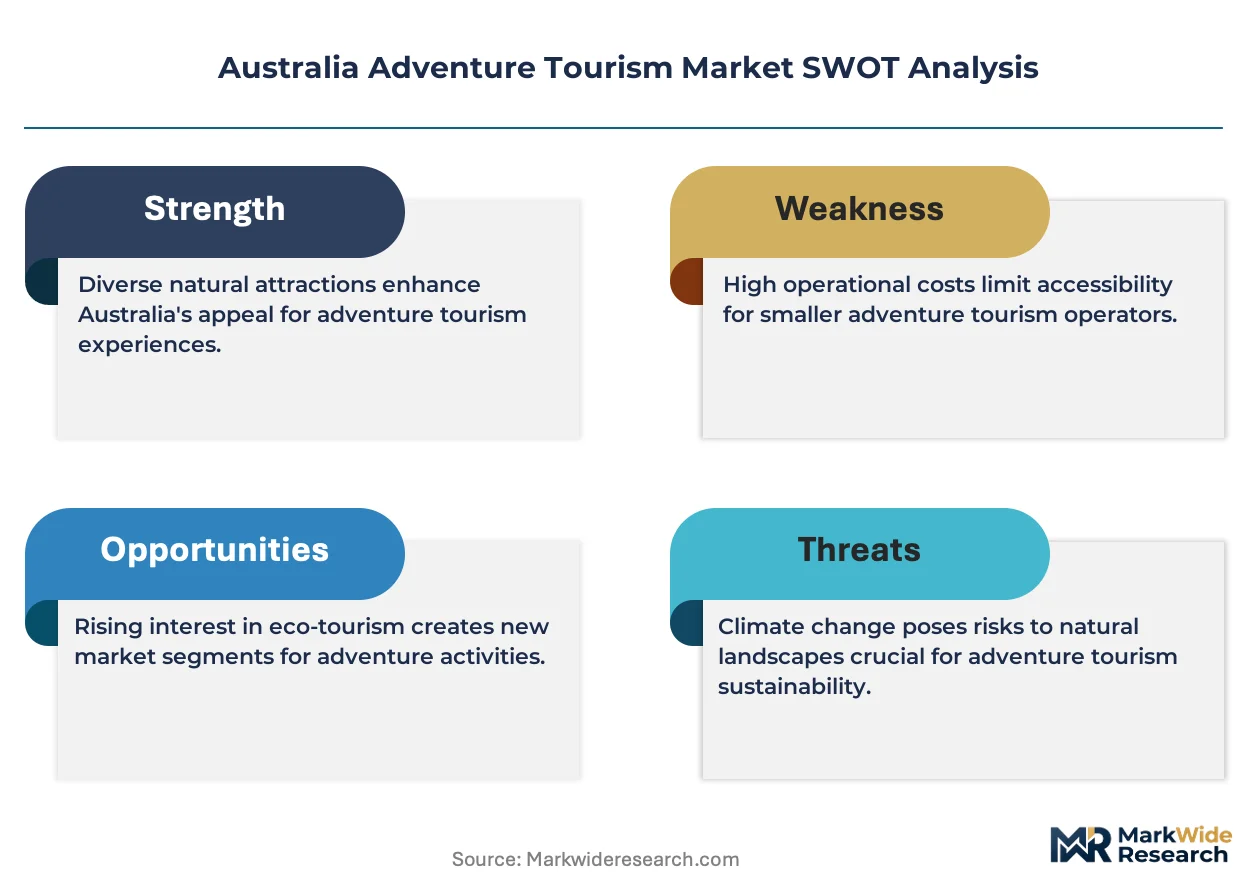
TGA oversight of remote-area medical evacuation standards combines with state tourism accreditation bodies and Parks Australia permit systems to shape operator compliance costs and market access thresholds across protected areas. These regulatory layers favor established players with in-house risk management and indigenous partnership frameworks over new entrants lacking operational track records. Stakeholders must weigh capital allocation between infrastructure-heavy permanent campsites and flexible guided-tour models as climate variability and seasonal access restrictions reshape route viability.
Market Dynamics
Domestic millennial and Gen Z travelers are compressing booking windows and demanding modular expedition packages that blend physical activity with environmental education, forcing operators to reconfigure inventory around shorter, higher-frequency departures rather than traditional fortnight-long circuits.
Growth Catalysts
- Queensland coastal clustering:Dense reef and rainforest proximity enables multi-activity itineraries that extend length-of-stay and repeat visitation rates above national averages.
- TGA remote-area medical standards:Accreditation frameworks that mandate satellite communication and evacuation protocols are professionalizing operator safety infrastructure and reducing incident liability exposure.
- Guided outback expedition formats:Small-group logistics with indigenous partnership frameworks unlock access to restricted Aboriginal lands and create premium pricing power through exclusivity.
Market Restraints
- Fuel cost volatility:Remote-area operations depend on diesel transport and aircraft charter, exposing margins to energy price swings that cannot be fully passed to price-sensitive domestic segments.
- Western Australia supply concentration:Kimberley and Pilbara infrastructure is controlled by a limited pool of licensed aircraft operators and permanent camp leaseholders, creating bottleneck risk during peak dry-season demand windows.
- Parks Australia permit scarcity:Strict caps on commercial activity in Uluru-Kata Tjuta and Kakadu restrict route expansion and concentrate revenue among incumbent holders with grandfathered access rights.
Strategic Opportunities
- Tasmanian alpine wilderness:Crag development and hut-to-hut trail networks remain underdeveloped relative to mainland coastal offerings, presenting first-mover positioning for multi-day hiking specialists.
- State tourism accreditation harmonization:Convergence of Queensland and Western Australia safety protocols could reduce compliance duplication and enable cross-border operator licensing.
- Self-guided 4WD logistics platforms:Vehicle-tracking telemetry and remote concierge services are opening independent travel segments previously captured only by guided tour inventory.
Industry Challenges
- Marine and alpine guide certification pipelines:TGA and state tourism bodies are rotating accreditation capacity toward specialized competencies faster than training institutions can supply qualified instructors.
- Permanent campsite capital intensity:Climate variability and seasonal access restrictions are forcing operators to weigh infrastructure commitments against flexible guided-tour models with lower fixed-cost exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Adventure Tourism Market |
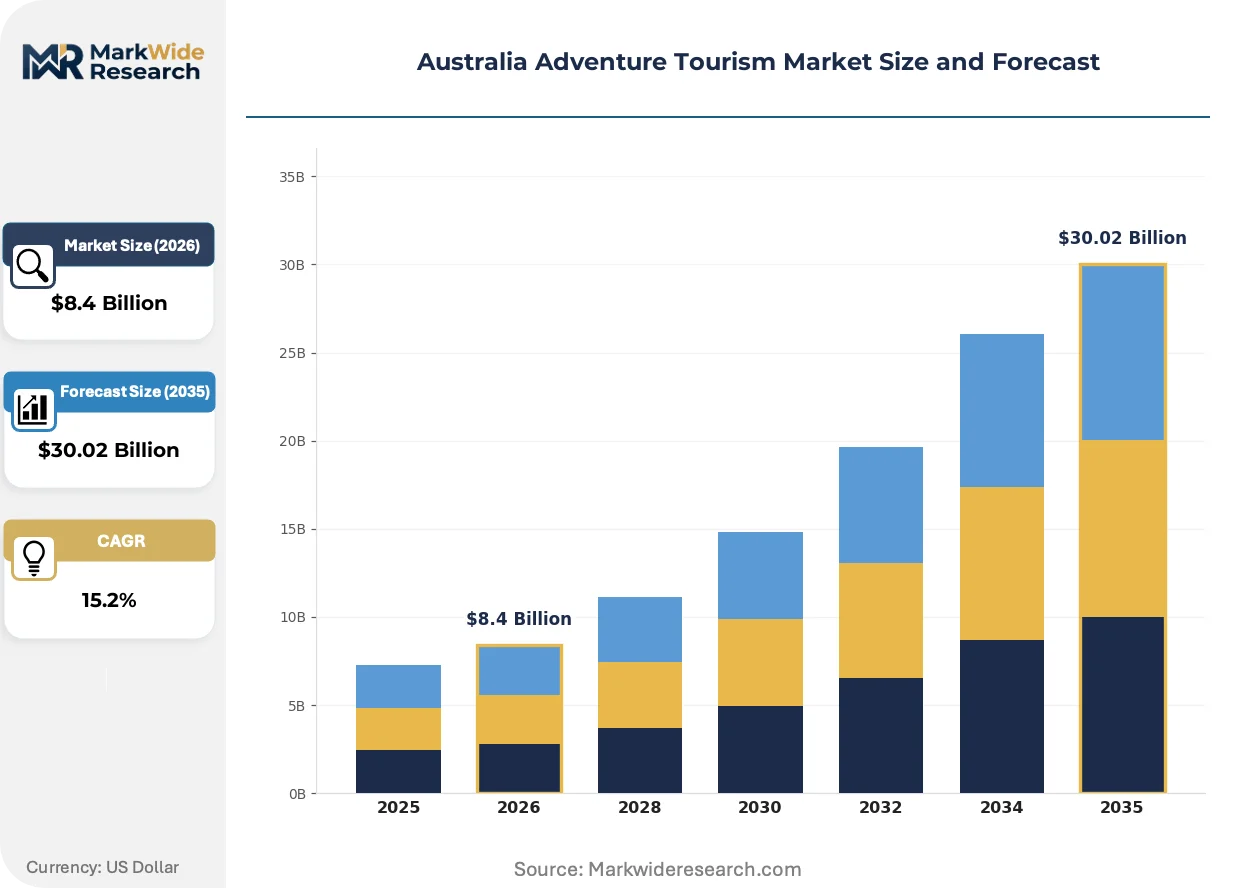
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Activity Type: Hiking, Rock Climbing, Surfing, Kayaking Tourism Segment: Solo Travelers, Family Groups, Adventure Seekers, Eco-Tourists Season: Summer, Winter, Spring, Autumn Service Type: Guided Tours, Self-Guided Adventures, Equipment Rentals, Campsite Services |
| Companies Covered | AAT Kings Tours Limited, Intrepid Travel, G Adventures, Contiki, Discovery Nomads, Trafalgar Travel, Insight Vacations, Intrepid Group Ltd, Ultimate Adventure Travel Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Adventure Tourism Market Trends and Innovations
Real-time environmental monitoring and modular booking platforms are compressing traditional expedition planning cycles and enabling dynamic itinerary adjustments based on weather, wildlife, and crowd conditions.
Biometric wearable integration is supplanting manual check-in protocols for remote-area safety compliance. Premium operators in Queensland's reef zones and Tasmania's Overland Track are deploying satellite-linked health monitors that transmit vital signs to base camps, reducing evacuation response times from hours to minutes and compressing insurance premiums for high-risk activities.
TGA oversight of remote-area medical evacuation standards is tightening liability frameworks for operators accessing terrain beyond conventional rescue infrastructure. The regulation mandates specific equipment configurations and communication redundancy, elevating compliance costs most acutely for small independent guides in Western Australia's Kimberley region who lack in-house risk management departments.
Domestic travelers are fragmenting booking channels away from traditional wholesale tour operators toward direct-to-consumer platforms and peer-to-peer recommendation engines. This disintermediation is compressing commission structures and forcing established operators to rebuild customer acquisition capabilities, with the shift most visible among solo travelers and eco-tourist segments in New South Wales and Victoria.
Australia Adventure Tourism Market Segmentation
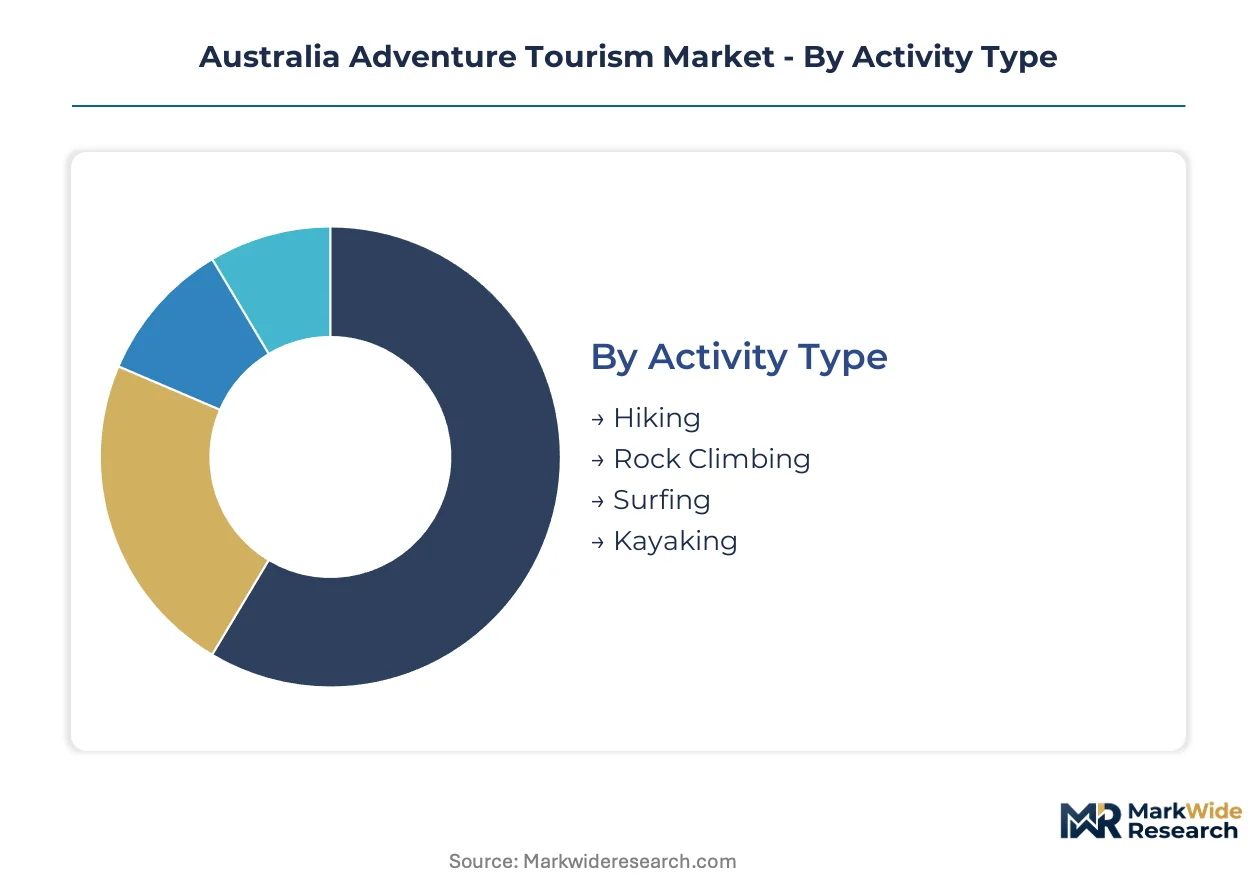
Segmentation in Australian adventure tourism reveals how distinct traveler profiles and activity formats concentrate demand across Queensland's reef zones and Western Australia's desert circuits. Operators calibrate inventory, staffing, and permit applications against these divides to optimize yield per departure.
Activity Type:
Channel distribution varies sharply by physical intensity and equipment requirements, with low-barrier activities flowing through direct-to-consumer platforms while technical specialties remain anchored in specialist outbound channels.
- Hiking:Multi-day trail networks across Tasmania's Overland Track and Queensland's Lamington Plateau drive the highest booking volumes through Parks Australia permit systems. Domestic millennials dominate reservations, compressing planning windows to under fourteen days.
- Surfing:Coastal infrastructure concentration along New South Wales' Byron Bay and Western Australia's Margaret River enables modular package construction blending lessons, board hire, and beachside accommodation. International visitors from North America and Europe sustain premium pricing during southern hemisphere winter.
- Rock Climbing:Grampians and Blue Mountains crag development is accelerating permit applications for commercial guiding.
- Kayaking:Reef and river variants in Queensland's Whitsunday Islands and Tasmania's Franklin River attract multi-day expedition bookings.
By volume, hiking leads. By growth pace, rock climbing is ahead.
Tourism Segment:
Customer acquisition costs and length-of-stay patterns diverge across these traveler profiles, with solo operators commanding premium per-night rates while family groups extend total trip duration through activity bundling.
- Solo Travelers:Digital-native booking behavior and modular itinerary preferences are compressing traditional wholesale tour operator margins. This segment exhibits the highest willingness-to-pay for exclusive access arrangements on restricted Aboriginal lands.
- Eco-Tourists:Education-intensive itineraries emphasizing biogeographic interpretation and low-impact protocols are extending length-of-stay in Tasmania's alpine wilderness and Queensland's Daintree rainforest. TGA accreditation requirements for environmental guide competency are tightening supply.
- Family Groups:Safety protocol sensitivity and activity gradation requirements dominate purchasing criteria.
- Adventure Seekers:Physical exertion thresholds and risk exposure preferences concentrate demand in Western Australia's Kimberley and Northern Territory's Red Centre.
Solo travelers generate highest revenue per departure. Eco-tourists are climbing the fastest.
Season:
Operational cost structures and route viability shift dramatically across the annual cycle, with dry-season concentration in northern Australia and alpine access windows in Tasmania creating distinct capital allocation pressures.
- Summer:Southern coastal surfing and Tasmanian alpine hiking peak simultaneously, straining guide certification pipelines and aircraft charter capacity across multiple jurisdictions.
- Winter:Northern Australia dry-season access concentrates Kimberley and Kakadu departures into compressed demand windows, elevating pricing power for licensed operators with grandfathered permit holdings.
- Spring:Transitional shoulder season enables route diversification and equipment repositioning.
- Autumn:Moderate temperatures across southern states sustain hiking and rock climbing volumes before alpine closures.
Winter commands peak pricing. Summer delivers highest absolute volume.
Service Type:
Capital intensity and margin structure differentiate these delivery formats, with permanent infrastructure commitments contrasting against flexible human-capital-dependent guided models.
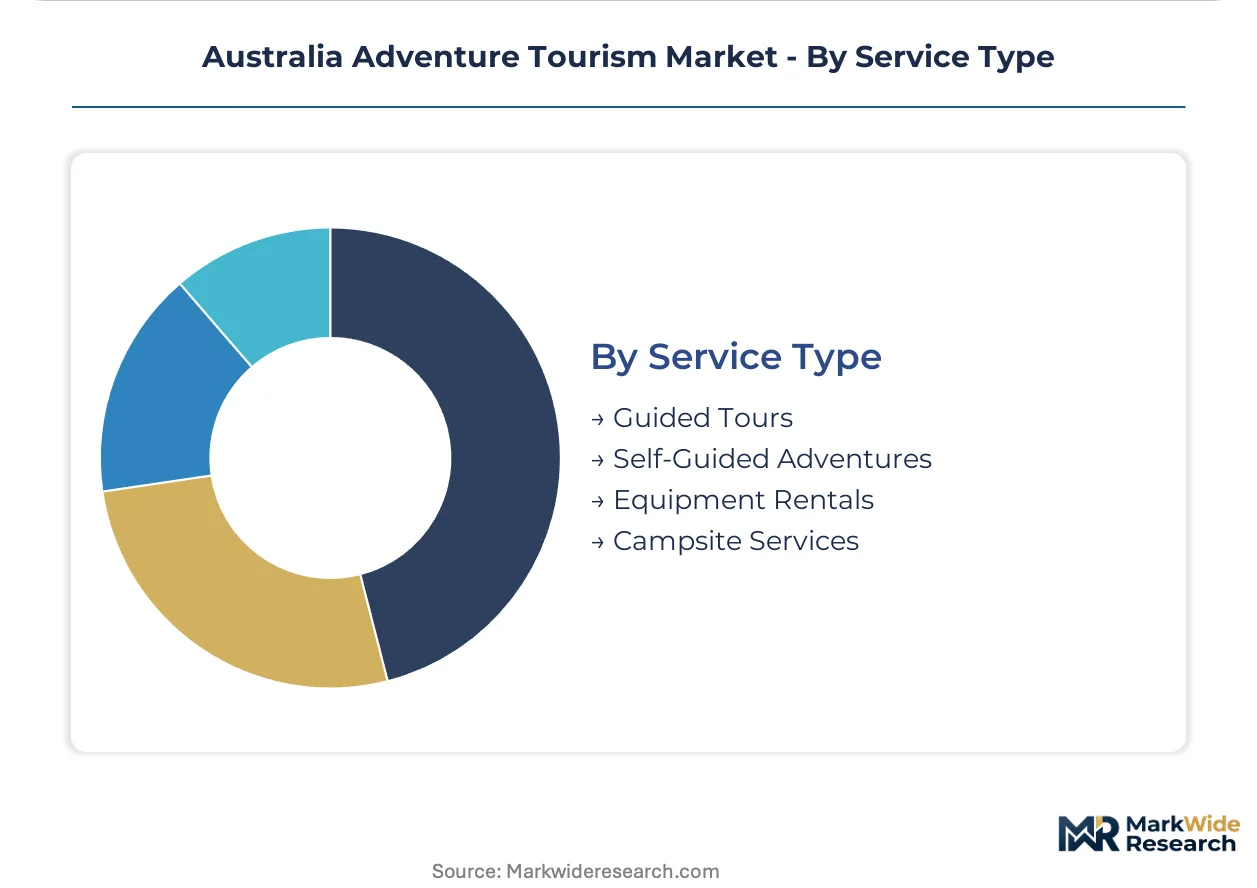
- Guided Tours:Small-group logistics with indigenous partnership frameworks unlock restricted land access and sustain premium positioning. TGA remote-area medical evacuation standards mandate satellite communication redundancy and specialized equipment configurations.
- Self-Guided Adventures:Vehicle-tracking telemetry and remote concierge services are displacing traditional guided inventory in Western Australia's Pilbara and Queensland's Cape York. Domestic Gen Z travelers drive adoption through peer-to-peer recommendation engines.
- Equipment Rentals:Surfboard and kayak hire along established coastal infrastructure generates recurring revenue with lower fixed-cost exposure.
- Campsite Services:Permanent facility commitments in national parks face climate variability and seasonal access restriction risks.
Guided tours retain highest margin per customer. Self-guided adventures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA accreditation frameworks and Parks Australia permit systems anchor operational requirements across Queensland and Western Australia, where coastal reef clusters and desert circuits generate the highest repeat visitation rates and premium pricing power.
Queensland
Great Barrier Reef diving packages and Daintree rainforest expeditions concentrate demand in Cairns and Port Douglas. Queensland state tourism accreditation mandates satellite communication redundancy for remote-area operators. The Whitsunday Islands marine cluster draws multi-day kayaking and sailing bookings through integrated reef access permits.
Western Australia
Kimberley dry-season departures and Pilbara 4WD circuits compress demand into narrow annual windows. Western Australia's Department of Biodiversity, Conservation and Attractions administers commercial activity permits with strict caps on group sizes. Broome and Kununurra serve as logistics hubs for licensed aircraft operators and permanent camp leaseholders.
New South Wales
Byron Bay surfing infrastructure and Blue Mountains rock climbing crags attract domestic millennial bookings through direct-to-consumer platforms. NSW National Parks and Wildlife Service regulates commercial guiding permits with environmental impact assessments. The Grampians climbing development is accelerating permit applications for technical expedition formats.
Victoria
Tasmanian alpine wilderness access and Victorian coastal hiking sustain year-round departure volumes. Parks Victoria manages permit scarcity through competitive allocation rounds for commercial operators. Melbourne serves as the primary gateway for Overland Track and Larapinta Trail logistics coordination.
South Australia
Flinders Ranges outback expeditions and Kangaroo Island eco-tourism extend length-of-stay for education-intensive itineraries. South Australian Tourism Commission accreditation frameworks emphasize indigenous partnership protocols. Adelaide-based operators coordinate multi-state circuits through cross-border licensing arrangements.
Australia Adventure Tourism Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium coach-based operators and small-group expedition specialists occupying distinct margin positions. The market structure reflects permit scarcity and indigenous land access agreements that favor established players with grandfathered holdings. Three archetypes dominate: global small-group specialists with year-round departure models, domestic premium coach operators with permanent camp infrastructure, and self-guided logistics platforms leveraging vehicle-tracking telemetry. Competitive moves concentrate on indigenous partnership expansion and modular itinerary reconfiguration around compressed booking windows.
Within the global expedition tier, Intrepid Travel and G Adventures exemplify small-group models that sustain multi-destination circuits across the Red Centre and Kimberley. AAT Kings Tours Limited anchors premium coach-based positioning through Uluru and Kakadu circuits with established indigenous partnership frameworks. Ultimate Adventure Travel Pty Ltd occupies the self-guided logistics vector, competing on 4WD and multi-day hiking infrastructure without permanent campsite commitments.
| Leading Market Players |
|---|
| AAT Kings Tours Limited |
| Intrepid Travel |
| G Adventures |
| Contiki |
| Discovery Nomads |
| Trafalgar Travel |
| Insight Vacations |
| Intrepid Group Ltd |
| Ultimate Adventure Travel Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Aircraft charter capacity utilization in Western Australia's Kimberley region shapes both supply concentration and price floors for remote-area operators. Fixed-wing and helicopter logistics dominate cost structures, with licensed operators commanding premium rates during narrow dry-season windows when Parks Australia permit holders must deploy or forfeit annual access.
Pricing Analysis
Queensland reef packages command substantial premiums over comparable Western Australia desert circuits due to infrastructure density and international gateway access. Three-tier pricing structure across premium indigenous-partnership expeditions, standard guided departures, and self-guided 4WD logistics separates market tiers. Pricing pressure stems from diesel transport cost volatility that small independent guides cannot fully pass to domestic millennial segments. Family groups exhibit highest price sensitivity, while solo travelers seeking exclusive Aboriginal land access demonstrate lowest elasticity.
Supply Chain Analysis
Inbound logistics costs through Fremantle and Brisbane ports constrain equipment repositioning for seasonal operations across multiple jurisdictions. Supply concentrates in Australia for satellite communication hardware, New Zealand for specialized alpine equipment, and Southeast Asia for marine diving gear. Raw material dependencies span aviation fuel contracts, camping infrastructure textiles, and telemetry device electronics. Single-source vulnerability runs through licensed aircraft operators controlling Kimberley access. Distribution runs through direct-to-consumer platforms displacing traditional wholesale tour operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine and alpine guide certification pipelines cannot expand fast enough to match operator demand, creating a persistent capability gap that reshapes competitive entry barriers. This scarcity favors incumbents with in-house training academies and indigenous partnership frameworks.
For Market Incumbents: Shield permit portfolios through accelerated indigenous land access agreements before competitive allocation rounds intensify. Deepen backward integration into aircraft charter operations to capture margin currently flowing to licensed Kimberley operators. Certification investment in TGA-accredited safety infrastructure raises rival cost structures beyond new entrant reach.
For New Entrants and Emerging Players: Lead with self-guided 4WD logistics platforms targeting domestic Gen Z travelers through peer-to-peer recommendation engines. Tasmania's underdeveloped alpine hut-to-hut networks present the most penetrable geography for first-mover positioning. Direct-to-consumer acquisition bypasses commission compression crushing established wholesale channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with telemetry-enabled safety infrastructure and modular booking platforms. Long-term viability hinges on climate-adaptive route portfolios that shift capital between permanent campsites and flexible guided models. Acquisition target archetype: small-group expedition specialists with grandfathered Parks Australia permits. Watch Parks Australia permit allocation round outcomes as inflection signal for competitive access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Partnership Expansion | Unlocks restricted Aboriginal land access and creates premium pricing power through exclusivity arrangements. |
| Telemetry Safety Infrastructure Deployment | Satisfies TGA remote-area medical evacuation standards while compressing insurance premiums for high-risk activities. |
| Modular Booking Platform Development | Captures compressed booking windows from domestic millennial and Gen Z traveler segments. |
| Cross-Border Operator Licensing | Reduces compliance duplication as Queensland and Western Australia safety protocols converge. |
| Self-Guided 4WD Logistics Platform | Displaces traditional guided inventory in Western Australia's Pilbara and Queensland's Cape York. |
Research Methodology
Initial hypotheses were tested against primary input from adventure tour operators, Parks Australia permit administrators, indigenous partnership coordinators, and aircraft charter logistics managers and refined through secondary validation. Primary interviews combined with Parks Australia commercial activity databases, TGA accreditation registries, state tourism commission arrival statistics, and operator financial disclosures. Bottom-up route viability modeling and top-down market sizing triangulated volume estimates.
Variance decomposition across activity type, tourism segment, seasonal access window, and service delivery format structured the analytical framework. CAGRs derived from segment-level booking trajectories and yield-per-departure trends across the projection horizon. Forecast inputs incorporated climate variability scenarios affecting route access and Parks Australia permit allocation policy shifts.
The analysis sits within stated boundaries; outcomes outside continued TGA regulatory tightening and sustained domestic millennial demand growth would require recalibration. Forecasts reflect assumptions around permit scarcity persistence and indigenous partnership framework stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
North America Amusement Parks Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
Hawaii Tourism Market