
 UK Family/ Indoor Entertainment Centers Market | 2026-2036
UK Family/ Indoor Entertainment Centers Market Size, Share, and Industry Trends Forecast 2026-2036
UK Family/ Indoor Entertainment Centers Market Insights
The UK's net-zero carbon mandate for commercial buildings is hardening operational requirements for indoor entertainment venues. Merlin Entertainments leverages its scale to retrofit legacy attractions with low-carbon systems across multiple UK sites. Hollywood Bowl Group anchors its competitive position through concentrated real estate in high-footfall retail parks. Gravity Active Entertainment specializes in trampoline parks that compete for the same teenage and young-adult demographic.
Family and indoor entertainment centers are purpose-built commercial facilities combining physical activity infrastructure, electronic gaming systems, and food-service operations under climate-controlled environments, typically spanning 10,000 to 80,000 square feet depending on format classification. Their primary commercial purpose is to monetize group leisure occasions through per-visit admission, in-venue consumption, and event hosting. Arcades and bowling represent the most mature service type segments with established margin pools, while virtual reality within the activity type dimension captures the fastest-growing spend per visit. Mega-facility formats concentrate capital investment in Greater London and the West Midlands, though medium-sized regional centers sustain higher utilization rates per square foot.
Health and Safety Executive guidelines govern mechanical ride safety and structural fire compliance, while local authority licensing frameworks control alcohol sales and late-opening permissions that extend revenue hours. The UK Gambling Commission regulates prize-redemption arcade machines, constraining product mix and floor-space allocation decisions. Operators must monitor how Building Regulations Part L amendments reshape HVAC and lighting upgrade timelines, as compliance deadlines force capital allocation trade-offs between expansion and refurbishment.
Market Dynamics
Building Regulations Part L amendments are forcing UK indoor entertainment operators to accelerate HVAC and lighting refurbishment timelines, creating capital allocation trade-offs between venue expansion and compliance-driven retrofit cycles.
Growth Catalysts
- Net-zero carbon mandate:The UK government's tightening energy efficiency standards for commercial leisure buildings is accelerating capital refurbishment cycles across Greater London and West Midlands clusters.
- Young adult social bookings:Social groups aged 18-34 are expanding their share of venue bookings across London, Manchester, and Birmingham, diversifying revenue beyond traditional family segments.
- Multi-activity mega-facilities:Demand is concentrating in facilities combining bowling, arcade gaming, and immersive virtual reality experiences under single-roof operations.
Market Restraints
- Energy input cost volatility:Natural gas and electricity price fluctuations strain operating margins for climate-controlled venues spanning 10,000 to 80,000 square feet.
- Real estate supply concentration:Prime retail park locations in high-footfall zones face limited availability and competing leisure tenants.
- Prize-redemption machine constraints:UK Gambling Commission regulations restrict product mix and floor-space allocation decisions for arcade operators.
Strategic Opportunities
- Regional city underpenetration:Medium-sized regional centers in Leeds, Liverpool, and Newcastle sustain higher utilization rates per square foot than saturated London mega-facilities.
- Immersive virtual reality convergence:Integration of VR systems with physical activity infrastructure creates differentiated experiences unavailable through home entertainment substitutes.
- Late-opening licensing expansion:Local authority alcohol sales permissions enable extended revenue hours targeting adult evening demographics.
Industry Challenges
- Mechanical ride safety certification:Health and Safety Executive guidelines govern structural fire compliance and mechanical ride safety, extending commissioning timelines for new attractions.
- Legacy system integration:Retrofitting low-carbon HVAC into existing buildings requires coordination with original structural specifications and local authority planning permissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Family/ Indoor Entertainment Centers Market |
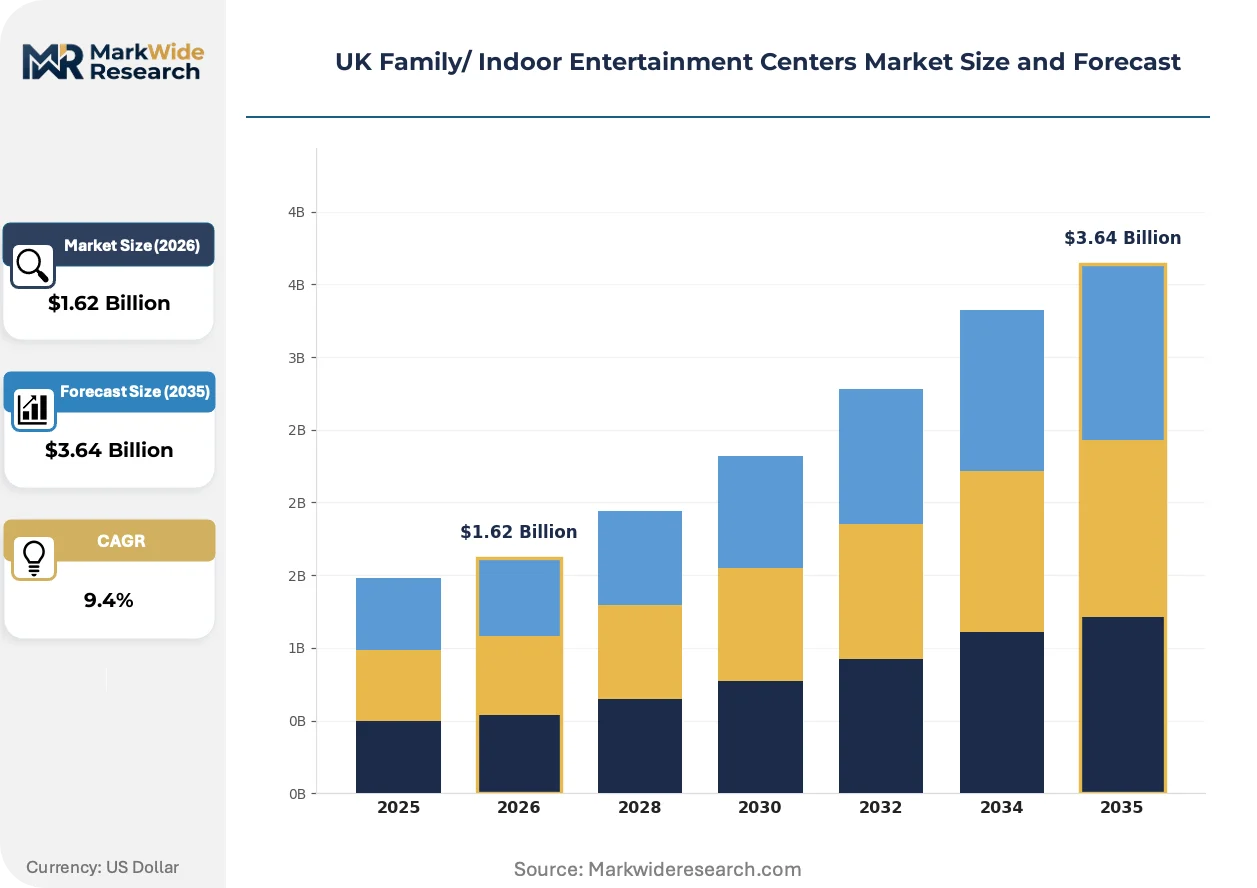
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Arcades, Bowling, Mini Golf, Laser Tag Age Group: Children, Teenagers, Adults, Seniors Activity Type: Active Games, Virtual Reality, Crafts, Events Facility Size: Small, Medium, Large, Mega |
| Companies Covered | Namco Funscape, Gravity Active Entertainment, Merlin Entertainments, Laser Quest, TeamSport, Hollywood Bowl Group, Flip Out, Quasar Elite, Tenpin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Family/ Indoor Entertainment Centers Market Trends and Innovations
Virtual reality technology is absorbing capital investment and floor space allocation across UK entertainment venues, while regulatory pressure on carbon intensity reshapes refurbishment priorities. These forces are compressing traditional format lifecycles.
Immersive virtual reality systems are absorbing visitor dwell time and per-visit spend previously captured by conventional arcade cabinets. Teenage and young-adult demographics are adopting VR experiences at the fastest pace, with operators reallocating 15-25% of floor space to VR pods and free-roam arenas. This technology is absorbing margin pressure from rising labor and energy costs by commanding premium admission pricing.
Building Regulations Part L amendments mandate specific HVAC and lighting efficiency thresholds for commercial buildings. Operators face compressed upgrade timelines as compliance deadlines approach, forcing simultaneous capital deployment across multiple sites. Mega-facility formats in Greater London encounter the steepest retrofit complexity due to 24-hour operating schedules and integrated building management systems.
Group booking behavior is fragmenting from traditional family occasion packages toward curated social experiences for adult friend networks. Venue operators are responding with segmented pricing for corporate events, competitive leagues, and themed evening sessions. Manchester and Birmingham clusters exhibit the most pronounced shift, with Friday and Saturday evening slots commanding yield premiums above standard family daytime rates.
UK Family/ Indoor Entertainment Centers Market Segmentation
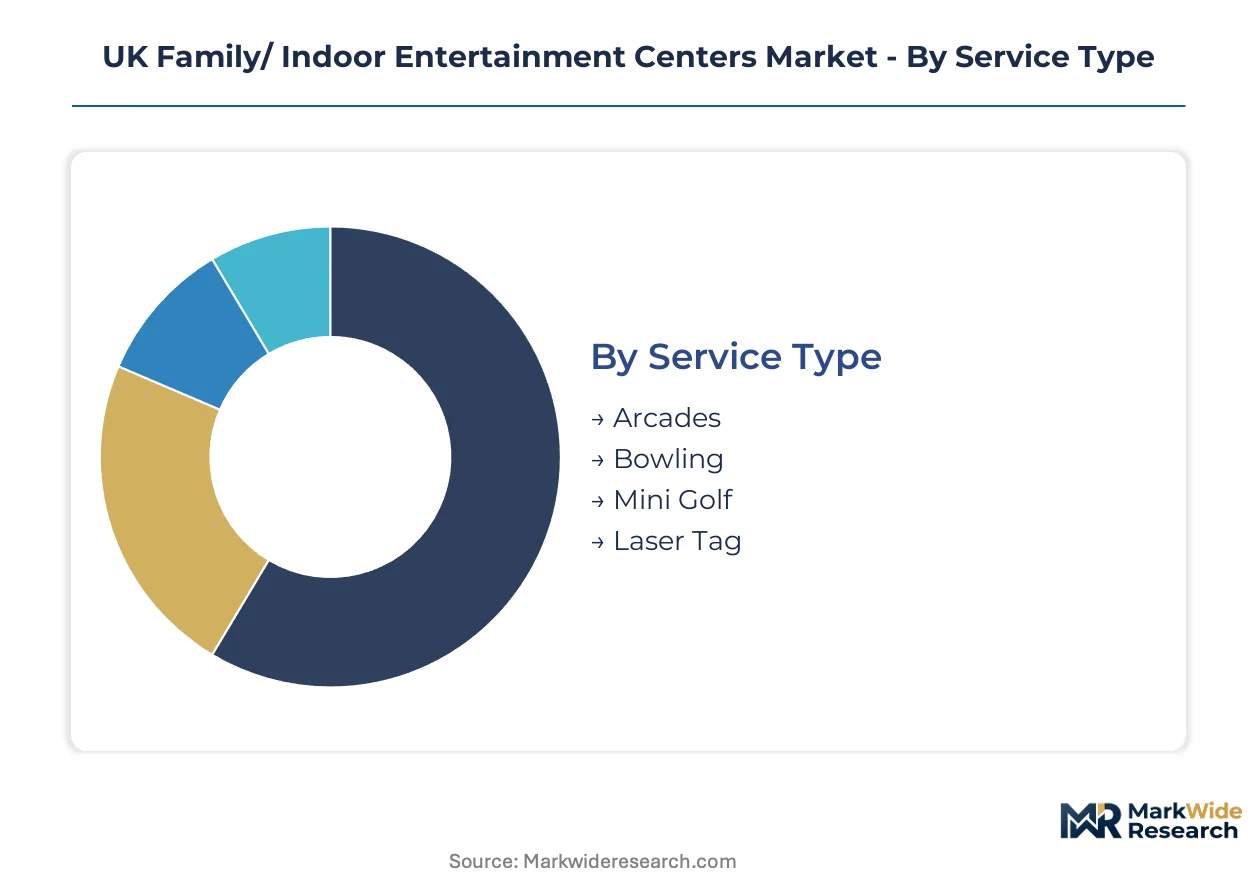
UK entertainment center operators configure venue layouts around four distinct segmentation axes. Each dimension shapes capital deployment, staffing models, and compliance exposure differently across the refurbishment cycles now accelerating under Building Regulations Part L.
Service Type:
Retrofit priorities diverge sharply across service categories, with energy-intensive mechanical systems demanding staggered upgrade timelines.
- Arcades:Prize-redemption and video gaming cabinets dominate floor space allocation. UK Gambling Commission oversight constrains machine density in Greater London clusters, compressing margin per square foot against Manchester and Birmingham equivalents.
- Bowling:Lane infrastructure requires climate-controlled environments with intensive HVAC loads. West Midlands operators face the steepest Part L compliance costs due to aging building stock and extended evening operating hours.
- Mini Golf:Indoor course construction leverages artificial turf and LED lighting systems with lower energy intensity than mechanical attractions.
- Laser Tag:Arena-based combat gaming targets teenage demographics with premium session pricing. Manchester venues report the highest per-visit spend in this category.
Bowling sits at the top of the volume ranking, with laser tag climbing the fastest.
Age Group:
Customer mix determines staffing ratios, safety certification requirements, and permissible operating hours under local authority licensing frameworks.
- Children:Birthday party packages and school holiday programming sustain weekday daytime utilization. Parental supervision mandates elevate staff-to-visitor ratios above adult-only sessions.
- Teenagers:Social group bookings concentrate in trampoline parks and VR arenas. Birmingham clusters capture disproportionate share of this demographic through concentrated retail park accessibility.
- Adults:Corporate events and competitive leagues extend revenue into evening slots. Alcohol licensing permissions unlock yield premiums above family-oriented programming.
- Seniors:Morning session discounts and low-impact activity programming fill underutilized capacity during off-peak hours.
Children anchor volume throughput, with adults expanding most quickly as operators pivot toward evening social occasion capture.
Activity Type:
Technology integration intensity varies across activity categories, reshaping depreciation schedules and vendor dependency structures.
- Active Games:Trampoline courts, climbing walls, and ninja obstacle courses demand specialized flooring and impact-absorbing surfaces. Gravity Active Entertainment specializes in this segment with concentrated West Midlands presence.
- Virtual Reality:Free-roam arenas and VR pods command premium pricing with 15-25% floor space allocation becoming standard. Hardware refresh cycles compress to 24-36 months against 7-10 year spans for traditional arcade cabinets.
- Crafts:Pottery painting and build-a-bear style workshops occupy smaller footprints with lower capital intensity. Seasonal demand spikes align with school holiday calendars.
- Events:Private function hosting leverages underutilized capacity with customized catering and dedicated staff deployment.
Active Games dominate current volume, with Virtual Reality gaining share fastest through technology-driven experience differentiation.
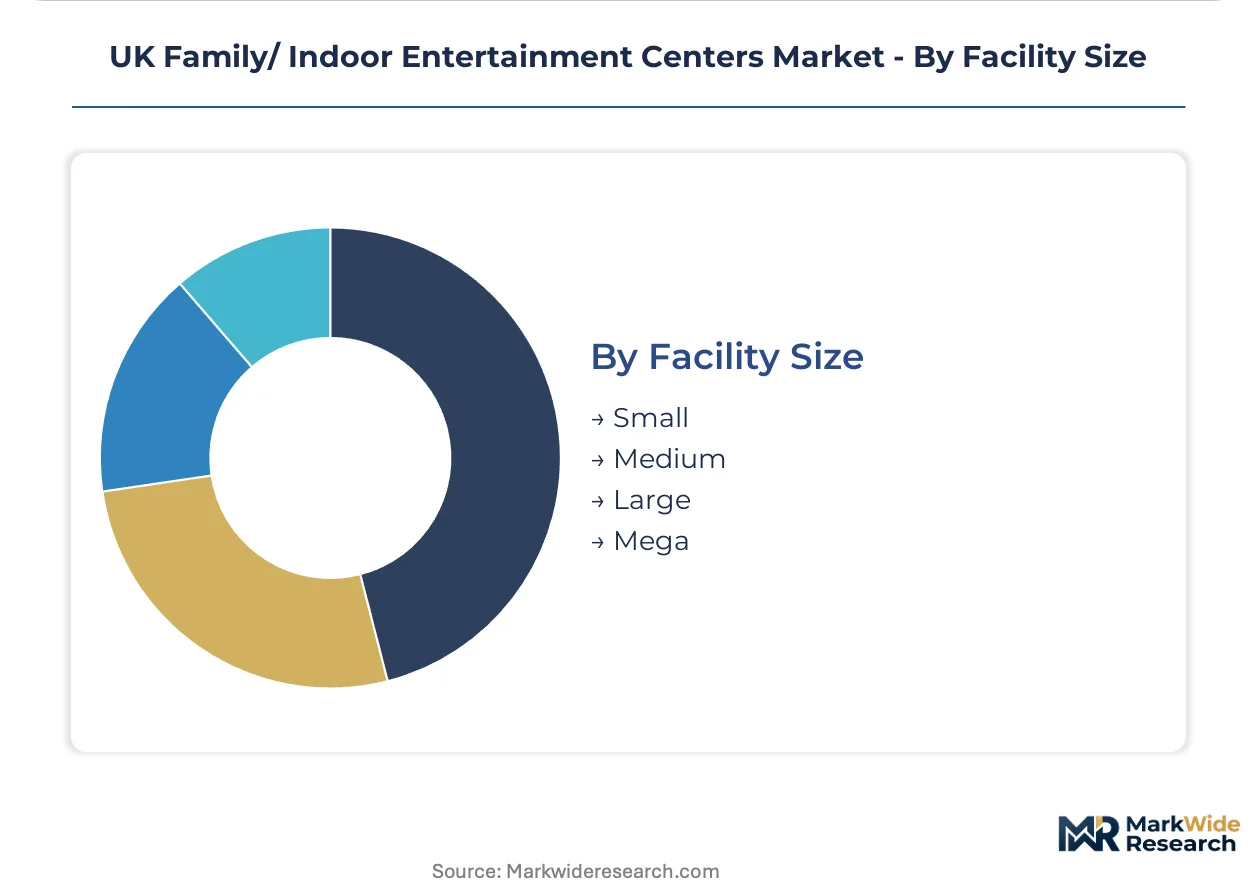
Facility Size:
Scale economics determine regulatory compliance complexity and energy efficiency investment viability.
- Small:Sub-10,000 square foot formats concentrate in secondary retail locations with limited activity diversification. Part L retrofit costs often exceed building value, accelerating obsolescence.
- Medium:10,000-25,000 square foot regional centers in Leeds, Liverpool, and Newcastle sustain higher utilization rates per square foot than saturated London mega-facilities.
- Large:25,000-50,000 square foot multi-activity venues balance diversification against operational complexity. Hollywood Bowl Group anchors this tier with concentrated retail park real estate.
- Mega:50,000-80,000 square foot integrated complexes combine bowling, arcade, VR, and F&B under single-roof operations. Greater London sites encounter steepest Part L compliance complexity due to 24-hour schedules and integrated building management systems.
Mega facilities concentrate capital headlines, with Medium formats delivering superior utilization efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK indoor entertainment center industry traces its modern lineage to the 1980s American-style family entertainment center imports, with British operators later pioneering the multi-activity mega-facility format that now dominates capital deployment across Greater London and the West Midlands.
London and Southeast England
Corporate event bookings and young adult social groups aged 18-34 drive demand concentration in this cluster. The Greater London Authority enforces strict planning permissions for late-opening venues under the Licensing Act 2003. Mega-facility operators in Croydon and Watford retrofit low-carbon HVAC systems to meet Building Regulations Part L deadlines while maintaining 24-hour operating schedules.
West Midlands
Teenage demographics and trampoline park penetration anchor volume throughput in Birmingham and Coventry clusters. The Health and Safety Executive maintains regional inspection offices that govern mechanical ride certification timelines. Bowling and laser tag operators in Solihull retail parks face the steepest Part L compliance costs due to aging building stock and extended evening hours.
Northwest England
Manchester anchors the fastest shift from family occasion packages toward curated adult social experiences. Local authority licensing frameworks in Salford and Trafford control alcohol sales permissions that unlock yield premiums for Friday evening slots. Regional centers here sustain higher utilization per square foot than saturated London equivalents.
Yorkshire and Humber
Leeds and Sheffield clusters exhibit underpenetration relative to population density, creating expansion opportunities for medium-format operators. The UK Gambling Commission's regional compliance teams monitor prize-redemption machine density in Bradford arcade venues. Trampoline park specialists target Wakefield and Doncaster retail parks for secondary location growth.
Scotland
Glasgow and Edinburgh concentrate Scottish demand for immersive virtual reality experiences alongside traditional bowling formats. The Scottish Government's building standards division applies Part L-equivalent energy efficiency mandates through Section 6 regulations. Aberdeen operators face compressed refurbishment timelines due to North Sea energy sector labor competition for HVAC contractors.
UK Family/ Indoor Entertainment Centers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across facility scale and geographic concentration dimensions. The UK market exhibits moderate consolidation with three to five dominant operators controlling mega-facility real estate in high-footfall retail parks while fragmented sub-regional players occupy secondary locations. Strategic archetypes divide between scale-driven national chains, activity-specialist verticals, and diversified leisure conglomerates. Competitive moves concentrate on portfolio diversification through multi-activity integration and selective geographic expansion into underpenetrated regional cities.
Among UK-based diversified leisure operators, Merlin Entertainments and Hollywood Bowl Group exemplify distinct scale archetypes, while Gravity Active Entertainment occupies the activity-specialist position focused on trampoline park formats. These three entities represent the primary competitive anchors shaping capital deployment patterns and real estate selection criteria across the national market.
| Leading Market Players |
|---|
| Namco Funscape |
| Gravity Active Entertainment |
| Merlin Entertainments |
| Laser Quest |
| TeamSport |
| Hollywood Bowl Group |
| Flip Out |
| Quasar Elite |
| Tenpin |
| Others |
Pricing and Supply Chain Analysis
HVAC technician concentration in Greater London and the West Midlands feeds directly into venue operating cost structures, with labor-cost differentials between these clusters widening the spread between premium mega-facility pricing and economy regional-center rates. Energy retrofit mandates compress margins at the economy tier while premium venues pass compliance costs through yield-managed evening sessions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels captures divergent buyer archetypes in the UK market. Premium tier differentiation rests on immersive VR integration and late-opening alcohol licensing in Greater London clusters, while standard bowling-arcade combinations compete on family occasion packaging. Economy regional centers in Leeds and Newcastle face price compression from energy input volatility. Corporate event planners exhibit lowest price sensitivity; school holiday family segments demonstrate highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for arcade cabinets and VR hardware concentrate refurbishment cycles in UK-based technical centers, with end-of-life equipment returning to West Midlands facilities for component recovery. Manufacturing of prize-redemption machines draws from China and Taiwan, while HVAC systems for Part L compliance rest on German and Dutch supplier networks. Single-source vulnerability sits with specialized VR motion-platform vendors. Distribution runs through consolidated leisure equipment distributors serving retail park clusters nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier yield management as energy compliance costs disproportionately burden economy competitors. VR integration and alcohol licensing extensions enable pricing power in adult evening demographics.
For Market Incumbents: Acquire underperforming medium-format regional centers in Yorkshire and Humber to consolidate utilization efficiency advantages against London mega-facility saturation. Defend against trampoline park specialists by integrating active-game infrastructure into existing bowling-arcade footprints. Prioritize Building Regulations Part L compliance scheduling to preempt regulatory bottlenecks. For New Entrants and Emerging Players: Adult social groups aged 25-34 in Manchester and Birmingham represent the most underserved buyer archetype with highest per-visit spend potential. White-space exists in competitive league programming and corporate event hosting where incumbent format rigidities create service gaps. Launch through partnership with local authority licensing frameworks to secure late-opening permissions ahead of real estate selection. For Investors and Strategic Acquirers: Diversified leisure conglomerates are the most active acquirer in this space, seeking multi-activity platform assets to extend venue networks. Long-term viability hinges on capital deployment flexibility between refurbishment cycles and greenfield expansion. Monitor Health and Safety Executive inspection queue lengths as lead indicator of new attraction commissioning delays.| Strategic Initiative | Industry Significance |
|---|---|
| VR Pod Network Expansion | Captures premium pricing from young adult demographics in Greater London and West Midlands clusters. |
| Part L Compliance Acceleration | Preempts regulatory bottlenecks for HVAC retrofit scheduling across aging building stock. |
| Alcohol Licensing Extension | Unlocks yield premiums from Friday evening slots in Manchester and Birmingham venues. |
| Regional Center Consolidation | Acquires underpenetrated medium-format assets in Leeds, Liverpool, and Newcastle markets. |
| Active-Game Infrastructure Integration | Defends against Gravity Active Entertainment trampoline park specialists through format diversification. |
Research Methodology
Coverage spans Greater London, West Midlands, Northwest England, Yorkshire and Humber, and Scotland, with primary inputs from each regional cluster. The analysis combines structured interviews with venue operations directors, local authority licensing officers, and leisure equipment procurement managers with secondary validation against Health and Safety Executive inspection records, UK Gambling Commission compliance filings, and Building Regulations Part L amendment documentation. Bottom-up venue utilization modeling triangulates against top-down regional spending pattern analysis.
Granularity-level framing applies separate modeling tracks for mega-facility, large, medium, and small format classifications across service type and activity type dimensions. CAGRs derive from weighted regression against refurbishment cycle timing, energy cost trajectory assumptions, and demographic shift parameters. Forecast inputs incorporate local authority planning permission approval rates and HVAC contractor capacity constraints specific to commercial leisure building retrofit demand.
Inputs from UK regulatory compliance databases and regional licensing authority records were available through the study window; gaps in real-time energy cost pass-through data at individual venue level introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding Part L enforcement timing and young adult booking share trajectories. Practitioners should monitor Health and Safety Executive mechanical ride certification queue lengths and local authority alcohol licensing approval velocity for early signals of operational constraint tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
India Faith Based Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Thailand Sustainable Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
Italy Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Industrial Tourism Market