
 Alternative Tourism Market | 2026-2036
Alternative Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Tourism Market Outlook
Curated expedition packages is repositioning how operators monetize traveler relationships beyond per-trip margins. Intrepid Travel leverages its B Corp certification to anchor premium pricing in ethical travel segments. G Adventures competes through localized supply chains that sustain community revenue retention across destination markets. National Geographic Expeditions differentiates via photography-led itineraries that dominate the educational expedition niche.
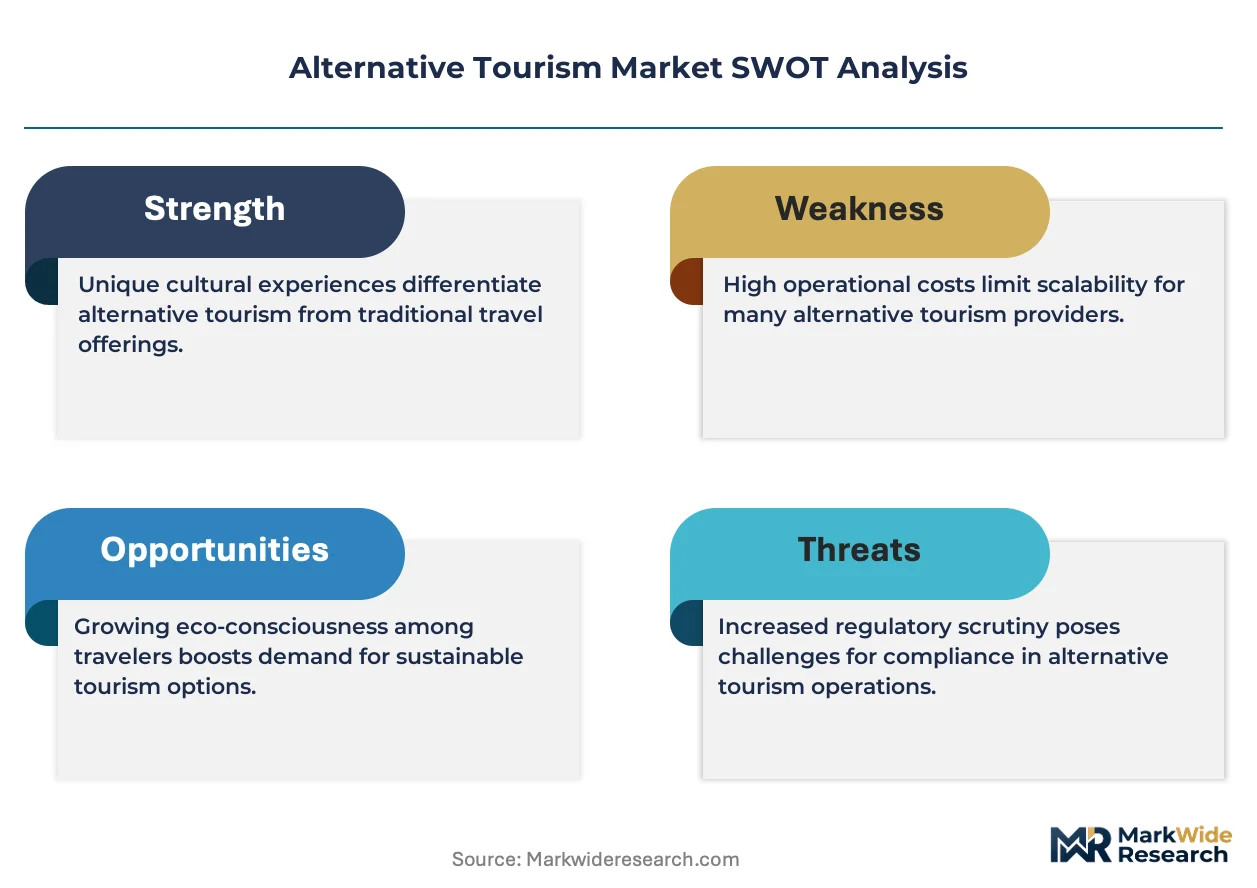
Alternative tourism encompasses travel models that deliberately minimize environmental extraction, prioritize host-community economic participation, and replace standardized hospitality with place-specific immersion; operators typically limit group sizes below sixteen participants, employ local guides exclusively, and allocate set revenue shares to conservation or development funds. Ecotourism and adventure travel represent the most mature revenue pools, while wellness retreats command the highest per-capita margins due to extended length-of-stay and ancillary service attachment. Customized itineraries are displacing fixed-departure products as the fastest-growing service type, reflecting traveler insistence on schedule autonomy and dietary or mobility accommodation.
ISO 14001 environmental management standards and the EU Green Deal's carbon disclosure rules shape operator eligibility for European source-market distribution, while Costa Rica's ICT sustainability certification and Australia's ECO Tourism Australia standard create bilateral recognition pathways that filter market access. The US Federal Trade Commission's green marketing guidelines constrain how US-originating operators label carbon-neutral claims. Stakeholders must monitor whether emerging biodiversity credit frameworks will commodify conservation outcomes as bookable trip components.
Market Dynamics
Millennial and Gen Z travelers are forcing operators to abandon fixed-departure products in favor of hyper-customized itineraries with dietary, mobility, and scheduling accommodations. This generational pivot is compressing traditional package-tour margins while rewarding agile, small-group operators with local supply-chain control.
Growth Catalysts
- EU Green Deal carbon-labeling mandates:European source-market distribution now requires verified environmental disclosure, filtering out non-compliant operators and concentrating bookings with certified providers.
- Community-based ecotourism models in Costa Rica:Deep market penetration here demonstrates scalable revenue-sharing frameworks that retain host-community income and attract premium pricing.
- Photography-led educational itineraries:Specialized expedition formats capture high-margin segments by combining skill instruction with conservation storytelling.
Market Restraints
- Small-group size ceilings:Operator commitments to sub-sixteen participant limits constrain per-departure revenue and require higher trip frequency to maintain fixed-cost coverage.
- Local guide exclusivity requirements:Dependence on destination-specific talent pools creates recruitment bottlenecks in remote regions with limited hospitality training infrastructure.
- Conservation fund allocation mandates:Set revenue shares to protected-area management reduce net operating margins compared to conventional tourism models.
Strategic Opportunities
- Biodiversity credit framework integration:Emerging conservation-outcome commodification allows operators to package measurable ecological impact as bookable trip components.
- Wellness retreat extension:Extended length-of-stay formats in this segment command the highest per-capita margins through ancillary service attachment.
- ISO 14001 bilateral recognition pathways:Costa Rica's ICT certification and Australia's ECO Tourism Australia standard create streamlined market access for compliant operators across multiple source regions.
Industry Challenges
- FTC green marketing guideline compliance:US-originating operators face strict constraints on carbon-neutral claim labeling, requiring legal review of all sustainability messaging.
- Supply chain localization complexity:Sustaining community revenue retention across fragmented destination markets demands continuous supplier relationship management without corporate infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Tourism Market |
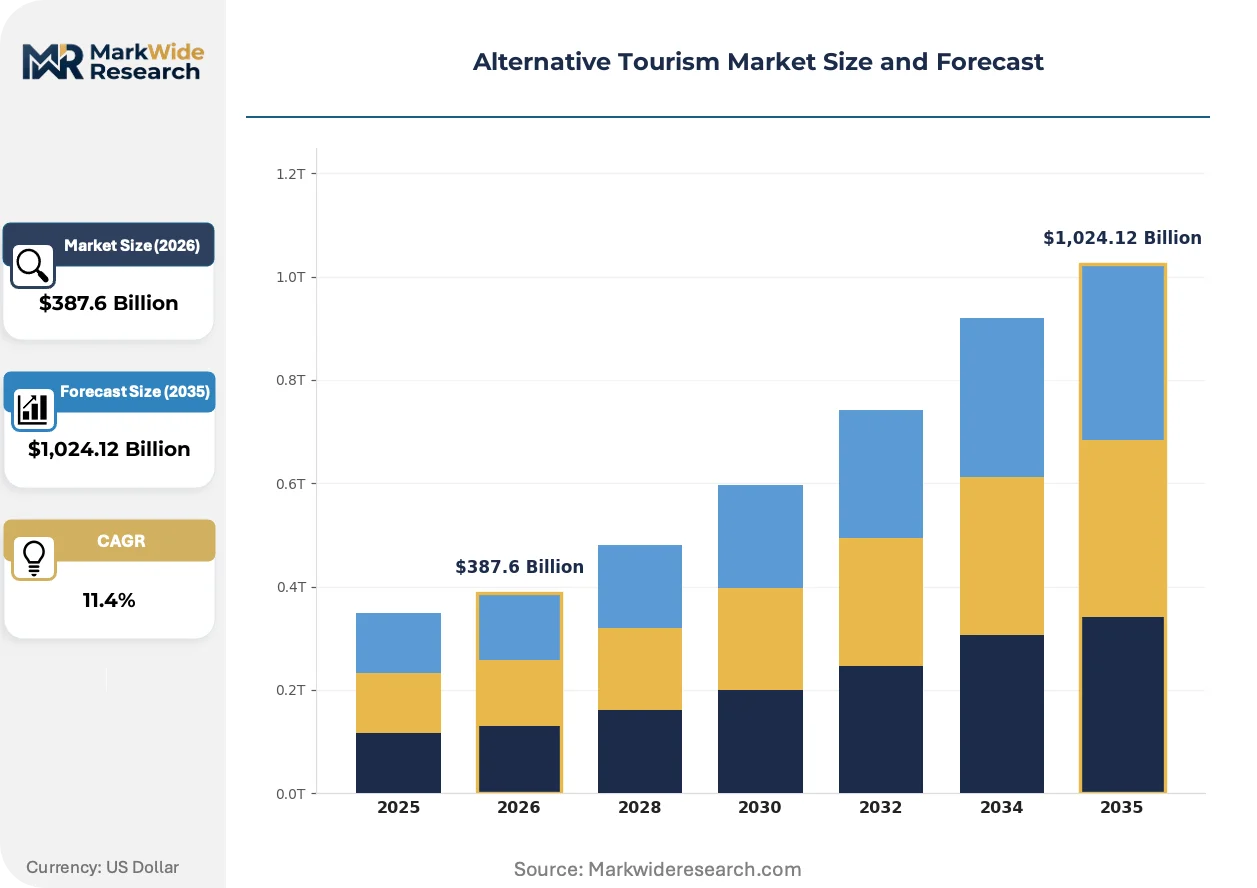
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourism Type: Ecotourism, Adventure Travel, Sustainable Travel, Cultural Tourism Customer Segment: Backpackers, Eco-Conscious Travelers, Cultural Enthusiasts, Luxury Seekers Activity Focus: Wildlife Tours, Community-Based Experiences, Outdoor Expeditions, Wellness Retreats Service Type: Guided Tours, Customized Itineraries, Volunteer Programs, Homestays |
| Companies Covered | Intrepid Travel, G Adventures, Responsible Travel, Exodus Travels, Adventure Life, National Geographic Expeditions, Wild Frontiers Adventures, Steppes Travel, Beyonder Experiences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Tourism Market Strategic Shifts
Technology-enabled personalization is collapsing the traditional trade-off between scale and customization. Operators now deploy modular itinerary architecture to deliver bespoke experiences without sacrificing operational efficiency.
Dynamic packaging platforms are expanding into the alternative tourism sector, allowing travelers to assemble component bookings across accommodation, transport, and activity providers within a single transaction interface. Mid-size operators in the experience-driven segment are adopting these tools fastest, compressing the booking window from research to confirmation. This technology is expanding into conservation-impact visualization, enabling real-time tracking of traveler contributions to destination funds.
EU Green Deal carbon disclosure rules are reshaping operator eligibility for European distribution channels. The regulation mandates granular emissions reporting across scope 1, 2, and 3 categories for travel services marketed to EU consumers. Expedition and ecotourism segments are responding by integrating third-party verification into pre-trip marketing materials to maintain source-market access.
Schedule autonomy has become the primary booking determinant for experience-driven travelers, displacing price sensitivity as the dominant decision factor. Fixed-departure products are losing share to open-date formats with flexible start points across multiple gateway cities. This pattern concentrates in Costa Rica and Australia, where established certification frameworks reduce perceived booking risk.
Alternative Tourism Market Segmentation
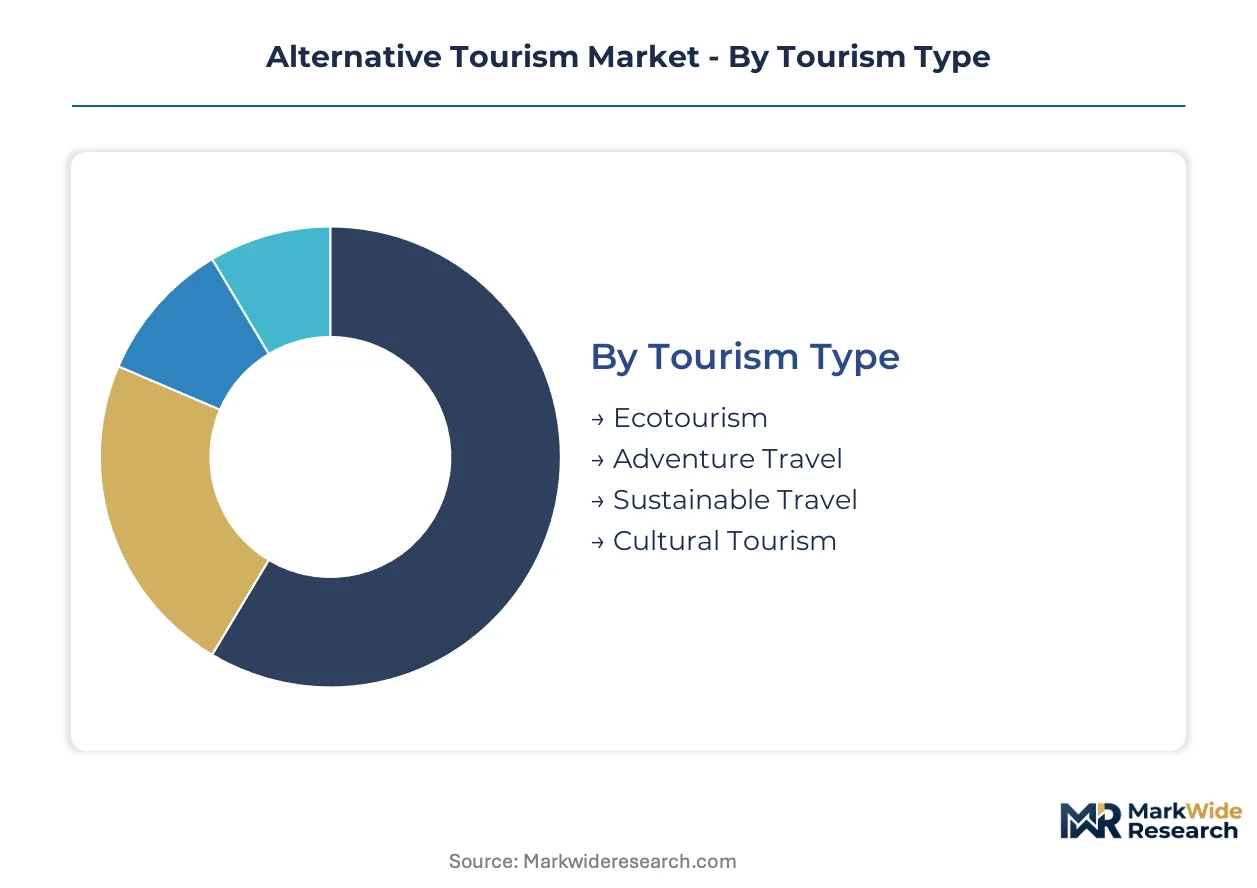
Alternative tourism operators must match certification requirements to segment-specific traveler expectations. ISO 14001 and EU Green Deal compliance thresholds vary sharply across tourism types and service formats, filtering market access by operational model.
Tourism Type:
Certification burdens stratify sharply across these four models, with EU Green Deal carbon-labeling mandates most stringent for mass-market formats and relaxed for community-embedded alternatives.
- Ecotourism:Operators must secure Costa Rica ICT certification or Australia's ECO Tourism Australia standard for bilateral recognition in European distribution channels. Demand concentrates in Costa Rica's protected-area buffer zones, where community revenue-sharing frameworks satisfy EU Green Deal supply-chain transparency requirements.
- Adventure Travel:Physical risk exposure elevates liability insurance and guide certification costs above other segments. European source markets demand ISO 14001 environmental management documentation alongside adventure-specific safety protocols from operators.
- Sustainable Travel:Carbon-neutral claim validation requires FTC green marketing guideline compliance for US-originating marketing and EU Green Deal scope 1-3 emissions disclosure for European distribution.
- Cultural Tourism:Heritage site access permits and host-community consent protocols create destination-specific regulatory layers beyond environmental certification.
Ecotourism sits at the top of the volume ranking, with Sustainable Travel climbing the fastest.
Customer Segment:
Price tolerance and booking behavior diverge across these traveler profiles, with certification willingness translating directly into margin capture potential.
- Backpackers:Price sensitivity limits certification premium absorption; operators target this segment with stripped-down ISO 14001 compliance rather than full EU Green Deal verification to maintain accessibility.
- Eco-Conscious Travelers:B Corp certification and carbon-label transparency command booking premiums. This segment drives demand for conservation fund allocation visibility and third-party verified impact reporting.
- Cultural Enthusiasts:Extended length-of-stay patterns support higher per-trip certification cost amortization across immersive itineraries.
- Luxury Seekers:Exclusive small-group formats absorb premium pricing for comprehensive certification portfolios including wellness-specific standards.
Eco-Conscious Travelers anchor revenue concentration, with Luxury Seekers expanding most quickly.
Activity Focus:
Operational complexity scales with wildlife proximity and community integration depth, shaping fixed-cost structures across activity types.
- Wildlife Tours:Protected-area access fees and conservation fund mandates compress margins unless offset by premium small-group pricing. Australia's ECO Tourism Australia certification dominates this segment's credibility signaling.
- Community-Based Experiences:Revenue-sharing frameworks with host communities create sustainable supply-chain localization but require continuous relationship management without corporate infrastructure support.
- Outdoor Expeditions:Seasonal weather windows and remote logistics constrain departure frequency, amplifying per-trip fixed-cost coverage pressure.
- Wellness Retreats:Extended length-of-stay generates the highest per-capita ancillary service attachment, supporting comprehensive certification investment recovery.
Wildlife Tours command the widest departure volume, while Wellness Retreats gain share fastest.
Service Type:
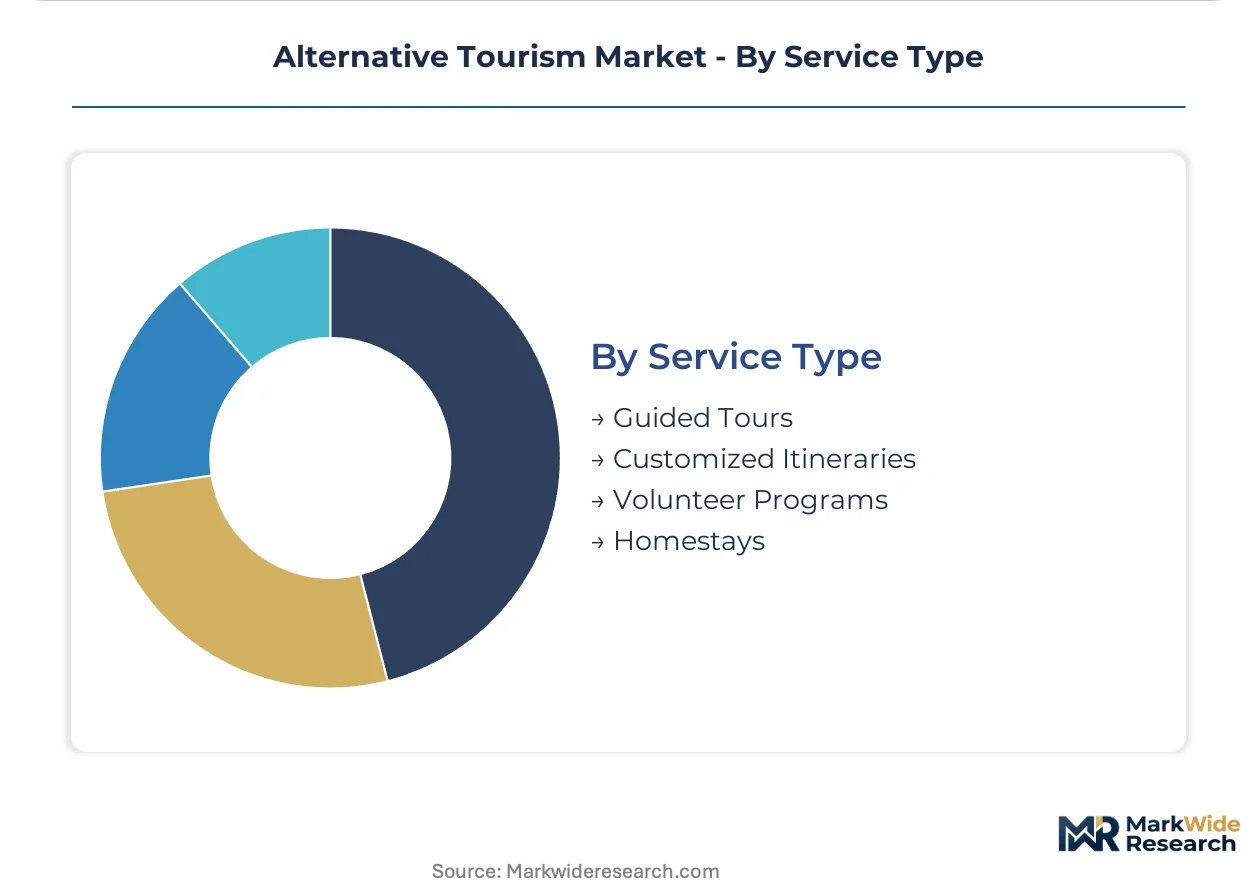
Technology enablement and personalization depth determine competitive positioning across booking format preferences.
- Guided Tours:Fixed-departure products face margin compression as schedule autonomy becomes the primary booking determinant for experience-driven travelers.
- Customized Itineraries:Modular itinerary architecture now delivers bespoke experiences without sacrificing operational efficiency, displacing fixed-departure products as the dominant growth format.
- Volunteer Programs:Conservation outcome commodification through emerging biodiversity credit frameworks creates new revenue attachment opportunities.
- Homestays:Direct host-community economic participation satisfies EU Green Deal supply-chain transparency requirements while reducing operator accommodation cost exposure.
Guided Tours retain volume leadership, with Customized Itineraries showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Costa Rica's community-based ecotourism models command deeper market penetration than Australia's certification-driven frameworks, though both nations anchor distinct regional development patterns in the alternative tourism sector.
Costa Rica
Community revenue-sharing frameworks and protected-area buffer zone expansion drive operator concentration around Monteverde and the Osa Peninsula. The country's ICT sustainability certification creates bilateral recognition pathways with EU Green Deal compliance requirements. Guanacaste province hosts the densest cluster of certified eco-lodges, where conservation fund allocation mandates have become standard contract terms.
Australia
ECO Tourism Australia certification dominates credibility signaling for wildlife-focused operators, with extended length-of-stay wellness retreats generating premium pricing in Queensland and New South Wales. The national regulator's scope 1-3 emissions disclosure alignment with EU standards streamlines European source-market access. The Great Barrier Reef catchment area concentrates photography-led educational itinerary development.
Germany
EU Green Deal carbon-labeling mandates filter non-compliant operators from German source-market distribution, concentrating bookings with ISO 14001-certified providers. The Federal Environment Agency's supply-chain transparency requirements shape outbound traveler expectations. Bavaria's Alpine regions host specialized adventure operators that have modularized itinerary architecture for schedule autonomy.
United States
FTC green marketing guideline compliance constraints reshape how domestic operators label carbon-neutral claims in promotional materials. National park concession reforms in Utah and Arizona create new community-based experience licensing opportunities. The Pacific Northwest concentrates B Corp-certified expedition operators targeting eco-conscious traveler segments.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance burdens for operators serving both EU and UK source markets, with carbon disclosure rules partially aligned but not identical. The Lake District and Scottish Highlands host specialized small-group operators limited to sub-sixteen participant formats. London-based distribution platforms increasingly demand third-party verified impact reporting.
Alternative Tourism Market Competitive Environment
Top-tier vendors anchor premium certification portfolios, while mid-scale operators compete through localized supply-chain control and modular itinerary customization. The vendor base stratifies across B Corp-certified ethical travel specialists, adventure operators with exclusive local guide networks, and photography-led educational expedition providers. Consolidation pressure concentrates among mid-size players seeking scale to amortize compliance costs across EU Green Deal and ISO 14001 verification requirements. Strategic moves center on biodiversity credit framework integration and dynamic packaging platform adoption.
Within the B Corp-certified tier, Intrepid Travel and G Adventures occupy positions that exemplify how ethical certification anchors premium pricing power in European source markets. National Geographic Expeditions represents the photography-led educational archetype, leveraging conservation storytelling formats that command high-margin segment concentration. These three operators illustrate the competitive divergence between certification-driven, supply-chain-localized, and content-specialized market positioning.
| Leading Market Players |
|---|
| Intrepid Travel |
| G Adventures |
| Responsible Travel |
| Exodus Travels |
| Adventure Life |
| National Geographic Expeditions |
| Wild Frontiers Adventures |
| Steppes Travel |
| Beyonder Experiences |
| Others |
Value Chain & Pricing Dynamics
Eco-conscious traveler concentration in European source markets anchors premium pricing for EU Green Deal-compliant operators, compressing margins for non-certified competitors while rewarding verified environmental disclosure with booking premiums.
Pricing Analysis
Capacity additions in Costa Rica's protected-area buffer zones are reshaping price floors for community-based ecotourism experiences. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, with B Corp and ICT sustainability credentials commanding measurable premiums. Price differentiation hinges on conservation fund allocation visibility and third-party verified impact reporting. Cost compression in the backpacker tier intensifies as stripped-down ISO 14001 compliance becomes the minimum viable entry point.
Supply Chain Analysis
Direct-to-traveler digital channels handle customized itinerary demand while traditional distribution partnerships retain fixed-departure volume. Supply concentrates in Costa Rica, Australia, and Germany as certification bilateral recognition pathways streamline market access. Raw material dependencies include local guide talent pools, protected-area access permits, and community partnership agreements. Single-source vulnerability in remote destination hospitality training infrastructure creates recruitment bottlenecks that constrain departure frequency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where traveler insistence on schedule autonomy and verified environmental impact has elevated certification depth above price as the primary booking determinant.
For Market Incumbents: Lock in community partnership exclusivity across Costa Rica's Osa Peninsula and Monteverde clusters before emerging regional operators replicate the ICT certification pathway. Deepen backward integration into local guide training pipelines to defend against talent poaching. Prioritize biodiversity credit framework integration to capture conservation outcome commodification before regulatory standardization dilutes first-mover premiums.
For New Entrants and Emerging Players: Dynamic packaging platform architecture offers the most penetrable wedge for mid-scale operators seeking schedule-autonomy market share without legacy fixed-departure infrastructure. Target wellness retreat extensions in Queensland and New South Wales where extended length-of-stay patterns support rapid certification investment recovery. Lead go-to-market with modular itinerary tools that collapse the traditional customization-efficiency trade-off.
For Investors and Strategic Acquirers: B Corp-certified ethical travel specialists are the most active acquirer category in this space, consolidating mid-scale players to amortize EU Green Deal and ISO 14001 verification costs across broader departure portfolios. Long-term viability favors operators with captive community partnership networks and bilateral certification recognition spanning multiple source regions. Monitor whether biodiversity credit frameworks achieve regulatory standardization as the inflection signal for conservation-outcome commodification maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodiversity Credit Framework Integration | Allows operators to package measurable ecological impact as bookable trip components ahead of regulatory standardization. |
| Dynamic Packaging Platform Adoption | Enables mid-scale operators to deliver bespoke experiences without sacrificing operational efficiency or margin structure. |
| Community Partnership Exclusivity | Secures sustainable supply-chain localization in Costa Rica's protected-area buffer zones against competitor replication. |
| Wellness Retreat Format Extension | Captures highest per-capita ancillary service attachment through extended length-of-stay in Queensland and New South Wales. |
| Bilateral Certification Recognition | Streamlines EU Green Deal and ISO 14001 compliance across Costa Rica ICT and Australia's ECO Tourism Australia standards. |
Study Parameters
Direct dialogue with expedition operators, sustainability certification officers, community tourism cooperative leaders, and European distribution platform executives grounded the qualitative foundation. Primary insights combined with secondary validation from EU Green Deal regulatory filings, ICT sustainability certification databases, ECO Tourism Australia operator registries, and FTC green marketing guideline enforcement records. Bottom-up departure volume analysis and top-down market sizing triangulated across the projection horizon.
Bottom-up modeling aggregated operator-level capacity and pricing data by tourism type, customer segment, activity focus, and service format dimensions. Top-down verification cross-checked against source-market outbound travel expenditure patterns and certification penetration rates. CAGRs derived from trend extrapolation of traveler preference shifts toward schedule autonomy and verified environmental disclosure, with specific weighting for EU Green Deal compliance thresholds and generational demand evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biodiversity credit framework regulatory adoption, community partnership stability in remote destinations, and potential carbon-labeling requirement expansion beyond European source markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
Global Religious Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market
Destination Management and Attractions
Music Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market