
 North America Amusement Parks Market | 2026-2036
North America Amusement Parks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Amusement Parks Market Outlook
Virtual queue systems and mobile-first guest management is narrowing the technology gap between premium resort operators and regional park chains. The Walt Disney Company leverages proprietary wearable platforms to sustain yield management across its resort parks. Cedar Fair anchors its competitive stance through seasonal event programming and regional market density. Six Flags Entertainment Corporation differentiates via thrill-ride density and value-tier season pass structures.
North America amusement parks constitute large-scale outdoor entertainment venues combining mechanical rides, themed environments, live performance spaces, and hospitality services across properties typically exceeding fifty acres. These facilities deploy steel-track roller coasters with launch systems reaching velocities above seventy miles per hour alongside water rides utilizing gravity-fed flume channels. Themed attractions command the highest per-visitor spending through intellectual property licensing and immersive set construction. Resort parks capture disproportionate margin pools by integrating on-site lodging and multi-day ticketing architectures. Seasonal parks compete through concentrated operating calendars and regional accessibility rather than capital-intensive destination draw.
The US Occupational Safety and Health Administration coordinates with state-level amusement ride inspection bureaus to mandate annual non-destructive testing of coaster support structures and restraint systems. ASTM International F24 committee standards govern design verification and operational safety protocols across Canadian and US jurisdictions. The Consumer Product Safety Commission tracks injury data patterns that inform incremental restraint redesign requirements. Stakeholders must monitor evolving state-level climate disclosure mandates and their downstream effects on outdoor operating season assumptions and infrastructure resilience planning.
Market Dynamics
Immersive digital attractions and virtual queue infrastructure are compressing the competitive gap between destination resort parks and regional operators, forcing capital reallocation across the entire North American landscape.
Growth Catalysts
- OSHA Ride Safety Mandates:Annual non-destructive testing requirements for coaster support structures and restraint systems are accelerating replacement cycles for aging steel-track infrastructure across US parks.
- Family Visitor Segments:Demand for intellectual property-licensed themed environments is pulling multi-generational attendance toward properties with immersive set construction and character integration.
- Florida-California Destination Clusters:Regional tourism flows concentrate in these states where on-site lodging and multi-day ticketing architectures capture disproportionate margin pools.
Market Restraints
- Steel and Aluminum Input Volatility:Launch system components and track fabrication face commodity price swings that compress visibility on project returns for new coaster installations.
- Seasonal Operating Constraints:Northern-tier parks in Canada and the northern United States confront compressed calendars that limit revenue recovery windows for capital-intensive attractions.
- ASTM F24 Compliance Friction:Design verification protocols across US and Canadian jurisdictions extend development timelines for novel ride mechanics and restraint innovations.
Strategic Opportunities
- Mobile-First Guest Management:Virtual queue platforms and wearable integration create yield optimization pathways for regional chains previously excluded from dynamic pricing capabilities.
- Seasonal Event Programming:Halloween and winter holiday overlays extend effective operating days for parks with limited warm-weather calendars in the northern United States and Canada.
- Water Ride Hybridization:Gravity-fed flume channels combined with digital projection mapping open refreshed attraction categories without full steel coaster capital commitments.
Industry Challenges
- Attraction Engineering Talent Scarcity:Specialized mechanical and controls engineers for launch system design command premium compensation that strains regional operator budgets.
- Intellectual Property Licensing Complexity:Negotiations with entertainment studios for character rights create unpredictable cost structures and renewal uncertainties for themed attractions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Amusement Parks Market |
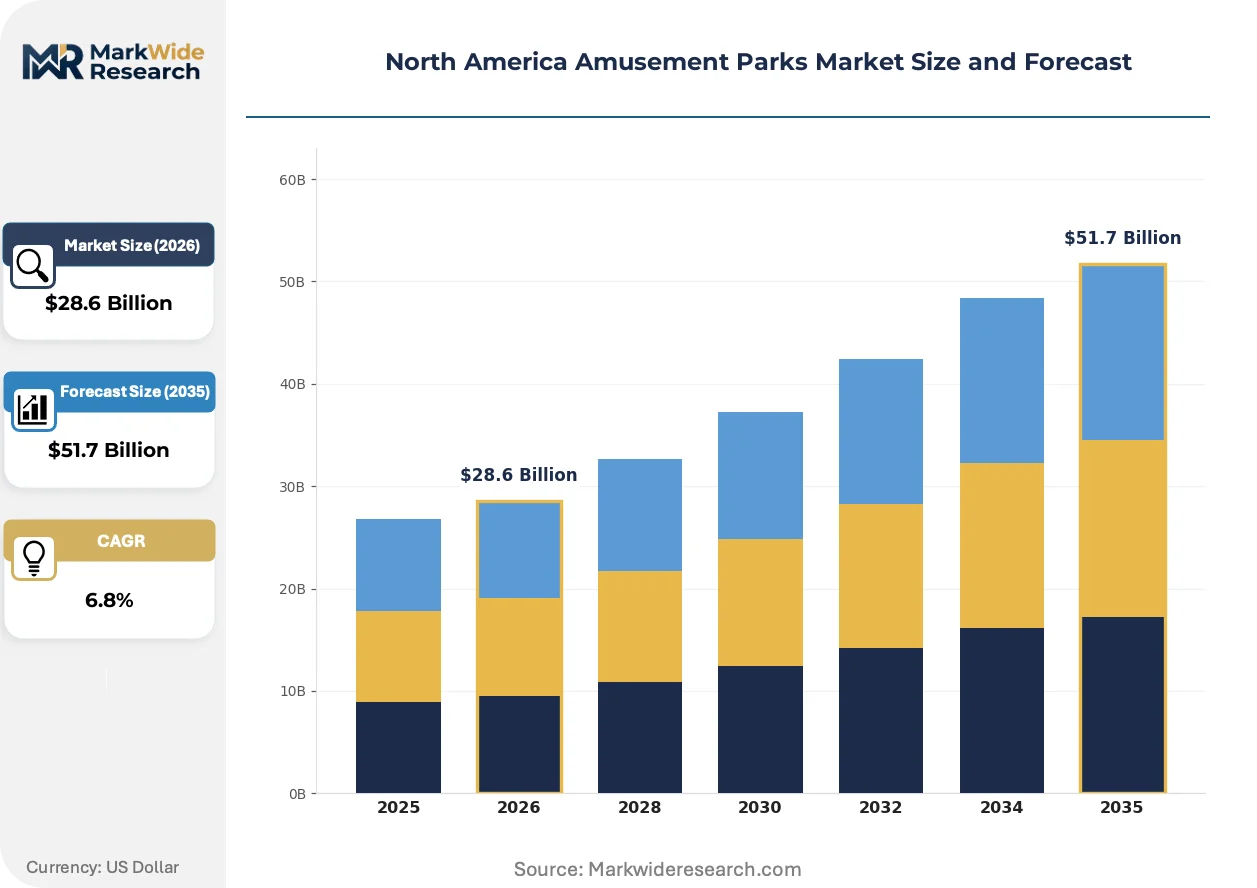
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Attraction Type: Roller Coasters, Water Rides, Themed Attractions, Live Shows Visitor Demographics: Families, Teenagers, Tourists, Corporate Groups Operating Model: Freestanding Parks, Amusement Complexes, Seasonal Parks, Resort Parks Ticketing Options: Single Entry, Season Passes, Group Discounts, VIP Packages |
| Companies Covered | United Parks & Resorts, Hershey Entertainment & Resorts Company, Six Flags Entertainment Corporation, Parques Reunidos, Merlin Entertainments, The Walt Disney Company, Cedar Fair, Premier Parks, Universal Destinations & Experiences, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Amusement Parks Market Strategic Shifts
Digital guest management infrastructure and immersive media integration are redrawing the boundary between mechanical ride experiences and theatrical entertainment, altering how parks monetize visitor dwell time.
Virtual queue systems utilizing smartphone-based reservation platforms are collapsing the operational advantage that proprietary wearable networks previously conferred upon integrated resort operators. Regional park chains in Texas, Ohio, and Pennsylvania are deploying third-party mobile platforms to match yield management capabilities without captive hardware ecosystems. This diffusion is compressing pricing power differentials between destination and regional tiers.
ASTM International F24 committee standards are tightening operational safety protocols for restraint system redesign across US and Canadian jurisdictions. The standards mandate enhanced documentation for failure-mode analysis and accelerated reporting timelines for incident data. High-velocity launch coasters with velocities exceeding seventy miles per hour face the most intensive scrutiny, prompting manufacturers to front-load verification testing.
Visitor purchasing patterns are fragmenting across single-day tickets, multi-day bundles, and membership structures with varying access tiers. Regional operators are unbundling previously inclusive offerings into à-la-carte add-ons for parking, dining, and line-skipping privileges. This shift is most visible in California and Texas markets where competitive density pressures base admission pricing.
North America Amusement Parks Market Segmentation
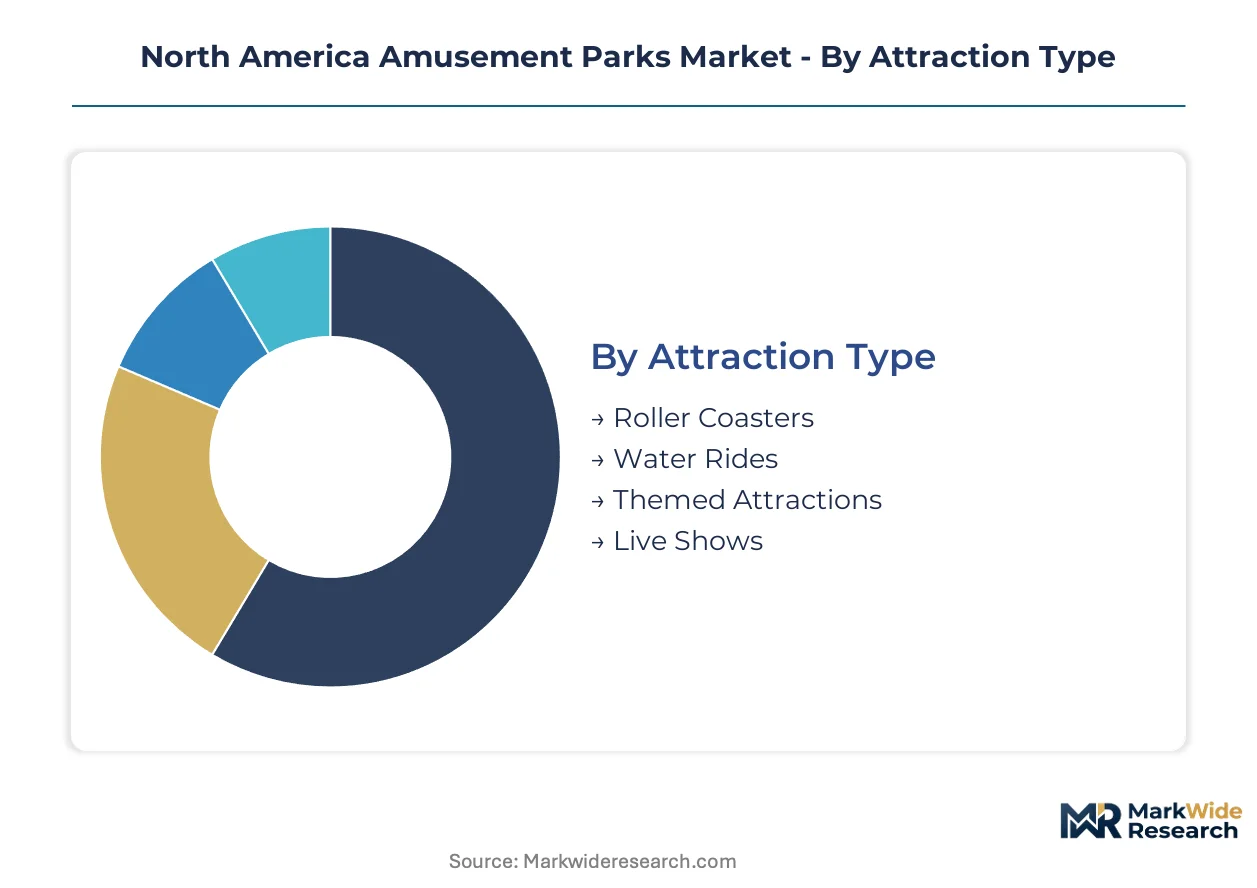
Segmentation in the North America amusement parks market reveals how capital intensity, visitor composition, and revenue architecture create distinct competitive arenas. Operators calibrate attraction portfolios and pricing structures against these dimensions to defend margin pools and extend operating calendars.
Attraction Type:
Capital allocation across ride categories determines per-visitor spending ceilings and repeat visitation rates for individual properties.
- Roller Coasters:Steel-track installations with launch systems exceeding seventy miles per hour command premium positioning and drive season pass renewals. Demand concentrates in Texas and Ohio regional chains where competitive density pressures continuous capital deployment for velocity records.
- Themed Attractions:Intellectual property-licensed immersive environments integrate set construction with character actors to maximize dwell time and ancillary spending. Florida and California destination clusters anchor demand as multi-generational families seek extended narrative experiences beyond mechanical rides.
- Water Rides:Gravity-fed flume channels offer lower capital intensity with refreshed digital projection overlays.
- Live Shows:Theatrical performance spaces extend monetizable hours without weather-dependent mechanical infrastructure.
Roller coasters command the established base. The steepest expansion runs through themed attractions.
Visitor Demographics:
Customer composition shapes everything from food service mix to merchandise licensing priorities and seasonal programming calendars.
- Families:Multi-generational units with children under fourteen drive intellectual property attachment and on-site lodging attachment rates. Demand concentrates in destination resort parks across Florida and California where multi-day ticketing architectures capture disproportionate margin pools.
- Tourists:Non-local visitors without season pass commitments generate highest per-capita spending through single-day premium ticketing and à-la-carte add-ons. Orlando and Anaheim destination clusters anchor this segment through integrated resort ecosystems.
- Teenagers:Thrill-seeking visitors prioritize velocity metrics and social media shareability.
- Corporate Groups:Private event bookings and team-building programming extend shoulder-season revenue recovery.
Families command the established base. Tourists are expanding most quickly as international visitation patterns normalize.
Operating Model:
Property configuration dictates capital structure, labor model, and exposure to weather and regulatory variables.
- Resort Parks:Integrated lodging and multi-day ticketing architectures spanning fifty-plus acres capture the highest margin pools through extended stays. Florida and California destination clusters anchor this tier where on-site hospitality services compound per-visitor yield.
- Seasonal Parks:Compressed operating calendars in northern-tier states and Canada limit revenue windows but reduce fixed cost exposure. Ohio and Pennsylvania regional operators concentrate here, competing through Halloween and winter holiday event overlays.
- Freestanding Parks:Single-property operations without captive lodging compete on regional accessibility.
- Amusement Complexes:Mixed-use developments combine parks with retail and entertainment districts.
Resort parks command the established base. Seasonal parks are gaining share fastest through event programming innovation.
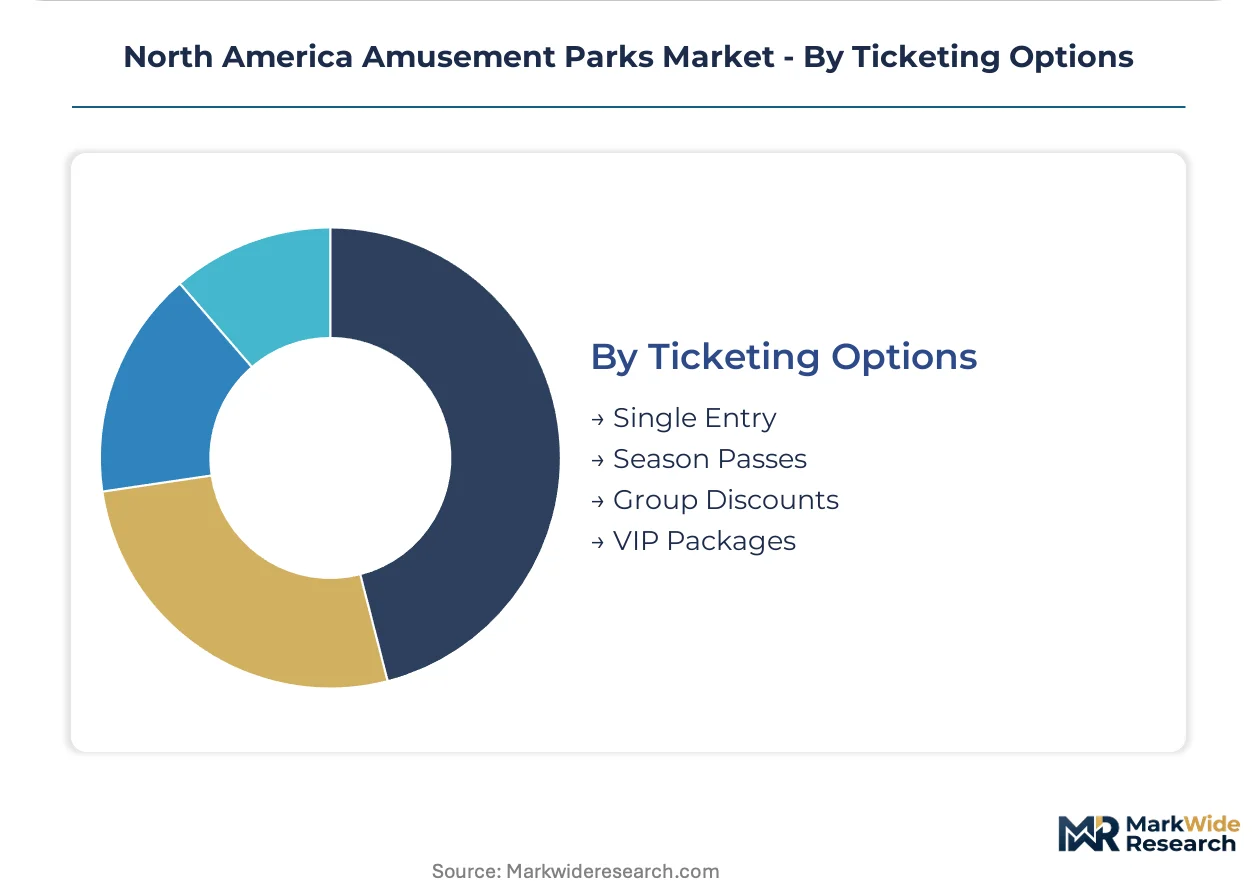
Ticketing Options:
Revenue architecture choices determine price transparency, advance commitment depth, and yield management flexibility.
- Season Passes:Membership structures with varying access tiers lock in recurring revenue and spread fixed costs across multiple visits. Texas and California markets show highest penetration as regional operators compete on value-tier positioning.
- VIP Packages:Bundled offerings combining parking, dining, and line-skipping privileges maximize per-visitor extraction from high-intent segments. Destination resort parks in Florida anchor demand for premium-tier experiences.
- Single Entry:Unbundled admission maintains price accessibility for infrequent visitors.
- Group Discounts:Volume pricing for educational institutions and corporate bookings fills shoulder-period capacity.
Season passes command the established base. VIP packages show the steepest expansion trajectory as unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America amusement parks generate substantial domestic tourism flows with limited cross-border equipment imports. Capital expenditure cycles concentrate in destination clusters where integrated resort ecosystems anchor regional visitor spending.
United States
Florida and California destination clusters drive the highest per-visitor spending through multi-day ticketing architectures. OSHA mandates annual non-destructive testing for coaster support structures, accelerating replacement cycles for aging steel-track infrastructure. Orlando and Anaheim anchor integrated resort ecosystems where on-site lodging compounds yield management capabilities.
Canada
Seasonal parks in Ontario and Quebec confront compressed operating calendars that limit revenue recovery windows. Provincial amusement ride inspection bureaus coordinate with ASTM F24 standards to govern design verification protocols. The Toronto-Niagara corridor hosts regional operators competing through Halloween and winter holiday event programming extensions.
Mexico
Central Mexico and the Yucatán Peninsula attract international visitation seeking value-tier experiences outside US pricing structures. Federal consumer protection regulations oversee ride safety inspections without equivalent OSHA enforcement stringency. Mexico City Metro anchors the largest concentration of freestanding parks competing on regional accessibility.
North America Amusement Parks Market Competitive Environment
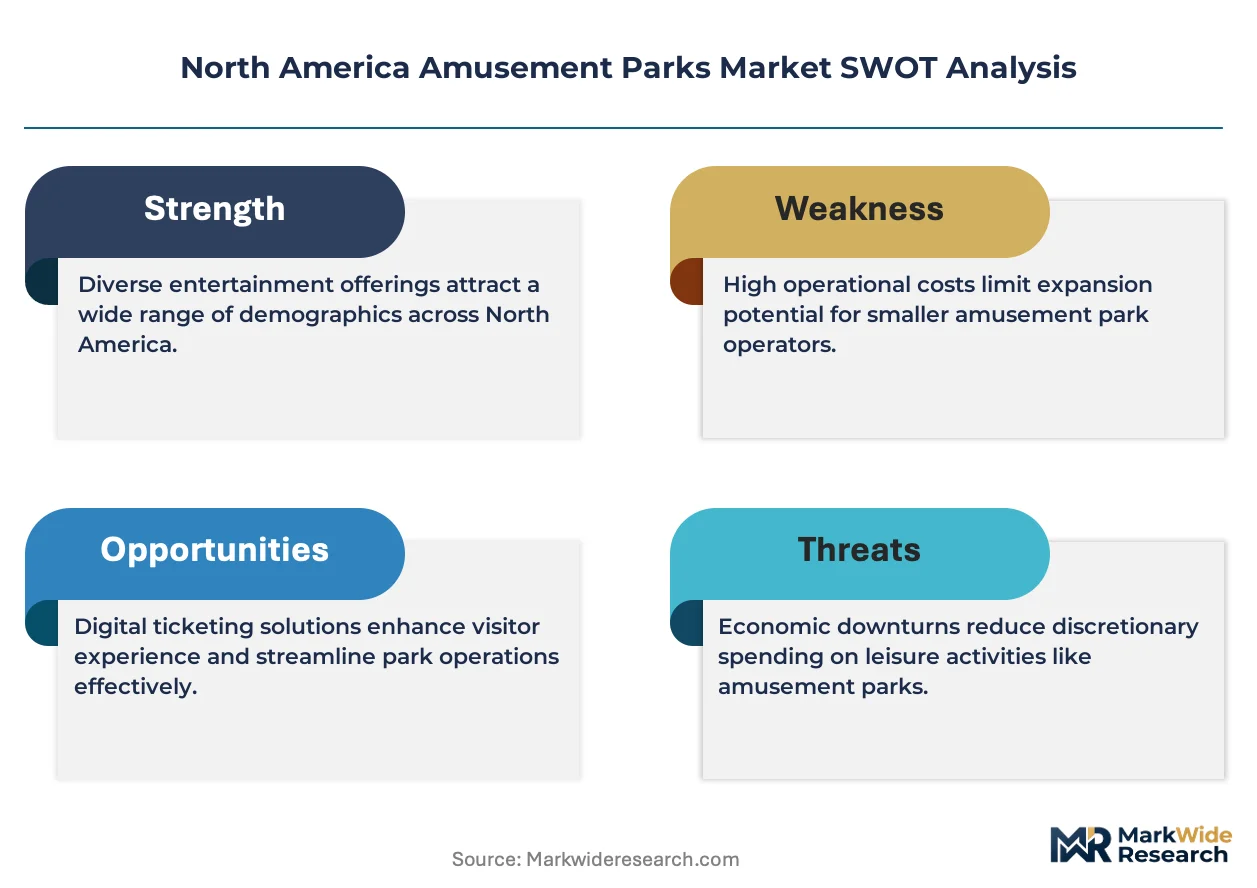
On the supply side, the industry is consolidated around integrated resort operators and fragmented across regional seasonal chains. Two strategic archetypes dominate: destination resort ecosystems with captive lodging and yield management infrastructure, and regional operators competing through thrill-ride density and value-tier season pass structures. Competitive moves concentrate on seasonal event programming expansion and mobile-first guest management platform deployment.
Within the integrated resort tier, The Walt Disney Company and Universal Destinations & Experiences exemplify yield management sophistication through proprietary wearable platforms and intellectual property licensing. Cedar Fair and Six Flags Entertainment Corporation occupy positions on the regional operator vector, competing through capital-efficient seasonal programming and multi-property market density across Ohio, Texas, and California corridors.
| Leading Market Players |
|---|
| United Parks & Resorts |
| Hershey Entertainment & Resorts Company |
| Six Flags Entertainment Corporation |
| Parques Reunidos |
| Merlin Entertainments |
| The Walt Disney Company |
| Cedar Fair |
| Premier Parks |
| Universal Destinations & Experiences |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum commodity volatility determines both the spread between premium destination resort pricing and value-tier regional admission tiers and the geographic clustering of coaster manufacturing capacity. This input cost uncertainty compresses margin visibility for operators contemplating launch system installations while concentrating fabrication contracts with suppliers possessing captive metallurgy capabilities.
Pricing Analysis
The pricing gap between immersive digital attractions and legacy mechanical ride experiences widens as virtual queue infrastructure and wearable integration separate yield-optimized resort parks from regional competitors. Three-tier pricing structure across premium VIP bundles, standard season passes, and single-day economy admission captures divergent visitor commitment levels. Price differentiation rests on intellectual property licensing depth and on-site lodging attachment. Cost compression in the value tier is intensifying because Six Flags and Cedar Fair compete on season pass density across Texas and Ohio corridors. Teenage thrill-seekers exhibit highest price sensitivity while multi-generational families booking resort packages show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates coaster component sourcing as launch system magnets and control electronics face trade policy uncertainty. Manufacturing concentrates in the United States, Germany, and Switzerland where specialized steel fabrication and precision engineering capabilities anchor production. Raw material dependencies include high-grade steel track alloys, rare-earth magnets for linear induction motors, and aluminum support structures. Single-source vulnerability concentrates in proprietary launch system technologies held by Bolliger & Mabillard and Intamin. Distribution runs through direct manufacturer-to-operator contracts with extended installation timelines and captive service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated regional operators capable of multi-property procurement leverage, fragmenting the vendor landscape for ride systems and digital infrastructure.
For Market Incumbents: Insulate proprietary yield management capabilities through deeper vertical integration into virtual queue software development and wearable hardware ecosystems. Defend margin pools by accelerating seasonal event programming extensions in northern-tier markets where compressed calendars threaten capital recovery. The emerging threat of mobile-first guest management platform commoditization demands urgent response through exclusive technology partnerships. For New Entrants and Emerging Players: Establish a beachhead in water ride hybridization where gravity-fed flume channels combined with digital projection mapping offer refreshed attraction categories without full steel coaster capital commitments. The most penetrable white space sits in secondary Texas and Pennsylvania markets where competitive density remains below Florida-California saturation. A targeted go-to-market angle emphasizes rapid-deployment seasonal overlays with lower regulatory compliance friction than permanent installations. For Investors and Strategic Acquirers: The market sits at a technology-diffusion phase that favors operators with captive digital infrastructure over pure mechanical ride portfolios. Long-term viability across the next decade hinges on intellectual property licensing depth and mobile platform penetration rather than coaster velocity records. Acquisition targets should demonstrate proven seasonal event programming capabilities and regional market density. The signal to watch is virtual queue adoption rates among regional chains previously excluded from dynamic pricing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Queue Platform Deployment | Cedar Fair's mobile-first rollout narrows the technology gap with Disney's proprietary MagicBand ecosystem. |
| Seasonal Event Programming Expansion | Halloween and winter holiday overlays extend effective operating days for Ohio and Pennsylvania regional operators. |
| Intellectual Property Licensing Agreement | Character rights negotiations with entertainment studios create unpredictable cost structures for themed attractions. |
| Water Ride Hybridization Investment | Digital projection mapping refreshes gravity-fed flume channels without full steel coaster capital commitments. |
| Proprietary Wearable Integration | The Walt Disney Company sustains yield management advantage through captive hardware and software ecosystems. |
Study Parameters
Desk research of SEC 10-K filings, ASTM F24 committee documentation, and OSHA enforcement records preceded structured interviews with amusement park operations directors, ride system procurement managers, and digital guest platform vendors. Primary fieldwork with regional chain executives in Texas, Ohio, and Pennsylvania validated capital expenditure patterns and seasonal programming calendars. Secondary sources included trade association data from the International Association of Amusement Parks and Attractions, state-level ride inspection bureau reports, and customs records for steel and aluminum import flows. Bottom-up attraction-level revenue modeling triangulated against top-down regional tourism expenditure estimates.
Assumptions held fixed across the modeling period include OSHA annual non-destructive testing mandates, ASTM F24 design verification protocols, and the concentration of destination resort demand in Florida and California clusters. Variables included steel and aluminum commodity price trajectories, virtual queue adoption rates among regional operators, and intellectual property licensing renewal terms. Segmentation dimensions spanned attraction type, visitor demographics, operating model, and ticketing architecture. CAGRs derived from logistic diffusion curves for digital guest management technology and replacement cycle analysis for aging steel-track infrastructure. Industry-specific inputs included coaster launch system installation timelines and seasonal event programming revenue contribution ratios.
Sensitivities concentrate around commodity price volatility for steel and aluminum, regulatory tightening on high-velocity launch coasters, and climate disclosure mandates affecting outdoor operating season assumptions. Forecasts reflect documented assumptions regarding technology adoption rates and capital allocation priorities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
Global Religious Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Museums Tourism Market