
 Global Database Management Software Market | 2026-2036
Global Database Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Database Management Software Market Foresight
Enterprise buyer concentration is consolidating around hyperscale cloud consumers and Fortune 500 data estates. Oracle Corporation leverages its autonomous database portfolio to anchor high-compliance workloads. Microsoft Corporation sustains integration advantages across its productivity and analytics stack. Amazon Web Services competes through purpose-built engines for transactional and analytical separation.
Database management software encompasses systems that organize, store, retrieve, and manipulate structured and unstructured data through query languages, indexing algorithms, and concurrency control mechanisms with throughput measured in transactions per second. These platforms enable operational continuity, regulatory audit trails, and real-time decision support across distributed architectures. Cloud-based deployment now captures the fastest expansion as organizations exit owned data centers, while relational databases retain the largest installed base and renewal revenue pool. NoSQL variants serve high-velocity IoT and content workloads where schema flexibility outweighs ACID consistency requirements.
The US FDA and SEC impose data integrity and auditability standards that shape validation requirements for financial and life-sciences deployments, while Europe's GDPR and EU AI Act mandate residency controls and algorithmic transparency that constrain cross-border architectures. China's MIIT and GB standards enforce localized encryption and operational sovereignty for foreign vendors. Stakeholders must monitor divergent compliance timelines as jurisdictions harden data-localization postures without harmonized interoperability frameworks.
Market Dynamics
Cloud migration mandates under Europe's GDPR and the EU AI Act are compressing replacement cycles for legacy on-premise installations, forcing enterprises to re-architect data estates around residency controls and algorithmic transparency requirements.
Growth Catalysts
- Real-Time Analytics Platforms:Financial institutions in the United States are expanding adoption of streaming transaction processing to support instant fraud detection and regulatory reporting.
- GDPR and EU AI Act:Europe's data localization mandates are accelerating hardware refresh cycles as organizations replace non-compliant legacy systems with sovereign cloud architectures.
- China's MIIT Standards:Localized encryption requirements under GB standards are driving domestic procurement of database management systems with operational sovereignty controls.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers proficient in distributed SQL and Kubernetes-native database administration constrains enterprise deployment velocity.
- Cross-Border Data Friction:Divergent residency requirements between the US CLOUD Act and China's Cybersecurity Law create architectural paralysis for multinational data pipelines.
- Legacy Integration Debt:Mainframe and COBOL-based systems in banking and insurance impose prohibitive switching costs for full-stack modernization.
Strategic Opportunities
- India's Digital Public Infrastructure:The country's account aggregator framework and open credit networks are generating demand for scalable, low-cost database solutions in fintech and government.
- Edge-Cloud Convergence:Manufacturing and logistics sectors are deploying hybrid transactional-analytical processing at plant-floor nodes to reduce latency for IoT telemetry.
- Subscription Model Penetration:Consumption-based pricing is displacing perpetual licenses in mid-market segments previously locked out of enterprise-grade capabilities.
Industry Challenges
- Multi-Cloud Skill Fragmentation:Database administrators must master divergent proprietary APIs across Amazon Web Services, Microsoft Azure, and Google Cloud Platform, diluting operational efficiency.
- Algorithmic Auditability:The EU AI Act's explainability requirements for automated decision systems are forcing engineering teams to retrofit logging and lineage capabilities into production workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Database Management Software Market |
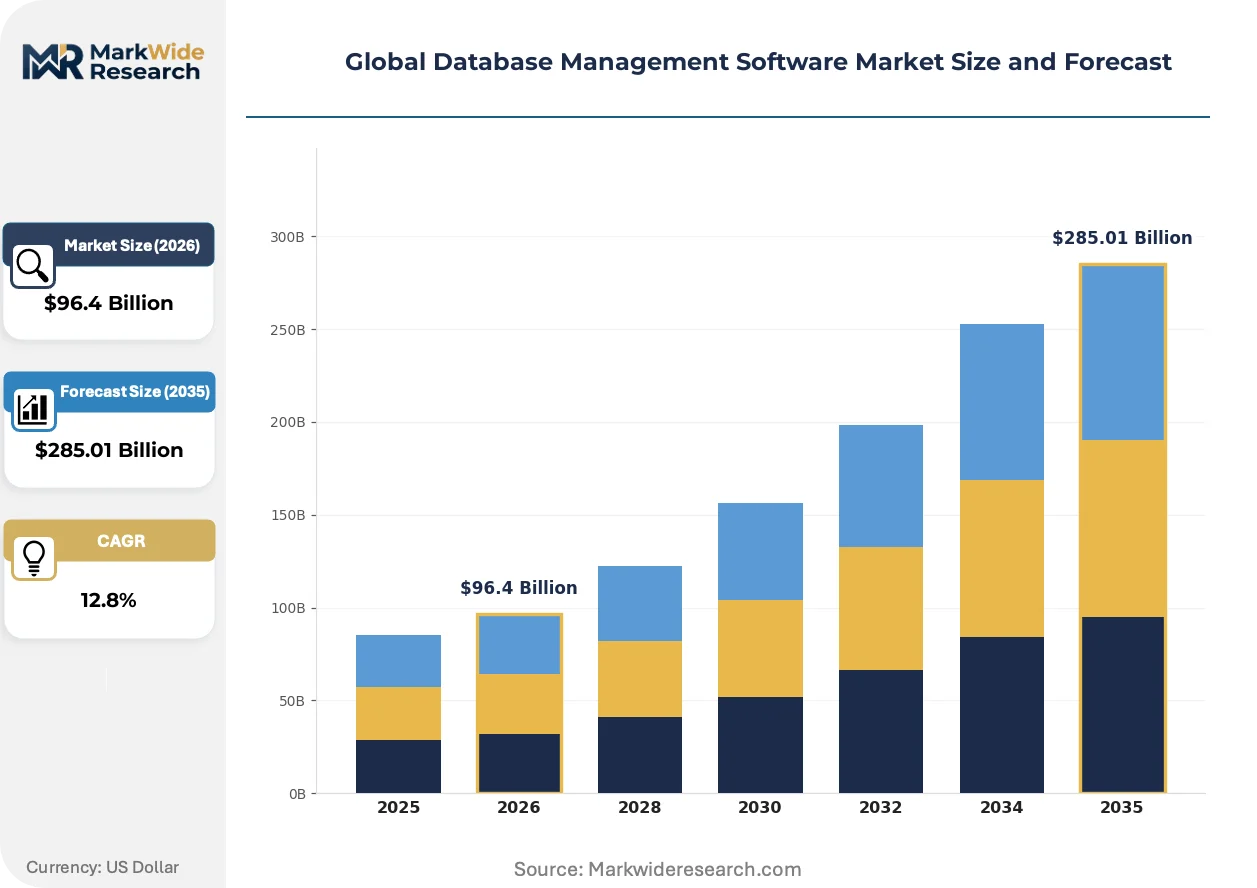
| Market Size in 2026 | $96.4 Billion |
| Market Size in 2035 | $285.01 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Mode: On-Premises, Cloud-Based, Hybrid, Edge Computing Database Type: Relational, NoSQL, NewSQL, In-Memory, Graph Application Area: ERP Systems, Customer Analytics, Fraud Detection, Supply Chain Optimization, Content Management End User: Telecom Providers, Financial Institutions, Government Agencies, Educational Institutes |
| Companies Covered | Oracle Corporation, Microsoft Corporation, IBM Corporation, Amazon Web Services, SAP SE, Google Cloud, MongoDB Inc., Snowflake Inc., Teradata Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Database Management Software Market Shifts & Advancements
Vector database architectures and AI-native indexing are reshaping how enterprises store and retrieve unstructured data, embedding search capabilities directly into operational pipelines rather than bolt-on analytics layers.
Graph database engines is converging with vector search capabilities to power recommendation systems and fraud detection networks. E-commerce platforms and payment processors are adopting these hybrid architectures within eighteen-month procurement cycles. This convergence is compressing the traditional separation between transactional records and analytical embeddings into unified query planes.
Europe's CSRD sustainability reporting mandate is requiring granular carbon accounting for data center operations and cloud workloads. Database vendors must now embed emissions telemetry into resource provisioning dashboards. Financial services and industrial conglomerates headquartered in Germany and France are prioritizing vendors with validated Scope 3 disclosure methodologies.
Buyers are unbundling database software from managed service contracts, selecting best-of-breed engines while negotiating separate infrastructure operations with systems integrators. This pattern is most pronounced in Germany's automotive supplier base and the United States' healthcare provider networks, where specialized compliance requirements favor modular procurement over vertically integrated stacks.
Global Database Management Software Market Segmentation
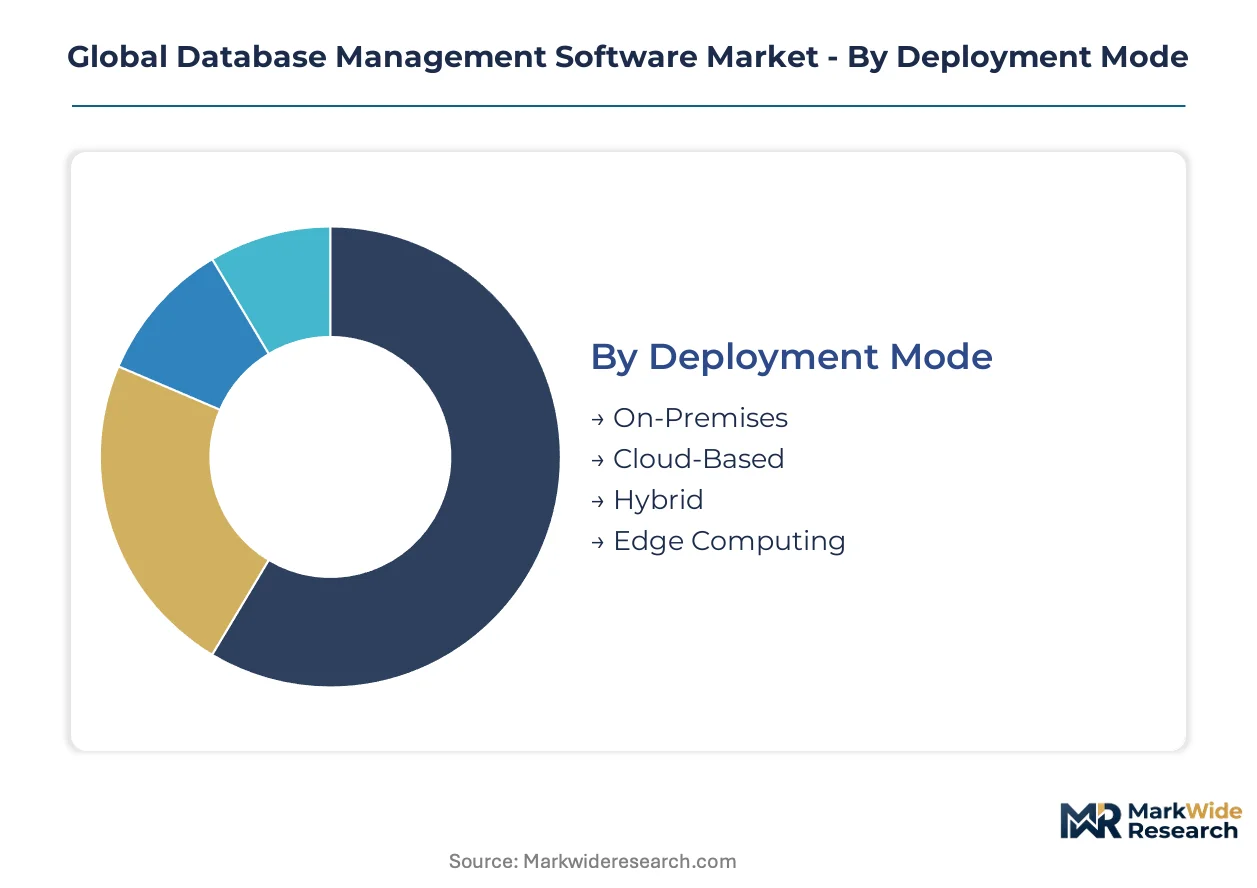
Database management software procurement diverges sharply by technical architecture and operational sovereignty requirements. Buyers segment choices around latency tolerance, compliance jurisdiction, and the trade-off between schema flexibility and transactional consistency.
Deployment Mode:
Cloud-based platforms command premium pricing and renewal velocity, while on-premises installations retain residual volume in regulated sectors.
- On-Premises:Hardware-resident installations with direct physical control over storage arrays and backup media. Financial institutions in Germany and government agencies in China under MIIT localization mandates sustain demand despite higher total cost of ownership.
- Cloud-Based:Fully managed services with elastic compute and storage provisioning across distributed availability zones. United States healthcare providers and Indian fintech startups drive fastest expansion as they exit capital-intensive data center operations.
- Hybrid:Architectures synchronizing private infrastructure with public cloud burst capacity for seasonal workloads. Japanese automotive manufacturers deploy these configurations to protect intellectual property while leveraging cloud analytics.
- Edge Computing:Distributed nodes processing telemetry at plant-floor or retail-point locations before cloud consolidation. Manufacturing clusters in Bavaria and logistics hubs in the Netherlands adopt these for sub-10-millisecond response requirements.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
Database Type:
Relational engines anchor enterprise revenue through maintenance renewals, while specialized architectures capture greenfield workloads.
- Relational:ACID-compliant systems using tabular schemas and SQL query interfaces with decades of tooling ecosystem maturity. Banking core systems in the United States and insurance policy administration in France retain these for audit trail requirements.
- NoSQL:Schema-flexible document, key-value, and wide-column stores optimized for horizontal scaling across commodity hardware. Chinese e-commerce platforms and Brazilian content distributors deploy these for high-velocity unstructured data ingestion.
- NewSQL:Distributed SQL engines combining transactional consistency with cloud-native elasticity. Fintech startups in India and payment processors in Singapore select these to bypass traditional sharding complexity.
- In-Memory:DRAM-resident processing eliminating disk I/O latency for real-time analytics and high-frequency trading. Securities exchanges in London and algorithmic trading desks in Chicago represent concentrated demand.
- Graph:Native storage of node-edge relationships enabling traversal queries for network analysis and recommendation engines. Fraud detection units at Australian banks and social platforms in South Korea leverage these for relationship mapping.
Relational systems still generate the largest renewal pools. Graph and vector convergence is climbing the fastest.
Application Area:
Operational systems attract conservative procurement cycles, while analytical and security applications command innovation budgets.
- ERP Systems:Integrated financial, human capital, and supply chain modules requiring transactional integrity across multi-module workflows. German industrial conglomerates and Mexican manufacturing exporters sustain this segment through multi-year implementation contracts.
- Customer Analytics:Unified profile repositories and behavioral segmentation engines feeding personalization pipelines. Retail chains in the United Kingdom and telecommunications operators in Spain invest here to reduce churn and increase basket values.
- Fraud Detection:Real-time pattern recognition across transaction streams with millisecond decision latency. Payment networks in the United States under SEC oversight and digital wallet providers in Indonesia deploy specialized graph-vector hybrid architectures.
- Supply Chain Optimization:Multi-echelon inventory and logistics coordination across supplier networks with demand forecasting integration. Automotive suppliers in Japan and pharmaceutical distributors in Switzerland prioritize these for resilience planning.
- Content Management:Unstructured data repositories for documents, media assets, and collaborative workspaces with versioning and access control. Publishing houses in Canada and government archives in Australia represent steady demand.
ERP Systems absorb the largest implementation budgets. Fraud Detection is expanding most quickly as real-time requirements harden.
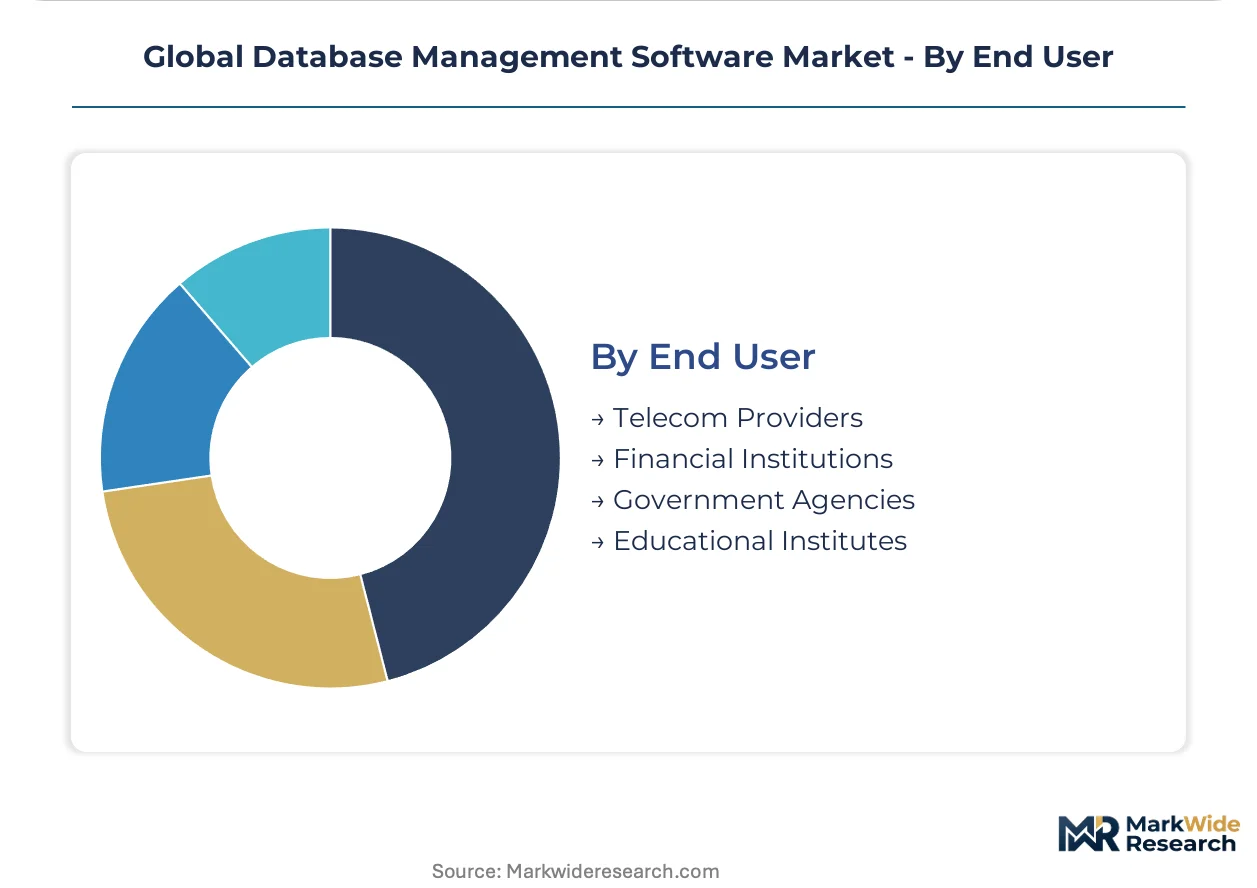
End User:
Regulated industries sustain premium pricing tolerance, while emerging digital infrastructure creates volume opportunities at lower price points.
- Telecom Providers:Subscriber data management, billing mediation, and network function virtualization requiring petabyte-scale throughput. Operators in South Korea and Saudi Arabia modernize these systems to support 5G service orchestration.
- Financial Institutions:Trading platforms, risk engines, and regulatory reporting with sub-second latency and immutable audit trails. Investment banks in New York and insurance groups in Zurich dominate procurement for high-compliance workloads.
- Government Agencies:Citizen identity systems, tax administration, and national statistics with sovereignty and interoperability mandates. India's digital public infrastructure and Brazil's federal data integration projects drive significant deployment.
- Educational Institutes:Student information systems, research data repositories, and learning management platforms with moderate scale and budget constraints. Universities in the Netherlands and technical colleges in Vietnam represent growing adoption.
Financial Institutions anchor premium segment profitability. Government Agencies are gaining share fastest through digital sovereignty investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in the United States deploy streaming analytics at scale, while China's MIIT localization mandates force architectural divergence between sovereign and multinational data estates.
United States
Investment banks in New York and healthcare providers across the Midwest drive demand for real-time fraud detection and HIPAA-compliant data lakes. The SEC and FDA impose immutable audit trail requirements that favor established relational engines with decades of validation documentation. Silicon Valley hyperscalers and Boston-area biotech clusters anchor cloud migration velocity.
China
Domestic e-commerce platforms and state-owned banks require petabyte-scale NoSQL ingestion for high-velocity transaction streams. MIIT's GB standards mandate localized encryption and operational sovereignty, excluding foreign vendors from critical infrastructure procurement. Beijing and Shanghai metropolitan clusters concentrate engineering talent for distributed SQL development.
Germany
Automotive suppliers in Bavaria and industrial conglomerates in North Rhine-Westphalia prioritize sovereign cloud architectures under GDPR and CSRD carbon accounting mandates. The country's federal data protection authority enforces strict residency controls for cross-border analytics. Frankfurt's financial district sustains premium pricing tolerance for high-compliance database workloads.
India
Fintech startups in Mumbai and Bangalore adopt NewSQL engines to bypass traditional sharding complexity for open credit networks. RBI guidelines and the account aggregator framework generate demand for scalable, low-cost transactional infrastructure. Hyderabad's technology corridor hosts expanding delivery centers for database administration services.
United Kingdom
Retail chains and telecommunications operators in London invest in customer analytics platforms to reduce churn and personalize engagement. The Financial Conduct Authority's operational resilience requirements shape procurement criteria for trading infrastructure. Edinburgh's financial services cluster maintains conservative refresh cycles for core banking systems.
Global Database Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and database architectures. The market structure concentrates around three tiers: hyperscale cloud providers with integrated analytics stacks, established enterprise software vendors with decades of maintenance revenue, and venture-backed challengers attacking vector and graph database niches. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized sovereign cloud offerings.
Within the established enterprise tier, Oracle Corporation and Microsoft Corporation exemplify platform consolidation strategies that bundle database engines with adjacent productivity and infrastructure software. Amazon Web Services occupies a distinct position as a cloud-native provider with purpose-built transactional and analytical separation. These three anchors represent divergent bets on how enterprises will balance compliance requirements against cloud migration imperatives over the forecast window.
| Leading Market Players |
|---|
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| SAP SE |
| Google Cloud |
| MongoDB Inc. |
| Snowflake Inc. |
| Teradata Corporation |
| Others |
Supply & Pricing Matrix
DRAM spot price indices and silicon wafer contract benchmarks cascade through database hardware procurement into tiered SaaS subscription structures, compressing margins for on-premise vendors while amplifying pricing power for hyperscale cloud providers with captive infrastructure.
Pricing Analysis
Capacity additions in United States hyperscale regions are reshaping price floors for managed database services, forcing legacy vendors toward consumption-based models. Three-tier pricing structure across premium sovereign-cloud, standard multi-tenant, and economy spot-instance levels dominates procurement. Price differentiation rests on compliance certification grade and dedicated tenancy guarantees. Cost compression in mid-market relational migrations is intensifying because Kubernetes-native alternatives displace per-core licensing. Indian fintech startups exhibit highest price sensitivity; German automotive suppliers tolerate premium sovereign-cloud rates.
Supply Chain Analysis
Freight cost volatility for specialized server hardware from Taiwan and South Korea is amplifying regional delivery premiums for edge-computing nodes. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; storage media production centers on Japan, South Korea, and China. Raw material dependencies span NAND flash, DDR modules, and custom ASICs. Single-source vulnerability in advanced node lithography equipment constrains supply elasticity. Distribution runs through direct hyperscaler marketplaces and systems integrator channels with compliance certification overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
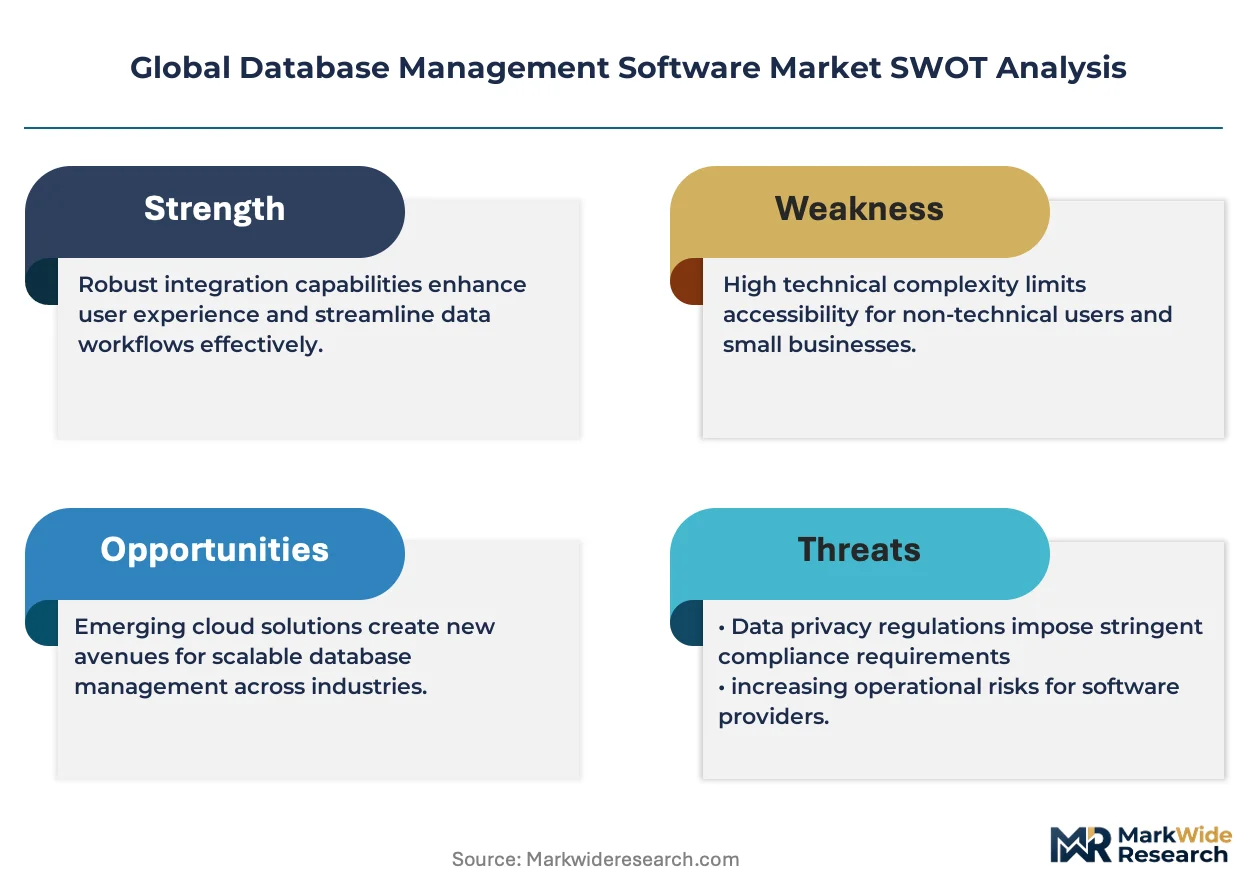
Margin expansion in database management software hinges on consumption-based pricing penetration and sovereign-cloud premium tier capture, with cost-down pressure from open-source query engine commoditization.
For Market Incumbents: Acquire vector database specialist teams to anchor AI-native indexing capabilities against venture-backed challengers. Defensive consolidation demands backward integration into Kubernetes storage orchestration and certification investment for EU AI Act algorithmic auditability. Channel control through exclusive systems integrator partnerships protects high-compliance workload pricing power. For New Entrants and Emerging Players: Enter via India's account aggregator framework and open credit network infrastructure, where legacy vendor presence remains thin. White-space targets include edge-cloud hybrid transactional-analytical processing for manufacturing telemetry and subscription-based NewSQL penetration in Southeast Asian fintech. Go-to-market angle emphasizes GDPR-compliant sovereign deployment without hyperscaler lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with graph-vector convergence specialists serving real-time fraud detection networks. Long-term viability favors platforms with validated Scope 3 carbon accounting methodologies under Europe's CSRD mandate. Watch hyperscaler capex allocation shifts toward purpose-built database engines as inflection indicator for architectural consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Systems Integrators | Unlocks sovereign-cloud procurement pathways for German automotive and French industrial conglomerates under GDPR. |
| Acquisition of Vector Database Specialist | Accelerates AI-native indexing capabilities for e-commerce recommendation engines and payment fraud detection. |
| Geographic Expansion via Localized Sovereign Cloud | Captures China MIIT-compliant procurement and India digital public infrastructure mandates. |
| Platform Integration with Analytics Stack | Reinforces Microsoft-style ecosystem lock-in across productivity and business intelligence workflows. |
| Product Launch for Edge-Cloud Convergence | Addresses sub-10-millisecond latency requirements in Bavarian manufacturing and Dutch logistics hubs. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers, hyperscaler capex disclosures, and regulatory filing analysis — were reconciled against secondary validation from SEC filings, EU AI Act implementation guidance, and MIIT localization standards. Database administrators, platform engineers, and channel partners at systems integrators provided operational deployment data. Bottom-up triangulation across organization-size cohorts and top-down reconciliation against cloud infrastructure spending estimates anchored volume projections.
Data-stream reconciliation across deployment mode, database architecture type, vertical industry, and regional compliance cluster shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity modeling of replacement-cycle compression under GDPR and EU AI Act mandates. Forecast inputs incorporated edge-computing node proliferation rates and sovereign-cloud procurement velocity in Germany and China.
Inputs from hyperscaler earnings disclosures and national regulator guidance documents were available through the study window; gaps in private-company NewSQL vendor financials introduce uncertainty bands around emerging-player market share trajectories. Forecasts reflect assumptions regarding compliance timeline adherence and cross-border data architecture feasibility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Global Call Tracking Software Market
Software & Services
Interior Design Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Optical Design Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Custom Software Development Market
Software & Services
Mobile Application Stores Market
Software & Services
Global Political Campaign Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Global Brand Management Software Market