
 Lease Accounting and Management Software Market | 2026-2036
Lease Accounting and Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lease Accounting and Management Software Market Outlook
Cloud infrastructure is consolidating on-premise data center economics across the lease accounting stack. MRI Software leverages deep property management integration to anchor enterprise accounts with bundled compliance workflows. FinQuery sustains R&D intensity in automated lease abstraction, while LeaseAccelerator competes through federal sector specialization and GSA schedule positioning.
Lease accounting and management software encompasses platforms that automate lease data extraction, amortization scheduling, and dual-ledger reporting across IFRS 16 and ASC 842 standards, typically delivered through multi-tenant SaaS architectures with API connectivity to ERP systems. Cloud-based deployment dominates new procurement as finance teams prioritize remote accessibility and automatic regulatory updates, while on-premise installations retain share in highly regulated national security and banking environments where data residency requirements constrain vendor selection. The compliance standard dimension—spanning FASB, IFRS, and jurisdiction-specific interpretations—represents the highest-margin segment as configuration complexity justifies premium pricing and recurring professional services.
The SEC enforces US GAAP lease disclosure timelines, while the IASB governs IFRS 16 recognition standards across European and Asian capital markets. FASB's ongoing agenda review of private company effective dates shapes mid-market vendor roadmaps and customer migration schedules. Stakeholders must monitor convergence divergence between US and international lease capitalization thresholds as a determinant of platform localization investments and cross-border product architecture decisions.
Market Dynamics
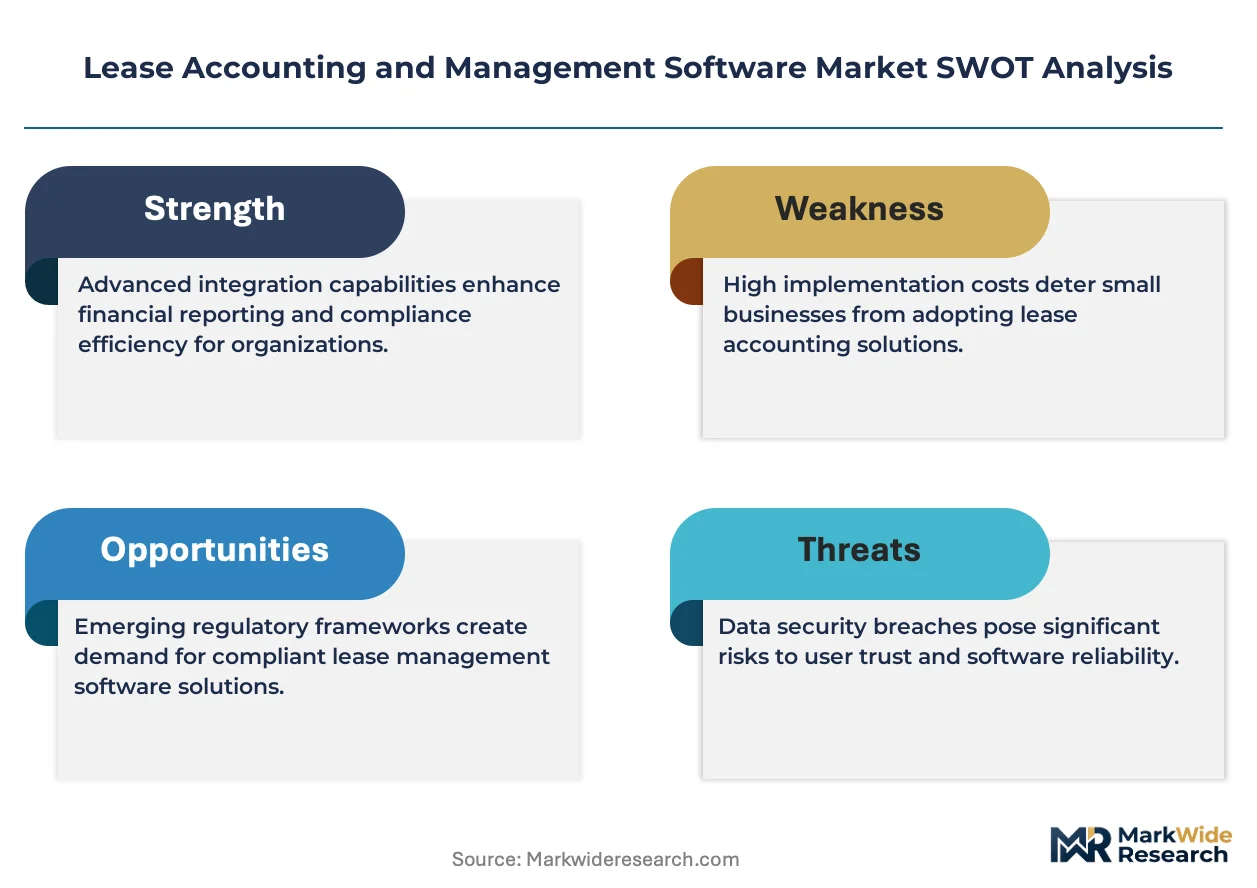
FASB ASC 842 and IFRS 16 lease capitalization mandates are compressing procurement cycles as finance teams replace spreadsheet-based compliance with automated amortization engines and dual-ledger reporting platforms.
Growth Catalysts
- SEC disclosure enforcement:US public company filing deadlines accelerate platform replacement of manual lease tracking systems.
- Retail and logistics chains:Corporate real estate departments automate lease abstraction to manage multi-location portfolios under compressed audit timelines.
- Cloud infrastructure economics:Multi-tenant SaaS architectures reduce total cost of ownership versus on-premise deployments and enable automatic regulatory updates.
Market Restraints
- Data residency constraints:National security and banking environments in the United States block cloud migration, preserving legacy on-premise vendor lock-in.
- Configuration complexity:Jurisdiction-specific interpretations of IFRS 16 and ASC 842 require premium professional services, inflating implementation costs.
- Mid-market saturation risk:Private company effective date delays under FASB agenda review stall upgrade cycles among smaller enterprise accounts.
Strategic Opportunities
- Federal sector specialization:GSA schedule positioning captures defense and civilian agency procurement vehicles with specialized security clearances.
- API-first ERP integration:Real-time connectivity to SAP and Oracle systems displaces batch-file imports and reduces reconciliation overhead.
- Automated lease abstraction R&D:Natural language processing of unstructured lease documents extracts critical dates and clauses without manual data entry.
Industry Challenges
- Technical accounting expertise scarcity:Finance teams lack personnel trained in both lease standards and software configuration, extending implementation timelines.
- Legacy ERP integration friction:Custom-coded on-premise systems require expensive middleware development to achieve API connectivity with modern platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lease Accounting and Management Software Market |
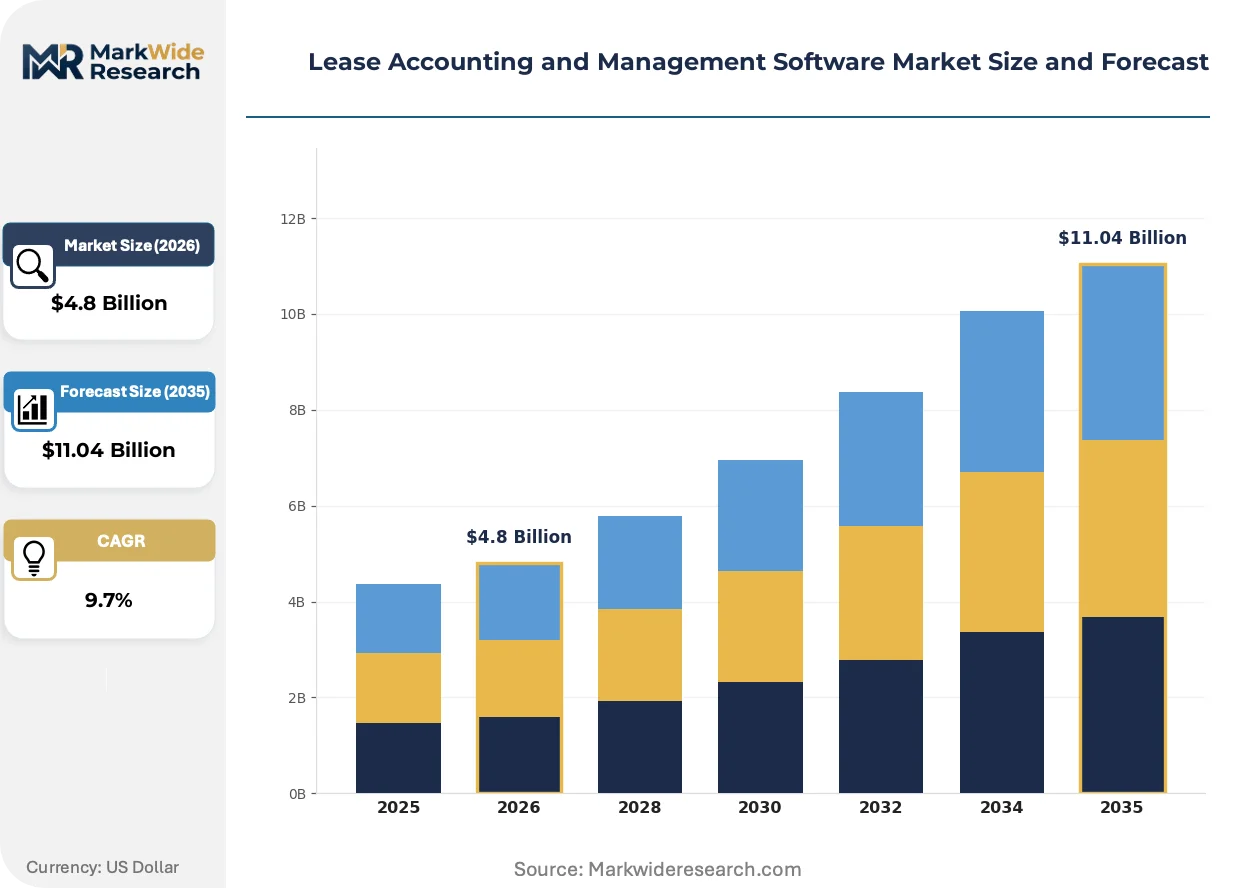
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Custom Solutions User Type: Small Businesses, Enterprises, Public Sector, Nonprofits Deployment Model: Single-Tenant, Multi-Tenant, Private Cloud, Public Cloud Compliance Standard: IFRS, GAAP, FASB, ASC 842 |
| Companies Covered | MRI Software, Trullion, FinQuery, Planon, LeaseAccelerator, Visual Lease, Nakisa, Sage Intacct, LeaseQuery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lease Accounting and Management Software Market Strategic Shifts
Lease accounting software is converging with broader financial planning systems as buyers demand unified data models spanning compliance, forecasting, and scenario analysis.
Natural language processing is electrifying lease document ingestion by extracting critical terms from PDF and scanned agreements without manual transcription. Mid-market finance teams adopt these tools to compress month-end close timelines. The technology is electrifying competitive positioning by collapsing the traditional trade-off between abstraction accuracy and implementation speed.
IASB IFRS 16 recognition standards govern capital market disclosures across European and Asian jurisdictions, forcing platform vendors to maintain parallel calculation engines. This regulatory fragmentation inflates R&D budgets and complicates product roadmaps. European multinational corporations respond by prioritizing vendors with proven dual-ledger capabilities and localized support infrastructure.
Subscription pricing models displace perpetual license structures as CFOs prioritize operational expenditure treatment and predictable cash outflows. Software vendors restructure revenue recognition and sales compensation to align with annual recurring revenue metrics. This shift concentrates most visibly in United States mid-market accounts where private equity ownership demands SaaS-like financial profiles.
Lease Accounting and Management Software Market Segmentation
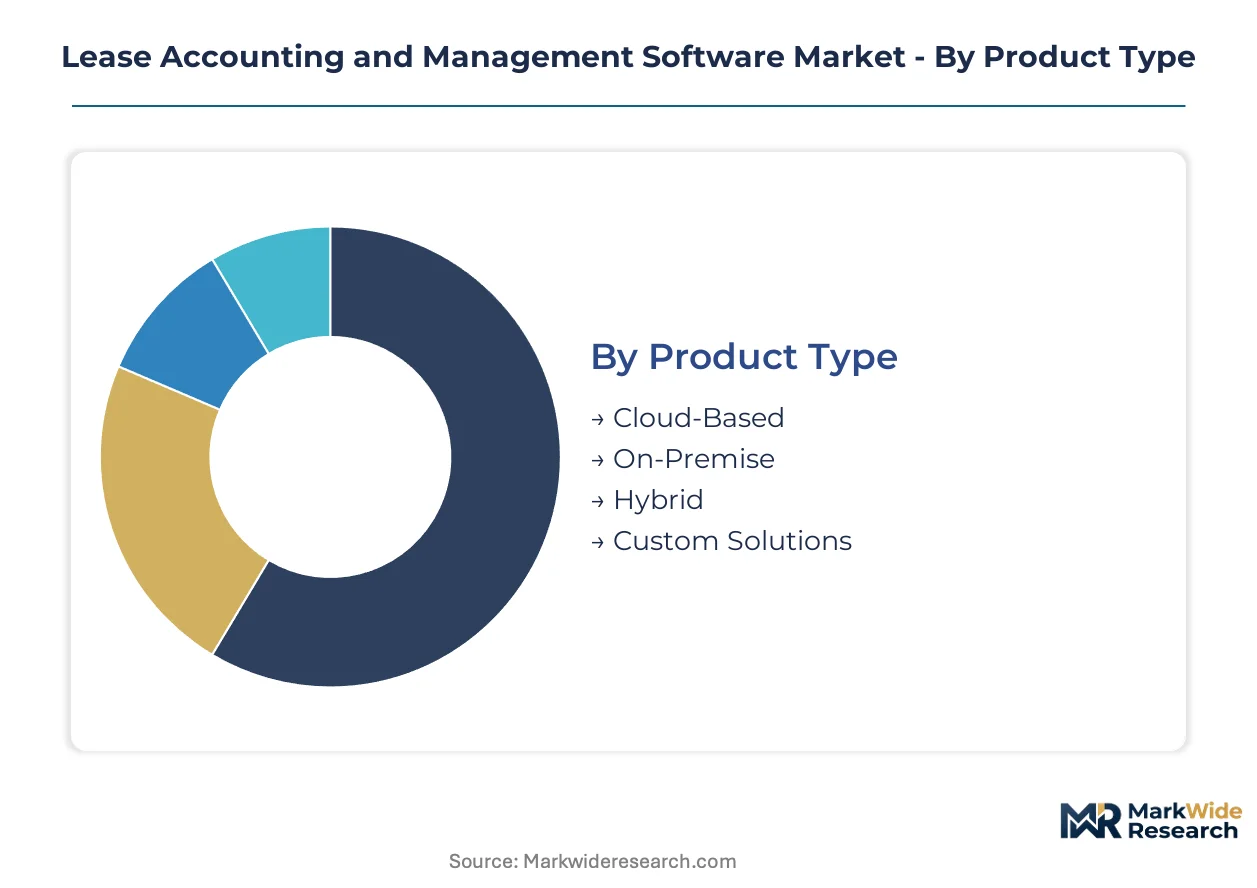
Segmentation in lease accounting software reveals how compliance mandates and deployment constraints fragment procurement patterns across buyer types. Vendors configure pricing and service tiers around certification complexity rather than pure scale.
Product Type:
Cloud-based deployments carry lighter SOC 2 and ISO 27001 certification burdens than on-premise alternatives requiring customer-managed security audits.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic ASC 842 and IFRS 16 updates through centralized infrastructure. Retail chains in the United States prioritize these platforms to compress month-end close timelines across distributed real estate portfolios.
- On-Premise:Licensed software installed within customer data centers satisfies data residency requirements in national security and federal banking environments. The United States Department of Defense and civilian agencies with classified lease portfolios mandate these deployments despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive lease data through on-premise nodes while pushing analytics to cloud tiers.
- Custom Solutions:Bespoke builds address idiosyncratic portfolio structures or legacy ERP integration requirements.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
User Type:
Enterprise accounts absorb the steepest professional services costs due to multi-entity consolidation requirements, while public sector buyers face specialized FedRAMP and CMMC compliance thresholds.
- Enterprises:Multi-subsidiary corporations with lease counts exceeding ten thousand agreements drive platform complexity. These buyers demand dual-ledger reporting engines capable of simultaneous ASC 842 and IFRS 16 calculation across operating and finance lease classifications.
- Small Businesses:Sub-threshold lease portfolios with fewer than one hundred contracts. United States mid-market companies in this tier delay upgrades pending FASB private company effective date clarifications.
- Public Sector:Federal, state, and local government agencies subject to GSA schedule procurement and specialized security clearance requirements.
- Nonprofits:Mission-driven organizations with donated property portfolios and grant-funded lease obligations.
Dominating procurement value: Enterprises. Expanding most quickly: Public Sector.
Deployment Model:
Single-tenant isolation commands premium pricing for buyers with heightened data segregation requirements, while multi-tenant economics concentrate vendor R&D investment.
- Multi-Tenant:Shared infrastructure pools enable automatic regulatory updates and lowest per-seat pricing. This model captures the majority of new United States mid-market deployments where CFOs prioritize predictable operational expenditure treatment.
- Single-Tenant:Dedicated instance isolation satisfies stringent audit requirements in healthcare and financial services. HIPAA-covered entities and SEC-registered investment advisors specify these deployments to enforce access logging and encryption key control.
- Private Cloud:Customer-controlled virtualized environments within third-party data centers.
- Public Cloud:Standardized hyperscaler infrastructure without tenant-level customization.
Highest volume concentration: Multi-Tenant. Steepest expansion trajectory: Private Cloud.
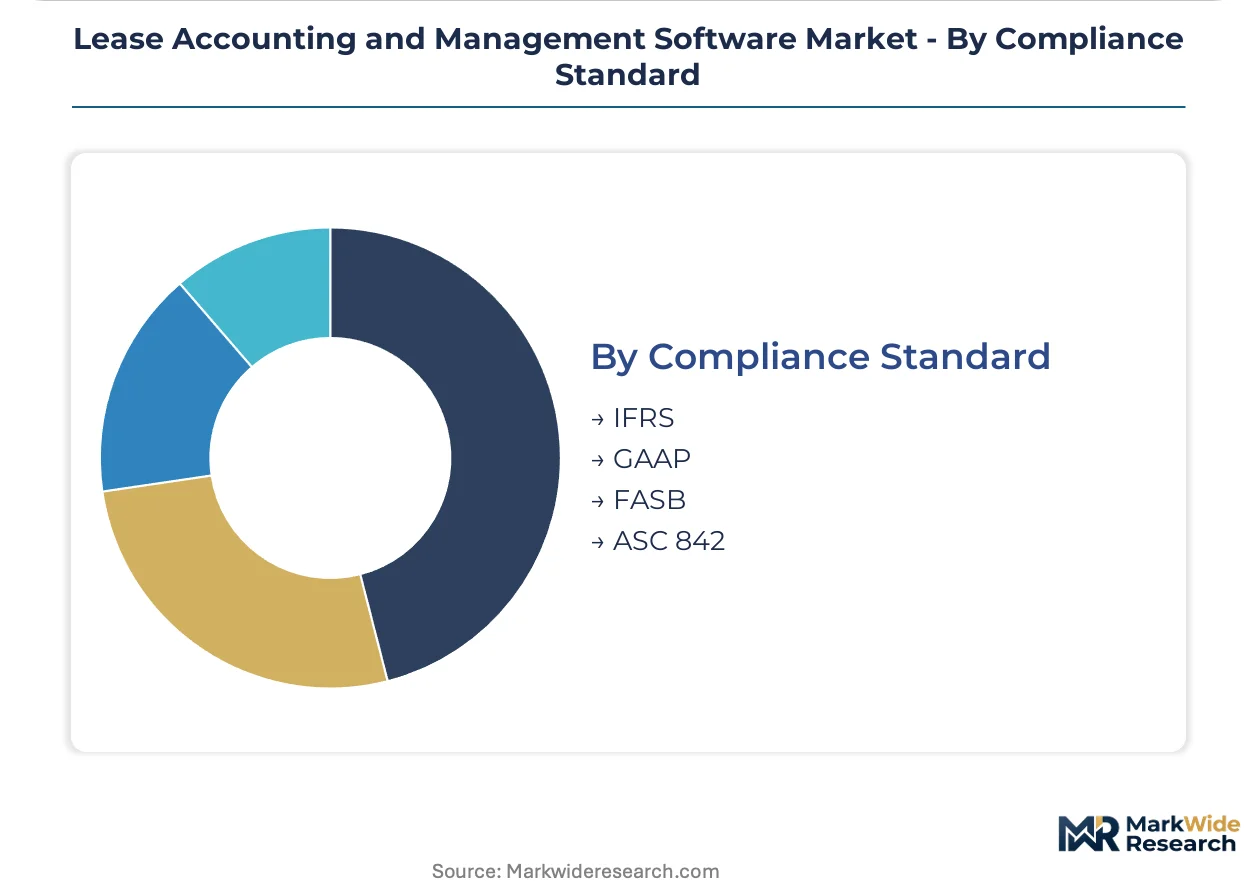
Compliance Standard:
FASB ASC 842 and IFRS 16 represent the core certification dual that vendors must maintain, with jurisdiction-specific interpretations inflating configuration complexity and professional services attach rates.
- ASC 842:The FASB lease capitalization standard governing United States public company financial statements. SEC enforcement of disclosure timelines accelerates replacement of spreadsheet-based compliance with automated amortization engines.
- IFRS 16:The IASB recognition standard applicable across European and Asian capital markets. European multinational corporations prioritize vendors with proven dual-ledger capabilities to avoid parallel system maintenance.
- GAAP:Broader United States generally accepted accounting principles frameworks incorporating lease treatment.
- FASB:Standard-setting body whose ongoing agenda review shapes vendor roadmaps and customer migration schedules.
Largest installed base: ASC 842. Gaining share fastest: IFRS 16.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where public company compliance deadlines drove initial platform deployments and mid-market expansion now sustains upgrade cycles. Corporate real estate departments across retail and logistics chains in Germany and Japan are accelerating adoption of automated lease abstraction tools.
United States
SEC disclosure enforcement accelerates replacement of spreadsheet-based compliance with automated amortization engines. FASB ASC 842 mandates reshape software procurement criteria for public companies. Corporate headquarters clusters in New York and Chicago drive enterprise account concentration for dual-ledger reporting platforms.
Germany
European multinational corporations prioritize vendors with proven dual-ledger capabilities to avoid parallel system maintenance. IFRS 16 recognition standards govern capital market disclosures across German capital markets. Frankfurt's financial services concentration anchors demand for localized support infrastructure and compliance configuration.
Japan
Tokyo-based corporate real estate departments automate lease abstraction to manage multi-location portfolios under compressed audit timelines. METI oversight shapes enterprise software procurement standards for lease management. Osaka and Nagoya manufacturing hubs generate mid-market demand for cloud-based deployment models.
United Kingdom
London's professional services sector drives demand for automated lease data extraction across client advisory engagements. IFRS 16 and UK-specific interpretations inflate configuration complexity and professional services attach rates. Manchester and Birmingham regional offices sustain mid-market upgrade cycles for SaaS platforms.
India
Bangalore and Hyderabad technology campuses generate demand for API-first ERP integration with SAP and Oracle systems. SEBI disclosure requirements for listed companies accelerate compliance platform adoption. Mumbai financial services clusters prioritize cloud-based deployments for remote accessibility and automatic regulatory updates.
Lease Accounting and Management Software Market Competitive Environment
API-first ERP integration dominates the current landscape as vendors compete to displace batch-file imports and reduce reconciliation overhead. The vendor base stratifies across three tiers: enterprise suite incumbents with deep property management integration, specialized lease accounting pure-plays with automated abstraction R&D intensity, and federal sector specialists with GSA schedule positioning. Consolidation pressures favor vendors bundling compliance workflows with broader real estate management capabilities. Technology licensing and strategic partnerships represent the dominant competitive moves as firms seek to accelerate natural language processing capabilities for unstructured lease document ingestion.
Within the enterprise suite tier, MRI Software anchors market positioning through deep property management integration that bundles compliance workflows. FinQuery occupies a position exemplifying automated lease abstraction R&D intensity. LeaseAccelerator represents federal sector specialization with GSA schedule positioning that captures defense and civilian agency procurement vehicles.
| Leading Market Players |
|---|
| MRI Software |
| Trullion |
| FinQuery |
| Planon |
| LeaseAccelerator |
| Visual Lease |
| Nakisa |
| Sage Intacct |
| LeaseQuery |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure costs cascade through subscription pricing tiers as hyperscaler compute and storage rates anchor SaaS vendor cost bases, with United States-based finance teams absorbing premium per-seat rates for FedRAMP-authorized instances while mid-market buyers trade data residency for standard multi-tenant economics.
Pricing Analysis
Volume concentration in multi-tenant SaaS deployments compresses per-seat margins while single-tenant isolation commands premium pricing for HIPAA-covered healthcare entities and SEC-registered investment advisors. Price differentiation hinges on FedRAMP authorization tier and API integration complexity, with federal sector buyers least sensitive due to GSA schedule procurement vehicles. Pricing pressure intensifies in the United States mid-market as private equity-owned accounts demand SaaS-like operational expenditure treatment, squeezing vendor revenue recognition flexibility.
Supply Chain Analysis
Freight and data transit costs escalate for hybrid deployments routing sensitive lease data through on-premise nodes while analytics tiers push to cloud infrastructure concentrated in United States, Ireland, and Singapore hyperscaler regions. Software vendors draw from specialized labor pools in Bangalore and Hyderabad for NLP engineering talent, with single-source vulnerability in natural language processing chipsets from Taiwan and South Korea. Distribution runs through direct enterprise sales teams for federal accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical integration into automated lease abstraction capabilities as vendors race to control NLP document ingestion pipelines and displace manual data entry costs from professional services margins.
For Market Incumbents: Deploy API-first ERP integration teams to deepen SAP and Oracle connectivity moats against emerging pure-plays. Consolidate automated abstraction R&D through captive NLP engineering centers in India to offset talent scarcity in technical accounting domains. Federal sector specialization with GSA schedule positioning defends against civilian agency procurement vehicle erosion. For New Entrants and Emerging Players: Regional system integrators represent the fastest channel to mid-market accounts stalled on FASB private company effective date clarifications. Target United States nonprofit and sub-threshold lease portfolio segments with lightweight cloud deployments priced below enterprise suite bundling. White-space exists in automated abstraction for non-English lease documents across European multinational implementations. For Investors and Strategic Acquirers: FASB agenda review publication timing is the leading indicator that mid-market upgrade cycles will accelerate or stall. Long-term viability favors vendors with proven dual-ledger ASC 842 and IFRS 16 engines rather than single-standard pure-plays facing regulatory fragmentation R&D inflation. Acquisition targets should demonstrate federal sector revenue concentration or API integration density with hyperscaler marketplaces.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Lease Abstraction R&D | NLP document ingestion collapses implementation timelines for retail chain real estate departments. |
| FedRAMP Authorization Investment | United States Department of Defense procurement vehicles require authorized cloud infrastructure deployment. |
| API-First ERP Integration | Real-time SAP and Oracle connectivity displaces batch-file reconciliation overhead in enterprise accounts. |
| Dual-Ledger Compliance Engine | Simultaneous ASC 842 and IFRS 16 calculation captures European multinational corporation demand. |
| Channel Partner Expansion | Regional system integrators accelerate mid-market penetration where direct sales economics fail. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews of CFOs, corporate real estate directors, technical accounting consultants, and software procurement officers at retail chains and logistics operators. SEC disclosure databases, FASB agenda documentation, GSA schedule award records, and hyperscaler capex disclosures supplied quantitative benchmarks. Bottom-up lease count aggregation and top-down software spend estimates were triangulated against vendor revenue disclosures.
Segment-level modeling tracked deployment model, organization size, vertical concentration, integration complexity, and regional adoption pattern across the projection horizon. CAGRs were derived from regression analysis against compliance deadline enforcement intensity and cloud migration rates. Forecast inputs included FASB private company effective date scenarios and federal sector procurement velocity indices.
Caveats apply where FASB agenda delays or IFRS 16 jurisdictional interpretation divergences could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Idea Management Software Market
Software & Services
Sports League Management Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Webcasting Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Sales Force Automation Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Global Open Source Services Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
ID Photo Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Global Test Data Management Market
Software & Services
Global Data Warehouse Software Market
Software & Services
Global Local SEO Software Market
Software & Services
CGI Software Market
Software & Services
Middle East and Africa Digital Signage Software Market