
 Global Call Tracking Software Market | 2026-2036
Global Call Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Call Tracking Software Market Foresight
The capability gap between cloud-native architectures and legacy on-premises systems is reorganizing competitive dynamics across the sector. Invoca leverages AI-powered conversation intelligence to anchor its position in enterprise sales environments. CallRail competes through accessible pricing and deep integration with Google Marketing Platform, while Phonexa Holdings LLC extends its footprint with bundled lead distribution and call tracking suites for insurance and financial verticals.
Call tracking software captures, routes, and analyzes inbound telephone interactions to attribute revenue to specific marketing campaigns, typically processing caller ID, duration, geographic origin, and keyword-level source data through dynamic number insertion. Cloud-based deployment leads segment composition due to minimal infrastructure overhead and elastic scaling for seasonal campaign volumes. Call analytics solutions capture the fastest expansion as real-time speech transcription and sentiment scoring replace post-call manual review. Integration platforms concentrate margin pools where APIs connect telephony data to CRM and advertising stacks, reducing customer churn through workflow embedding.
The Federal Communications Commission enforces STIR/SHAKEN caller ID authentication standards that elevate compliance costs for voice infrastructure providers while filtering illegitimate traffic. GDPR and the EU AI Act impose consent documentation and algorithmic transparency obligations on European deployments of automated call scoring. Stakeholders must monitor emerging state-level US privacy statutes and telemarketing consent frameworks as these determine where attribution data legally resides and how long caller records remain actionable.
Market Dynamics
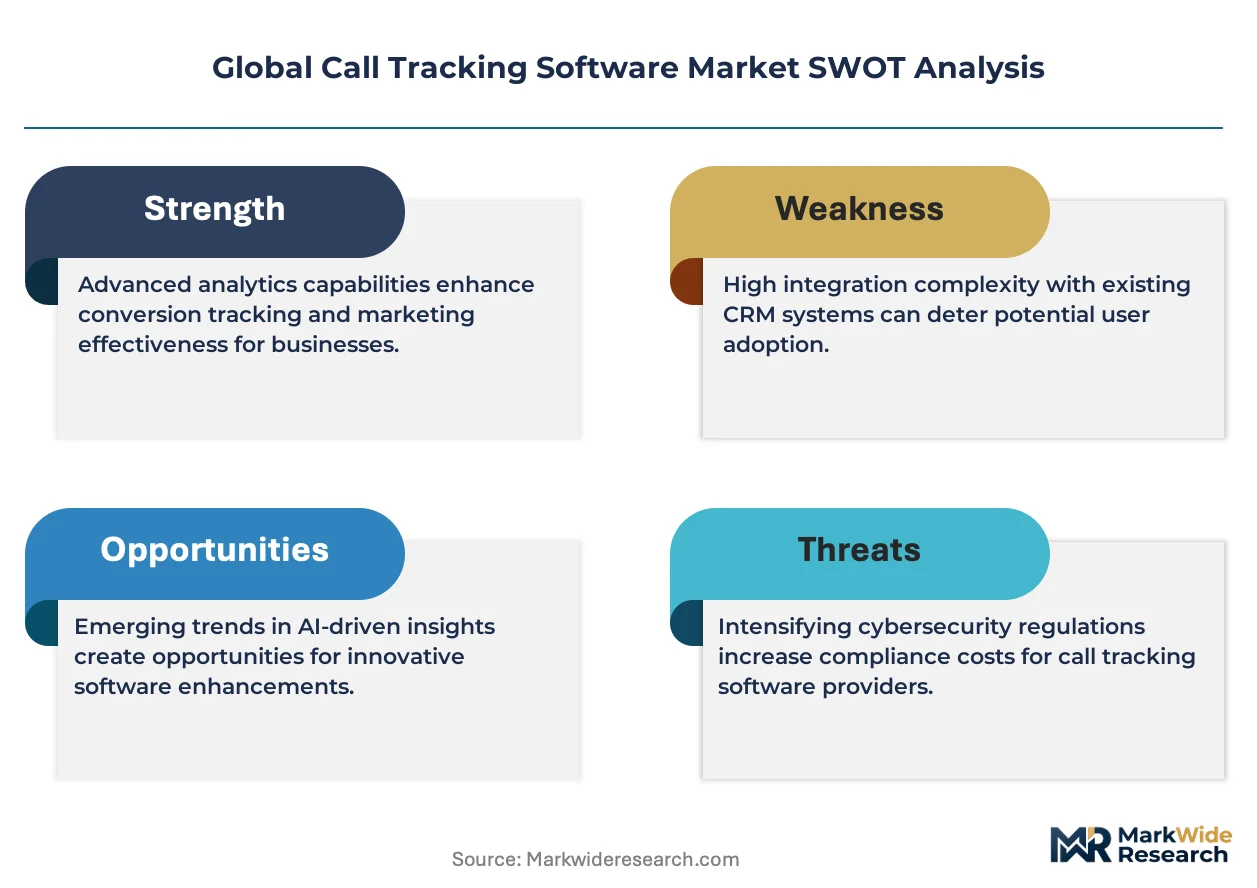
The migration from on-premises telephony to cloud-native architectures is compressing vendor margins while expanding addressable use cases beyond traditional marketing attribution into sales enablement and customer success workflows.
Growth Catalysts
- Dynamic Number Insertion Technology:Real-time phone number swapping based on traffic source enables keyword-level attribution for search and social campaigns, driving adoption among performance marketing agencies.
- GDPR Consent Frameworks:European data protection requirements have standardized caller consent documentation, creating compliance-driven replacement cycles for legacy systems lacking audit trails.
- Insurance Vertical Concentration:Lead distribution platforms in the United States now bundle call tracking with policy quoting workflows, embedding attribution into core revenue operations.
Market Restraints
- STIR/SHAKEN Compliance Costs:FCC-mandated caller ID authentication elevates infrastructure overhead for voice providers, squeezing margins on low-ARPU customer tiers.
- Cloud Infrastructure Concentration:Dependency on AWS, Google Cloud, and Microsoft Azure for elastic scaling creates single-supplier vulnerability during regional outages.
- Speech Recognition Accuracy Limitations:Background noise and accented speech degrade transcription quality in real-time analytics, limiting automated sentiment scoring reliability.
Strategic Opportunities
- German Mid-Market Penetration:Mittelstand manufacturers with field sales operations remain underserved by current vendor pricing models designed for enterprise scale.
- Convergence of Conversation Intelligence and CRM:Native integration between call transcripts and Salesforce or HubSpot records eliminates API latency and data fragmentation.
- EU AI Act Algorithmic Transparency:Automated call scoring systems in Europe must document decision logic, creating first-mover advantage for vendors with built-in explainability features.
Industry Challenges
- Telephony Engineering Talent Scarcity:SIP protocol expertise and carrier interconnection management skills command premium compensation, constraining vendor R&D velocity.
- Legacy PBX Integration Complexity:Hybrid deployments requiring synchronization between cloud analytics and on-premises Avaya or Cisco systems extend implementation timelines and elevate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Call Tracking Software Market |
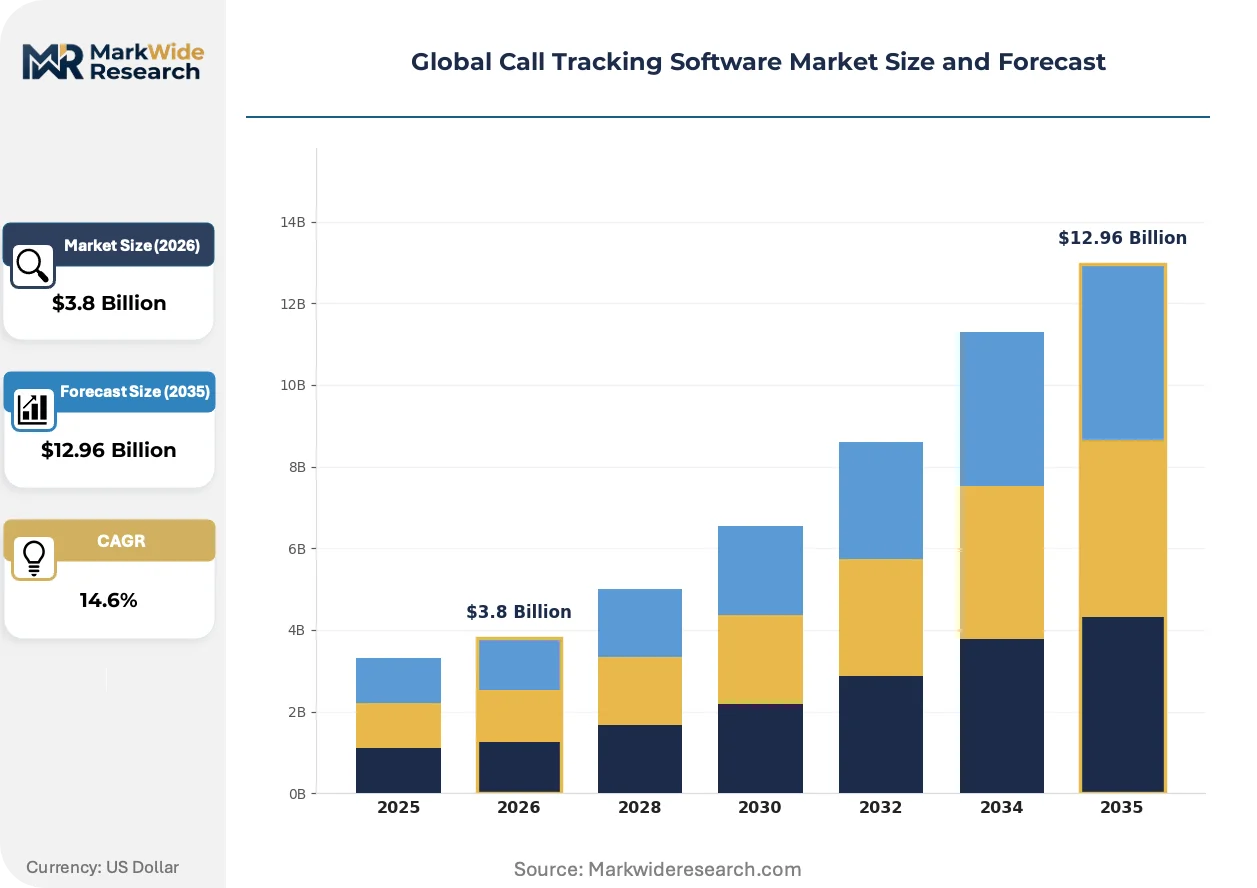
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Call Analytics, Interactive Voice Response, Lead Management, Campaign Attribution, Integration Platforms Application Area: Small Business Marketing, Large Enterprise Sales, Customer Support, Real Estate Promotion, Hospitality Booking, Educational Outreach Client Type: Advertising Agencies, Digital Marketers, Telecommunication Providers, Insurance Brokers, Financial Advisors, Legal Firms |
| Companies Covered | CallRail, Invoca, Marchex Inc., CallTrackingMetrics LLC, Call Box, DialogTech, Phonexa Holdings LLC, CloudTalk, Infinity Tracking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Call Tracking Software Market Shifts & Advancements
Artificial intelligence is restructuring competitive advantage around real-time conversation analysis rather than retrospective reporting, while regulatory fragmentation forces architectural decisions that prioritize data residency flexibility.
Speech-to-text engines with domain-specific training for financial services and healthcare verticals is bifurcating the analytics tier. Enterprise buyers in the United States now demand sub-five-second transcription latency for live agent coaching, compressing the window for batch-processing alternatives and rewarding GPU-accelerated inference architectures.
GDPR and the EU AI Act are imposing layered consent and explainability obligations on European deployments. Vendors must now maintain separate model versions with documented decision trails for automated lead scoring, increasing engineering overhead but creating compliance moats against less sophisticated competitors in France and Germany.
Subscription packaging is fragmentating as buyers resist bundled suites. Digital marketing agencies in the United Kingdom increasingly unbundle call tracking from broader attribution platforms, preferring best-of-breed APIs over integrated stacks, which pressures vendors to expose granular pricing for number provisioning, minute volumes, and transcription tiers.
Global Call Tracking Software Market Segmentation
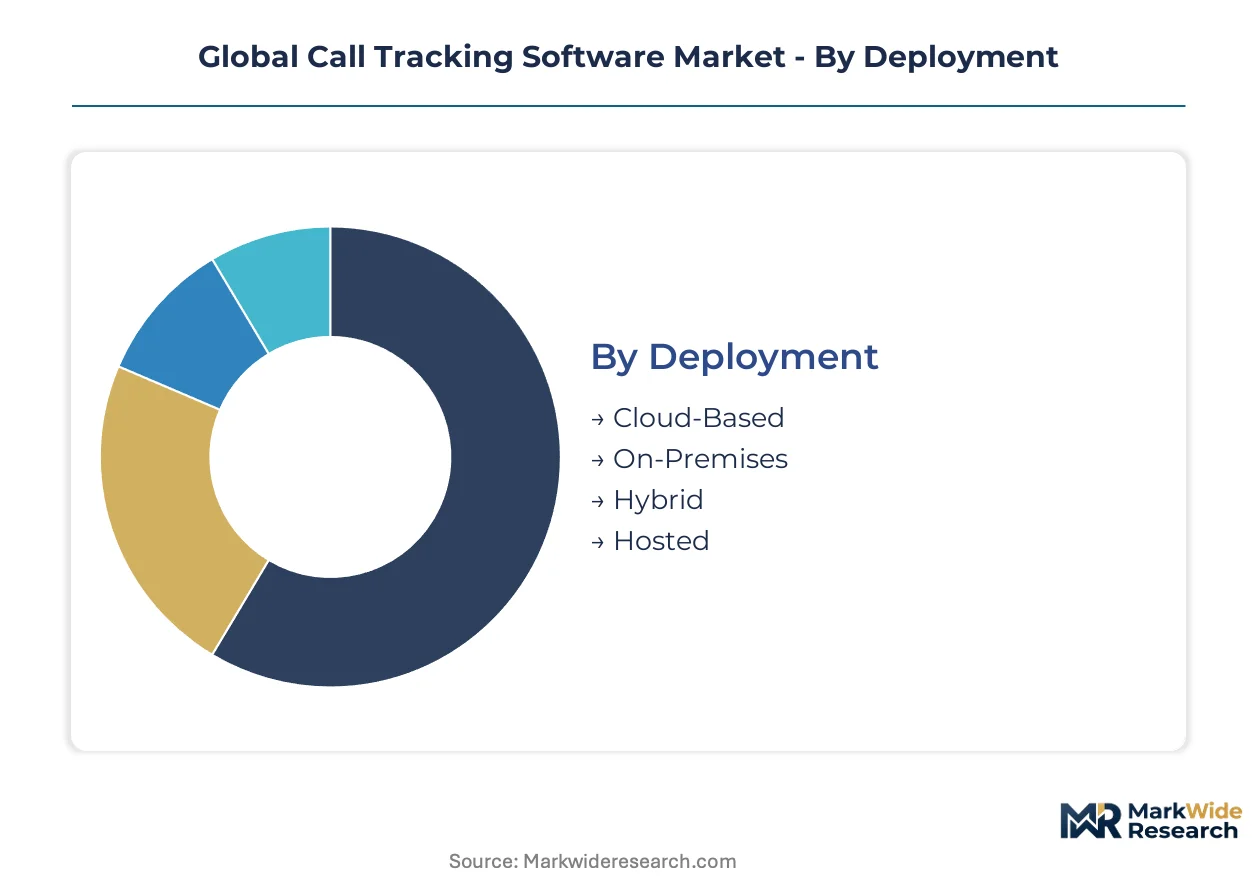
Call tracking software segments reflect divergent compliance burdens and infrastructure requirements across deployment modes and client categories. Buyers select architectures based on data residency mandates, integration complexity, and seasonal volume elasticity needs.
Deployment:
GDPR and the EU AI Act impose distinct architectural obligations that favor cloud-native deployments in Europe while sustaining hybrid demand in regulated US states.
- Cloud-Based:Multi-tenant SaaS architectures provision dynamic number pools through AWS, Google Cloud, or Microsoft Azure infrastructure. Enterprise sales teams in the United States and United Kingdom dominate consumption as these organizations prioritize elastic scaling for seasonal campaign surges without capital expenditure.
- On-Premises:Dedicated server installations within client data centers retain complete caller record custody. German Mittelstand manufacturers and Swiss financial institutions specify this mode to satisfy national data localization requirements and direct supervisory authority oversight.
- Hybrid:Split architectures route sensitive call metadata through on-premises gateways while pushing analytics workloads to cloud inference engines. US healthcare providers deploy this configuration to segment HIPAA-protected voice data from AI transcription processing.
- Hosted:Single-tenant managed services operated by vendor personnel within third-party colocation facilities. Australian and Canadian mid-market agencies select this tier to obtain dedicated infrastructure without internal telephony engineering capacity.
Cloud-Based handles the majority of throughput; Hybrid is expanding most quickly as regulated industries seek architectural compromise.
Solution Type:
Margin concentration follows integration depth, with API-connected platforms commanding premium positioning against standalone analytics tools.
- Call Analytics:Real-time speech transcription and sentiment scoring engines process conversational data for agent coaching and quality assurance. Financial services contact centers in the United States and United Kingdom drive demand as these buyers require sub-five-second transcription latency for live intervention.
- Interactive Voice Response:Automated call routing and self-service menus reduce agent handling costs for high-volume inbound operations. Telecommunication providers in Germany and France deploy IVR layers to manage subscriber service requests without expanding human headcount.
- Lead Management:Caller qualification and distribution workflows prioritize prospects based on demographic and behavioral scoring. Insurance brokers in the United States embed these capabilities within policy quoting sequences to accelerate conversion velocity.
- Campaign Attribution:Source tracking and keyword-level performance measurement link telephone inquiries to specific marketing spend. Digital marketing agencies across the United Kingdom unbundle this function from broader attribution suites to maintain best-of-breed flexibility.
- Integration Platforms:API middleware connecting telephony data to Salesforce, HubSpot, and advertising technology stacks. Enterprise procurement teams in the United States prioritize native CRM synchronization to eliminate data fragmentation and reduce IT integration burdens.
Integration Platforms capture the steepest expansion trajectory; Call Analytics retains the largest installed base by revenue.
Application Area:
Use case maturity varies sharply, with sales enablement applications overtaking traditional marketing attribution in technology sophistication.
- Small Business Marketing:Local service providers and franchise operators track call volume from directory listings and search advertising. Plumbers, contractors, and medical practices in the United States constitute the core demand base for accessible pricing tiers.
- Large Enterprise Sales:Field sales organizations and B2B account teams leverage conversation intelligence to extract competitive intelligence and next-step commitments. Technology vendors and industrial distributors in Germany and the United States deploy these capabilities across thousands of rep conversations monthly.
- Customer Support:Post-purchase call monitoring identifies escalation patterns and product defect reports. E-commerce and consumer electronics retailers in the United Kingdom apply sentiment scoring to prioritize warranty intervention and retention offers.
- Real Estate Promotion:Property listing attribution connects inquiries to specific portal placements and agent marketing spend. Brokerage networks in Australia and the United States track caller intent to optimize listing exposure fees.
- Hospitality Booking:Reservation call tracking measures conversion from property websites and third-party travel platforms. Hotel chains in France and Spain analyze abandonment points to refine rate presentation and availability messaging.
- Educational Outreach:Enrollment call monitoring supports admissions optimization for universities and vocational programs. US higher education institutions apply conversation analysis to improve financial aid counseling effectiveness.
Large Enterprise Sales commands the highest average contract value; Customer Support is gaining share fastest as post-purchase analytics mature.
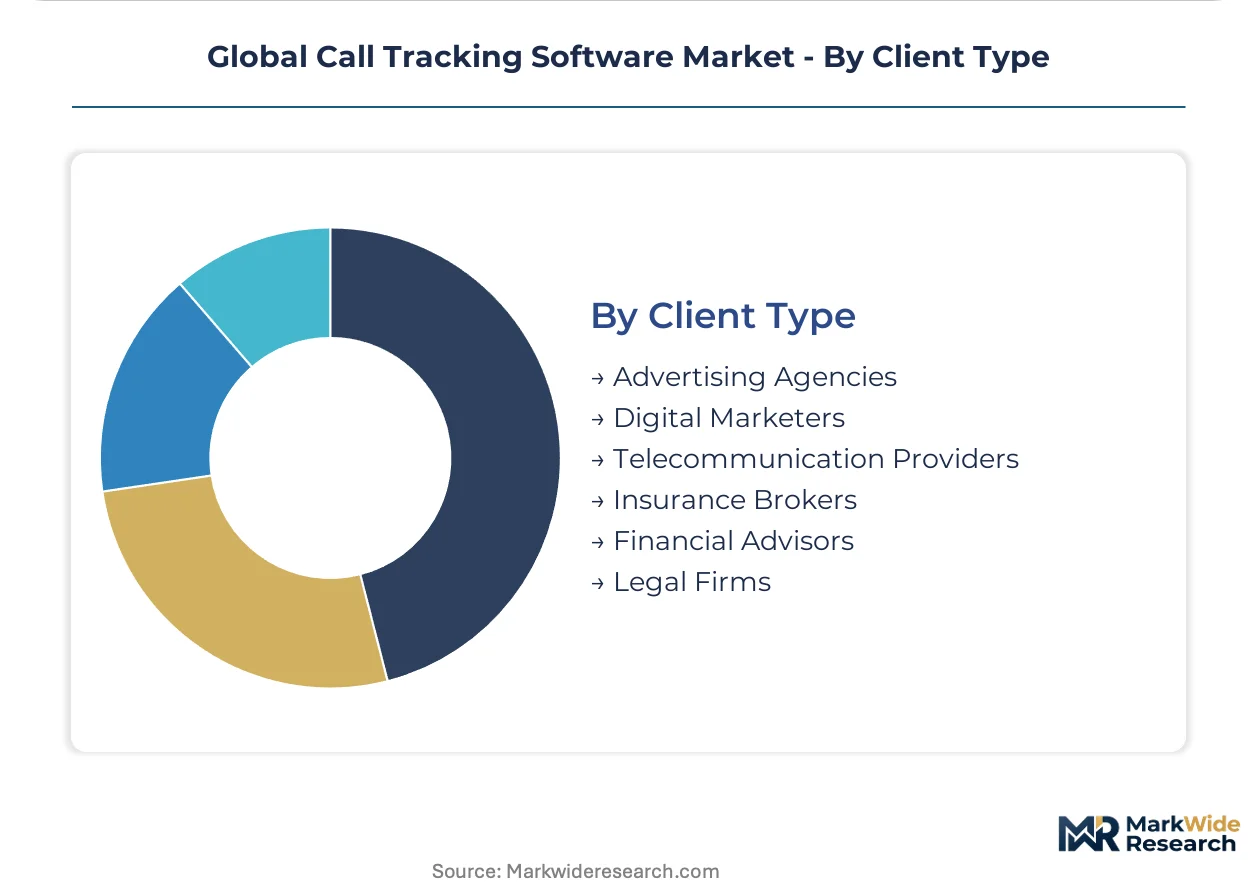
Client Type:
Vertical specialization determines vendor selection criteria, with regulated industries demanding audit trails and consent documentation absent from generalist deployments.
- Advertising Agencies:Multi-client media buyers require white-labeled reporting and cross-account data segregation. Performance marketing shops in the United Kingdom and United States represent the primary channel for mid-market software distribution.
- Digital Marketers:In-house brand teams and independent consultants manage search and social campaign attribution directly. E-commerce operators and direct-to-consumer brands in the United States dominate this category.
- Telecommunication Providers:Carriers and resellers embed call tracking within subscriber service and sales operations. Mobile virtual network operators in Germany and France deploy these tools to differentiate enterprise offerings.
- Insurance Brokers:Independent agents and carrier distribution partners track policy quoting calls from comparison websites and referral networks. US state-level regulatory variations shape compliance requirements for call recording disclosure.
- Financial Advisors:Wealth management and retirement planning practices monitor client consultation quality. SEC-registered investment advisers in the United States maintain conversation archives to satisfy examination documentation standards.
- Legal Firms:Plaintiff attorneys and practice groups track intake call conversion from television and digital advertising. Personal injury and mass tort practices in the United States prioritize rapid response time measurement to optimize marketing spend.
Advertising Agencies represent the largest client category by vendor count; Financial Advisors are climbing fastest as fiduciary documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and United Kingdom show the lowest price sensitivity, prioritizing AI transcription latency and CRM integration depth, while German Mittelstand manufacturers and Australian mid-market agencies demand modular, consumption-based pricing to control operational expenditure.
United States
Enterprise sales teams and insurance brokers drive premium-tier consumption, with sub-five-second transcription latency becoming a standard procurement requirement. FCC STIR/SHAKEN enforcement elevates infrastructure compliance costs for voice providers. California technology vendors and New York financial services firms anchor demand for conversation intelligence platforms that integrate natively with Salesforce deployments.
United Kingdom
Digital marketing agencies unbundle call tracking from broader attribution suites, favoring API-first architectures over integrated stacks. GDPR consent documentation requirements have standardized audit trail capabilities across vendor offerings. London-based performance marketing shops and Manchester media buyers concentrate procurement decisions, with white-labeled reporting emerging as a competitive differentiator.
Germany
Mittelstand manufacturers with field sales operations remain underserved by enterprise-scale pricing models, creating whitespace for mid-market specialists. The EU AI Act imposes algorithmic transparency obligations on automated call scoring systems deployed across Bavaria and Baden-Württemberg. Stuttgart industrial distributors and Frankfurt financial advisors are expanding conversation intelligence adoption to extract competitive intelligence from thousands of monthly rep interactions.
Australia
Mid-market agencies select hosted single-tenant deployments to obtain dedicated infrastructure without internal telephony engineering capacity. The country's national privacy regulator enforces consent documentation standards comparable to GDPR frameworks. Sydney property brokerage networks and Melbourne hospitality chains apply call tracking to optimize listing exposure fees and reservation conversion workflows respectively.
France
Telecommunication providers deploy IVR layers to manage subscriber service requests without expanding human headcount, particularly in high-volume inbound operations. CNIL oversight of automated decision-making systems shapes vendor architectural choices for explainable AI features. Paris hotel chains and Lyon insurance distributors are analyzing abandonment points to refine rate presentation and accelerate policy quoting sequences.
Global Call Tracking Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-native architectures displacing legacy on-premises installations across enterprise accounts. The upper tier commands premium positioning through native CRM synchronization and real-time speech analytics, while mid-market specialists compete on accessible pricing and vertical-specific workflow templates. Two dominant competitive moves are reshaping positioning: API-first unbundling to capture agency demand for best-of-breed flexibility, and compliance-driven replacement cycles in European markets lacking audit trail capabilities.
Within the integrated leader tier, Invoca and CallRail exemplify divergent positioning strategies. Invoca anchors the enterprise conversation intelligence segment with AI-powered transcription and sentiment scoring capabilities. CallRail occupies a position among accessible cloud-native platforms competing through deep Google Marketing Platform integration and modular pricing structures. Phonexa Holdings LLC sits within the vertical specialist category, bundling lead distribution with call tracking suites tailored to insurance and financial services workflows.
| Leading Market Players |
|---|
| CallRail |
| Invoca |
| Marchex Inc. |
| CallTrackingMetrics LLC |
| Call Box |
| DialogTech |
| Phonexa Holdings LLC |
| CloudTalk |
| Infinity Tracking |
| Others |
Supply & Pricing Matrix
FCC STIR/SHAKEN authentication mandates gate both vendor qualification and price differentiation in call tracking infrastructure, elevating compliance costs for voice providers while compressing margins on entry-tier subscriptions and rewarding premium-tier vendors with pre-certified carrier interconnections.
Pricing Analysis
Extended professional services contracts and API integration retainers drive lifetime value beyond base subscription revenue. Three-tier pricing structure across premium, standard, and economy levels stratifies by transcription latency, CRM native connectivity, and vertical-specific AI model training. Cost compression in the economy tier intensifies because AWS, Google Cloud, and Microsoft Azure infrastructure costs scale linearly with call volume. Digital marketing agencies in the United Kingdom exhibit highest price sensitivity, while enterprise sales teams in the United States prioritize sub-five-second latency over per-minute cost.
Supply Chain Analysis
Elastic provisioning eliminates traditional inventory buffers, though carrier interconnection lead times for dedicated number pools extend vendor fulfillment cycles. Cloud infrastructure concentrates in the United States, Ireland, and Germany as AWS, Google Cloud, and Microsoft Azure dominate elastic compute provisioning. GPU-accelerated inference chips, carrier-grade SIP trunking capacity, and consent-management middleware constitute critical input dependencies. Single-source vulnerability during regional hyperscaler outages threatens service continuity. Distribution runs through direct SaaS self-service portals and agency channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-market verticals as unbundling demand from digital marketing agencies creates specialist niches alongside integrated platform leaders.
For Market Incumbents: Consolidate API ecosystem control through native Salesforce and HubSpot synchronization to reduce churn from workflow embedding. Acquire speech-to-text engineering teams in financial services and healthcare verticals to defend against domain-specific challengers. FCC compliance cost escalation threatens low-ARPU customer tiers; vertical integration into carrier-grade voice infrastructure insulates margin pressure. For New Entrants and Emerging Players: Anchor in German Mittelstand manufacturers with field sales operations, a segment underserved by enterprise-scale pricing models. Target white-labeled agency solutions in the United Kingdom where procurement favors best-of-breed API flexibility over bundled suites. Go-to-market through consumption-based pricing with modular transcription tiers to differentiate from incumbent subscription bundles. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency mandates reshape the acquisition landscape toward vendors with built-in explainability features and documented decision trails. Long-term viability centers on compliance moats against less sophisticated European competitors. Target acquisition archetype: mid-market specialists with vertical workflow templates in insurance or financial services. Signal to watch: state-level US privacy statute proliferation accelerating replacement cycles for legacy systems lacking audit capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical AI Model Development | Domain-specific transcription engines for financial services reduce latency below five seconds. |
| Native CRM Integration | Salesforce and HubSpot synchronization eliminates API latency for enterprise sales teams. |
| Compliance-First Architecture | GDPR and EU AI Act documentation trails create defensive moats in European deployments. |
| Carrier Infrastructure Partnership | STIR/SHAKEN pre-certification reduces voice provider compliance overhead. |
| Consumption-Based Pricing Launch | Modular transcription tiers capture agency demand resisting bundled suite commitments. |
Research Methodology
Desk research of FCC regulatory filings, GDPR implementation guidance, hyperscaler infrastructure disclosures, and carrier interconnection tariffs preceded structured interviews with CTOs at digital marketing agencies, telephony engineering directors, CRM integration specialists, and procurement leads at insurance brokerages. Primary intelligence combined with secondary validation across SEC filings, cloud provider capex reports, and vertical software procurement databases. Bottom-up deployment model sizing triangulated against top-down addressable market estimates.
Variance decomposition across deployment modes, solution types, application areas, and client verticals shaped analytical framework construction throughout the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating seasonal campaign volume patterns and compliance-driven replacement cycle timing. Speech recognition accuracy benchmarks and carrier infrastructure cost trajectories informed technology diffusion assumptions.
Material uncertainties — FCC rulemaking evolution, EU AI Act enforcement interpretation, hyperscaler regional outage frequency — sit outside the modeled envelope. Forecasts reflect assumptions about cloud migration velocity and vertical AI adoption without claiming predictive precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Metal Fabrication Software Market
Software & Services
Attendance Management Software Market
Software & Services
Objectives & Key Results (OKR) Software Market
Software & Services
Global Client Portal Software Market
Software & Services
Construction Suites Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Machine Translation Software Market
Software & Services
Lead Scoring Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
System Infrastructure Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Global Childcare Management Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Europe Human Resource (HR) Technology Market