
 Optical Design Software Market | 2026-2036
Optical Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Design Software Market Insights
Cloud-native architecture is tilting how optical design workflows reach end users, replacing perpetual licenses with scalable SaaS delivery. Synopsys leverages its EDA heritage to extend simulation capabilities across semiconductor-optical boundaries. Ansys (Zemax) anchors high-end lens design through deep physics integration and established user communities. Lambda Research Corporation specializes in illumination engineering, competing on sector-specific tool depth rather than platform breadth.
Optical design software comprises computational tools that model light propagation through ray-tracing, wave-optics, and finite element methods to predict system performance before physical prototyping. These platforms integrate refractive index databases, coating algorithms, and tolerance analysis to optimize lenses, mirrors, and photonic components for cameras, lasers, and sensors. Cloud-based deployment is capturing fastest growth as research institutions and mid-tier manufacturers trade capital expenditure for operational flexibility. Ray-tracing technology dominates current revenue pools due to mature solver performance and broad applicability across automotive lighting and consumer electronics. Wave-optics segments command premium positioning where sub-wavelength precision governs semiconductor lithography and biomedical imaging outcomes.
FDA scrutiny of optical diagnostic devices elevates traceability requirements in software validation workflows, particularly for ophthalmic and endoscopic applications. REACH compliance in Europe constrains material libraries within simulation databases, forcing vendors to update optical glass and coating specifications reactively. ISO 10110 drawing standards and IEC laser safety protocols shape how design outputs translate to manufacturable specifications across jurisdictions. Stakeholders must monitor how AI-assisted optimization reshapes the skill threshold for optical engineers and whether regulatory bodies adapt qualification frameworks for machine-generated designs.
Market Dynamics
Cloud-native SaaS delivery is restructuring how optical design software reaches end users, compressing procurement cycles and displacing perpetual license models among research institutions and mid-tier manufacturers.
Growth Catalysts
- Semiconductor lithography scaling:Sub-wavelength precision requirements in EUV systems pull wave-optics simulation demand from foundries in Taiwan, South Korea, and the United States.
- FDA validation frameworks:Traceability mandates for optical diagnostic devices elevate software qualification budgets in ophthalmic and endoscopic equipment supply chains.
- Photonics cluster density:Concentrated R&D spending in Germany's Zeiss-Jena corridor and Japan's Tsukuba district sustains specialized tool procurement independent of macroeconomic cycles.
Market Restraints
- Computational infrastructure costs:Wave-optics solvers demand GPU clusters that price out smaller design houses and independent consultants.
- Material database compliance:ECHA's REACH restrictions force reactive updates to optical glass and coating specifications, fragmenting simulation libraries across jurisdictions.
- Skill threshold elevation:Multi-physics integration requires optical engineers to command finite element methods and electromagnetic theory simultaneously, narrowing qualified labor pools.
Strategic Opportunities
- India's PLI-linked photonics investments:Domestic manufacturing incentives for telecom and defense optics create first-mover SaaS adoption potential among Bangalore and Hyderabad engineering centers.
- AI-assisted optimization modules:Machine learning convergence with ray-tracing engines promises automated tolerance analysis, compressing design iteration cycles for automotive lighting suppliers.
- Subscription tiering for academia:Floating license pools and semester-based billing address budget seasonality at U.S. national laboratories and European metrology institutes.
Industry Challenges
- Legacy code integration:Decades of proprietary macros and custom solver scripts in established user bases complicate cloud migration and API standardization.
- Cross-disciplinary talent scarcity:The intersection of optical physics, software engineering, and domain-specific manufacturing knowledge concentrates in aging specialist populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Design Software Market |
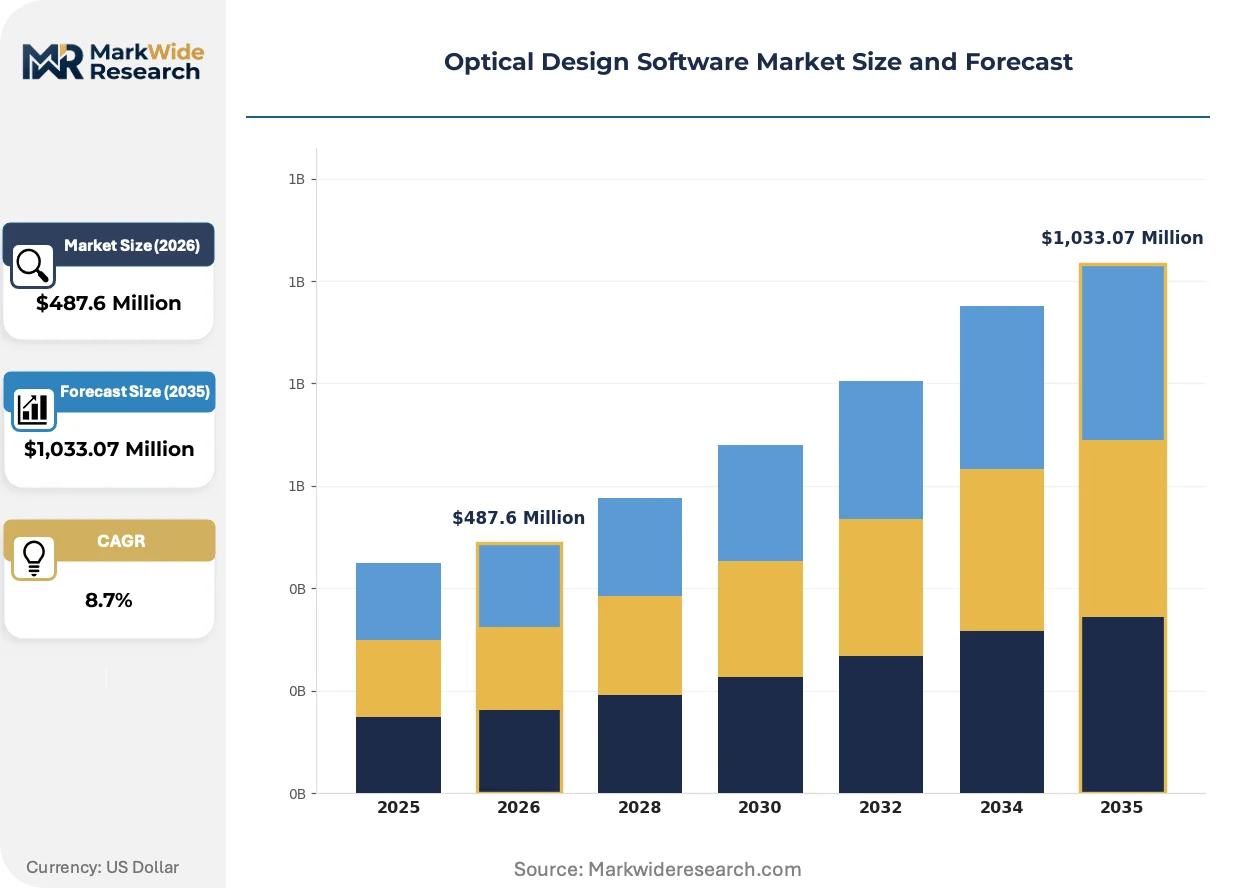
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Lens Design, Simulation, Testing, Image Analysis End User: Research Institutions, Manufacturing Companies, Educational Institutions, Government Agencies Deployment: On-Premise, Cloud-based, Hybrid, SaaS Technology: Ray-Tracing, Wave-Optics, Geometric Optics, Finite Element Method |
| Companies Covered | LTI Optics, Breault Research Organization, Synopsys, COMSOL Multiphysics, Optica Software, Ansys (Zemax), OptiLayer GmbH, Optiwave Systems, Lambda Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Design Software Market Trends and Innovations
Computational methods and delivery architectures are converging to reshape how optical systems move from concept to fabrication, with implications for cost structures, competitive positioning, and regulatory compliance workflows.
Wave-optics simulation is migrating from niche semiconductor lithography applications toward mainstream biomedical imaging and augmented-reality waveguide design. Medical device manufacturers in Switzerland and the Netherlands are adopting these solvers for ophthalmic instrument tolerancing, where sub-micron precision governs clinical outcomes. The shift is compressing the addressable market gap between high-end lens design and photonic integrated circuit simulation.
REACH compliance in Europe constrains how vendors maintain material property databases, with ECHA substance restrictions forcing quarterly updates to refractive index libraries and coating dispersion models. Optical glass suppliers must now certify composition data through simulation-integrated traceability chains. German and French metrology institutes are responding by consolidating procurement around vendors with dedicated regulatory affairs functions.
Research institutions are unbundling perpetual licenses in favor of consumption-metered cloud access, with usage tracking tied to grant reporting requirements. This pattern concentrates among U.S. National Science Foundation awardees and Horizon Europe beneficiaries, where operational expenditure treatment improves budget flexibility. The shift pressures traditional vendors to restructure pricing architectures without cannibalizing established academic discount tiers.
Optical Design Software Market Segmentation
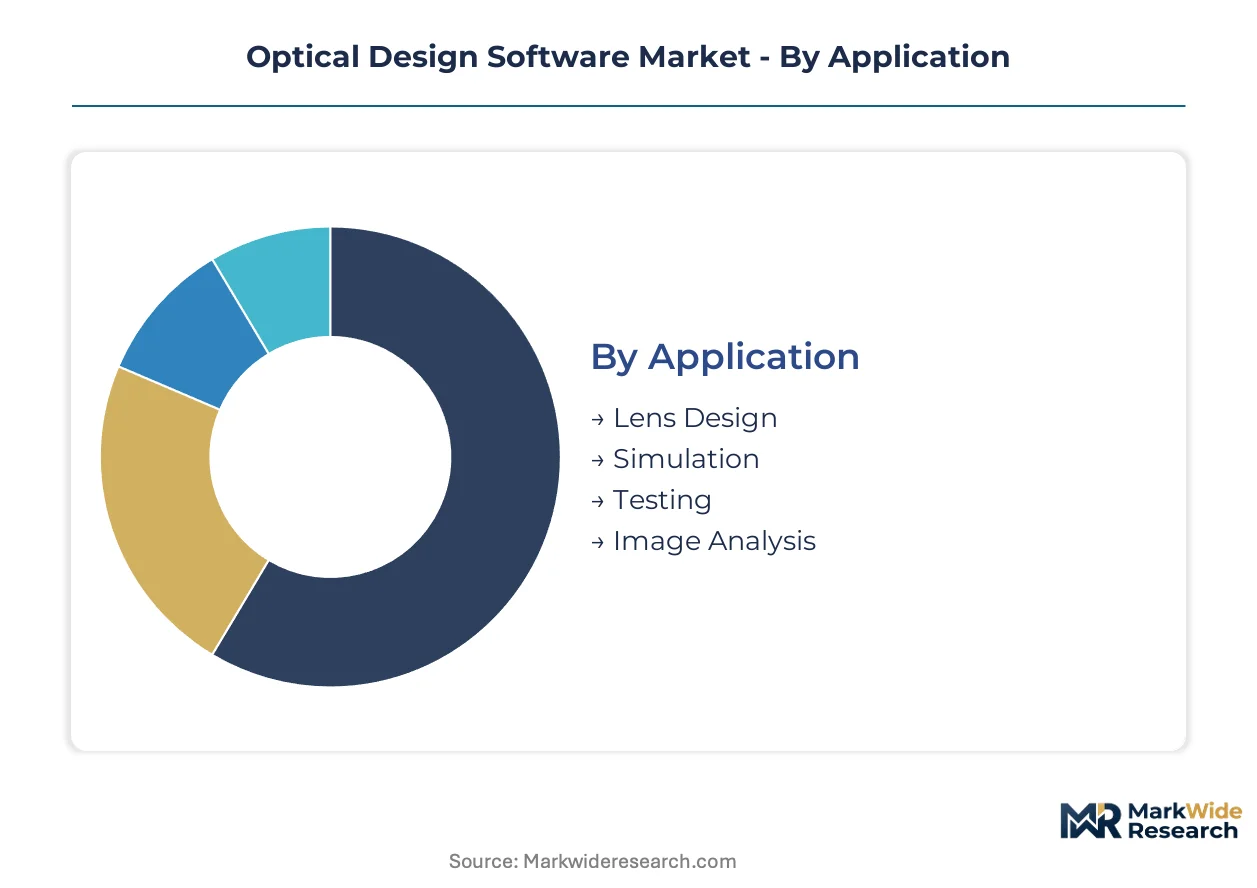
Optical design software segmentation reveals how computational methods, delivery architectures, and user sophistication stratify across application domains. Procurement patterns diverge sharply between semiconductor foundries requiring wave-optics precision and automotive suppliers optimizing illumination through geometric methods.
Application:
Mature segments anchor revenue stability while emerging functions capture R&D investment flows.
- Simulation:Wave-optics and ray-tracing engines model light propagation through complex optical systems before physical prototyping. Taiwan Semiconductor Manufacturing Company and Samsung Foundry deploy these tools for EUV lithography mask optimization, where sub-wavelength accuracy governs yield.
- Lens Design:Geometric optics solvers optimize surface curvatures, thicknesses, and material selections for camera objectives and microscope objectives. German automotive Tier-1 suppliers in Stuttgart and Munich dominate procurement for headlamp projection systems.
- Testing:Tolerance analysis modules predict manufacturing variation impact on optical performance.
- Image Analysis:Post-capture processing algorithms evaluate modulation transfer function and point spread function metrics.
Simulation handles the majority of throughput; Image Analysis is expanding most quickly on share as machine vision applications proliferate.
End User:
Customer sophistication tiers separate capital-intensive manufacturing from grant-dependent research operations.
- Manufacturing Companies:Foundries and optical component producers integrate design software with metrology equipment for closed-loop quality control. South Korean display panel manufacturers in Gyeonggi Province deploy hybrid deployment models combining on-premise solvers with cloud burst capacity.
- Research Institutions:National metrology institutes and university photonics laboratories drive wave-optics method development. Max Planck Institute and Tsukuba research cluster scientists require floating license pools for collaborative multi-site projects.
- Government Agencies:Defense contractors and space agencies mandate ITAR-compliant on-premise installations.
- Educational Institutions:Undergraduate engineering programs prioritize cost-effective semester-based SaaS access.
Manufacturing Companies generate the dominant procurement volume; Research Institutions are climbing the fastest on license expansion.
Deployment:
Delivery architecture choices reflect data sovereignty requirements against computational elasticity needs.
- Cloud-based:GPU-accelerated solvers scale processing capacity for wave-optics simulations without capital infrastructure. Swiss biomedical device startups in Basel and Zurich adopt consumption-metered access for ophthalmic instrument development.
- SaaS:Browser-native interfaces eliminate local installation and maintenance overhead. Indian engineering services firms in Bangalore leverage subscription tiers for project-based optical design outsourcing.
- On-Premise:Air-gapped installations satisfy defense and intelligence community security protocols.
- Hybrid:Mixed architectures preserve sensitive IP locally while bursting compute-intensive simulations to cloud.
Cloud-based deployment commands the steepest expansion trajectory; On-Premise retains dominance in classified and FDA-regulated environments.
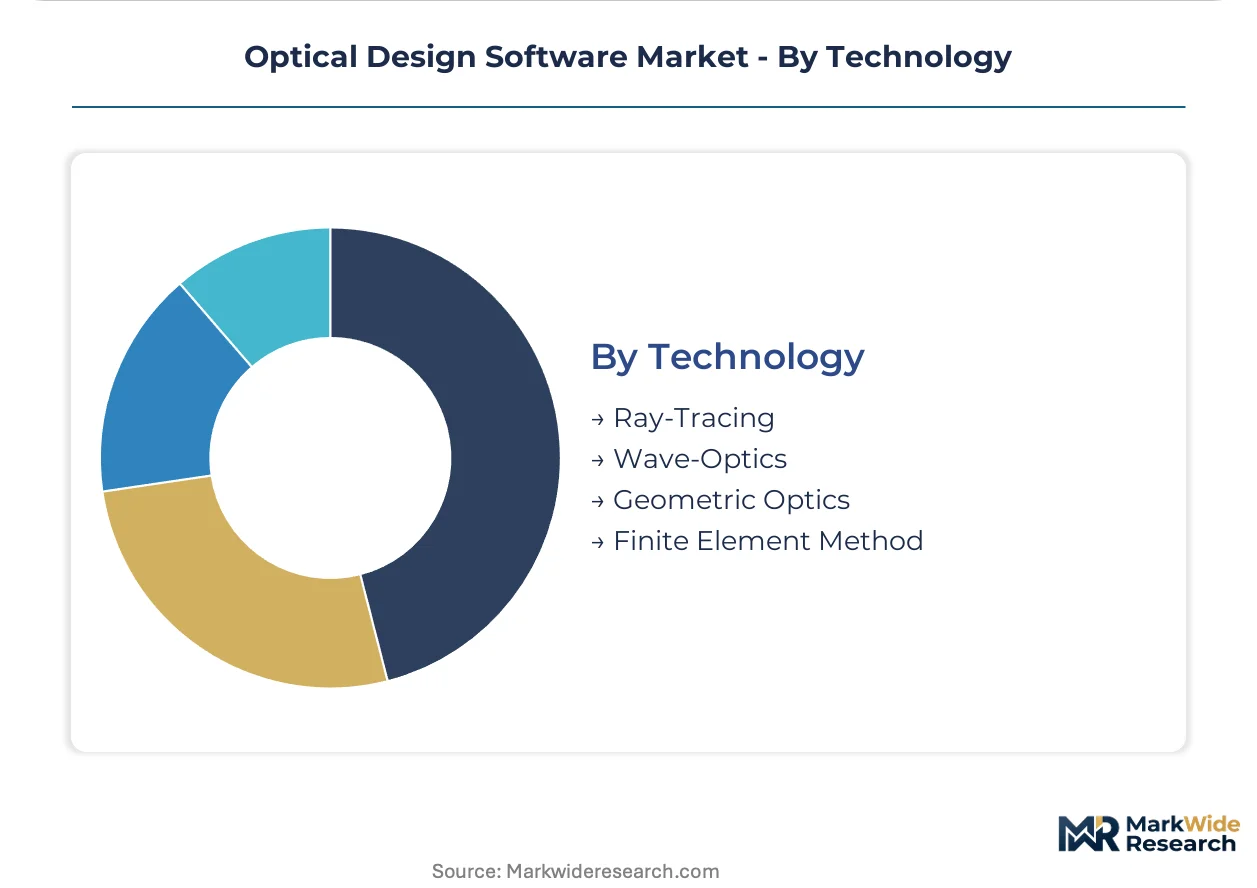
Technology:
Computational method selection correlates directly with feature scale relative to illumination wavelength.
- Ray-Tracing:Geometric optics approximation traces light paths through refractive and reflective surfaces for systems where features exceed tens of wavelengths. Japanese camera module suppliers in Oita Prefecture rely on mature solver performance for smartphone lens optimization.
- Wave-Optics:Electromagnetic field solvers resolve diffraction, interference, and polarization effects at sub-wavelength scales. ASML and its supply chain partners in the Netherlands and Germany require these methods for extreme ultraviolet lithography source-mask optimization.
- Geometric Optics:Simplified paraxial approximations enable rapid first-order system layout.
- Finite Element Method:Structural-thermal-optical performance integration predicts how mechanical stress and temperature gradients deform precision optics.
Ray-Tracing carries the bulk of commercial simulation workload; Wave-Optics is gaining share fastest as semiconductor lithography pushes deeper into sub-wavelength regimes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and semiconductor foundries concentrate procurement in jurisdictions with established photonics infrastructure and stringent export control regimes. National metrology institutes anchor specialized tool consumption in Germany, Japan, and the United States. Cloud-native delivery is compressing procurement cycles among research institutions across all major markets.
United States
Defense primes in Massachusetts and California drive ITAR-compliant on-premise installations for precision optical systems. FDA validation frameworks for ophthalmic and endoscopic devices elevate software qualification budgets in medical device supply chains. The Tucson and Rochester photonics clusters sustain specialized procurement independent of commercial software cycles.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich dominate lens design procurement for headlamp projection systems. ECHA REACH compliance forces quarterly updates to refractive index libraries and coating dispersion models. The Zeiss-Jena corridor concentrates R&D spending that sustains wave-optics method development at Max Planck Institute facilities.
Japan
Camera module suppliers in Oita Prefecture rely on mature ray-tracing solvers for smartphone lens optimization. METI industrial policy supports domestic photonics manufacturing through targeted R&D subsidies. The Tsukuba research cluster scientists require floating license pools for collaborative multi-site projects across national laboratories.
South Korea
Display panel manufacturers in Gyeonggi Province deploy hybrid deployment models combining on-premise solvers with cloud burst capacity. MFDS medical device regulations shape validation workflows for optical diagnostic equipment. Samsung Foundry and domestic supply chain partners pull wave-optics simulation demand for EUV lithography mask optimization.
India
Engineering services firms in Bangalore leverage subscription tiers for project-based optical design outsourcing. PLI scheme incentives for telecom and defense optics create first-mover SaaS adoption potential. Hyderabad's defense research centers are expanding procurement of simulation tools for precision optical systems under domestic manufacturing programs.
Optical Design Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architectures and computational method depth. The vendor base stratifies into three tiers: EDA-heritage platforms extending across semiconductor-optical boundaries, dedicated optics houses anchoring high-end lens design through physics integration, and sector-specific tool developers competing on illumination engineering depth. Dominant competitive moves include cloud-native platform restructuring and AI-assisted optimization module development.
Within the EDA-heritage tier, Synopsys and Ansys (Zemax) exemplify platform breadth strategies that leverage existing user communities across adjacent simulation domains. Lambda Research Corporation occupies a position among specialists in illumination engineering, competing on tool depth rather than horizontal expansion. OptiLayer GmbH represents the European precision coating segment, anchoring niche workflows for thin-film optical design.
| Leading Market Players |
|---|
| LTI Optics |
| Breault Research Organization |
| Synopsys |
| COMSOL Multiphysics |
| Optica Software |
| Ansys (Zemax) |
| OptiLayer GmbH |
| Optiwave Systems |
| Lambda Research Corporation |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's automotive Tier-1 engineering corridors concentrate GPU cluster procurement for wave-optics solvers, compressing margins for mid-tier design houses unable to match capital deployment scale. This capacity asymmetry translates directly into pricing power for EDA-heritage platforms that bundle semiconductor-optical simulation workflows.
Pricing Analysis
Cost-plus contracts with semiconductor foundries index SaaS subscription tiers to wafer throughput volumes, creating sticky revenue streams for vendors serving TSMC and Samsung Foundry. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant on-premise installations from consumption-metered cloud access and semester-based academic licenses. Pricing pressure stems from Indian engineering services firms in Bangalore demanding project-based billing for optical design outsourcing. Government agencies exhibit lowest price sensitivity due to security-mandated procurement protocols, while educational institutions face acute budget seasonality constraints.
Supply Chain Analysis
Export-control regimes under ITAR and EAR restrictions limit wave-optics solver technology flows to defense contractors in Massachusetts and California, fragmenting global distribution. Supply concentrates in the United States, Germany, and Japan where photonics clusters anchor specialized software consumption. Raw material dependencies include GPU accelerator chips from NVIDIA and AMD, optical glass composition data from Schott and Hoya, and cloud infrastructure from hyperscale providers. Single-source vulnerability runs through Taiwan Semiconductor Manufacturing Company's EUV lithography tool deployment schedules. Distribution runs through direct enterprise sales for on-premise installations and self-service portals for SaaS tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
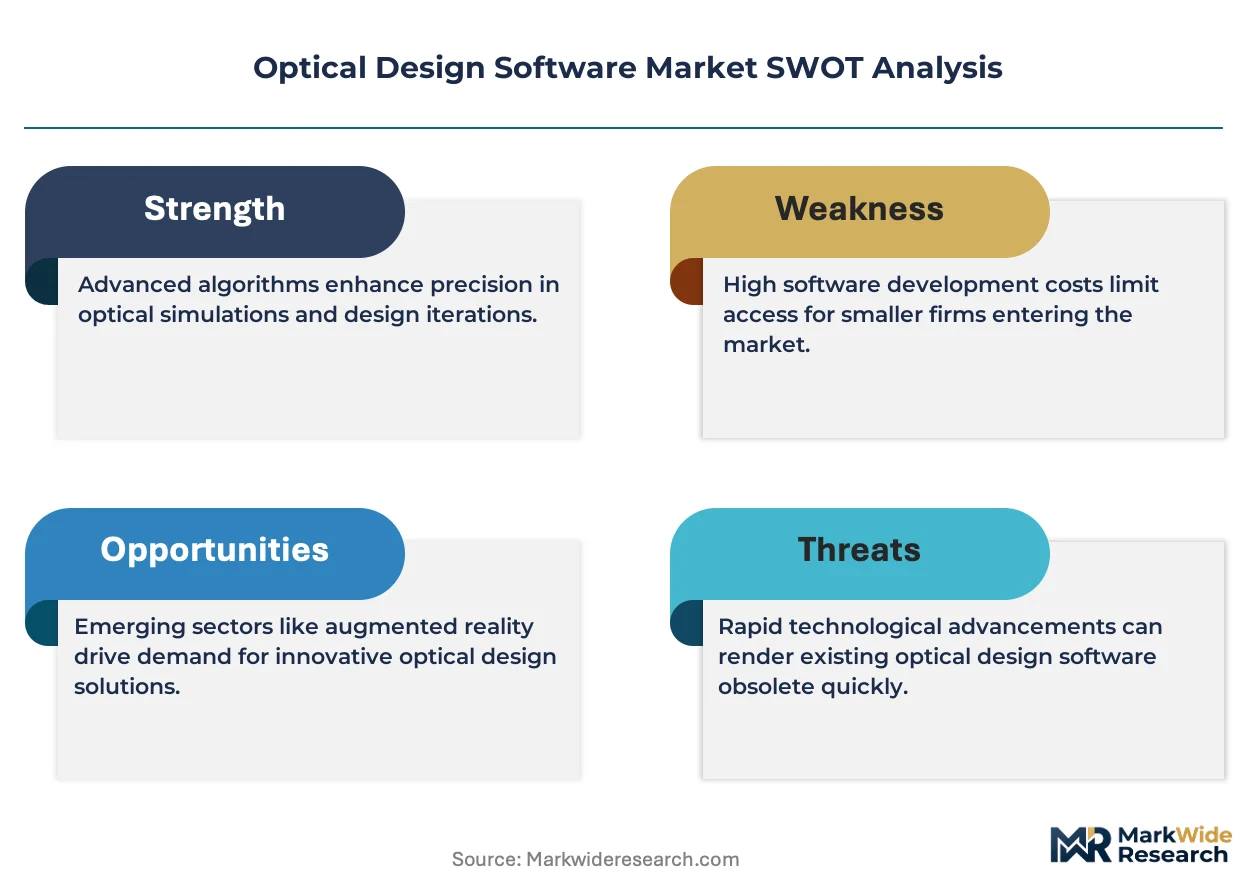
Open-source photonics simulation frameworks threaten to commoditize basic ray-tracing functionality, forcing incumbents to defend substitution through proprietary physics integration and regulatory-compliant validation workflows.
For Market Incumbents: Build switching-cost moats through deep integration of FDA validation traceability chains into ophthalmic and endoscopic design workflows. Incumbents should anchor backward integration into GPU-accelerated solver development to reduce dependency on NVIDIA hardware pricing. Cloud-native platform restructuring addresses the threat from agile SaaS entrants targeting mid-tier manufacturers. For New Entrants and Emerging Players: India's PLI-linked photonics investments in Bangalore and Hyderabad represent underpenetrated white space where domestic manufacturing incentives outpace established vendor presence. New entrants should target semester-based billing for national laboratories as the most penetrable procurement pattern, leveraging consumption-metered access to bypass perpetual license incumbency. A channel partnership strategy with Indian engineering services firms accelerates market entry without direct sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EDA-heritage platforms will absorb specialized illumination engineering tools to extend semiconductor-optical boundaries. Acquisition targets should display deep physics integration in wave-optics methods and established user communities at Max Planck Institute or Tsukuba research clusters. The signal to watch is AI-assisted optimization module deployment by automotive lighting suppliers, indicating automation-driven margin compression that favors scaled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | GPU-accelerated SaaS delivery captures research institutions trading CapEx for operational flexibility. |
| AI-Assisted Optimization Module Development | Machine learning convergence with ray-tracing engines compresses design iteration cycles for German automotive Tier-1 suppliers. |
| Regulatory Affairs Function Investment | Dedicated ECHA REACH compliance teams secure procurement from French and German metrology institutes. |
| Academic Subscription Tiering | Floating license pools address budget seasonality at U.S. National Science Foundation awardees. |
| Hybrid Deployment Architecture | Mixed on-premise and cloud burst models satisfy South Korean display panel manufacturers' IP sensitivity. |
Research Methodology
Initial hypotheses were tested against primary input from optical design software product managers, semiconductor foundry process engineers, defense contractor procurement officers, and national metrology institute research scientists and refined through secondary validation. Primary fieldwork encompassed structured interviews across 12 stakeholder roles spanning EDA-heritage vendors, specialized optics houses, and sector-specific tool developers. Secondary sources included SEC 10-K filings from listed simulation software providers, ECHA substance restriction updates, FDA 510(k) optical device submissions, and IEEE photonics conference proceedings. Bottom-up license deployment tracking was triangulated against top-down market sizing from vendor revenue disclosures.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled by deployment architecture, computational method, end-user sophistication tier, and regional regulatory cluster. CAGRs were derived from installed base evolution and pricing trajectory analysis rather than simple extrapolation. Industry-specific forecast inputs included EUV lithography node transition schedules from ASML supply chain partners and PLI scheme disbursement timelines from India's Ministry of Electronics and Information Technology.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers entering specialized simulation markets would shift outcomes. Material shifts in FDA software validation requirements for AI-generated optical designs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Thermal Analysis Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Custom Software Development Market
Software & Services
Account-Based Advertising Software Market
Software & Services
SAP HANA and S4HANA Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Global Application Release Automation Market
Software & Services
Global Absence Management Software Market
Software & Services
Global Survey Software Market
Software & Services
Software Release Management Tools Market
Software & Services
Global Intelligent Apps Market
Software & Services
Global Testing Software Market
Software & Services
Middle East HR Payroll Software Market