
 Cloud Backup and Recovery Software Market | 2026-2036
Cloud Backup and Recovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Backup and Recovery Software Market Analysis
Subscription-based software-defined backup tiers is restructuring how vendors monetize cloud data protection, shifting perpetual licenses toward consumption-aligned recurring models. Microsoft Corporation leverages its Azure-native integration to anchor enterprise workloads within its cloud ecosystem. Veeam Software specializes in multi-cloud portability, allowing customers to navigate heterogeneous infrastructure without vendor lock-in. Rubrik differentiates through immutable backup architectures that compete on ransomware resilience rather than storage economics alone.
Cloud backup and recovery software comprises agent-based or agentless applications that capture, deduplicate, encrypt, and replicate enterprise datasets across distributed infrastructure with recovery point objectives measured in minutes. The technology serves commercial and industrial users by minimizing downtime, satisfying audit requirements, and enabling granular restoration of virtual machines, databases, and SaaS application data. Hybrid cloud deployment configurations currently occupy the largest addressable base as organizations retain sensitive workloads on-premise while bursting archival copies to public environments. Disaster recovery as a solution type is expanding fastest among mid-market buyers who previously relied on tape rotation and cold-site contracts. Managed backup services within the service model dimension concentrate margin pools because providers bundle monitoring, compliance reporting, and incident response into multi-year agreements.
FDA enforces 21 CFR Part 11 requirements that shape validation protocols for pharmaceutical and medical device manufacturers selecting backup platforms. HIPAA mandates business associate agreements that restrict which cloud regions and subcontractors may process protected health information. The EU AI Act and GDPR cross-reference data governance obligations that influence where European enterprises provision recovery infrastructure. Stakeholders must weigh sovereignty requirements against hyperscaler economies of scale when architecting resilient data protection strategies.
Market Dynamics
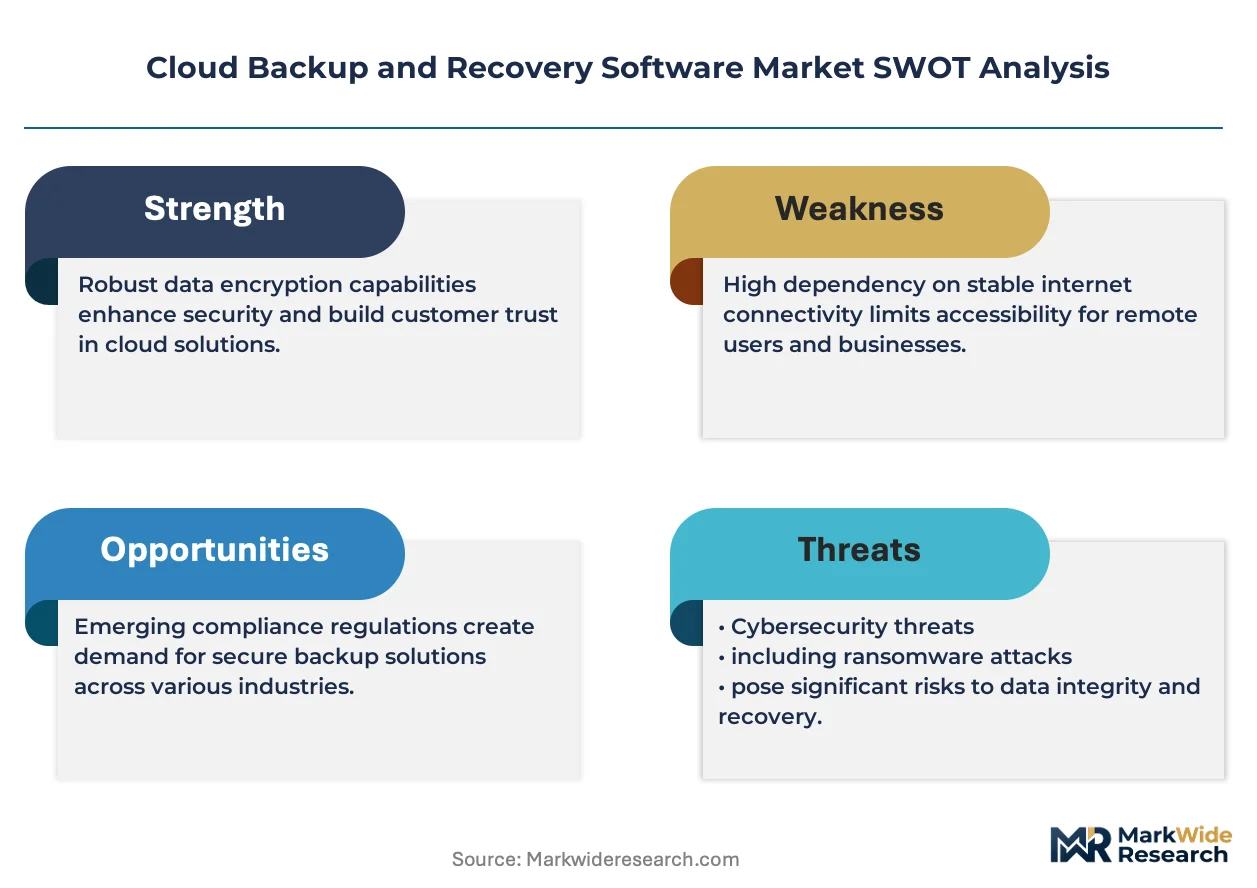
Ransomware frequency is forcing enterprises to re-architect backup infrastructure around immutability and air-gapped recovery tiers, shifting procurement criteria from storage economics to cyber resilience guarantees.
Growth Catalysts
- HIPAA Business Associate Agreements:Healthcare systems in the United States must verify backup vendors meet strict data handling protocols, creating mandatory upgrade cycles for legacy tape-dependent providers.
- India's Data Localization Mandates:Enterprises operating in India face requirements to maintain in-country recovery infrastructure, driving sovereign cloud capacity buildouts and domestic vendor partnerships.
- Immutable Snapshot Architectures:Write-once-read-many storage protocols prevent encrypted payload overwrites, giving buyers technical confidence to accelerate cloud migration timelines.
Market Restraints
- Hyperscaler Concentration Risk:Three vendors control the majority of underlying object storage infrastructure, creating single-point-of-failure exposure for multi-tenant backup platforms.
- GDPR Cross-Border Transfer Friction:European enterprises face legal uncertainty when replicating recovery copies to non-adequacy jurisdictions, complicating disaster recovery topology design.
- Egress Fee Volatility:Cloud providers impose unpredictable data retrieval charges that distort total cost of ownership calculations and delay procurement approvals.
Strategic Opportunities
- Germany's Gaia-X Sovereignty Framework:Federated data infrastructure standards create openings for European-native backup vendors to displace US-dominated incumbents in public sector tenders.
- SaaS Application Coverage Gaps:Native backup tools from Microsoft 365 and Salesforce leave recovery granularity limitations, creating attach opportunities for third-party platforms.
- AI-Assisted Recovery Orchestration:Machine learning models trained on failure patterns are automating runbook execution, compressing mean time to recovery for database workloads.
Industry Challenges
- Legacy Mainframe Integration Complexity:Financial institutions struggle to extend immutable backup protocols to IBM z/OS environments, requiring costly middleware development.
- Multi-Cloud Skill Scarcity:Certified architects capable of designing resilient topologies across AWS, Azure, and Google Cloud command premium compensation, constraining service provider expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Backup and Recovery Software Market |
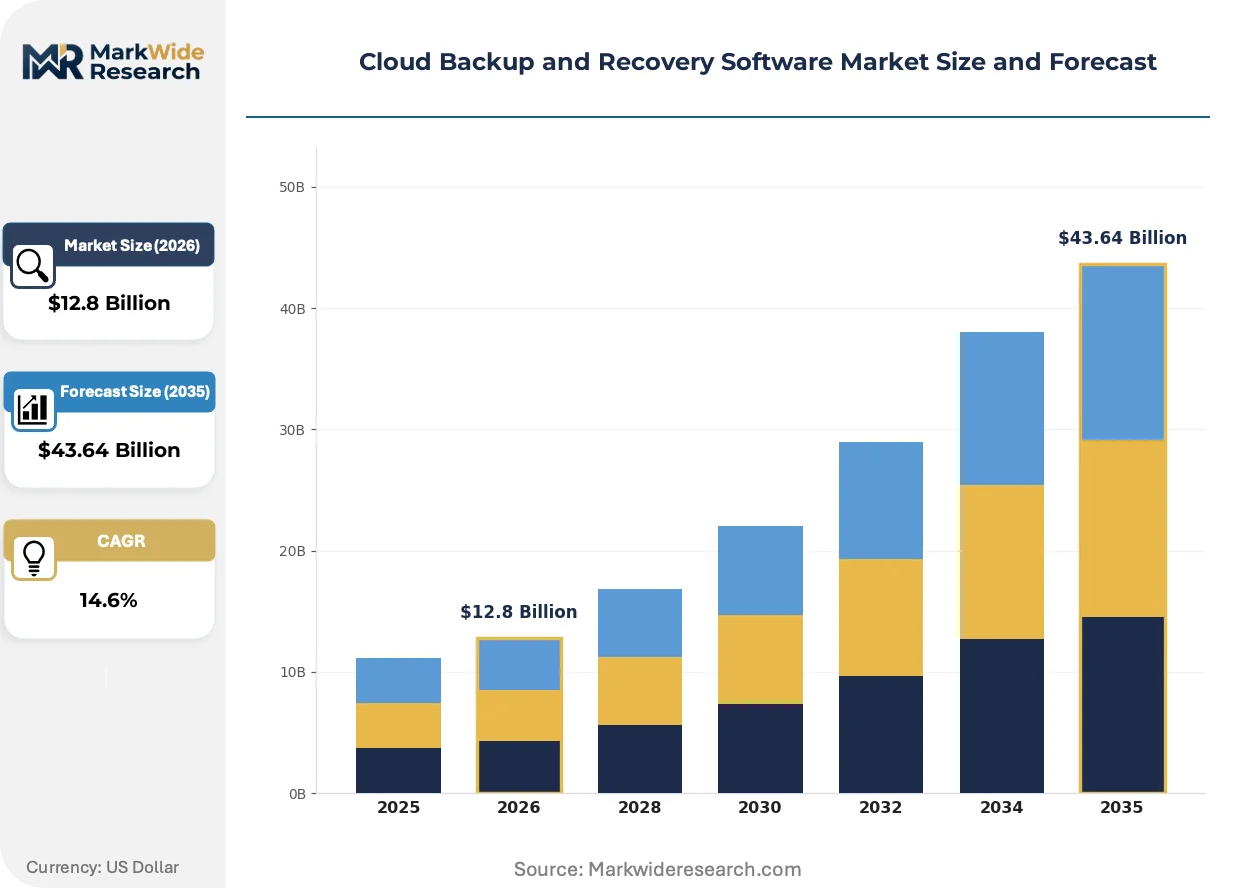
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Solution Type: Disaster Recovery, Data Archiving, Continuous Backup, Remote Backup End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Service Model: Backup as a Service, Recovery as a Service, Managed Backup, Data Transfer Services |
| Companies Covered | Microsoft Corporation, IBM Corporation, Veeam Software, Commvault, Rubrik, Cohesity, Veritas Technologies, Dell Technologies, Druva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Backup and Recovery Software Market Emerging Trajectories
Agentless data capture methods are displacing traditional endpoint software, reducing deployment friction while expanding coverage to ephemeral container workloads and serverless functions.
Continuous data protection platforms are automating sub-minute recovery point objectives by streaming block-level changes directly to object storage, eliminating scheduled backup windows. Mid-market manufacturers with limited IT staffing are adopting these tools fastest, trading upfront subscription costs for eliminated overnight operational overhead. The technology is automating compliance evidence collection for FDA-regulated environments, compressing audit preparation cycles from weeks to hours.
The EU AI Act cross-references GDPR data governance obligations, requiring backup vendors to document training data lineage and deletion capabilities for machine learning models embedded in recovery platforms. Pharmaceutical sponsors must now validate that AI-driven anomaly detection in backup systems does not introduce algorithmic bias into audit trails. German medical device manufacturers are responding by demanding ISO 27001-certified AI operations from their backup suppliers.
Enterprise procurement teams are consolidating backup spend under infrastructure-as-a-service contracts rather than standalone software licenses, unbundling professional services from product subscriptions. Value-added resellers face margin compression as hyperscalers sell direct through enterprise agreements, forcing channel partners to pivot toward managed detection and response bundles. This pattern is most visible in United States healthcare systems, where CIOs prefer single-vendor accountability for both primary storage and disaster recovery outcomes.
Cloud Backup and Recovery Software Market Segmentation
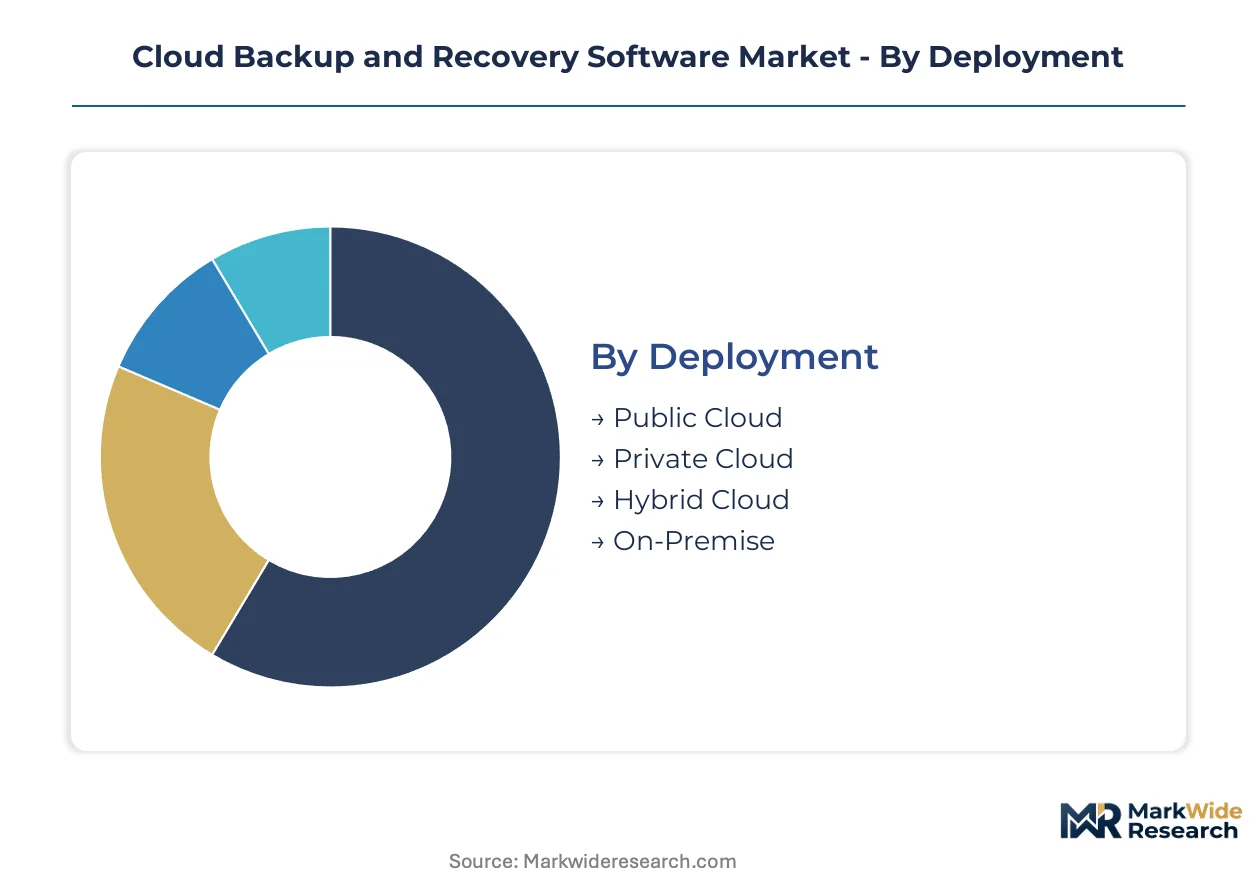
Cloud backup and recovery software exhibits divergent technical requirements across deployment topologies, organizational scale, and service consumption models. Procurement patterns fragment sharply between cost-sensitive mid-market buyers and regulated enterprises with immutable retention mandates. Vendors must architect platform variants that span consumption-aligned SaaS delivery through sovereign on-premise installations.
Deployment:
Architectural topology determines data sovereignty posture, latency constraints, and hyperscaler dependency exposure for enterprise recovery strategies.
- Hybrid Cloud:Organizations retain primary workloads on-premise while bursting archival copies to public object storage, balancing HIPAA-controlled data residency with elastic capacity. Financial services firms in the United States and German automotive suppliers concentrate demand here, driven by GDPR adequacy requirements and sub-hour recovery point objectives for trading systems.
- Public Cloud:Native Azure, AWS, and Google Cloud backup services eliminate capital expenditure for cloud-first enterprises. India's data localization mandates are redirecting this segment toward domestic cloud regions operated by local telecommunications providers.
- Private Cloud:Dedicated infrastructure serves defense contractors and pharmaceutical manufacturers requiring 21 CFR Part 11 validation protocols with air-gapped recovery tiers.
- On-Premise:Legacy tape-dependent healthcare systems and classified government networks maintain this architecture despite operational overhead.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Hybrid Cloud.
Solution Type:
Recovery granularity and automation sophistication separate premium offerings from commodity replication tools.
- Disaster Recovery:Automated failover orchestration compresses mean time to recovery from hours to minutes for database workloads. Mid-market manufacturers lacking dedicated site reliability engineering teams are expanding adoption fastest, trading upfront subscription costs for eliminated cold-site contracts.
- Continuous Backup:Block-level change streaming eliminates scheduled backup windows, satisfying FDA validation requirements for pharmaceutical batch record protection. German medical device manufacturers demand ISO 27001-certified implementations.
- Data Archiving:WORM-compliant long-term retention serves SEC 17a-4 and HIPAA record-keeping mandates with litigation hold capabilities.
- Remote Backup:Endpoint-centric protection for distributed workforces lacks enterprise-grade immutability, constraining adoption to SMB segments.
Established procurement concentrates on Data Archiving. Steepest expansion trajectory belongs to Continuous Backup.
End User:
Organizational scale dictates compliance burden complexity and acceptable total cost of ownership thresholds.
- Large Enterprises:Global 2000 corporations mandate multi-cloud portability and ransomware resilience guarantees over storage economics. These buyers consolidate backup spend under infrastructure-as-a-service contracts with single-vendor accountability clauses.
- SMEs:Limited IT staffing drives preference for managed backup services with bundled monitoring and incident response. India's domestic software vendors are capturing this segment through localized pricing and Hindi-language support.
- Government Agencies:FedRAMP and state-level certification requirements restrict vendor pools to established defense contractors.
- Educational Institutions:Budget constraints and fragmented IT governance produce price-sensitive procurement with limited disaster recovery sophistication.
Revenue concentration anchors with Large Enterprises. Gaining share fastest are SMEs adopting consumption-aligned service models.
Service Model:
Margin pools concentrate where providers bundle operational responsibility with software delivery.
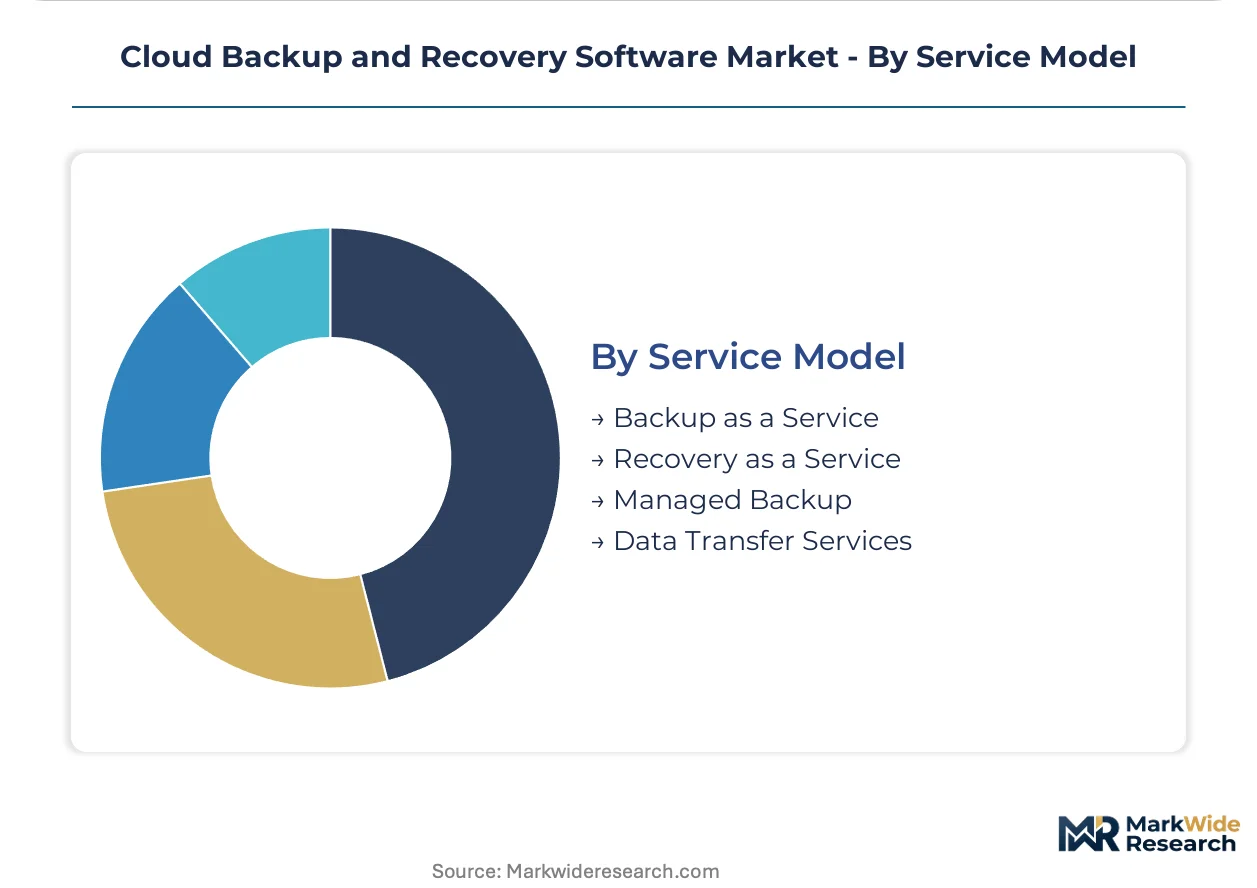
- Managed Backup:Providers assume 24/7 monitoring, compliance reporting, and incident response under multi-year agreements. United States healthcare systems prefer this model to satisfy HIPAA business associate agreement obligations without expanding internal security operations centers.
- Recovery as a Service:Guaranteed recovery time objectives with penalty-backed service level agreements appeal to risk-averse financial institutions. German banks under BaFin supervision are mandating these contracts for critical payment infrastructure.
- Backup as a Service:Self-service portals with metered consumption suit cloud-native development teams requiring ephemeral workload protection.
- Data Transfer Services:Physical appliance-based seeding and egress acceleration address bandwidth-constrained edge locations.
Contract value peaks with Managed Backup. Fastest-growing attach rates appear in Recovery as a Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Western Europe, while consumption spreads across healthcare systems in India and sovereign cloud deployments in Germany. Regulatory fragmentation is forcing vendors to maintain parallel infrastructure across jurisdictions.
United States
HIPAA business associate agreements mandate encrypted backup protocols for healthcare providers, driving replacement of tape-dependent systems. FDA enforces 21 CFR Part 11 validation requirements for pharmaceutical manufacturers selecting disaster recovery platforms. Boston's medical device cluster and North Carolina's research triangle anchor demand for compliant cloud infrastructure.
Germany
Gaia-X sovereignty frameworks create procurement preferences for European-native backup vendors in public sector tenders. GDPR adequacy requirements restrict cross-border replication to non-certified jurisdictions. Baden-Württemberg's automotive suppliers and Bavaria's medical technology manufacturers lead private cloud deployment for immutable retention.
India
Data localization mandates require in-country recovery infrastructure for enterprises processing citizen data. RBI and SEBI regulations impose retention periods on financial institutions. Mumbai's banking headquarters and Bengaluru's SaaS development centers drive sovereign cloud capacity buildouts with domestic vendor partnerships.
United Kingdom
NCSC cyber resilience standards influence backup architecture decisions across financial services and critical infrastructure operators. Post-Brexit data transfer mechanisms complicate disaster recovery topology design for multinational corporations. London's insurance market and Edinburgh's fintech cluster demand guaranteed recovery time objectives with penalty-backed service agreements.
Japan
METI guidelines on operational continuity shape enterprise procurement criteria for ransomware-resilient systems. Financial institutions under FSA supervision mandate air-gapped recovery tiers for core banking infrastructure. Tokyo's trading floors and Osaka's manufacturing headquarters concentrate demand for sub-minute recovery point objectives.
Cloud Backup and Recovery Software Market Vendor Landscape
Top-tier vendors anchor hyperscale cloud ecosystems, while mid-tier specialists compete on multi-cloud portability and immutable architectures. The vendor base stratifies across three tiers: cloud-native platforms with embedded backup services, independent software vendors with cross-platform orchestration, and managed service providers bundling operational responsibility. Strategic moves concentrate on M&A for data protection portfolios and partnerships with sovereign cloud operators.
Within the independent software tier, Veeam Software and Rubrik exemplify divergent positioning around multi-cloud flexibility versus ransomware-centric immutability. Microsoft Corporation occupies the ecosystem-anchored position through native Azure integration. Commvault represents the legacy-transition archetype as enterprises migrate from perpetual licenses toward consumption-aligned subscriptions.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Veeam Software |
| Commvault |
| Rubrik |
| Cohesity |
| Veritas Technologies |
| Dell Technologies |
| Druva |
| Others |
Supply Flow & Price Mechanics
United States healthcare systems consolidating backup spend under infrastructure-as-a-service contracts anchor pricing power with hyperscalers, compressing margin pools for independent software vendors and forcing channel partners toward managed service bundles.
Pricing Analysis
Margin tightening in the mid-market reflects hyperscaler direct-selling through enterprise agreements that bypass traditional value-added resellers. Pricing stratifies across consumption-aligned SaaS tiers, volume commitment discounts, and penalty-backed recovery time objective guarantees. Cost compression accelerates because CIOs prefer single-vendor accountability for primary storage and disaster recovery outcomes. SMEs exhibit highest price sensitivity, while regulated pharmaceutical manufacturers accept premium tiers for FDA-validated immutable retention.
Supply Chain Analysis
India's data localization mandates are redirecting sovereign cloud capacity buildouts toward domestic telecommunications providers, reshaping hyperscaler infrastructure deployment patterns. Underlying object storage infrastructure draws from United States, Ireland, and Singapore regions, with compute orchestration layers resting on semiconductor supply chains centered in Taiwan and South Korea. Single-source vulnerability concentrates in three vendors controlling majority object storage infrastructure. Distribution runs through direct enterprise agreements, managed service providers, and value-added resellers with compliance specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immutable snapshot architectures are displacing legacy tape-dependent backup systems, compressing procurement cycles and redefining vendor selection criteria around cyber resilience rather than storage economics alone.
For Market Incumbents: To counter hyperscaler ecosystem lock-in through native Azure and AWS integration, independent software vendors must deepen multi-cloud portability investments and pursue ISO 27001 certification for AI-driven anomaly detection modules. Capacity addition in Germany's Gaia-X federated infrastructure and India's sovereign cloud regions offers defensive positioning against regulatory fragmentation. For New Entrants and Emerging Players: SaaS application coverage gaps in Microsoft 365 and Salesforce recovery granularity present the most penetrable white-space for third-party platforms targeting mid-market manufacturers with limited IT staffing. German medical device manufacturers demanding validated AI operations and Indian SMEs seeking Hindi-language support represent parallel entry vectors. Go-to-market execution should anchor on managed backup service bundles with bundled compliance reporting. For Investors and Strategic Acquirers: The window for entry favors specialists with immutable architecture IP and sovereign cloud partnerships over generalist replication tools. Acquisition targets should demonstrate cross-platform orchestration capabilities and established HIPAA business associate agreement frameworks. The signal to watch is Gaia-X certification momentum displacing US-dominated incumbents in European public sector tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native anchoring captures enterprise workload gravity within Microsoft's cloud ecosystem. |
| Acquisition of Specialist Firm | Immutable architecture IP accelerates ransomware resilience differentiation against commodity replication. |
| Strategic Partnership | Gaia-X federation membership unlocks German public sector procurement preferences. |
| Geographic Expansion | India sovereign cloud buildouts satisfy RBI data localization mandates for financial institutions. |
| Product Launch | AI-assisted recovery orchestration compresses mean time to recovery for database workloads. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chief technology officers, IT procurement officers, platform engineers, and channel partners specializing in compliance. SEC 10-K disclosures, hyperscaler capex reports, and hospital procurement databases provided demand-side validation. Bottom-up sizing of deployment configurations and solution types triangulated against top-down industry spend estimates from trade associations.
Reconciliation of shipment data, vendor revenue disclosures, and end-user survey responses informed the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, organization scale, service consumption model, vertical regulatory cluster, and regional sovereignty posture. CAGRs were derived from curve-fitting historical adoption patterns against regulatory mandate timelines and infrastructure investment cycles. AI-assisted recovery adoption rates and sovereign cloud capacity buildouts served as industry-specific forecast inputs.
Revisions become necessary when data localization mandates expand to additional jurisdictions, hyperscaler egress fee structures shift materially, or ransomware attack vectors evolve beyond current immutable snapshot protections. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise cloud migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Category Management Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
G Suite Technology Services Market
Software & Services
Debt Collection Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Brain Training Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Load Testing Software Market
Software & Services
Service Scheduling Software Market
Software & Services
HPC Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Printing Software Market
Software & Services
Discount Management Software Market
Software & Services
Applicant Tracking System (ATS) Market