
 Public Financial Management Software Market | 2026-2036
Public Financial Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Public Financial Management Software Market Analytics
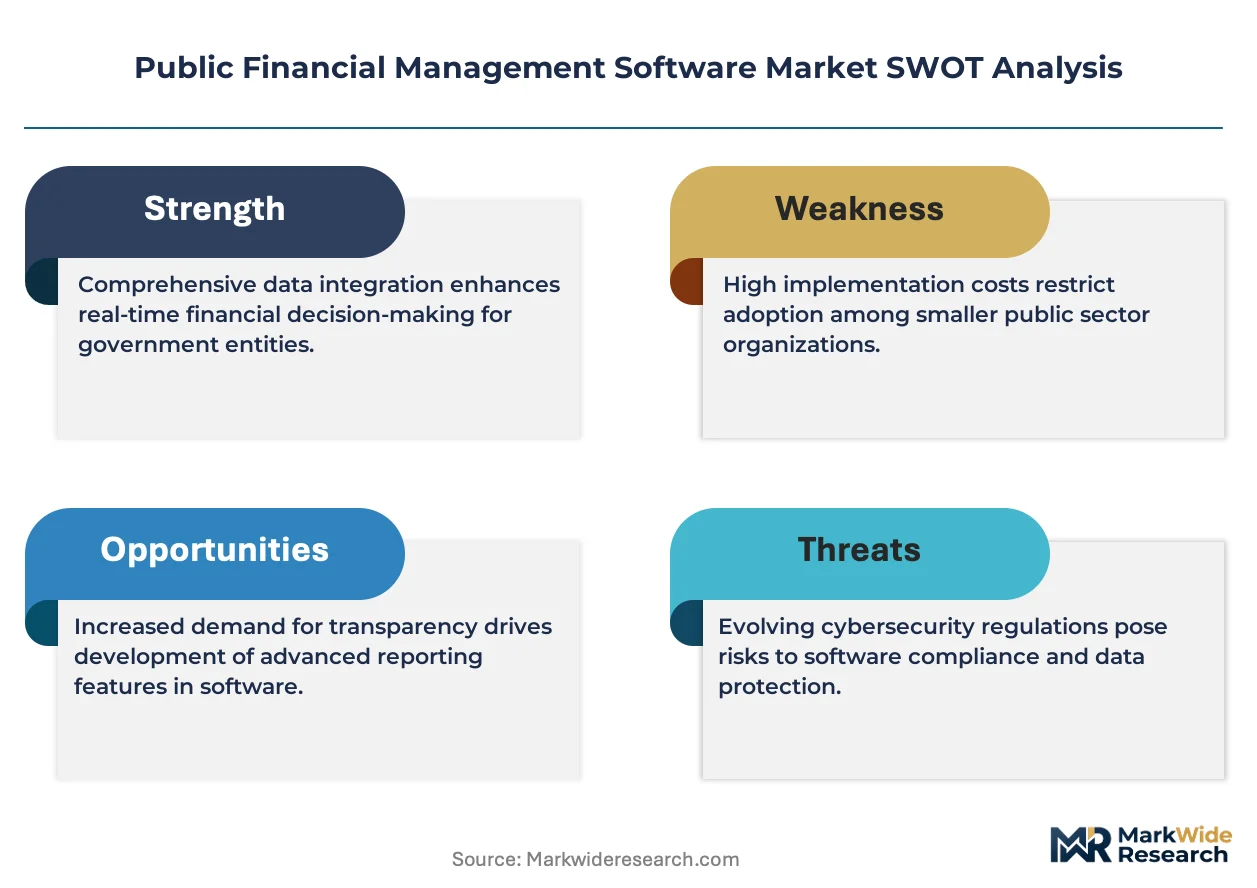
EU Green Deal public procurement standards is expanding the addressable market for environmental impact tracking modules within financial platforms. Tyler Technologies dominates state-level enterprise resource planning deployments across the United States. OpenGov leverages its cloud-native architecture to anchor municipal budgeting workflows in mid-sized cities. Questica specializes in capital planning and project cost management for Canadian and US provincial governments.
Public financial management software encompasses integrated digital platforms that automate government accounting, budget formulation, treasury operations, and fiscal reporting through multi-ledger architectures supporting fund-based accounting standards. These systems enforce segregation of duties, maintain audit trails compliant with GASB and IPSAS frameworks, and enable real-time consolidation across departmental appropriations. Cloud-based deployment leads functionality adoption as municipalities abandon legacy client-server installations that demand dedicated IT maintenance. Government agencies represent the deepest end-user segment where procurement modules and audit management tools command premium pricing due to compliance complexity. Subscription-based pricing models now displace perpetual licenses, shifting vendor revenue toward recurring streams and lowering upfront barriers for budget-constrained public buyers.
FERC grid investment rules, GASB Statement 87 lease accounting standards, and the EU AI Act's public sector algorithmic transparency requirements collectively reshape product roadmaps and certification requirements for vendors serving regulated public institutions. The US Office of Management and Budget's federal zero trust architecture mandate accelerates security hardening investments across SaaS providers. Stakeholders must evaluate how emerging interoperability standards between treasury systems and central bank digital currency infrastructure will redefine platform architecture decisions.
Market Dynamics
Cloud migration is compressing deployment cycles from 18-month on-premise installations to 90-day SaaS rollouts, forcing incumbent vendors to rebuild architecture around API-first microservices and consumption-based pricing tiers.
Growth Catalysts
- FERC grid investment rules:US utilities must modernize capital planning modules to track rate-base eligibility and depreciation schedules across transmission assets.
- Germany's federal-state-municipal coordination:Complex intergovernmental fiscal flows create demand for multi-ledger consolidation engines that reconcile appropriations across administrative levels.
- AI-augmented audit trails:Machine learning anomaly detection is automating fraud prevention in procurement workflows, reducing manual sampling requirements.
Market Restraints
- Legacy data migration costs:Municipal IT departments face six-figure professional services bills to extract historical appropriation records from 1990s-era COBOL systems.
- Treasury system vendor concentration:Three dominant banking interface providers control 70% of US state-level payment rails, creating single-point-of-failure risk.
- EU AI Act algorithmic transparency:Public sector automated decision systems require explainability documentation that extends procurement module development timelines.
Strategic Opportunities
- Canadian provincial capital planning:Infrastructure stimulus programs are expanding demand for project cost management tools that track multi-year appropriation carryforwards.
- Central bank digital currency interoperability:Treasury platforms that pre-integrate with pilot CBDC settlement layers will capture early-mover advantage in wholesale payment modernization.
- EU Green Deal procurement standards:Environmental impact tracking modules are becoming mandatory selection criteria for public tenders above threshold values.
Industry Challenges
- GASB 87 lease accounting expertise:Government finance departments lack personnel trained to classify service concession arrangements and calculate right-of-use liabilities.
- Zero trust security retrofit:Federal architecture mandates require SaaS vendors to reengineer identity management and data segmentation without disrupting 24/7 treasury operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Financial Management Software Market |
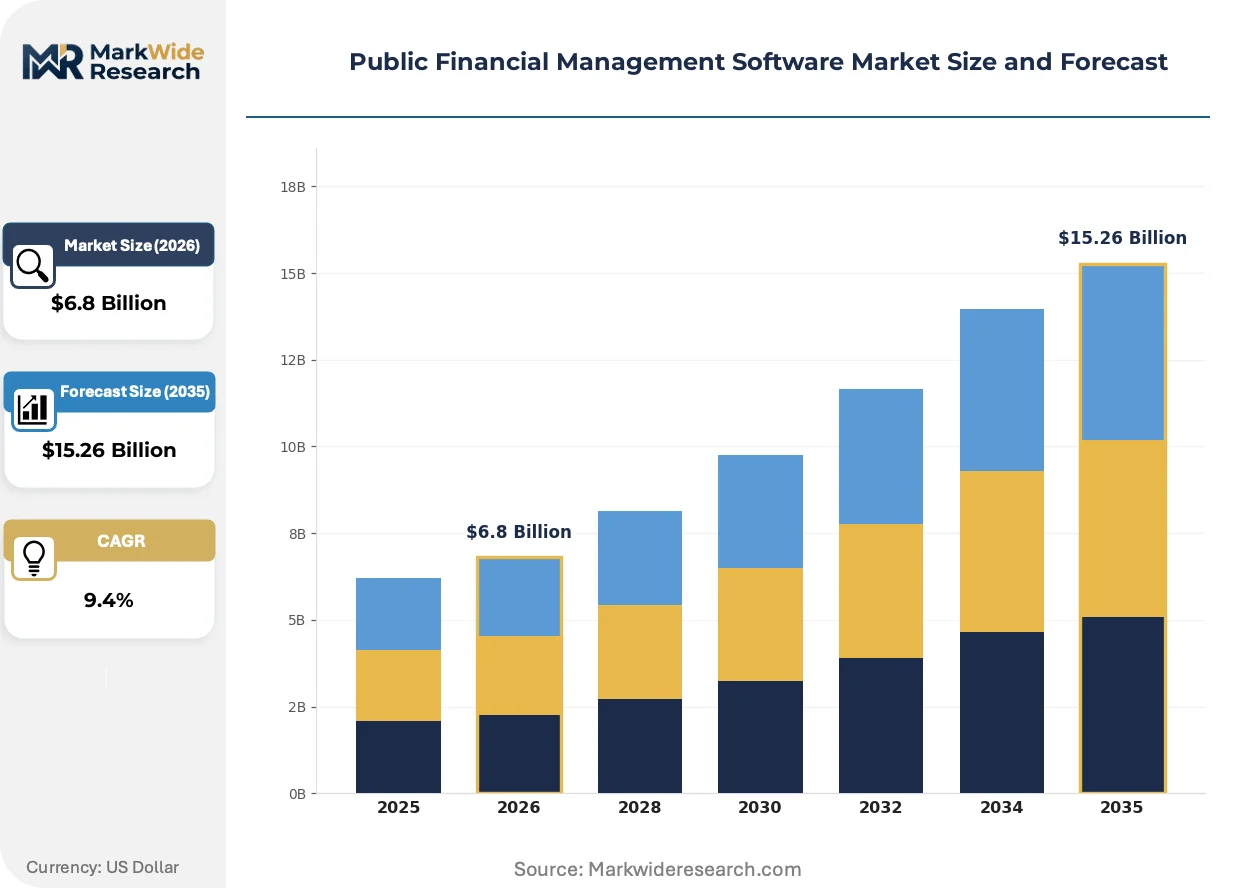
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Government Agencies, Non-Profit Organizations, Educational Institutions, Municipalities Functionality: Budgeting, Reporting, Procurement, Audit Management Pricing Model: Subscription-Based, Perpetual License, Usage-Based, Free Trial |
| Companies Covered | Salesforce, Questica, Tyler Technologies, Accela, LogiSense, OpenGov, Euna Solutions, ClearGov, Cogitate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Financial Management Software Market Evolving Landscape
Generative AI and embedded analytics are redefining how budget officers interact with fiscal data, shifting from static reports to conversational interfaces that surface variance explanations and scenario projections on demand.
Natural language query engines are automating the translation of plain-English budget questions into structured SQL against multi-dimensional appropriation cubes. State finance departments in Texas and Florida are piloting these tools for legislative briefing preparation. The technology is automating analyst labor previously consumed by ad-hoc report requests, compressing response times from days to minutes.
The EU CSRD reporting mandates are forcing public sector entities to adopt double materiality assessment frameworks that track both financial and sustainability impacts. European municipalities must now publish machine-readable sustainability disclosures that integrate with national statistical databases. German Länder finance ministries are responding by procuring ESG data collection modules as mandatory add-ons to core financial platforms.
Budget formulation workflows are migrating toward collaborative cloud workspaces that replace sequential email-based review cycles with real-time multi-stakeholder editing. Mid-sized US cities with 50,000-250,000 residents are adopting these tools fastest, driven by city manager demands for faster council presentation cycles. California and Colorado municipalities show highest penetration, where charter requirements mandate public budget workshops with compressed comment periods.
Public Financial Management Software Market Segmentation
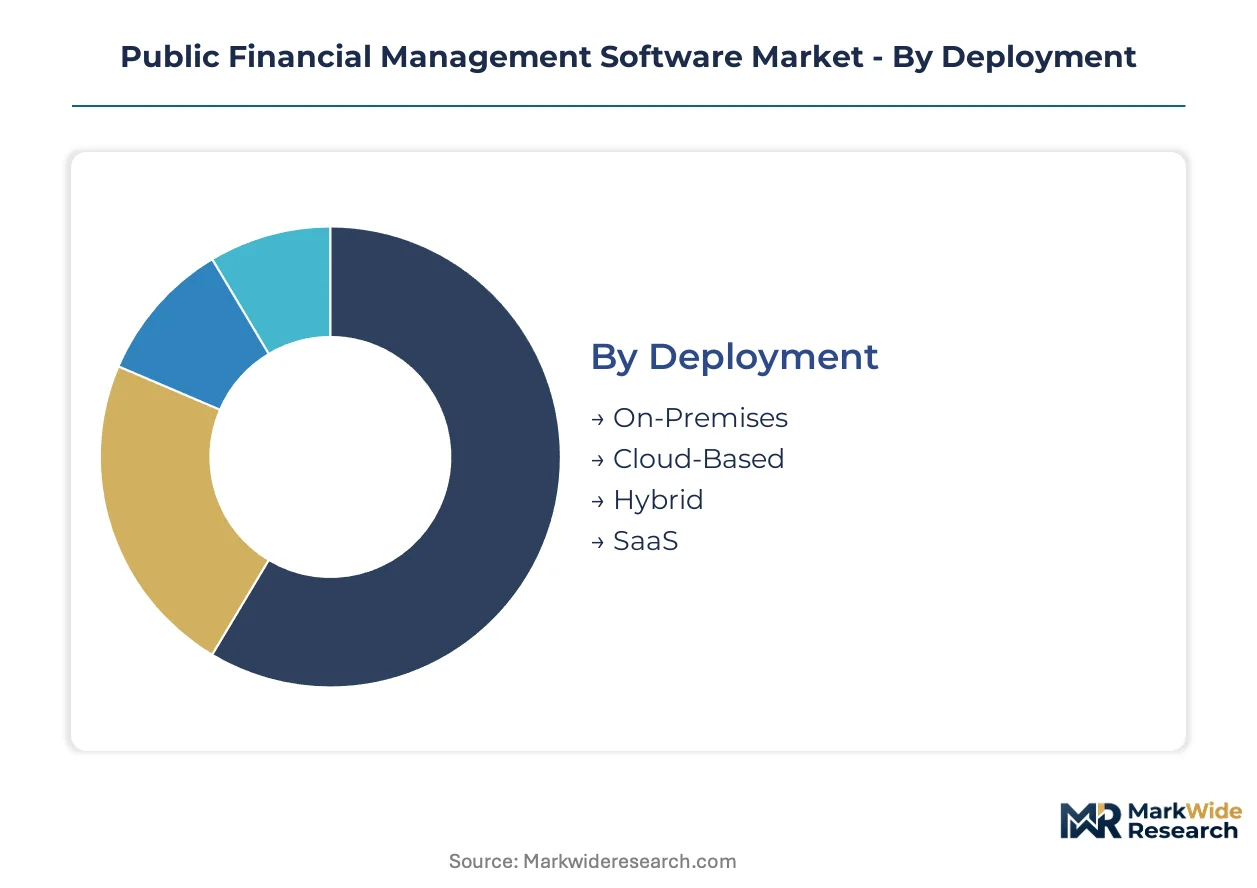
Public financial management software segments diverge sharply by deployment architecture and procurement authority. Integration depth determines whether modules operate as standalone systems or embed within broader enterprise resource planning stacks.
Deployment:
Cloud-native architectures displace client-server installations as municipalities abandon dedicated IT maintenance obligations.
- Cloud-Based:Multi-tenant SaaS platforms host government accounting data on shared infrastructure with automatic security patching. Demand concentrates in mid-sized US municipalities where city managers prioritize 90-day implementation cycles over 18-month on-premise deployments. Tyler Technologies and OpenGov anchor this segment with API-first microservices.
- SaaS:Subscription delivery models shift revenue recognition to recurring streams and eliminate upfront capital expenditure barriers for budget-constrained public buyers. German Länder finance ministries procure these solutions to meet federal-state-municipal fiscal coordination requirements without infrastructure ownership.
- On-Premises:Legacy installations persist where data sovereignty mandates or air-gapped security requirements override cloud migration incentives.
- Hybrid:Split architectures maintain sensitive treasury operations on-premise while offloading reporting modules to cloud instances.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to SaaS.
End User:
Procurement complexity and audit stringency separate premium-paying segments from cost-sensitive adopters.
- Government Agencies:Federal and state departments enforce segregation of duties through multi-ledger architectures supporting GASB and IPSAS frameworks. Procurement modules and audit management tools command premium pricing due to compliance complexity. The US Office of Management and Budget's zero trust architecture mandate accelerates security hardening investments.
- Municipalities:Cities with 50,000-250,000 residents adopt collaborative cloud workspaces fastest, driven by compressed council presentation cycles. California and Colorado municipalities show highest penetration where charter requirements mandate public budget workshops.
- Educational Institutions:University finance departments track restricted fund balances across research grants and endowment portfolios.
- Non-Profit Organizations:Grant compliance requirements drive demand for restricted net asset tracking and donor restriction management.
Revenue concentrates in Government Agencies; Municipalities are climbing the fastest.
Functionality:
Module interconnectivity determines whether platforms serve as point solutions or integrated fiscal operating systems.
- Budgeting:Cloud-native formulation workflows replace sequential email-based review cycles with real-time multi-stakeholder editing. Natural language query engines automate translation of plain-English budget questions into structured SQL, compressing legislative briefing preparation from days to minutes in Texas and Florida pilot programs.
- Audit Management:Machine learning anomaly detection automates fraud prevention in procurement workflows, reducing manual sampling requirements. EU AI Act explainability documentation extends development timelines but creates competitive moat for compliant vendors.
- Reporting:Double materiality assessment frameworks track financial and sustainability impacts under EU CSRD mandates.
- Procurement:Environmental impact tracking modules become mandatory selection criteria for public tenders above threshold values under EU Green Deal standards.
Adoption concentrates in Budgeting; Audit Management shows steepest expansion trajectory.
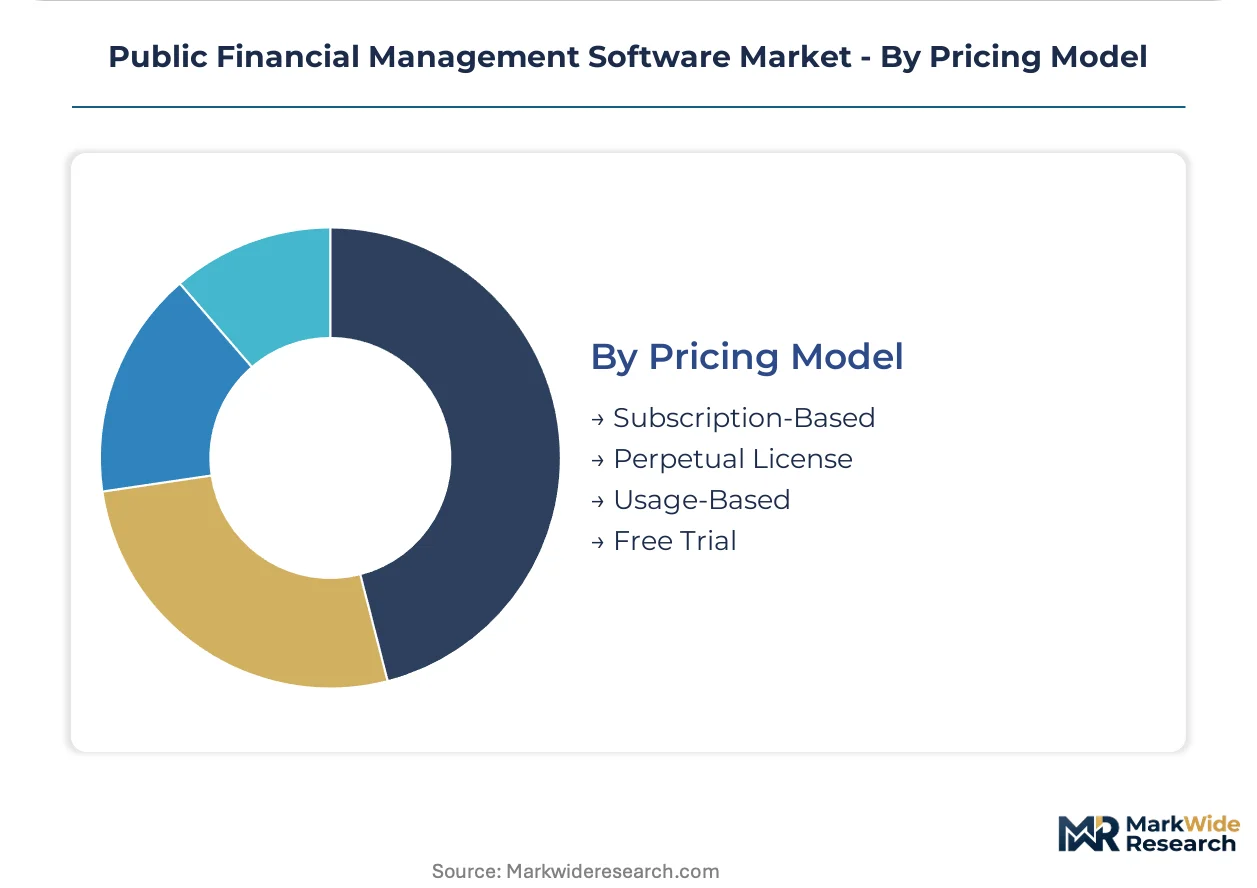
Pricing Model:
Contract structure aligns vendor cash flows with public sector budget cycles and appropriation volatility.
- Subscription-Based:Annual or multi-year recurring contracts displace perpetual licenses across SaaS deployments. This model lowers upfront barriers for municipalities with unpredictable tax revenue streams and shifts vendor revenue toward predictable recurring streams.
- Perpetual License:One-time acquisition with maintenance fees persists in on-premise installations where capital budgets accommodate lump-sum appropriations.
- Usage-Based:Consumption tiers align costs with transaction volumes or user counts for agencies with seasonal workload fluctuations.
- Free Trial:Limited-functionality pilots reduce procurement risk for skeptical finance departments evaluating cloud migration.
Contract volume concentrates in Subscription-Based; Usage-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C.'s concentration of federal procurement agencies and SaaS vendors anchors North American demand for treasury modernization platforms. Municipal finance departments in Sacramento and Austin are piloting cloud-native budgeting workflows ahead of statewide rollouts.
United States
FERC grid investment rules and GASB Statement 87 lease accounting standards drive utility and state agency procurement. The US Office of Management and Budget's zero trust architecture mandate accelerates security hardening investments across SaaS providers. Texas and Florida state finance departments pilot natural language query engines for legislative briefing preparation.
Germany
Federal-state-municipal fiscal coordination requirements create demand for multi-ledger consolidation engines. The EU CSRD reporting mandates and EU AI Act algorithmic transparency requirements reshape certification requirements for vendors serving public institutions. Bavarian and North Rhine-Westphalian Länder finance ministries procure ESG data collection modules as mandatory platform add-ons.
Canada
Infrastructure stimulus programs expand demand for project cost management tools tracking multi-year appropriation carryforwards. Canadian provincial governments enforce IPSAS-compliant audit trails through modernized treasury operations. Ontario and Quebec municipal clusters adopt capital planning modules for transit and utility modernization programs.
United Kingdom
Local government finance departments modernize accounting platforms ahead of consolidated audit deadlines. UK public sector procurement regulations emphasize environmental impact tracking for tenders above threshold values. Greater Manchester and West Midlands combined authorities deploy collaborative cloud workspaces for multi-stakeholder budget formulation.
France
Regional councils and departmental prefectures replace legacy client-server installations with subscription-based SaaS platforms. ANSM and CNIL data governance standards influence public sector software selection criteria. Île-de-France municipalities integrate sustainability disclosure modules with national statistical databases under EU Green Deal alignment requirements.
Public Financial Management Software Market Competitive Landscape
The competitive structure tilts toward cloud-native specialists with API-first architectures. Incumbent enterprise resource planning vendors and municipal-focused SaaS providers occupy distinct tiers with minimal direct overlap. Three strategic archetypes dominate: legacy system modernizers, pure-play cloud natives, and capital planning specialists. Geographic expansion into Canadian provinces and strategic partnerships with treasury system vendors represent the dominant competitive moves.
Within the cloud-native tier, OpenGov and ClearGov exemplify municipal-focused deployment models. Tyler Technologies anchors state-level enterprise resource planning deployments across mid-market agencies. Questica occupies a position within capital planning specialization for provincial and federal infrastructure programs.
| Leading Market Players |
|---|
| Salesforce |
| Questica |
| Tyler Technologies |
| Accela |
| LogiSense |
| OpenGov |
| Euna Solutions |
| ClearGov |
| Cogitate |
| Others |
Value Network & Pricing Analysis
Municipal budget officers' preference for 90-day SaaS deployment cycles forces vendors to compress professional services margins and absorb cloud infrastructure costs upfront, shifting pricing power toward buyers with predictable recurring revenue streams.
Pricing Analysis
Value-based pricing anchors on audit compliance outcomes and treasury uptime guarantees rather than seat counts. Three-tier pricing structure across premium, standard, and economy levels separates government agencies with GASB 87 complexity from mid-sized municipalities with basic budgeting needs. Cost compression in the economy tier intensifies because OpenGov and ClearGov compete aggressively for 50,000-250,000 resident city contracts. Educational institutions exhibit highest price sensitivity due to restricted fund accounting requirements that vendors struggle to scope accurately.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Canada maintain hub-and-spoke patterns for cloud infrastructure delivery. Software development draws from engineering talent pools in India, Poland, and Portugal for cost-efficient module customization. Single-source vulnerability concentrates in three dominant banking interface providers controlling state-level payment rails. Distribution runs through direct sales teams for enterprise agencies and channel partners for municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized GASB 87 lease accounting expertise scarcity props pricing for compliance-heavy modules, constraining supply expansion as vendors compete for qualified government finance specialists.
For Market Incumbents: To counter cloud-native entrants with faster deployment cycles, Tyler Technologies should acquire API-first specialists in municipal budgeting workflows and embed zero trust architecture certifications as mandatory platform standards. Capacity addition in German Länder markets addresses federal-state-municipal coordination demand without diluting US federal security investments. For New Entrants and Emerging Players: Enter via Canadian provincial capital planning segments where infrastructure stimulus programs lack incumbent saturation and procurement modules for multi-year appropriation carryforwards remain undersupplied. White-space concentration in Ontario and Quebec municipal clusters favors partnerships with treasury system vendors rather than direct competitive displacement. For Investors and Strategic Acquirers: The window for entry favors vertical software specialists with GASB and IPSAS certification moats rather than horizontal ERP players. Long-term viability rests on central bank digital currency interoperability investments and ESG data collection module integration. Watch for EU AI Act explainability documentation completion as inflection signal for compliant vendor premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first microservices enable 90-day municipal deployment cycles that displace legacy client-server installations. |
| Geographic Expansion | Canadian provincial infrastructure programs demand project cost management tools tracking multi-year appropriation carryforwards. |
| Strategic Partnership | Treasury system vendor alliances reduce single-point-of-failure risk in state-level payment rail integrations. |
| Acquisition of Specialist Firm | GASB 87 lease accounting expertise scarcity creates defensive moats for compliance module providers. |
| Product Launch | Environmental impact tracking modules capture EU Green Deal procurement standards for tenders above threshold values. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with government CIOs, municipal finance directors, procurement officers, and SaaS implementation specialists. SEC 10-K disclosures, FERC infrastructure investment reports, EU CSRD implementation guidance, and municipal budget audit databases provided validation layers. Bottom-up deployment volume estimates triangulated against top-down public sector IT spending aggregates.
Granularity-level modeling captured deployment architecture, end-user segment, functionality module, and pricing model dimensions at the country-regulatory cluster intersection. CAGRs derived from logistic adoption curves fitted to cloud migration penetration data and subscription revenue recognition patterns across the analysis window. Central bank digital currency pilot timelines and EU AI Act compliance cost assumptions informed scenario weightings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated CBDC interoperability mandates or retroactive GASB 87 restatement requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Compensation Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Non-Profit Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Global Call Center Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Optical Design Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Statistics Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Web Framework Software Market
Software & Services
Human Identification Analysis Software Market