
 Global Data Visualization Tools Market | 2026-2036
Global Data Visualization Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Visualization Tools Market Foresight
The gap between premium enterprise suites and lightweight embedded modules is realigning procurement patterns across the Global Data Visualization Tools Market. Tableau Software dominates the high-end segment through deep integration with Salesforce's ecosystem and advanced geospatial rendering capabilities. Microsoft Corporation leverages its Azure cloud backbone to bundle Power BI at aggressive price points, capturing mid-market expansion. QlikTech International AB differentiates through associative engine architecture that reduces query latency for complex datasets.
Data visualization tools comprise software platforms that transform structured and unstructured datasets into graphical representations—charts, heat maps, network diagrams, and interactive dashboards—enabling pattern recognition without manual statistical processing. These platforms ingest data through APIs, SQL connectors, and flat-file uploads, then apply rendering algorithms to produce visual outputs at refresh intervals ranging from batch daily cycles to sub-second streaming. Cloud-based deployment leads volume growth as organizations eliminate server maintenance overhead, while augmented analytics represents the fastest-expanding technology segment by automating insight generation through natural language queries and machine learning-driven anomaly detection. On-premises installations retain footholds in defense and regulated banking environments where data sovereignty requirements block external hosting.
The EU AI Act and GDPR impose algorithmic transparency obligations that shape how European vendors design explainable visualization layers, while the SEC's disclosure modernization rules in the United States mandate machine-readable financial reporting that feeds directly into BI dashboards. ISO 27001 certification has become a de facto market-access threshold for enterprise procurement teams evaluating vendor security postures. Stakeholders must weigh cloud migration timelines against evolving cross-border data localization requirements that could fragment platform architectures.
Market Dynamics
Cloud-native architectures are compressing deployment timelines and collapsing the traditional vendor lock-in that once protected incumbent platforms, forcing incumbents to restructure pricing around consumption-based metering rather than perpetual licenses.
Growth Catalysts
- Federal open-data mandates:US agencies must publish machine-readable datasets under the OPEN Government Data Act, creating procurement pull for tools that render public financial and operational data into citizen-accessible dashboards.
- Real-time risk monitoring:Financial services firms deploy streaming visualization layers to track counterparty exposures and liquidity positions, embedding BI into trading floor workflows rather than batch reporting cycles.
- Augmented analytics:Natural language query interfaces and automated anomaly detection reduce dependency on specialized data science teams, expanding addressable users from analysts to operational managers.
Market Restraints
- Cross-border data localization:Russia, China, and Vietnam require citizen data to reside within national borders, fragmenting cloud architectures and forcing redundant infrastructure investments.
- Skilled visualization designers:Shortage of professionals who combine statistical literacy with UX design principles limits enterprise ability to extract value from purchased platforms.
- Legacy on-premises sunk costs:Defense contractors and regulated banks face write-downs on existing server investments when migrating to cloud-native alternatives, delaying refresh cycles.
Strategic Opportunities
- India's digital public infrastructure:The Account Aggregator framework and UPI data streams create demand for visualization tools that render real-time payment flows and credit analytics for fintechs and NBFCs.
- EU AI Act explainability requirements:Mandates for algorithmic transparency create specialized demand for visualization layers that expose model decision paths to auditors and affected individuals.
- Edge computing convergence:Integration of visualization engines with IoT gateways enables factory-floor and retail-location dashboards without round-trip latency to centralized clouds.
Industry Challenges
- ISO 27001 certification timelines:Enterprise procurement teams require current security attestations, and vendor backlogs for auditor availability extend sales cycles by six to nine months.
- Multi-cloud integration complexity:Organizations operating across AWS, Azure, and GCP environments face data pipeline fragmentation that visualization platforms must reconcile through federated query architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Visualization Tools Market |
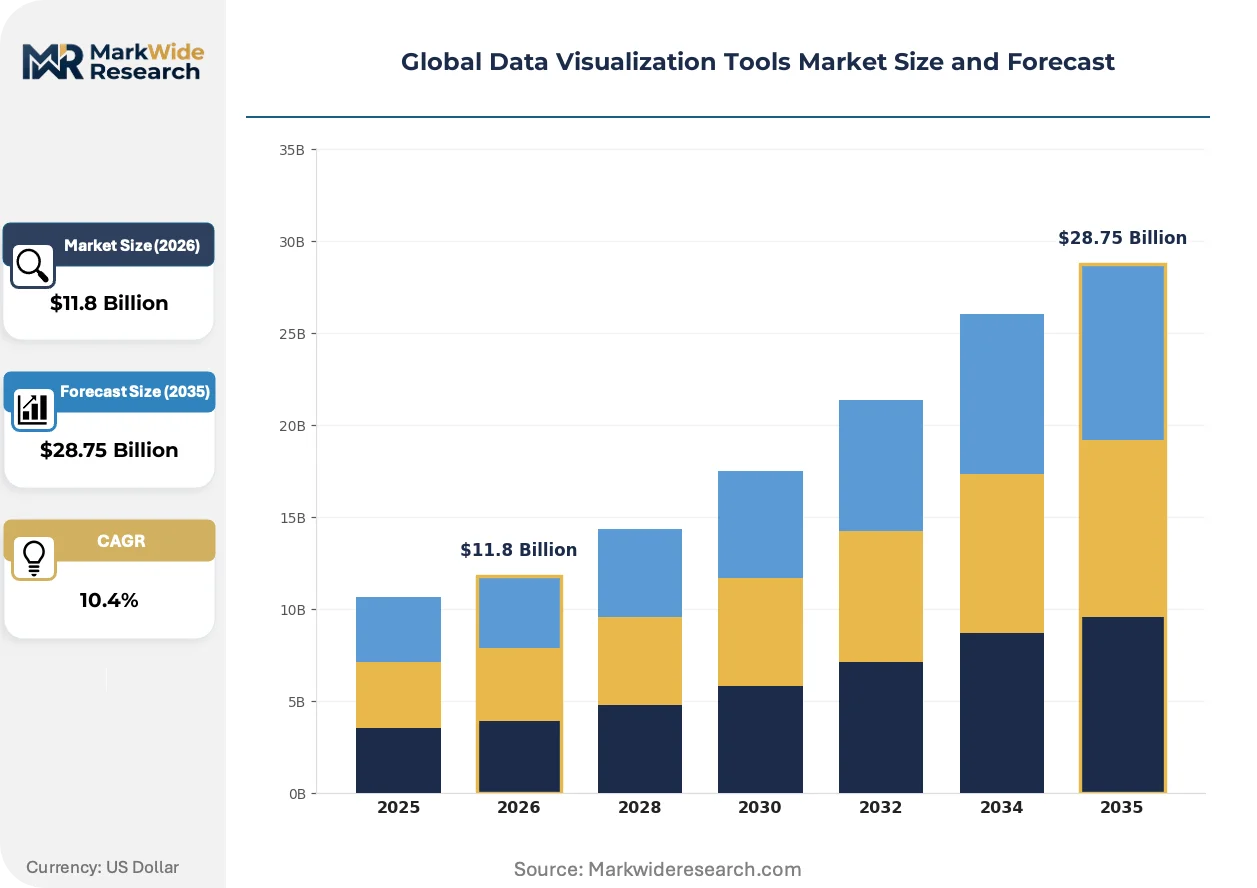
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $28.75 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Web-Based Technology: Interactive Dashboards, Geographic Information Systems, Real-Time Data Processing, Augmented Analytics, Predictive Analytics End User Industry: Financial Services, Telecommunication, Manufacturing, Education, Government Application: Business Intelligence, Customer Analytics, Risk Management, Operational Efficiency, Market Research |
| Companies Covered | Tableau Software, Microsoft Corporation, IBM Corporation, SAP SE, QlikTech International AB, Alteryx Inc., Domo Inc., Sisense Ltd., TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Visualization Tools Market Shifts & Advancements
Generative AI is compressing the distance between raw data and narrative insight, embedding natural language generation directly into visualization interfaces so that pattern detection and explanation occur within the same interaction layer.
Automated insight generation is automating the translation of statistical anomalies into contextual business narratives. Retail and logistics operators deploy these capabilities to flag inventory discrepancies and demand spikes without analyst intervention. The technology is automating the lowest tier of BI work, reallocating human attention toward hypothesis testing and strategic scenario modeling rather than descriptive reporting.
The EU AI Act's risk-based classification system mandates human oversight interfaces for high-stakes algorithmic decisions. Healthcare and credit-scoring applications must expose model inputs, confidence intervals, and alternative outcomes through interactive visual layers. German and French regulators are already enforcing these provisions through national supervisory authorities, accelerating vendor investment in explainable AI modules.
Self-service procurement is displacing centralized IT gatekeeping for departmental visualization licenses. Marketing and operations teams directly evaluate and adopt lightweight embedded tools through product-led growth channels rather than enterprise sales cycles. This pattern is most visible in US mid-market technology and professional services firms where SaaS management platforms track shadow IT proliferation.
Global Data Visualization Tools Market Segmentation
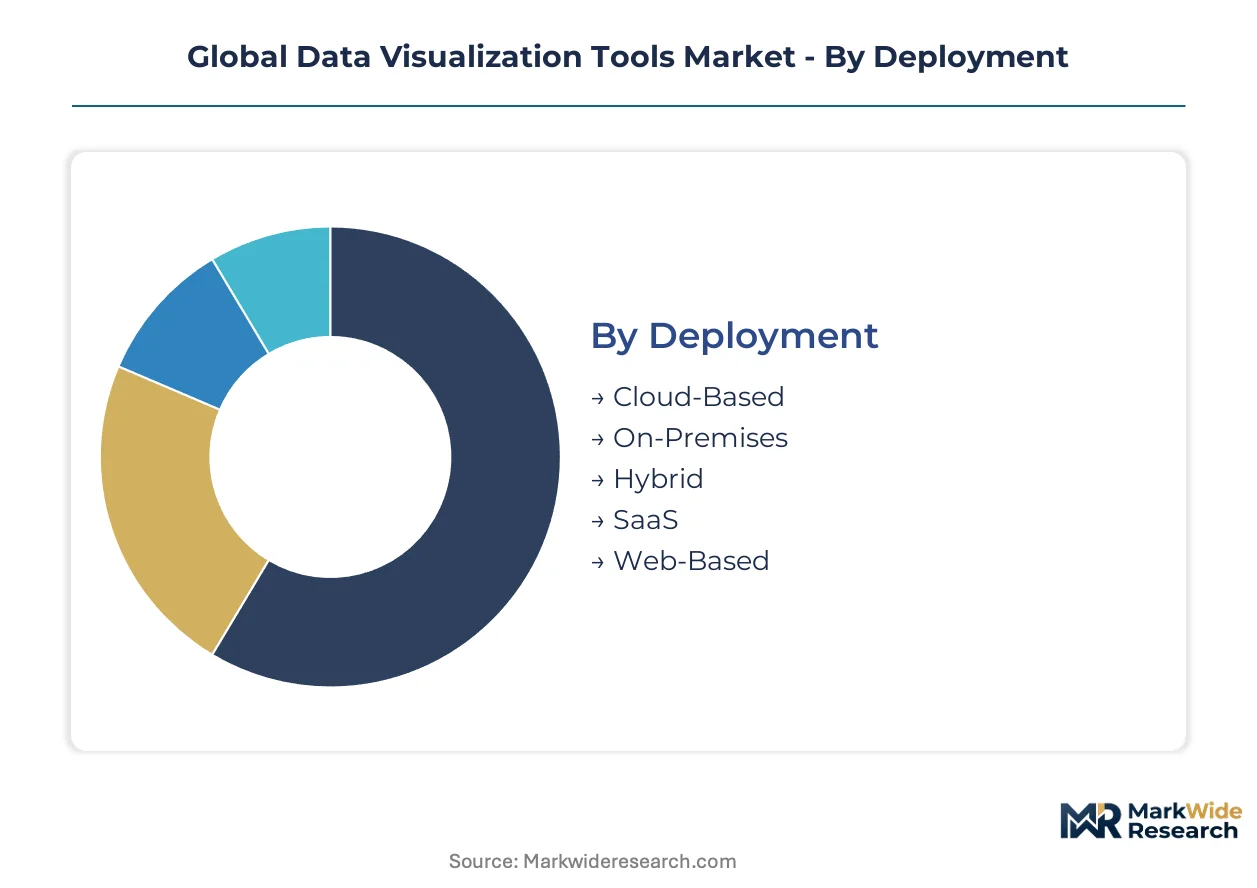
Procurement teams evaluate data visualization platforms through multiple lenses simultaneously. Deployment architecture determines total cost of ownership and compliance posture. Technology modality shapes which user populations can extract value without specialized training.
Deployment:
IT infrastructure budgets and data sovereignty requirements drive the initial platform selection decision.
- Cloud-Based:Multi-tenant architectures eliminate server procurement and maintenance overhead. United States federal agencies and Fortune 500 enterprises prioritize these deployments for elastic scaling during quarterly reporting surges.
- On-Premises:Dedicated hardware installations within corporate data centers. Defense contractors and Swiss banking institutions mandate these configurations to satisfy national security certifications and FINMA data localization rules.
- Hybrid:Split architectures route sensitive workloads to private infrastructure while pushing public dashboards to cloud edge nodes. German automotive manufacturers deploy this model to balance GDPR compliance with global operational visibility.
- SaaS:Fully managed subscription services with zero infrastructure footprint. Mid-market professional services firms in India and Brazil adopt these for rapid departmental deployment without central IT approval cycles.
- Web-Based:Browser-rendered visualization layers requiring no local software installation. Educational institutions and distributed field sales teams favor these for device-agnostic access across unmanaged endpoints.
Volume sits with Cloud-Based configurations; growth tilts toward Hybrid models as cross-border data fragmentation intensifies.
Technology:
The functional sophistication of the rendering engine determines which analytical questions the platform can answer.
- Interactive Dashboards:Drag-and-drop interfaces enabling non-technical users to manipulate filters, drill paths, and comparative time windows. Financial services risk committees in London and Singapore deploy these for real-time counterparty exposure monitoring.
- Geographic Information Systems:Spatial data layers combining coordinate-based datasets with demographic and infrastructure overlays. Telecommunication network planners and logistics dispatchers in the United States and Germany rely on these for coverage optimization and route planning.
- Real-Time Data Processing:Sub-second refresh intervals connecting streaming data pipelines to visual outputs. Manufacturing operations teams in Japan and South Korea implement these for production line anomaly detection.
- Augmented Analytics:Natural language query interfaces and automated insight generation reducing dependency on dedicated data science resources. Expanding most quickly among marketing departments seeking self-service customer segmentation.
- Predictive Analytics:Embedded statistical models projecting future states from historical patterns. Credit scoring and demand forecasting applications in India's NBFC sector drive specialized procurement here.
Interactive Dashboards capture the largest installed base; Augmented Analytics climbs the fastest as talent scarcity pressures enterprise analytics teams.
End User Industry:
Regulatory intensity and data volume characteristics create divergent technical requirements across verticals.
- Financial Services:Trading floor surveillance, regulatory reporting, and client portfolio visualization with millisecond latency requirements. SEC disclosure modernization rules and ECB stress testing mandates sustain procurement velocity in the United States and European Union.
- Telecommunication:Network performance monitoring, subscriber churn analysis, and infrastructure capacity planning. 5G rollout investments in South Korea and Germany generate demand for geospatial network visualization.
- Manufacturing:Shop-floor quality control, supply chain visibility, and predictive maintenance dashboards. Japan's METI-connected industry initiatives and Germany's Industrie 4.0 programs accelerate adoption among automotive and precision equipment producers.
- Education:Student performance tracking, enrollment analytics, and research data publication. University systems in the United States and United Kingdom deploy these for enrollment management and federal reporting compliance.
- Government:Citizen-facing open data portals, internal performance management, and emergency response coordination. India's digital public infrastructure and the United States OPEN Government Data Act create sustained procurement channels.
Financial Services maintains the deepest penetration; Government represents the steepest expansion trajectory as open-data mandates proliferate.
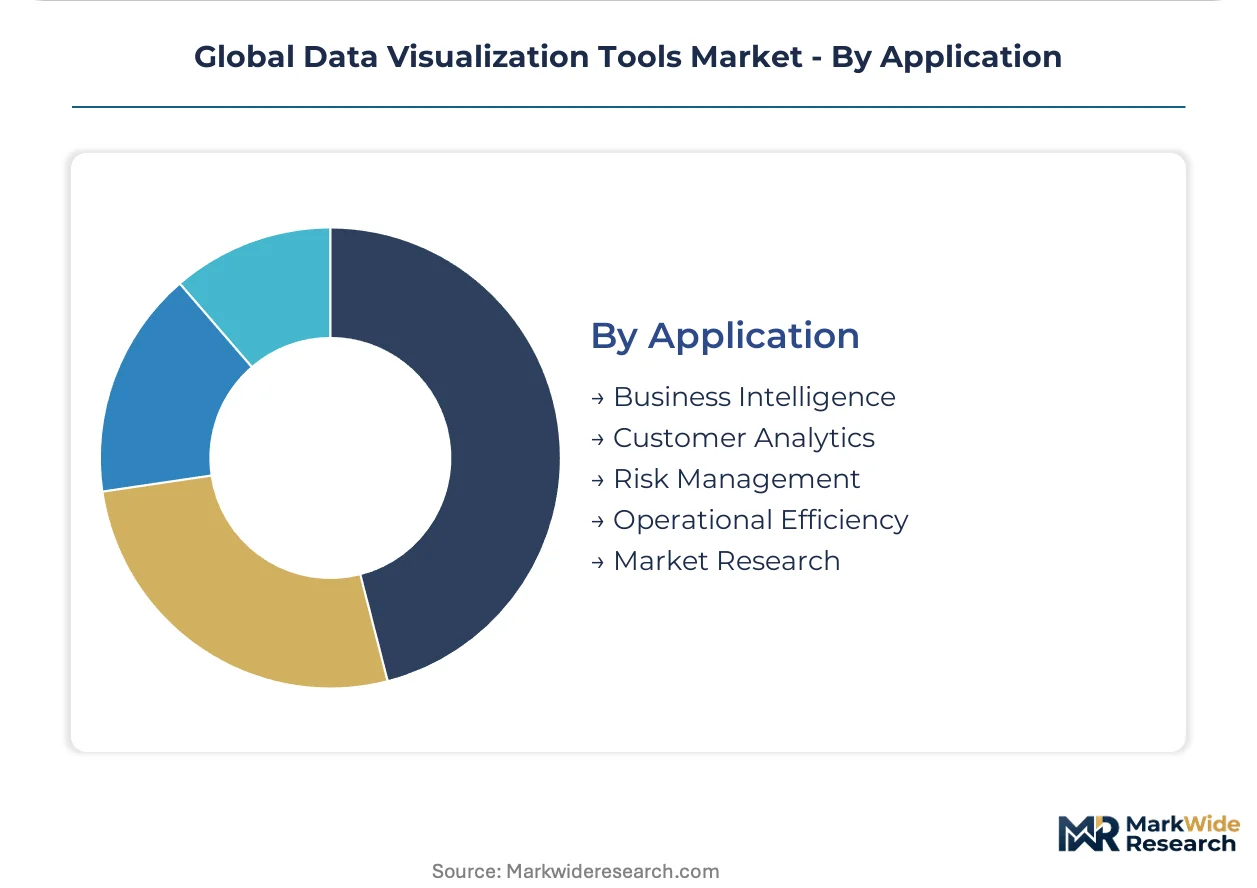
Application:
The business problem being solved shapes integration depth and user licensing models.
- Business Intelligence:Enterprise-wide reporting consolidation from disparate operational systems. C-suite executive teams in the United States and United Kingdom standardize on these platforms for board-level performance reviews.
- Customer Analytics:Segmentation, lifetime value modeling, and behavioral journey mapping. E-commerce operators in China and Brazil prioritize these capabilities for personalization engine feeding.
- Risk Management:Credit, operational, and market risk quantification with regulatory capital implications. Basel III implementation in the European Union and India's RBI guidelines drive specialized visualization requirements.
- Operational Efficiency:Process bottleneck identification, resource utilization optimization, and cost-to-serve analysis. Lean manufacturing practitioners in Japan and Germany embed these into continuous improvement workflows.
- Market Research:Survey data analysis, competitive intelligence synthesis, and trend identification. Consumer packaged goods firms in the United States and France deploy these for brand tracking and concept testing.
Business Intelligence commands the broadest deployment; Customer Analytics gains share fastest as first-party data strategies intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the most concentrated cluster of data visualization development, hosting headquarters for multiple platform vendors and the densest concentration of enterprise BI procurement teams in North America.
United States
Financial services firms in Manhattan and Chicago deploy streaming dashboards for real-time risk monitoring under SEC disclosure modernization rules. The OPEN Government Data Act mandates machine-readable federal datasets, creating sustained procurement pull for citizen-facing visualization portals. Silicon Valley technology vendors and Fortune 500 headquarters in Seattle and Boston drive enterprise adoption of cloud-native platforms.
Germany
Automotive manufacturers in Stuttgart and Munich implement hybrid deployment models balancing GDPR compliance with global operational visibility. The EU AI Act's risk-based classification system mandates explainable visualization layers for algorithmic decision-making. Industrie 4.0 initiatives across Baden-Württemberg accelerate demand for factory-floor dashboards integrating IoT sensor streams.
India
Fintech operators in Mumbai and Bangalore leverage the Account Aggregator framework to render real-time payment flows and credit analytics. RBI guidelines on data localization shape vendor selection for NBFC risk management applications. The UPI data ecosystem creates specialized demand for visualization tools processing high-velocity transaction streams.
Japan
Manufacturing operations teams in Toyota City and Osaka deploy sub-second refresh dashboards for production line anomaly detection. METI-connected industry initiatives standardize data exchange protocols across automotive and precision equipment supply chains. Kanto region technology integrators specialize in edge-computing convergence for shop-floor visualization.
United Kingdom
London-based financial institutions embed BI into trading floor workflows for counterparty exposure tracking under ECB stress testing alignment. The Financial Conduct Authority's operational resilience requirements drive investment in real-time monitoring infrastructure. Edinburgh and Manchester technology hubs develop specialized capabilities for regulatory reporting visualization.
Global Data Visualization Tools Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and rendering sophistication, creating a tiered structure where ecosystem bundling determines pricing power. The vendor base consolidates around three strategic archetypes: cloud-native challengers with consumption-based metering, incumbent enterprise suites with deep legacy system connectors, and embedded analytics specialists targeting product teams. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into data pipeline infrastructure.
Within the enterprise suite tier, Tableau Software and Microsoft Corporation occupy positions defined by ecosystem leverage rather than standalone product differentiation. Salesforce's acquisition integration creates captive distribution for Tableau's advanced geospatial capabilities, while Azure's infrastructure backbone enables Microsoft's aggressive bundling of Power BI at price points that reshape mid-market procurement patterns. QlikTech International AB anchors the associative engine specialization, representing an architectural alternative for enterprises prioritizing query latency reduction over visualization polish.
| Leading Market Players |
|---|
| Tableau Software |
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| QlikTech International AB |
| Alteryx Inc. |
| Domo Inc. |
| Sisense Ltd. |
| TIBCO Software Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into cloud infrastructure anchors both supply resilience and pricing power for enterprise visualization vendors. Salesforce's captive control over Tableau's distribution layer and Microsoft's in-house Azure backbone demonstrate how upstream ownership of compute resources insulates margin structures from third-party hosting volatility.
Pricing Analysis
Value-based pricing anchored to dashboard consumption throughput dominates the Global Data Visualization Tools Market. Three-tier pricing structure across premium, standard, and economy levels separates enterprise geospatial suites from mid-market self-service tools and lightweight embedded modules. Price differentiation rests on ISO 27001 certification tier and integration depth with hyperscaler ecosystems. Cost compression in the mid-market tier is intensifying because Microsoft's aggressive Azure bundling reshapes procurement benchmarks. Small professional services firms in India and Brazil exhibit highest price sensitivity; defense contractors in Switzerland and regulated banks in Germany demonstrate lowest sensitivity due to compliance-driven vendor lock-in.
Supply Chain Analysis
Regional distribution centers in the United States, Ireland, and Singapore orchestrate hub-and-spoke delivery of visualization software licenses and cloud compute capacity. Development gravity centers on the San Francisco Bay Area, Bangalore, and Berlin, with engineering talent pools feeding platform R&D. Raw material dependencies include open-source rendering libraries, proprietary GPU acceleration frameworks, and API connector ecosystems. Single-source vulnerability concentrates in hyperscaler infrastructure partnerships where AWS, Azure, or GCP exclusivity clauses constrain multi-cloud portability. Distribution runs through direct enterprise sales teams, product-led growth channels, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Data Visualization Tools Market is becoming a vertical-integration race. Vendors are pursuing captive control over data pipeline infrastructure to differentiate beyond visualization rendering layers.
For Market Incumbents: Anchor ecosystem stickiness through deeper Salesforce CRM integration and Azure Active Directory embedding. Tableau should accelerate geospatial module development to defend against emerging cloud-native challengers with consumption-based metering. Microsoft must extend Power BI's on-premises connector library to counter QlikTech's associative engine latency advantage in legacy system environments. For New Entrants and Emerging Players: The premium-to-economy price-point gap in India's fintech visualization segment offers white-space entry. Target NBFC risk management applications underserved by ISO 27001-certified incumbents. Product-led growth through UPI data stream templates provides a low-friction go-to-market angle against enterprise sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition archetypes seeking vertical data stack completion. Long-term viability favors vendors with hybrid deployment architectures addressing EU AI Act explainability mandates. The signal to watch is ISO 27001 auditor backlog duration as a proxy for enterprise sales cycle extension.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Salesforce CRM embedding creates captive distribution for Tableau's geospatial capabilities. |
| Geographic Expansion | India's Account Aggregator framework opens real-time payment visualization demand for fintech operators. |
| Acquisition of Specialist Firm | Hyperscalers target edge-computing visualization engines for factory-floor IoT convergence. |
| Product Launch | EU AI Act-compliant explainable AI modules address German and French regulatory enforcement. |
| Strategic Partnership | Azure bundling agreements reshape mid-market procurement patterns through infrastructure leverage. |
Research Methodology
Independent corroboration across CTO interviews, IT procurement officer surveys, and platform engineer discussions underwrites the qualitative findings. Primary fieldwork engaged data science team leads, BI directors at financial services firms, and integration specialists at systems integrators. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory impact assessments. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate cloud software spending produced convergent estimates.
Rate-of-change decomposition across deployment architecture, organization size, vertical industry, and integration complexity segments structured the forecast framework. CAGRs were derived from segment-level growth rate reconciliation against macro technology spending trajectories. Inputs included real-time processing latency benchmarks, open-data mandate implementation timelines, and cross-border data localization enforcement patterns.
Inputs from regulatory filings and vendor disclosure documents were available through the study window; gaps in private fintech adoption metrics introduce uncertainty bands around India's trajectory. Forecasts reflect documented assumptions regarding EU AI Act implementation pacing and hyperscaler pricing discipline. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Behavior Analytics Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Global Social Intelligence Market
Analytics
Big Data Analytics Market
Analytics
Data Analysis Tools Market
Analytics
AI Performance Marketing Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Multi-Touch Attribution Market
Analytics
Edge Analytics Market
Analytics
Service Analytics Market
Analytics
Patent Analytics Services Market
Analytics
Legal Analytics Market
Analytics
Israel ICT Market
Analytics
Condition Monitoring Service Market