
 United Kingdom Geospatial Imagery Analytics Market | 2026-2036
United Kingdom Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Geospatial Imagery Analytics Market Insights
Project finance structures for satellite constellation deployment are reshaping competitive entry barriers in the United Kingdom geospatial sector. Esri leverages its established ArcGIS platform to anchor enterprise accounts across British utilities and transport networks. Planet Labs PBC sustains rapid revisit capabilities through its Dove and SkySat fleets, while Maxar Technologies dominates high-resolution defense and intelligence contracts with the UK Ministry of Defence.
Geospatial imagery analytics encompasses the extraction of actionable intelligence from remotely sensed visual data through spectral analysis, orthorectification, and machine learning classification algorithms, primarily serving spatial decision-making in government, commercial, and environmental domains. Satellite imagery leads product type revenue due to persistent coverage of British territorial waters and rural estates, while drone imagery represents the fastest-growing segment as Civil Aviation Authority regulations mature beyond visual line-of-sight frameworks. Cloud computing within the technology dimension now captures expanding margin pools as Ministry of Defence and Environment Agency clients migrate processing workloads from on-premise servers to distributed architectures.
The UK Space Agency's National Space Strategy and the Civil Aviation Authority's evolving unmanned aircraft system frameworks jointly determine market access conditions for imagery collection and analytics service providers. Ordnance Survey's geospatial data standards and the Environment Agency's flood risk mapping mandates shape product specifications and procurement criteria across public-sector contracts. Stakeholders must monitor forthcoming statutory instruments on satellite data sovereignty and aerial surveillance privacy as these will redefine competitive positioning and customer addressability across British markets.
Market Dynamics
The UK Space Agency's National Space Strategy is compressing procurement cycles for geospatial services across British public-sector bodies, forcing legacy vendors to restructure delivery models around cloud-native architectures and satellite-tasking APIs.
Growth Catalysts
- Environment Agency flood mapping mandates:Statutory requirements for high-resolution terrain modeling accelerate satellite imagery procurement across local authorities in England and Wales.
- London insurance sector:Property risk modeling teams within Lloyd's syndicates now embed orbital analytics into catastrophe bond pricing and reinsurance layering decisions.
- Cloud-native processing architectures:Distributed computing platforms enable real-time orthorectification and machine learning classification at scales impossible with on-premise server farms.
Market Restraints
- Launch cost volatility:Access to low-Earth orbit rideshare slots remains concentrated with a handful of commercial launch providers, creating input cost uncertainty for constellation operators.
- Civil Aviation Authority BVLOS delays:Regulatory friction around beyond-visual-line-of-sight drone operations constrains aerial imagery collection in congested airspace corridors.
- High-resolution defense contracting concentration:Ministry of Defence imagery requirements flow predominantly to established defense primes, limiting addressable market for commercial entrants.
Strategic Opportunities
- Scottish offshore wind expansion:Crown Estate Scotland leasing rounds create demand for seabed surveying and construction-phase monitoring using synthetic aperture radar.
- Ordnance Survey data standards convergence:National mapping frameworks now mandate interoperable geospatial formats, opening procurement to analytics platforms with API-first architectures.
- AI-driven change detection:Convolutional neural networks trained on British land use patterns enable automated identification of unauthorized development for planning enforcement teams.
Industry Challenges
- Spectral imaging expertise scarcity:Shortages of data scientists capable of interpreting hyperspectral signatures for agricultural and mineralogical applications constrain service expansion.
- Legacy GIS integration complexity:Enterprise clients maintain decades of ArcGIS layer dependencies, complicating migration to cloud-native analytics pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Geospatial Imagery Analytics Market |
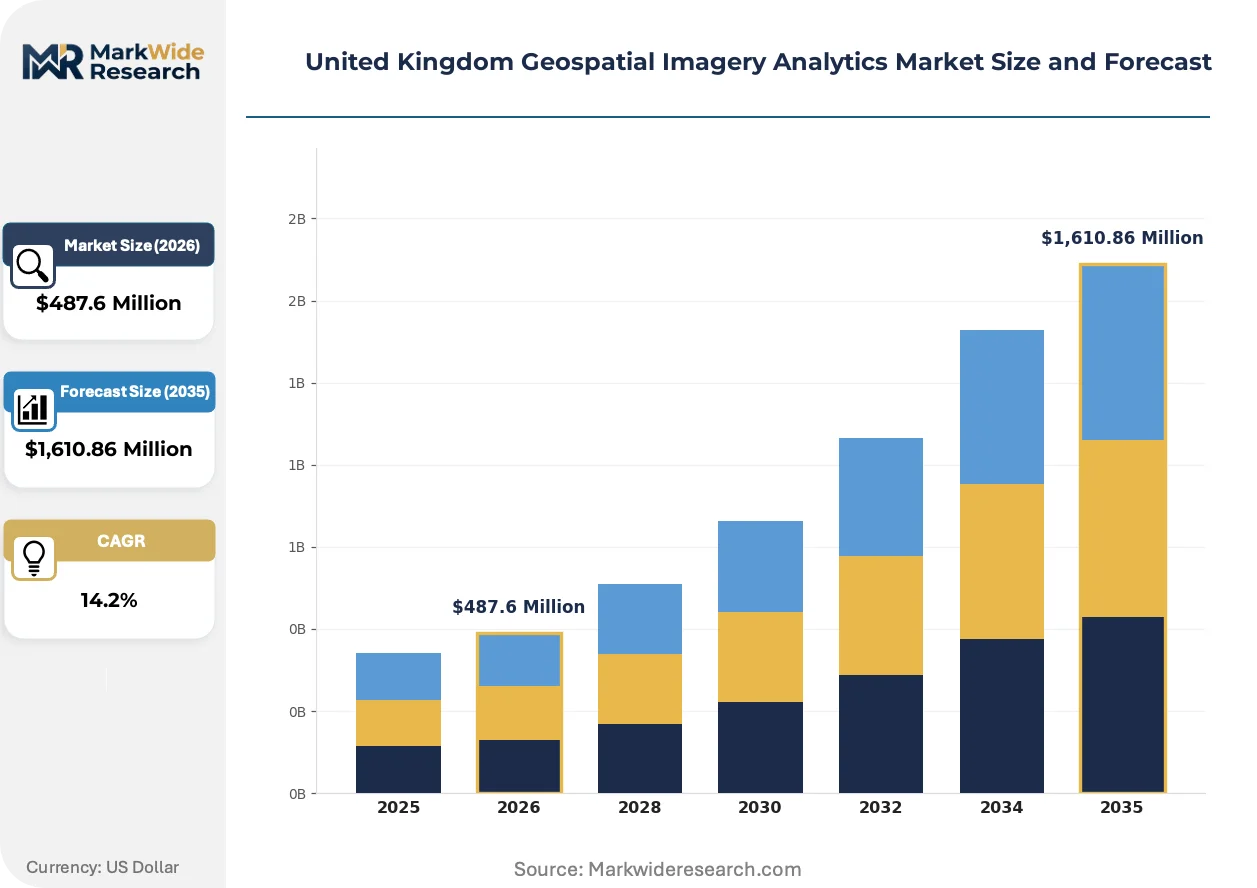
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Imagery, Aerial Imagery, Drone Imagery, Ground-Based Imagery Technology: Remote Sensing, GIS, Image Processing, Cloud Computing End User: Agriculture, Urban Planning, Environmental Management, Defense Application: Disaster Response, Land Use Analysis, Infrastructure Monitoring, Climate Research |
| Companies Covered | Maxar Technologies, Esri, Hexagon AB, Planet Labs PBC, Airbus Defence and Space, Trimble Inc., Bentley Systems, Google, IQGeo Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Geospatial Imagery Analytics Market Trends and Innovations
Orbital analytics capabilities are fragmenting across specialized sensor constellations and edge-computing architectures, dissolving the monopoly of single-vendor geospatial platforms in British enterprise accounts.
Synthetic aperture radar is migrating from defense-exclusive applications to commercial infrastructure monitoring. Network Rail and National Highways now deploy SAR-based ground motion detection for embankment stability assessment. This technology is migrating from classified military specifications to subscription-based civil engineering services, compressing delivery timelines from weeks to hours.
The UK Space Agency's regulatory sandbox for satellite operators is accelerating licensing timelines for novel Earth observation constellations. British startups now access streamlined frequency coordination and orbital slot allocation. Small satellite manufacturers in Oxfordshire and Glasgow clusters are exploiting this tailwind to secure anchor tenancy on upcoming rideshare missions.
Utility procurement teams now unbundle imagery acquisition from analytics processing, contracting directly with constellation operators for raw data feeds. This disintermediation fragments the traditional prime contractor model. Water companies in the Thames and Anglian regions lead this pattern, establishing direct satellite tasking relationships for leakage detection and drought monitoring.
United Kingdom Geospatial Imagery Analytics Market Segmentation
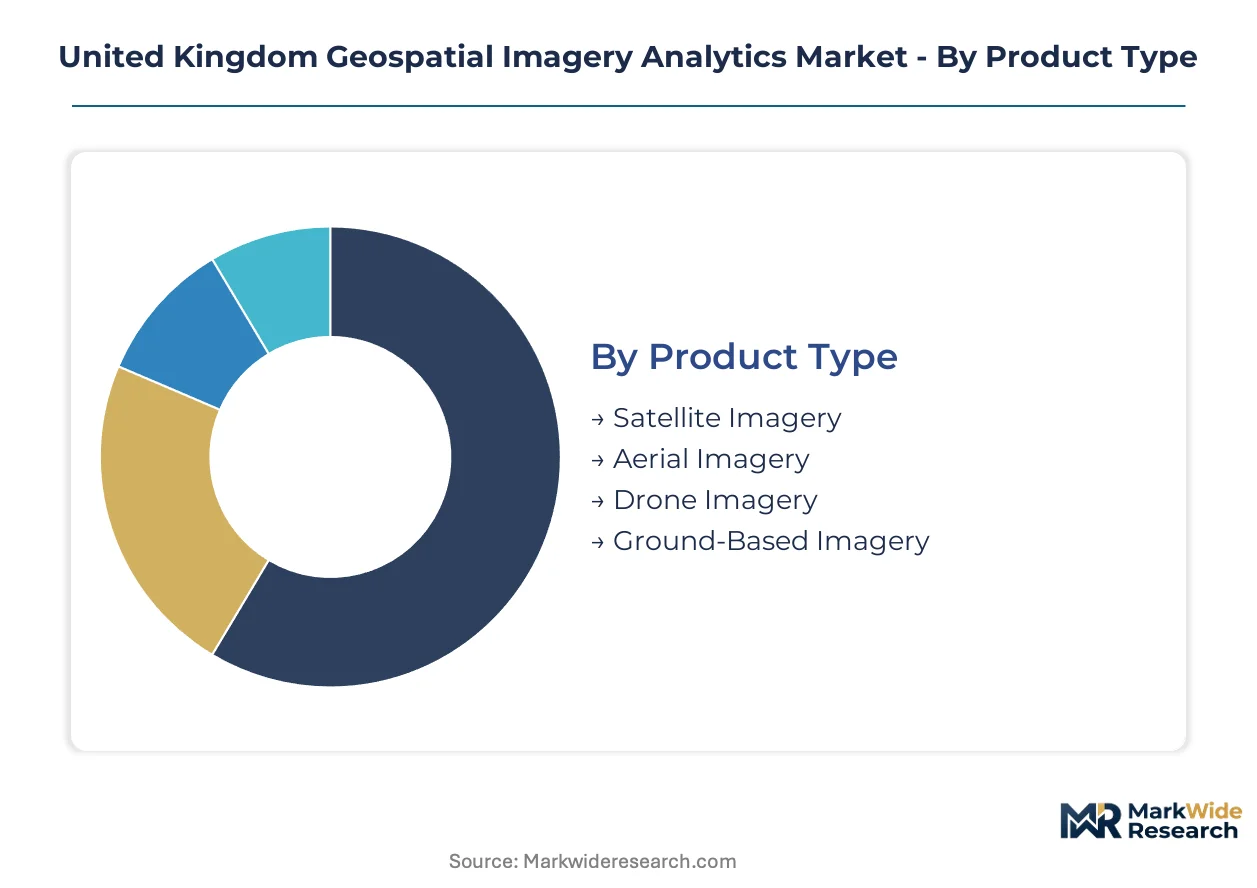
Geospatial imagery analytics in the United Kingdom fragments across collection platforms, processing architectures, and sector-specific use cases. Understanding these divisions reveals where procurement budgets concentrate and which technologies are displacing legacy workflows.
Product Type:
Collection platforms differ in altitude, revisit frequency, and regulatory burden, creating distinct cost-to-resolution trade-offs for British buyers.
- Satellite Imagery:Orbital platforms deliver persistent coverage of British territorial waters and rural estates through multispectral and synthetic aperture radar sensors. The Environment Agency mandates high-resolution terrain modeling for flood risk assessment across England and Wales, anchoring public-sector demand for taskable satellite constellations.
- Drone Imagery:Unmanned aerial systems capture centimeter-scale resolution for construction progress monitoring and precision agriculture. Civil Aviation Authority beyond-visual-line-of-sight frameworks are maturing, though regulatory friction in congested airspace corridors around London and Birmingham constrains rapid scaling.
- Aerial Imagery:Manned aircraft platforms bridge the gap between satellite coverage and drone precision, serving Ordnance Survey national mapping contracts.
- Ground-Based Imagery:Terrestrial photogrammetry and LiDAR systems support infrastructure asset inspection at the network edge.
Satellite imagery holds installed capacity. Drone imagery is rotating up the share rankings.
Technology:
Processing architectures determine whether analytics pipelines run on legacy on-premise servers or distributed cloud environments.
- Cloud Computing:Distributed architectures enable real-time orthorectification and machine learning classification at scales impossible with server farms. Ministry of Defence and Environment Agency clients are migrating processing workloads, expanding margin pools for platform providers.
- Remote Sensing:Spectral analysis of reflected electromagnetic radiation underpins agricultural health monitoring and mineralogical surveys. Shortages of data scientists capable of interpreting hyperspectral signatures constrain service expansion in British markets.
- GIS:Spatial data management systems anchor enterprise accounts across utilities and transport networks, though decades of ArcGIS layer dependencies complicate cloud-native migration.
- Image Processing:Algorithmic pipelines for orthorectification, mosaicking, and feature extraction convert raw sensor data into actionable intelligence.
GIS holds installed capacity. Cloud computing is climbing the fastest.
End User:
Sector-specific procurement patterns reflect divergent resolution requirements and regulatory compliance burdens.
- Defense:Ministry of Defence imagery requirements concentrate on high-resolution tasking for intelligence and situational awareness. Contracts flow predominantly to established defense primes, limiting addressable market for commercial entrants.
- Urban Planning:Local authorities in England and Wales deploy satellite-based land use analytics for densification projects and unauthorized development detection. Convolutional neural networks trained on British land use patterns automate planning enforcement workflows.
- Agriculture:Precision farming operations leverage spectral indices for crop health monitoring and yield prediction across East Anglia and the Scottish Borders.
- Environmental Management:Statutory flood mapping mandates and seabed surveying for offshore wind leasing drive procurement from the Environment Agency and Crown Estate Scotland.
Defense holds installed capacity. Urban planning is rotating up the share rankings.
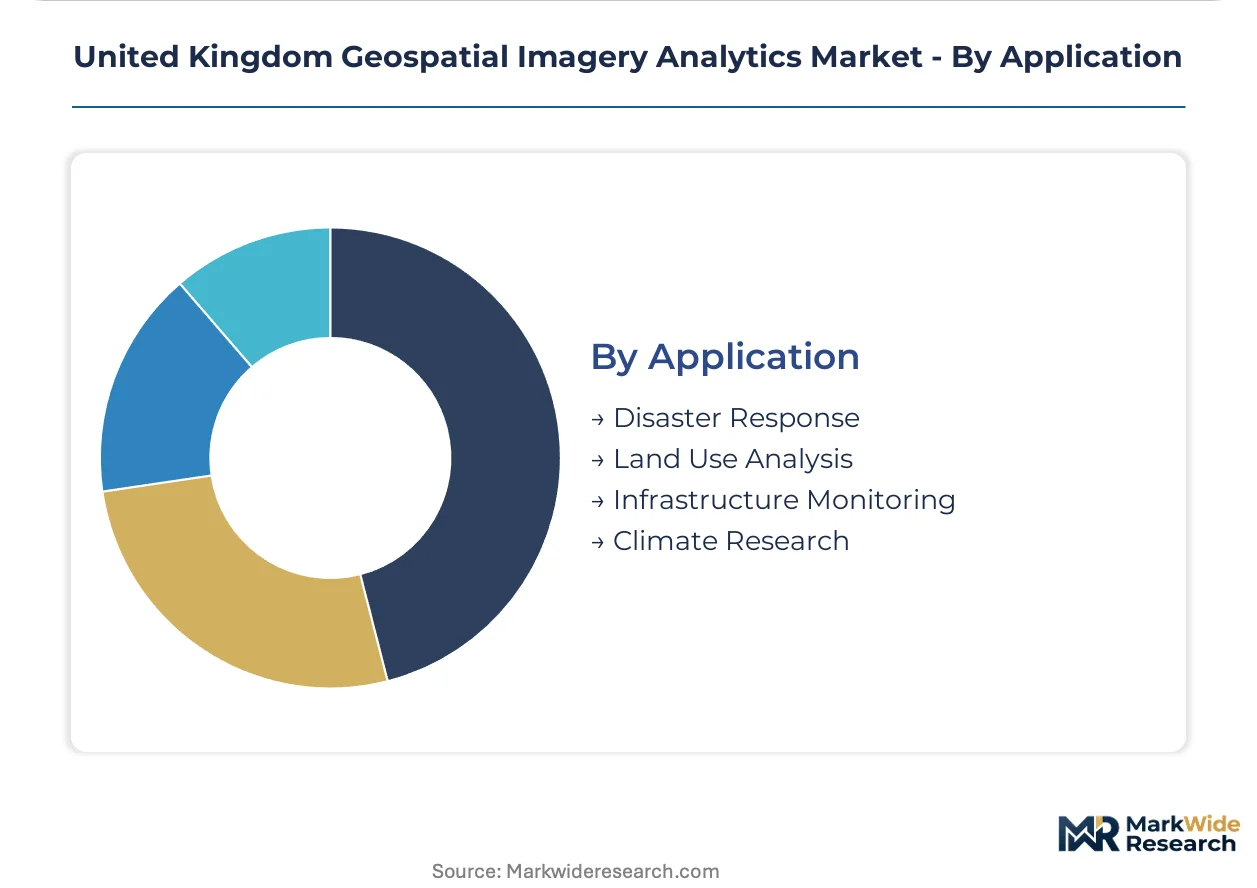
Application:
Use case differentiation determines sensor selection, revisit frequency, and analytical complexity.
- Land Use Analysis:Classification of urban, agricultural, and natural surfaces supports planning decisions and compliance monitoring. London financial and insurance sectors embed orbital analytics into property risk modeling and catastrophe bond pricing.
- Infrastructure Monitoring:Synthetic aperture radar ground motion detection now serves Network Rail and National Highways for embankment stability assessment, compressing delivery timelines from weeks to hours.
- Disaster Response:Rapid damage assessment following flooding or coastal erosion requires taskable satellite constellations with sub-24-hour revisit capabilities.
- Climate Research:Long-term vegetation and cryosphere monitoring supports academic and government research programs tracking environmental change across British territories.
Land use analysis holds installed capacity. Infrastructure monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scottish offshore wind leasing rounds command pricing premiums for seabed surveying contracts, while Welsh local authorities operate under tighter procurement constraints for flood risk mapping services.
London and the Southeast
Lloyd's syndicates embed orbital analytics into catastrophe bond pricing and reinsurance layering decisions. The UK Space Agency's National Space Strategy accelerates public-sector procurement of geospatial services across Whitehall departments. Tech clusters in Oxfordshire and Cambridge supply machine learning classification algorithms to Environment Agency contractors.
Midlands
Network Rail and National Highways deploy SAR-based ground motion detection for embankment stability assessment across the West Coast Main Line corridor. Ordnance Survey national mapping contracts mandate interoperable geospatial formats that open procurement to API-first analytics platforms. Birmingham's transport authority trials satellite-based land use analytics for urban densification projects.
North England
Water companies in the Thames and Anglian regions establish direct satellite tasking relationships for leakage detection and drought monitoring. Local authorities in Manchester and Leeds deploy convolutional neural networks for automated identification of unauthorized development. The Northern Powerhouse agenda channels infrastructure investment toward geospatial-enabled asset management systems.
Scotland
Crown Estate Scotland leasing rounds create concentrated demand for synthetic aperture radar seabed surveying and construction-phase monitoring. Edinburgh and Glasgow clusters of small satellite manufacturers exploit streamlined frequency coordination from the UK Space Agency's regulatory sandbox. Scottish Water migrates processing workloads from on-premise servers to distributed cloud architectures for catchment management.
Wales
Local authorities across England and Wales deploy satellite-based land use analytics, though Welsh procurement operates under devolved budgetary frameworks. The Environment Agency's flood risk mapping mandates drive high-resolution terrain modeling requirements in the Severn and Wye catchments. Cardiff's emerging space sector focuses on Earth observation data processing rather than constellation ownership.
United Kingdom Geospatial Imagery Analytics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the imagery collection layer. The vendor base organizes around three strategic archetypes: defense primes with classified contracting relationships, cloud-native analytics platforms with API-first architectures, and satellite constellation operators with rapid revisit capabilities. Competitive moves concentrate on vertical integration into data processing pipelines and strategic partnerships with public-sector procurement frameworks.
Within the defense prime tier, Maxar Technologies and Airbus Defence and Space occupy positions shaped by Ministry of Defence imagery requirements and high-resolution tasking specifications. Planet Labs PBC exemplifies the constellation operator archetype with its Dove and SkySat fleets, while Esri anchors the platform integrator segment through established ArcGIS deployments across British utilities and transport networks. These three companies represent the dominant competitive positioning vectors in the United Kingdom geospatial imagery analytics market.
| Leading Market Players |
|---|
| Maxar Technologies |
| Esri |
| Hexagon AB |
| Planet Labs PBC |
| Airbus Defence and Space |
| Trimble Inc. |
| Bentley Systems |
| IQGeo Group |
| Others |
Pricing and Supply Chain Analysis
Harwich International Port freight corridors connecting Oxfordshire satellite manufacturing clusters to Scottish offshore wind survey sites concentrate logistics cost dynamics, compressing margins for constellation operators while amplifying price differentiation between defense-grade tasking and commercial subscription tiers.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure blending subscription SaaS tiers for analytics platforms with per-task transactional fees for satellite imagery collection. Pricing stratifies across premium, standard, and economy tiers based on resolution grade and UK Space Agency licensing certification. Cost compression in commercial satellite tasking is intensifying because rideshare launch slot scarcity concentrates upstream supplier power. Local authorities in England and Wales exhibit highest price sensitivity due to devolved budgetary constraints, while Ministry of Defence contracts demonstrate lowest sensitivity given mission-critical specifications.
Supply Chain Analysis
Extended payment terms from prime contractors to small satellite manufacturers in Glasgow and Oxfordshire clusters now stretch 90-120 days, straining working capital for component suppliers. Manufacturing draws from US sensor payloads, German precision optics, and British software-defined radio systems. Single-source vulnerability concentrates in synthetic aperture radar antenna supply from a limited qualified vendor base. Distribution runs through direct satellite tasking APIs for enterprise accounts and systems integrator partnerships for public-sector frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom geospatial imagery analytics market tracks a cyclical recovery pattern as Crown Estate Scotland offshore wind leasing rounds reactivate capital deployment paused during regulatory uncertainty periods.
For Market Incumbents: Entrench cloud-native platform architectures through backward integration into edge-computing infrastructure, countering the threat of disintermediation by constellation operators establishing direct API relationships with utility buyers. Prioritize certification investment against Ordnance Survey data standards to lock in procurement framework eligibility. For New Entrants and Emerging Players: Build out specialized synthetic aperture radar analytics capabilities targeting Network Rail and National Highways infrastructure monitoring contracts, the most penetrable segment given SAR's migration from defense-exclusive applications. Pursue a channel partnership go-to-market angle through established civil engineering consultancies with existing public-sector relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-first analytics platforms with demonstrated Environment Agency contract execution over capital-intensive constellation ownership. Long-term viability hinges on recurring revenue depth rather than one-off project margins. Monitor Civil Aviation Authority beyond-visual-line-of-sight regulatory finalization as the signal indicating drone imagery segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Environment Agency and Ministry of Defence procurement now mandates distributed processing architectures over legacy server farms. |
| Synthetic Aperture Radar Capability Buildout | Network Rail and National Highways contracts require ground motion detection compressing delivery timelines from weeks to hours. |
| API-First Architecture Development | Ordnance Survey data standards convergence opens procurement to analytics platforms with interoperable geospatial formats. |
| Direct Satellite Tasking Relationships | Thames and Anglian water companies now unbundle imagery acquisition from analytics processing, fragmenting prime contractor models. |
| AI-Driven Change Detection Investment | Convolutional neural networks trained on British land use patterns automate unauthorized development identification for planning enforcement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with satellite constellation operators, analytics platform engineers, Environment Agency procurement officers, and civil aviation regulators; and secondary validation through UK Space Agency licensing disclosures, Crown Estate Scotland leasing round documentation, Ordnance Survey framework agreements, and Civil Aviation Authority regulatory consultation responses. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Forecast inputs considered platform deployment models, resolution tiers, end-use verticals, and regional procurement frameworks across the analysis window. CAGRs derived from segment-level growth trajectory modeling incorporating satellite launch cadence projections and regulatory sandbox expansion timelines. Industry-specific inputs included synthetic aperture radar commercialization curves and cloud migration velocity among British utilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers entering geospatial analytics would shift outcomes. Macroeconomic contraction affecting Lloyd's syndicate catastrophe bond issuance, statutory instrument delays on satellite data sovereignty, or breakthroughs in drone beyond-visual-line-of-sight automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Marketing Analytics Software Market
Analytics
Text Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
North America Location Analytics Market
Analytics
US Video Analytics Market
Analytics
Embedded Business Intelligence Market
Analytics
Process Analytics Market
Analytics
Customer Data Platform Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Global Sales Performance Management Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Investigative Analytics Market
Analytics
Global in-Memory Analytics Market
Analytics
Global Subscription Analytics Software Market
Analytics
BI and Analytics Market