
 North America Superplasticizers Market | 2026-2036
North America Superplasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Superplasticizers Market Analytics
High-range water-reducing specification tiers is bifurcating the competitive landscape across North America. Sika AG leverages its integrated supply chain from raw monomers to finished admixtures, sustaining cost advantages in polycarboxylate formulations. BASF SE anchors its position through R&D intensity in tailored molecular architectures for extreme weather concrete.
Superplasticizers are synthetic polymer admixtures, primarily polycarboxylate ethers, naphthalene sulfonates, and melamine formaldehydes, that disperse cement particles to achieve fluid concrete at low water-to-cement ratios without sacrificing compressive strength. Polycarboxylate dominates product type segments due to superior slump retention and compatibility with supplementary cementitious materials, while lignosulfonate occupies cost-sensitive mortar applications where performance thresholds are lower. Infrastructure leads end user segments driven by bridge deck and tunnel lining specifications, though residential competes through self-leveling underlayment demand in multifamily construction.
The U.S. EPA oversees volatile organic compound limits in admixture manufacturing, while ASTM C494 governs chemical requirements and performance benchmarks for Type F and Type G superplasticizers in North American projects. Canada's CSA A23.1 standards parallel these specifications, creating cross-border product uniformity that simplifies supplier certification. Stakeholders must monitor evolving low-carbon procurement mandates from state departments of transportation, as these will increasingly dictate admissible chemistries and embodied carbon thresholds in public infrastructure bids.
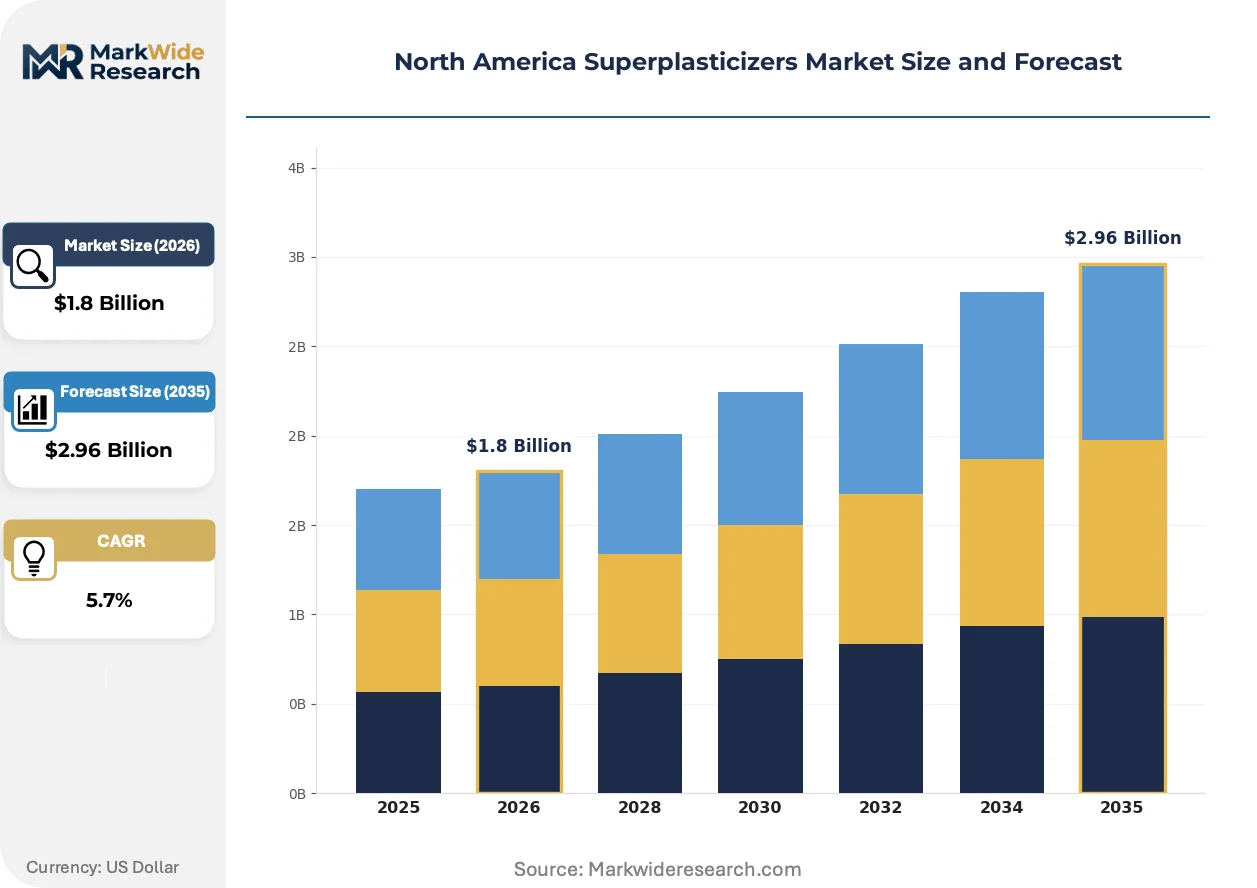
Market Dynamics
The U.S. Environmental Protection Agency's tightening embodied carbon thresholds for federally funded infrastructure are forcing concrete producers to reformulate admixture specifications, compressing the viable chemistry set for superplasticizer suppliers.
Growth Catalysts
- Buy America provisions:Domestic content requirements in the Infrastructure Investment and Jobs Act are steering DOT procurement toward U.S.-manufactured polycarboxylate ethers, reinforcing local production capacity.
- CSA A23.1 alignment:Canadian provincial transportation agencies harmonizing with U.S. ASTM C494 standards are eliminating cross-border certification friction for admixture suppliers.
- Self-consolidating concrete:Dense rebar configurations in seismic-resistant bridge columns are mandating high-slump retention chemistries that only next-generation polycarboxylates deliver.
Market Restraints
- Propylene oxide volatility:Polycarboxylate backbone synthesis depends on petrochemical feedstocks concentrated along the Texas Gulf Coast, exposing margins to hurricane-season supply disruptions.
- Technical ceiling in cold climates:Extended slump retention below 5°C remains chemically unresolved, limiting year-round specification in Canadian prairie provinces and northern U.S. tier.
- Low-carbon binder incompatibility:High-volume fly ash and slag blends react unpredictably with conventional superplasticizer charge densities, requiring costly reformulation cycles.
Strategic Opportunities
- Mexican infrastructure pipeline:Pemex refinery upgrades and Tren Maya rail segments are creating first-mover openings for admixture suppliers with established U.S. Gulf distribution networks.
- Carbon capture utilization:CO2-cured concrete systems emerging from Canadian cleantech clusters demand superplasticizers compatible with accelerated carbonation curing protocols.
- Performance-based DOT contracting:State transportation departments in California and New York are piloting durability-guarantee procurement models that reward admixture suppliers for lifecycle performance.
Industry Challenges
- Polymer synthesis talent scarcity:Specialized organic chemists capable of tailoring polycarboxylate side-chain architectures command premium compensation, constraining R&D velocity at mid-tier suppliers.
- ASTM C494 Type G certification timelines:Extended slump retention validation requires 14-day field trials, stretching product launch cycles and freezing formulation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Superplasticizers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylate, Naphthalene, Melamine, Lignosulfonate Application: Concrete Mixtures, Mortar, Grouting, Self-Leveling End User: Residential, Commercial, Infrastructure, Industrial Distribution Channel: Direct Sales, Online, Retail, Distributors |
| Companies Covered | Sika AG, BASF SE, Arkema, GCP Applied Technologies Inc., Mapei SpA, MBCC Group, Kao Corporation, W. R. Grace & Co.-Conn., Fosroc Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Superplasticizers Market Evolving Landscape
Admixture chemistry is pivoting toward molecular precision as infrastructure owners demand predictable performance across extreme weather envelopes and aggressive sustainability targets.
Viscosity-modifying polycarboxylate copolymers with tailored side-chain density are supplanting traditional naphthalene sulfonates in high-performance infrastructure specifications. State DOTs in Florida and Texas are specifying these chemistries for marine exposure zones where sulfate resistance and workability retention must coexist. The shift is compressing the addressable market for legacy melamine formaldehyde formulations to dry-mix mortar applications where cost sensitivity dominates.
The EPA's evolving Greenhouse Gas Reduction Fund criteria are embedding embodied carbon thresholds into federal infrastructure grant requirements. Concrete producers bidding on bridge and tunnel projects must now document cradle-to-gate emissions for all chemical admixtures, favoring suppliers with verified supply chain carbon accounting. Polycarboxylate manufacturers with bio-based feedstock pathways are capturing specification preference in California Caltrans and New York Thruway Authority tenders.
Integrated service contracts bundling admixture supply with onsite rheology testing are displacing transactional chemical sales in megaproject procurement. General contractors on the Hudson River Tunnel and I-5 Columbia River Crossing are requiring admixture partners to embed technical field staff for duration of concrete placement. This model concentrates volume with suppliers capable of deploying specialized labor across multi-year construction timelines, marginalizing regional distributors without technical service depth.
North America Superplasticizers Market Segmentation
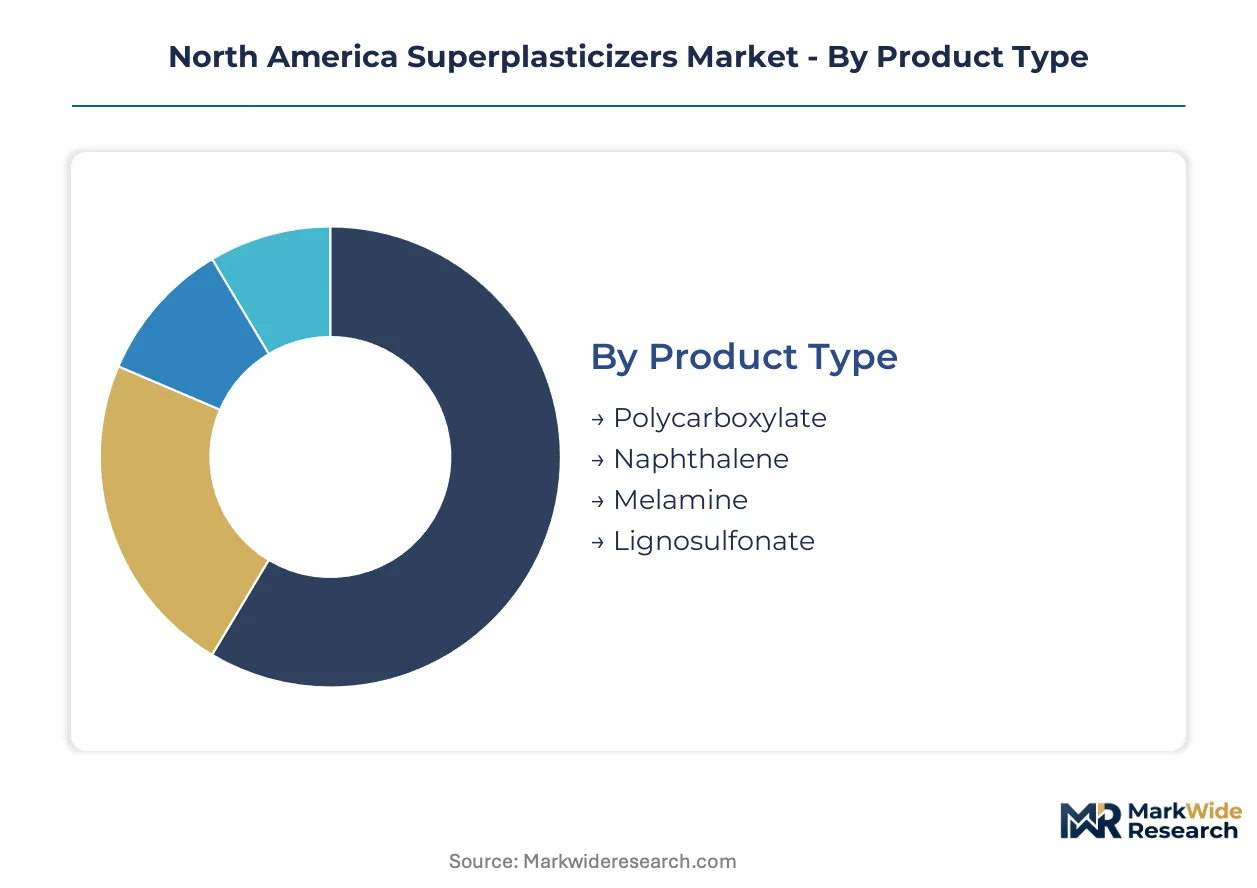
Superplasticizer procurement patterns diverge sharply across formulation chemistry, placement method, and project scale. Specification tiers create distinct margin architectures that suppliers must navigate through targeted technical service deployment.
Product Type:
Substitute pressure intensifies for legacy chemistries as infrastructure owners rewrite performance specifications around sustainability and extreme-weather durability.
- Polycarboxylate:These ether-based polymers deploy comb-shaped molecular architectures with polyethylene glycol side chains that electrosterically disperse cement particles. U.S. Gulf Coast petrochemical corridors supply the propylene oxide feedstocks, though hurricane-season disruptions compress margins unpredictably. Infrastructure megaprojects specify polycarboxylates exclusively for self-consolidating concrete in seismic-resistant bridge columns.
- Naphthalene:Sulfonated condensates deliver cost-effective water reduction but sacrifice slump retention beyond 45 minutes. Demand concentrates in residential flatwork and precast yard operations across the U.S. Sun Belt where rapid placement cycles dominate over extended workability.
- Melamine:Formaldehyde-based chemistry retains niche specification in dry-mix mortar applications where powder stability and storage longevity outweigh performance premiums. Cost-sensitive tile adhesive manufacturers in Mexico specify melamine for retail-channel construction chemicals.
- Lignosulfonate:Derived from wood pulp processing byproducts, these natural polymers occupy the economy tier for non-structural grouting and soil stabilization. Canadian prairie provinces specify lignosulfonates for seasonal road maintenance where freeze-thaw tolerance requirements are minimal.
Polycarboxylate retains volume leadership; lignosulfonate holds the steepest expansion curve as low-carbon binder systems force reformulation trials.
Application:
Cost tier stratification separates premium-specification infrastructure placements from commodity-grade residential applications where admixture spend per cubic yard drops by half.
- Concrete Mixtures:High-range water reducers enable 25-40% cement reduction while maintaining compressive strength targets. Infrastructure specifications in California and New York mandate polycarboxylate admixtures for bridge deck overlays exposed to de-icing salt cycles.
- Mortar:Masonry and rendering applications prioritize air entrainment compatibility over extreme slump retention. U.S. residential construction channels specify mid-range naphthalene formulations for block-laying operations in multifamily developments.
- Grouting:Precision injection applications for tunnel lining and dam rehabilitation demand zero-bleed formulations with controlled viscosity development. Canadian hydroelectric operators specify tailored polycarboxylate-grout hybrids for pressure grouting in fractured rock formations.
- Self-Leveling:Underlayment compounds for commercial flooring require extended open time combined with rapid early strength gain. Texas and Florida commercial contractors drive specification for viscosity-modified polycarboxylates in large-format retail buildouts.
Concrete mixtures dominate value capture; self-leveling compounds gain share fastest through multifamily construction acceleration.
End User:
Customer type determines specification authority—engineer-driven infrastructure projects impose rigorous ASTM C494 validation while residential builders prioritize distributor availability and field technical support.
- Infrastructure:State DOTs and federal agencies mandate Type F and Type G certification with documented slump retention curves. The Infrastructure Investment and Jobs Act channels specification toward domestic-manufactured polycarboxylates through Buy America compliance requirements.
- Commercial:General contractors on design-build projects balance performance guarantees against liquidated damages exposure. High-rise core wall placements in Chicago and Toronto specify extended-set polycarboxylates for 3-hour pumpability windows.
- Residential:Production homebuilders optimize for cost per cubic yard and placement crew productivity. Sun Belt metropolitan areas specify mid-range water reducers for slab-on-grade foundations where finish quality tolerances are forgiving.
- Industrial:Petrochemical and power generation facilities impose sulfate resistance and thermal compatibility requirements. U.S. Gulf Coast refinery expansions specify naphthalene-polycarboxylate blends for massive mat foundations resisting aggressive groundwater exposure.
Infrastructure commands specification premium; residential segments expand most quickly through single-family permitting recovery.
Distribution Channel:
Supply chain configuration separates integrated service models from transactional chemical sales, with megaproject procurement increasingly bundling admixture supply with embedded technical labor.
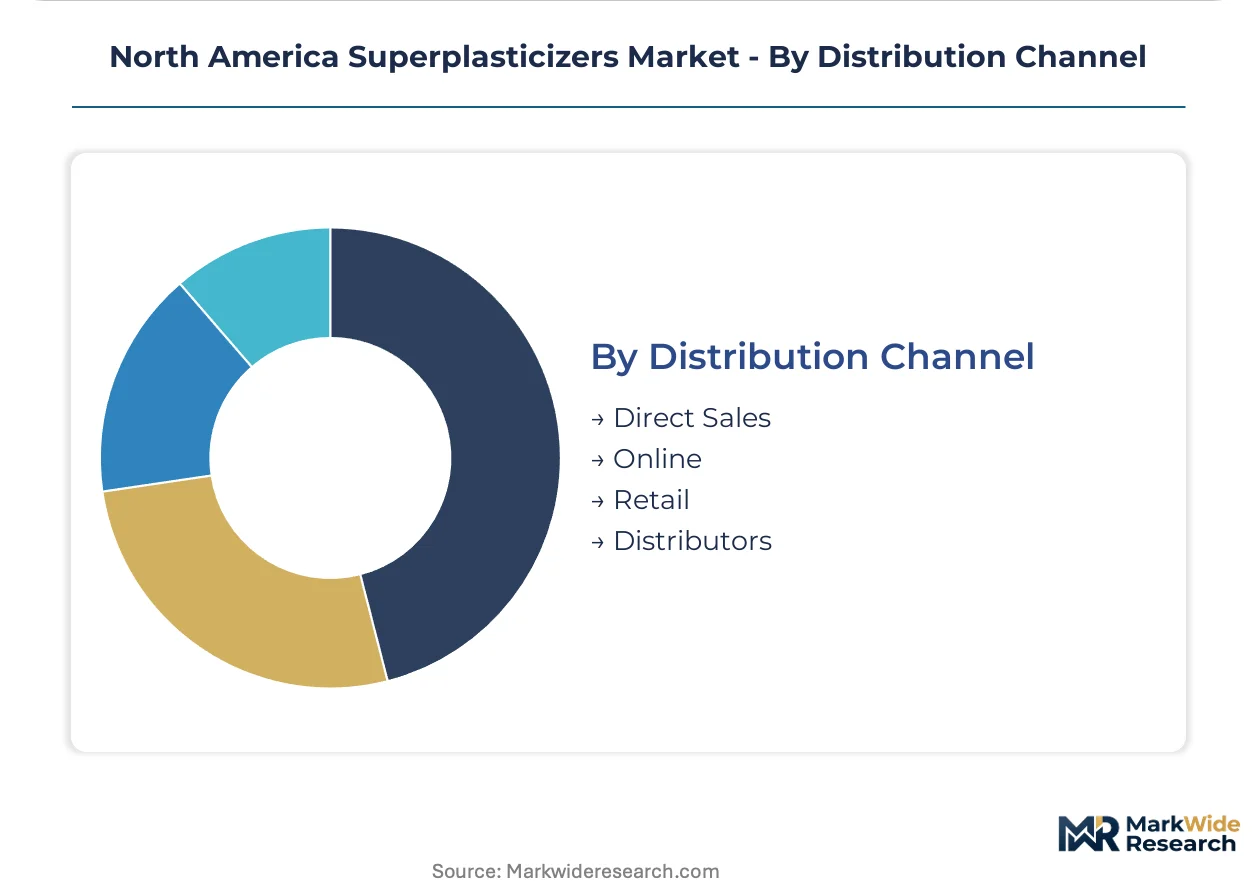
- Direct Sales:Major suppliers deploy field rheologists for multi-year infrastructure commitments. Hudson River Tunnel and I-5 Columbia River Crossing contractors require dedicated admixture technical staff for concrete placement duration.
- Distributors:Regional chemical distributors serve mid-tier ready-mix producers with inventory financing and just-in-time delivery. Texas and California independent ready-mix operators rely on distributor networks for formulation flexibility across multiple project types.
- Retail:Big-box construction supply channels move bagged admixture formulations to contractor direct purchasers. Residential repair and small commercial renovation segments in Florida and Arizona specify retail-channel polycarboxylates for patch and overlay applications.
- Online:Digital procurement platforms emerge for standardized formulations with certified test data. Canadian prairie contractors pilot online specification for remote project sites beyond distributor coverage areas.
Direct sales retain value concentration; online channels climb fastest as procurement digitization penetrates mid-tier construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a modest superplasticizer trade surplus, with U.S. Gulf Coast production capacity exceeding domestic absorption and supplying Mexican infrastructure projects. Canadian demand outstrips local formulation capability, creating import dependence on polycarboxylate ethers from Texas and Louisiana. Cross-border supply chains face friction from divergent carbon-accounting standards rather than tariff barriers.
United States
Infrastructure megaprojects along the I-5 corridor and Hudson River Tunnel drive specification for extended-set polycarboxylates. The EPA's evolving embodied carbon thresholds for federally funded construction are compressing admissible chemistry sets. Houston and Beaumont anchor production capacity, with propylene oxide feedstock availability sustaining integrated manufacturing.
Canada
Hydroelectric rehabilitation and Arctic port expansion create demand for cold-weather-compatible formulations. CSA A23.1 harmonization with ASTM C494 simplifies U.S. supplier certification across provincial transportation agencies. Ontario and Quebec concentrate specification authority, though prairie provinces struggle with slump retention below 5°C.
Mexico
Pemex refinery upgrades and Tren Maya rail segments are opening first-mover positions for suppliers with established U.S. Gulf distribution networks. Mexican federal procurement lacks domestic content mandates, allowing specification of U.S.-manufactured admixtures. Nuevo León and Mexico City Metro concentrate commercial construction activity driving self-leveling underlayment demand.
North America Superplasticizers Market Competitive Landscape
Concentration sits with integrated chemical conglomerates commanding backward integration into petrochemical feedstocks. Three archetypes populate the competitive map: multinational admixture specialists with field service depth, diversified construction chemical divisions of industrial majors, and regional distributors lacking technical capabilities. Capacity expansion along the Texas Gulf Coast and strategic partnerships for bio-based feedstock sourcing represent the dominant competitive vectors.
Within the integrated multinational tier, Sika AG and BASF SE exemplify archetypes of technical-service-intensive positioning, while Arkema represents specialty chemical lineage applied to tailored molecular architectures. These three entities anchor the premium specification segment where DOT certification and embedded technical labor determine competitive outcomes.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Arkema |
| GCP Applied Technologies Inc. |
| Mapei SpA |
| MBCC Group |
| Kao Corporation |
| W. R. Grace & Co.-Conn. |
| Fosroc Inc. |
| Others |
Value Network & Pricing Analysis
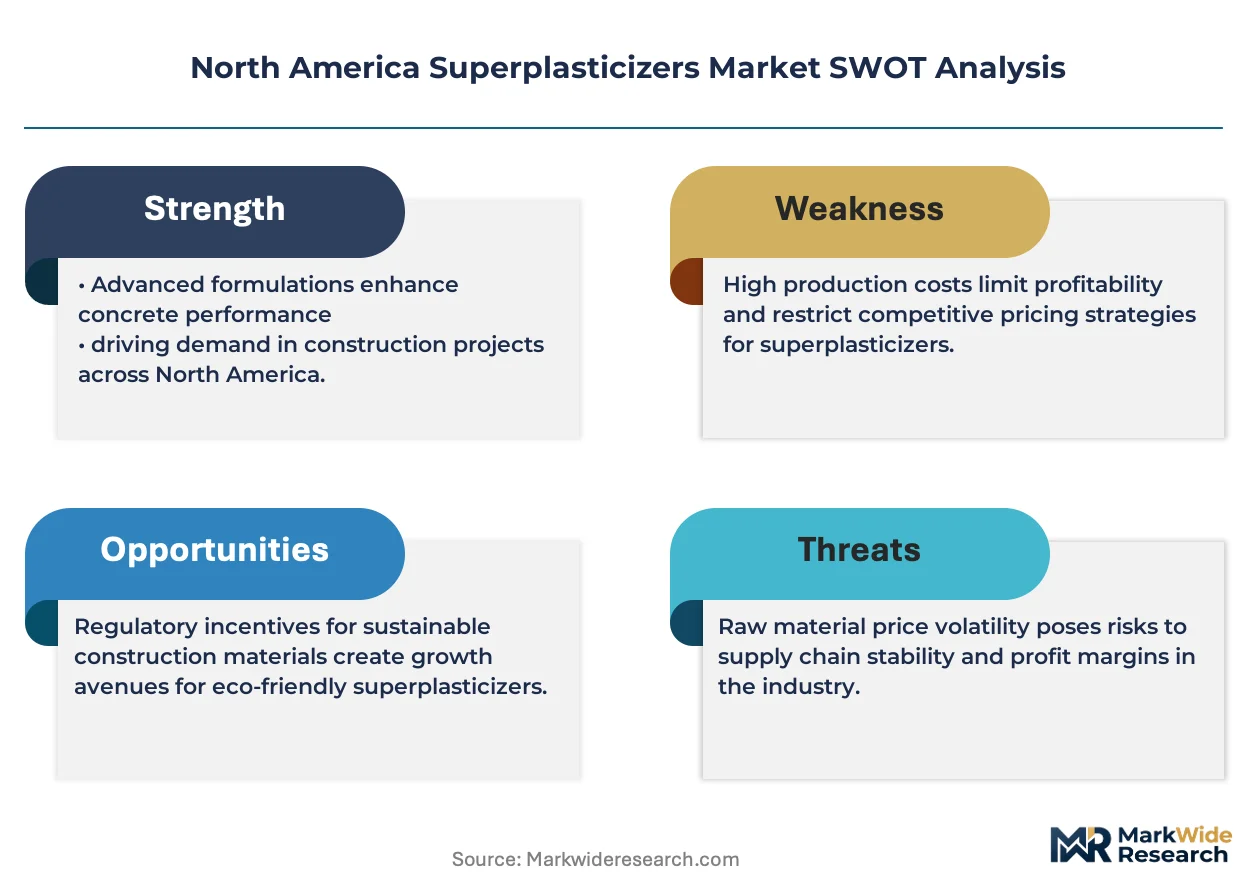
Fourteen-day ASTM C494 Type G certification cycles compress inventory turnover and amplify pricing power for Gulf Coast integrated producers with captive propylene oxide supply. This lead-time rigidity concentrates margin capture among manufacturers with backward integration into Texas petrochemical corridors, while forcing spot-market buyers into premium pricing for expedited formulation validation.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across the North American superplasticizer market. Price differentiation rests on certification tier—ASTM C494 Type F versus Type G validation—and embedded technical service depth rather than commodity chemistry alone. Cost compression in standard-grade naphthalene formulations is intensifying because Mexican dry-mix mortar producers are expanding regional blending capacity. Residential ready-mix operators exhibit highest price sensitivity due to per-cubic-yard cost optimization mandates, while infrastructure DOT contractors accept premium pricing for documented slump retention curves and field rheology support.
Supply Chain Analysis
Houston Ship Channel throughput constraints expose polycarboxylate ether production to hurricane-season disruption cascades. Manufacturing gravity centers on the United States, Canada, and Mexico, with propylene oxide feedstock, polyethylene glycol side chains, and sulfonated naphthalene intermediates drawing from Texas Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in propylene oxide supply, where three integrated producers control North American capacity. Distribution runs through direct sales with embedded field technical staff for megaprojects, supplemented by regional distributor networks serving independent ready-mix operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American superplasticizer market is approaching a platform-economics inflection as integrated service contracts bundling admixture supply with onsite rheology testing displace transactional chemical sales. This interoperability shift concentrates volume with suppliers capable of deploying specialized labor across multi-year infrastructure timelines.
For Market Incumbents: Secure ASTM C494 Type G certification pipelines for next-generation viscosity-modified polycarboxylates before California and New York DOTs finalize low-carbon procurement mandates. Expand backward integration into bio-based feedstock pathways to capture specification preference in federal infrastructure bids governed by EPA Greenhouse Gas Reduction Fund criteria. Threat substitution from CO2-cured concrete systems demands accelerated R&D in carbonation-curing-compatible molecular architectures. For New Entrants and Emerging Players: Technical field staff deployment gaps in Canadian prairie provinces and remote Mexican project sites represent the most penetrable white-space targets. Target these geographies through digital procurement platforms with certified test data and distributor partnerships for just-in-time delivery. A go-to-market angle bundling admixture supply with seasonal cold-weather formulation consulting addresses the unresolved slump-retention ceiling below 5°C that limits incumbent year-round specification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction chemical divisions of industrial majors lacking dedicated polycarboxylate R&D infrastructure. Long-term viability over a five-to-ten-year window favors suppliers with verified supply chain carbon accounting and established U.S. Gulf distribution networks for Mexican infrastructure pipeline access. Watch California and New York state DOT durability-guarantee procurement pilots as the signal for performance-based contracting inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captures EPA Greenhouse Gas Reduction Fund specification preference in federal bridge and tunnel tenders. |
| Long-Term Supply Agreement with State DOTs | Locks in volume commitments through Infrastructure Investment and Jobs Act domestic content compliance. |
| Joint Venture for Mexican Distribution Network | Establishes first-mover position in Pemex refinery upgrades and Tren Maya rail segments. |
| Capacity Expansion in Texas Gulf Coast Corridor | Consolidates propylene oxide feedstock access against hurricane-season supply disruption risk. |
| Green Manufacturing Transition | Aligns with evolving low-carbon procurement mandates from state departments of transportation. |
Research Methodology
Operator-level perspectives from ready-mix plant managers, DOT materials engineers, admixture procurement leads at general contractors, and technical R&D directors at integrated chemical conglomerates anchored the qualitative base. These primary interviews combined with secondary validation from EPA enforcement guidance documents, ASTM C494 certification records, state DOT procurement databases, and customs/trade data for propylene oxide derivatives. Bottom-up volume modeling triangulated against top-down infrastructure spending allocation analysis across the analysis window.
Sensitivity analysis tested demand elasticity to federal infrastructure appropriation volatility and propylene oxide price shock scenarios. Segmentation dimensions modeled include formulation chemistry tier, end-use application, project scale category, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and specification shift trajectories, with forecast inputs incorporating CSA A23.1 harmonization progress and Buy America compliance thresholds.
Material uncertainties—hurricane-season feedstock disruption severity, state-level low-carbon mandate adoption timing, and CO2-cured concrete technology maturation—sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained federal infrastructure spending authorization and polycarboxylate retention of specification dominance in high-performance concrete. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Global Fiber Reinforced Composites Market
Chemicals & Materials
North America Abrasives Market
Chemicals & Materials
Global Thermosetting Polymer Market
Chemicals & Materials
Europe Metal Cleaning Chemicals Market
Chemicals & Materials
Drum Filters Market
Chemicals & Materials
Global High Performance Polyamides Market
Chemicals & Materials
Toluene Diisocyanates (TDI) Market
Chemicals & Materials
Hair Lightening Product Market
Chemicals & Materials
United States Neoprene Market
Chemicals & Materials
South America Adhesives and Sealants Market
Chemicals & Materials
Propionic Acid Market
Chemicals & Materials
Superabrasive Electroplated Grinding Wheel Market
Chemicals & Materials
Global Chromatography Resin Market
Chemicals & Materials
Organic Friction Modifier Additives Market
Chemicals & Materials
Magnetic Plastics Market
Chemicals & Materials
Magnesia Carbon Bricks Market