
 Retail Core Banking Solution Market | 2026-2036
Retail Core Banking Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Core Banking Solution Market Intelligence
ISO 20022 certification is reorganizing competitive access in retail core banking, as institutions now require message-format compliance for cross-border payments and real-time settlement networks. Oracle leverages its database heritage to anchor large-scale on-premise deployments at tier-one institutions. Temenos differentiates through cloud-native architecture built for progressive modernization paths. Fiserv sustains dominance in North American payment processing through deep channel control and correspondent banking relationships.
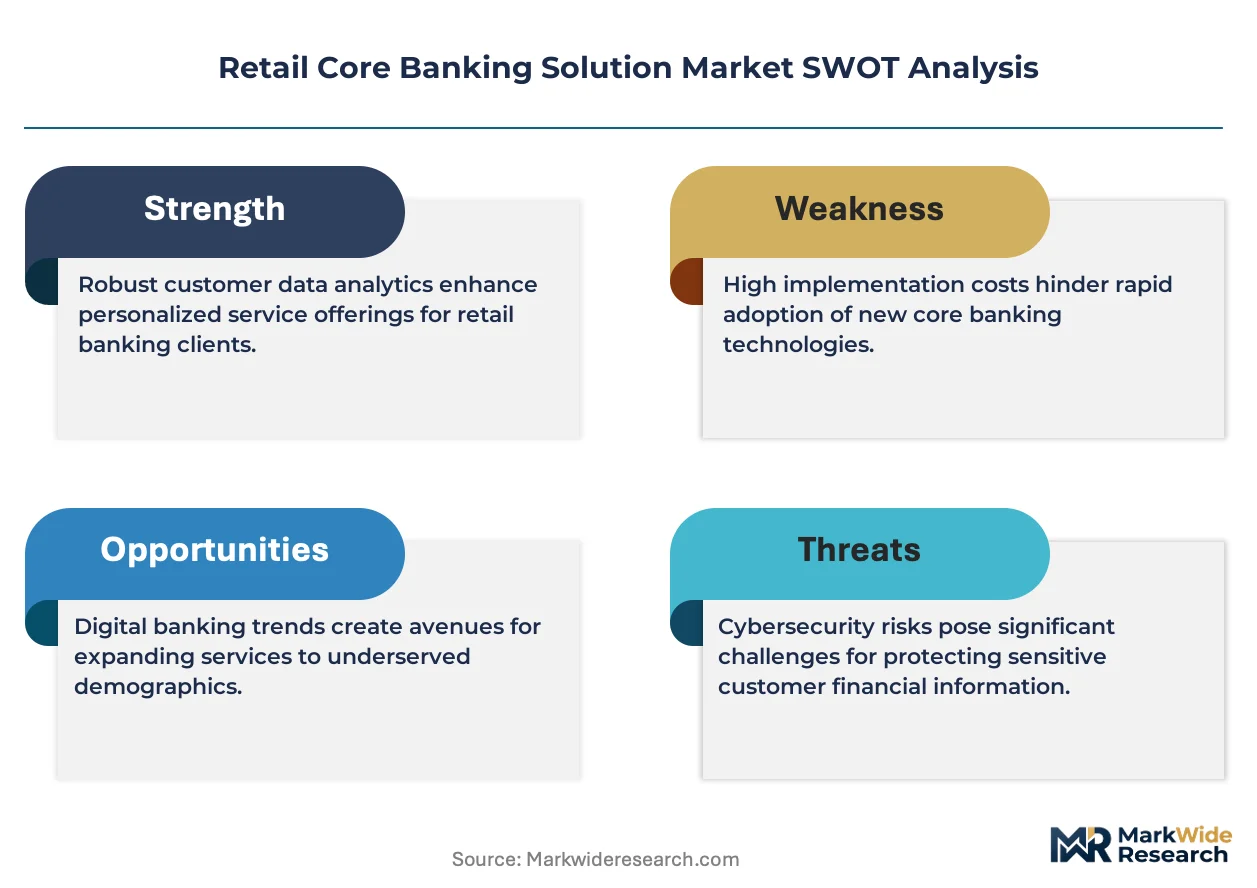
Retail core banking solutions comprise integrated software platforms managing deposit accounts, payment rails, lending workflows, and customer data across branch and digital channels, typically running on relational databases with sub-second transaction latency requirements and API layers for open banking connectivity. These systems serve as the operational backbone enabling financial institutions to process daily transactions, maintain regulatory ledgers, and deliver unified customer experiences across touchpoints. Cloud-based deployment is capturing the fastest expansion as banks exit datacenter ownership, while SaaS models concentrate margin pools through recurring revenue structures. Payment processing within service type segments leads absolute revenue contribution due to persistent transaction volume growth and interchange economics.
The European Banking Authority enforces DORA operational resilience standards that mandate recovery time objectives for critical banking functions, directly shaping vendor selection criteria and platform architecture requirements. In the United States, the OCC and FDIC supervise technology service provider risk management through FFIEC examination guidelines that extend liability chains to software vendors. India's RBI issues periodic master directions on information technology frameworks for regulated entities, forcing domestic and foreign platform providers to localize data residency and cybersecurity controls. Stakeholders must monitor how divergent national cloud sovereignty rules fragment previously standardized deployment playbooks.
Market Dynamics
Cloud migration mandates from national banking regulators are forcing wholesale replacement of on-premise core systems, compressing vendor selection cycles and redistributing procurement authority from IT departments to risk committees.
Growth Catalysts
- RBI Master Direction Guidelines:India's central bank mandates localized data residency and cybersecurity controls for regulated entities, accelerating domestic platform modernization among regional banks and credit unions.
- Real-Time Payment Rails:ISO 20022 message-format compliance requirements for cross-border settlement networks are compelling tier-one institutions to upgrade legacy infrastructure.
- Datacenter Exit Economics:Banks across Germany, Singapore, and Brazil are terminating co-location contracts to capture operational cost reductions through SaaS consumption models.
Market Restraints
- Specialized Engineering Talent Scarcity:Shortage of COBOL and mainframe specialists capable of maintaining legacy cores limits migration velocity and inflates project timelines.
- Concentrated Cloud Infrastructure:Dependence on hyperscale providers in Ireland, Virginia, and Mumbai creates single-point-of-failure exposure for mission-critical banking functions.
- Regulatory Fragmentation:Divergent national cloud sovereignty rules across EU member states fragment standardized deployment architectures and multiply compliance costs.
Strategic Opportunities
- Embedded Finance Convergence:API-first core architectures enable non-bank platforms to offer deposit and lending products, opening white-space revenue in retail and logistics verticals.
- DORA Operational Resilience:European Banking Authority recovery time mandates create vendor selection tailwinds for platforms with proven disaster recovery automation.
- Progressive Modernization Pathways:Tier-two institutions in Poland, Mexico, and Vietnam seek phased cloud transitions without full rip-and-replace disruptions.
Industry Challenges
- Core-to-Core Migration Complexity:Data mapping between disparate ledger formats requires multi-year parallel run periods that strain operational continuity.
- API Security Certification Delays:Open banking connectivity standards demand penetration testing cycles that extend go-live timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Core Banking Solution Market |
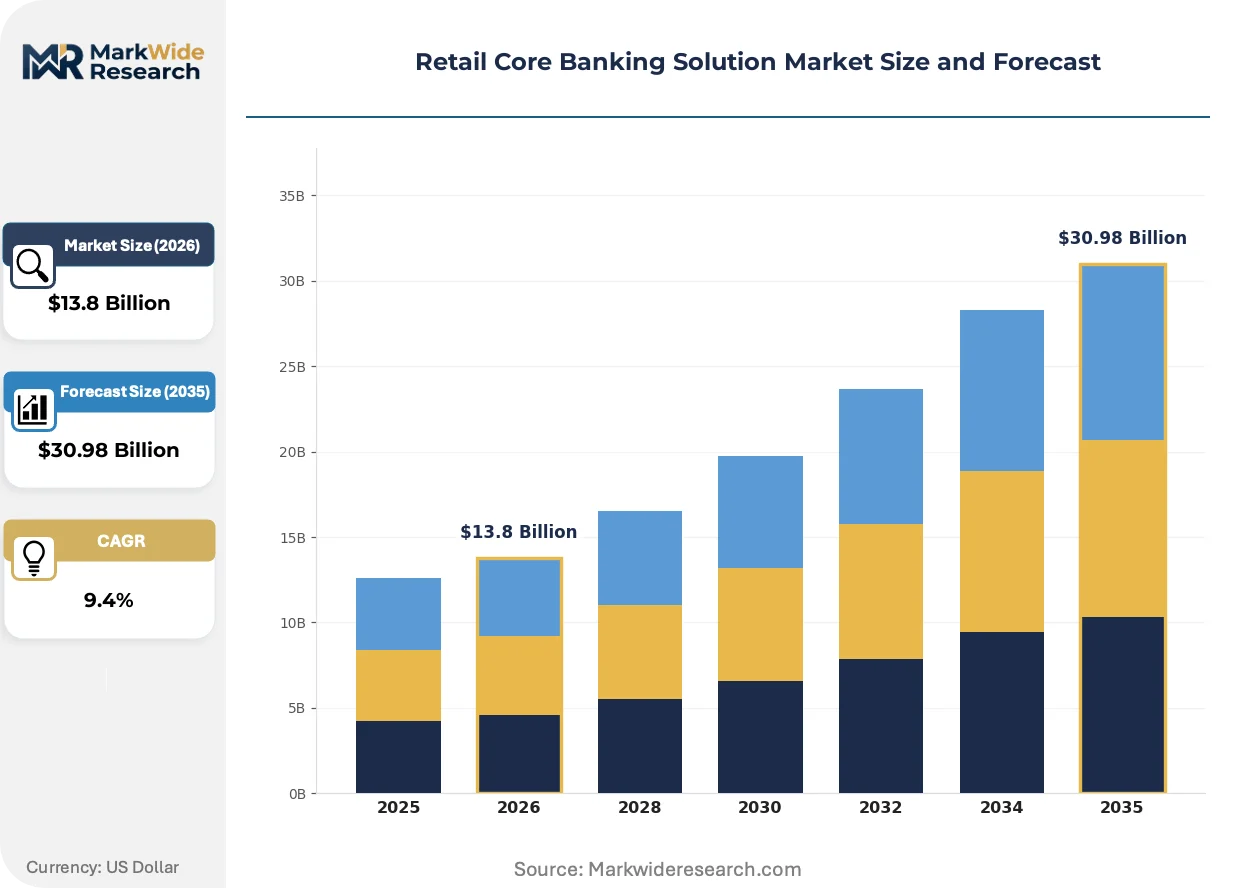
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $30.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Payment Processing, Loan Origination, Customer Relationship Management Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Banks, Credit Unions, Digital Banks, Fintech Companies Feature: Mobile Banking, Internet Banking, Analytics Dashboard, Compliance Management |
| Companies Covered | Oracle, Temenos, Fiserv, FIS, Finastra, SAP, Infosys, Tata Consultancy Services, NCR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Core Banking Solution Market Strategic Shifts & Innovations
Retail core banking technology is pivoting from monolithic architectures toward composable service meshes, enabling institutions to swap functional components without system-wide replacement.
Containerized microservices architectures are fragmenting the traditional core banking stack into discrete, independently deployable functions. Mid-tier banks in Australia and Canada are adopting these modular patterns fastest, lured by reduced vendor lock-in. The structural consequence is compressing implementation timelines from multi-year transformations to phased capability rollouts.
Europe's Digital Operational Resilience Act imposes strict recovery time objectives for critical banking functions. The regulation forces vendors to engineer automated failover capabilities and continuous backup verification. Tier-one institutions in France and Italy are prioritizing platforms with pre-certified DORA compliance to accelerate procurement approvals.
Buying committees are unbundling implementation services from software licenses to source specialized system integrators separately. Regional banks in Spain and the Netherlands now split RFPs between platform selection and deployment partners, fragmenting vendor control over project outcomes. This pattern is most visible among institutions with prior failed modernization attempts seeking risk distribution.
Retail Core Banking Solution Market Segmentation
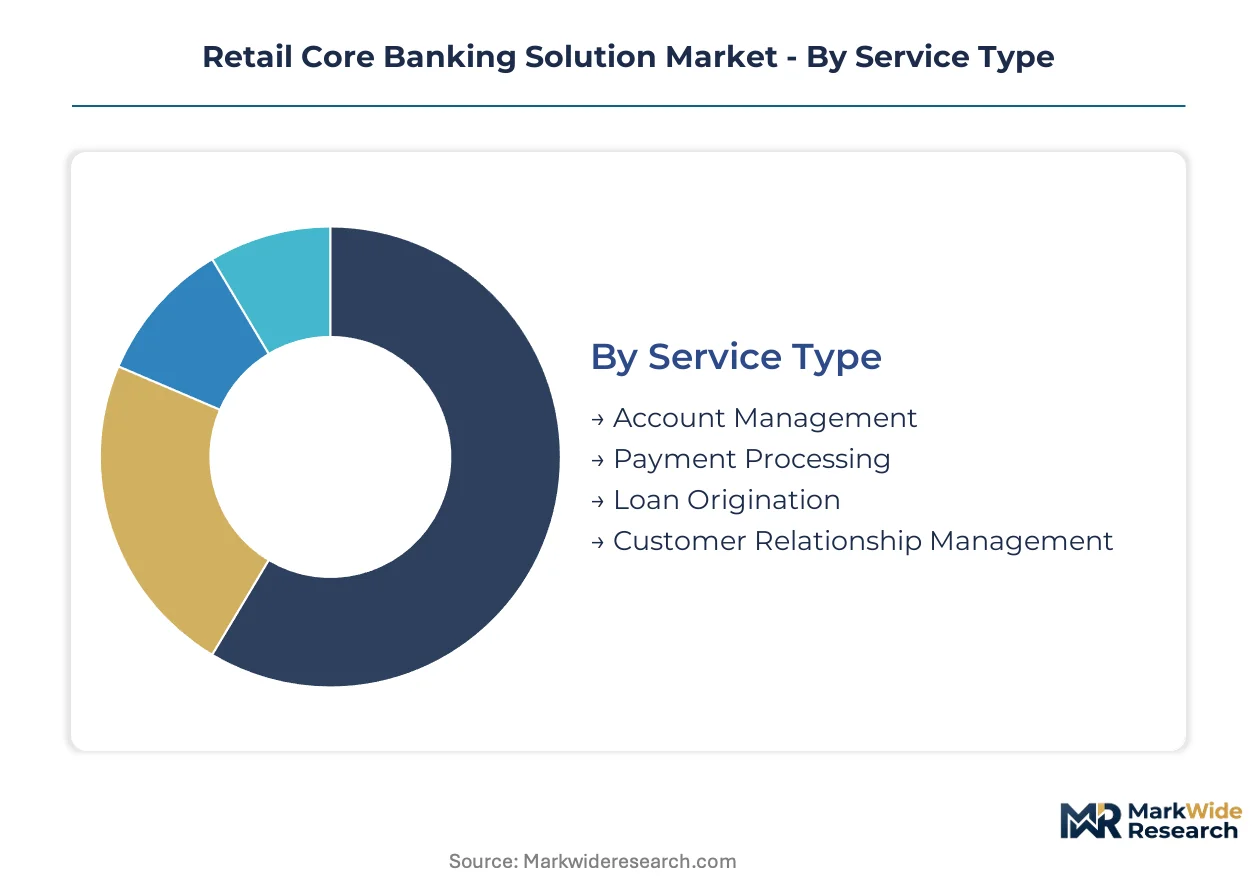
Retail core banking solutions fragment across four structural dimensions that determine procurement priorities and vendor selection criteria. Deployment architecture and service type classifications exert the strongest influence on contract value and implementation timelines. Each segmentation axis reveals distinct substitution pressures as banks weigh build-versus-buy decisions against modernization imperatives.
Service Type:
Payment processing faces acute substitution pressure from specialist fintech processors, while account management functions remain deeply embedded in proprietary legacy stacks.
- Payment Processing:Real-time settlement engines handling ISO 20022 message formats with sub-second latency requirements. Demand concentrates in India where RBI mandates push domestic banks toward certified platforms, constrained by interchange economics and volume-based pricing models.
- Account Management:Core ledger systems maintaining deposit records, interest calculations, and regulatory reporting across multi-currency environments. Regional banks in Germany and Brazil prioritize these modules as they exit datacenter ownership, driven by operational cost reduction targets.
- Loan Origination:Workflow automation for credit scoring, collateral verification, and disbursement scheduling.
- Customer Relationship Management:Unified profile management across branch and digital touchpoints with predictive analytics integration.
Payment processing retains volume leadership; loan origination holds the steepest expansion curve.
Deployment:
Cost tier stratification separates enterprise-grade on-premise installations from mid-market SaaS consumption, with hybrid architectures capturing institutions seeking phased transition paths.
- Cloud-Based:Fully managed infrastructure eliminating datacenter capital expenditure with auto-scaling compute resources. Tier-two institutions in Poland and Vietnam adopt these fastest, constrained by data residency requirements and regulator-mandated recovery time objectives.
- SaaS:Subscription licensing with embedded maintenance and upgrade cycles, typically delivered through multi-tenant architectures. Digital banks in Singapore and Mexico gravitate toward these models, driven by speed-to-market imperatives and reduced IT headcount needs.
- On-Premise:Self-managed installations retaining full infrastructure control for compliance-sensitive operations.
- Hybrid:Split architectures keeping sensitive workloads on-premise while offloading customer-facing channels to cloud.
SaaS deployment is climbing the fastest; on-premise retains the largest installed base.
End User:
Customer type determines functional requirements breadth, with credit unions demanding specialized member-centric workflows absent from generic banking platforms.
- Banks:Full-function platforms serving retail, commercial, and wealth segments with complex regulatory reporting needs.
- Credit Unions:Member-owned institutions requiring democratic governance tools and community-focused lending modules.
- Digital Banks:Branchless operators prioritizing API-first architectures and mobile-native experiences.
- Fintech Companies:Non-bank platforms seeking embedded finance capabilities through banking-as-a-service partnerships.
Traditional banks dominate current procurement volumes; fintech companies are gaining share fastest.
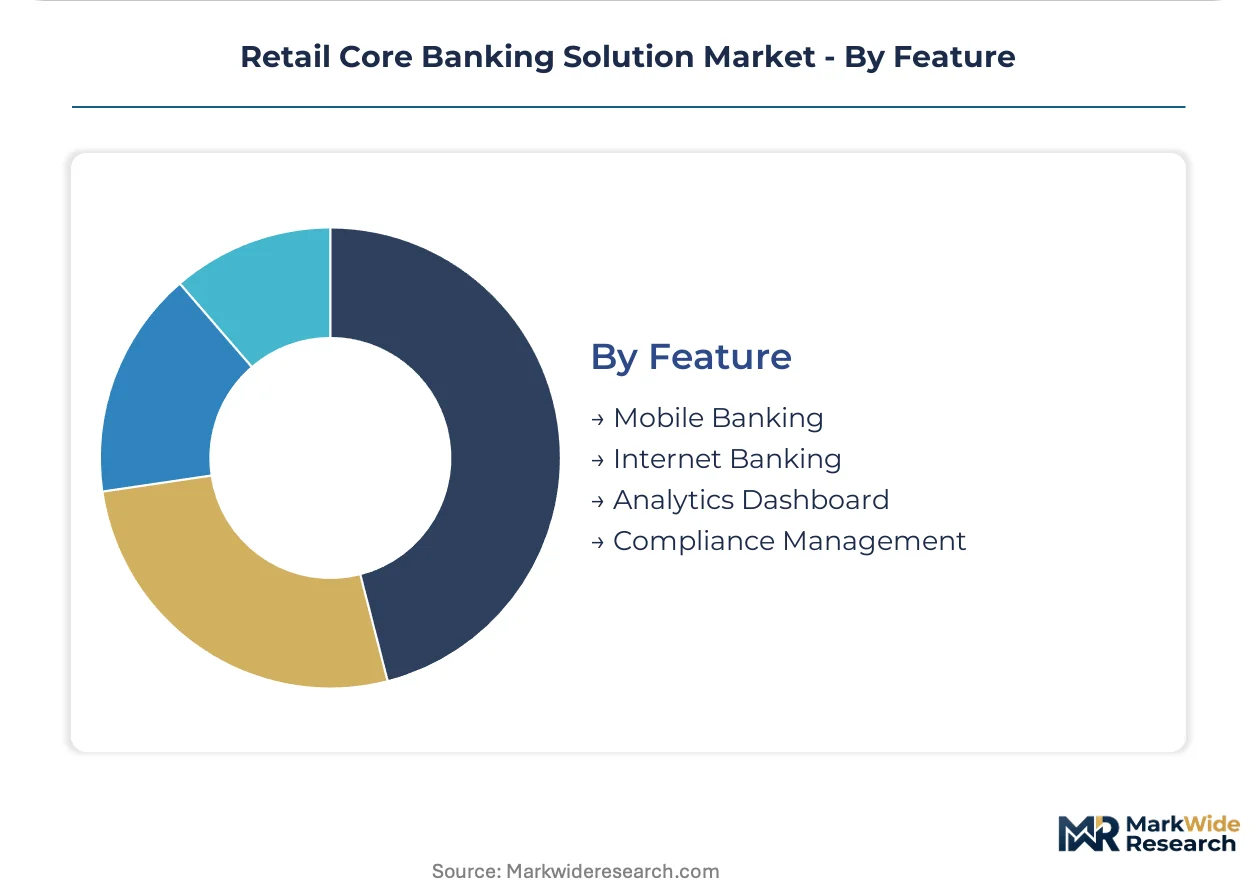
Feature:
Application maturity varies sharply, with mobile banking approaching commoditization while compliance management functions command premium pricing due to regulatory complexity.
- Mobile Banking:Native iOS and Android applications with biometric authentication and real-time transaction alerts.
- Internet Banking:Browser-based portals supporting bulk payments and document management for commercial clients.
- Analytics Dashboard:Predictive models for customer lifetime value and churn risk visualization.
- Compliance Management:Automated regulatory reporting with audit trail preservation and stress testing integration.
Mobile banking holds the largest user base; compliance management shows the steepest pricing premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's central bank mandates localized data residency and cybersecurity controls for regulated entities, accelerating domestic platform modernization among regional banks and credit unions. Cloud migration directives from national banking regulators in Germany and Singapore are forcing wholesale replacement of on-premise core systems. Brazil's datacenter exit economics are compressing vendor selection cycles across Latin America's largest banking market.
India
Regional banks and credit unions are accelerating modernization of legacy infrastructure to meet RBI Master Direction Guidelines. The central bank mandates localized data residency and cybersecurity controls for regulated entities, forcing domestic and foreign platform providers to localize data residency. Mumbai and Bangalore host the densest concentration of banking technology procurement activity as tier-two institutions seek phased cloud transitions.
Germany
Datacenter exit economics are driving banks to terminate co-location contracts and capture operational cost reductions through SaaS consumption models. The European Banking Authority enforces DORA operational resilience standards that mandate recovery time objectives for critical banking functions. Frankfurt's banking cluster prioritizes platforms with pre-certified DORA compliance to accelerate procurement approvals.
Singapore
Digital banks gravitate toward subscription licensing with embedded maintenance and upgrade cycles, driven by speed-to-market imperatives and reduced IT headcount needs. The Monetary Authority of Singapore supervises technology service provider risk management through examination guidelines that extend liability chains to software vendors. The city-state's financial district anchors Southeast Asian demand for API-first core architectures.
Brazil
Banks are terminating co-location contracts to capture operational cost reductions through SaaS consumption models as datacenter exit economics reshape procurement priorities. The central bank's open banking regulations mandate API connectivity standards that demand penetration testing cycles. São Paulo's financial corridor concentrates vendor selection activity among institutions seeking progressive modernization pathways.
United States
The OCC and FDIC supervise technology service provider risk management through FFIEC examination guidelines that extend liability chains to software vendors. Tier-one institutions require message-format compliance for cross-border payments and real-time settlement networks. New York and Charlotte banking clusters sustain dominance in North American payment processing through deep channel control.
Retail Core Banking Solution Market Key Industry Players
Listed leaders compete with private specialists across cloud-native architecture and on-premise deployment dimensions, creating a tiered competitive structure. Database heritage providers anchor large-scale enterprise installations while cloud-native specialists capture mid-market modernization cycles. Three archetypes dominate: legacy infrastructure incumbents with mainframe migration expertise, cloud-native challengers with progressive modernization toolkits, and system integrators bundling implementation with platform selection. Competitive moves concentrate on unbundling implementation services from software licenses and pre-certifying regulatory compliance to accelerate procurement timelines.
Within the legacy infrastructure tier, Oracle leverages its database heritage to anchor large-scale on-premise deployments at tier-one institutions. Temenos exemplifies the cloud-native challenger archetype through architecture built for progressive modernization paths. Fiserv occupies a position sustaining dominance in North American payment processing through deep channel control and correspondent banking relationships.
| Leading Market Players |
|---|
| Oracle |
| Temenos |
| Fiserv |
| FIS |
| Finastra |
| SAP |
| Infosys |
| Tata Consultancy Services |
| NCR Corporation |
| Others |
Cost & Logistics Intelligence
Containerized microservices architectures displacing monolithic legacy stacks simultaneously redistribute engineering talent demand toward India and Poland while compressing implementation pricing premiums previously commanded by mainframe migration specialists. This substitution dynamic fragments procurement authority across risk committees and IT departments, forcing vendors to unbundle implementation services from software licenses to maintain margin capture.
Pricing Analysis
Certification level for ISO 20022 message-format compliance creates the primary spread between premium and standard pricing tiers, with DORA pre-certified platforms commanding substantial premiums in Frankfurt and Paris banking clusters. Subscription-based SaaS licensing dominates contract structures, though project-based implementation fees persist for tier-one institutions requiring bespoke data migration. Price differentiation hinges on recovery time objective guarantees and data residency localization scope. Cost compression in mid-market cloud deployments intensifies as Polish and Vietnamese regional banks standardize on multi-tenant architectures. Digital banks in Singapore exhibit lowest price sensitivity, prioritizing speed-to-market over per-seat economics.
Supply Chain Analysis
Inbound logistics costs for specialized mainframe hardware components face acute pressure from container availability constraints across the Mumbai-Hamburg trade lane, forcing regional banks to accelerate datacenter exit timelines. Engineering talent supply concentrates in India, Ireland, and Singapore, with Hyderabad and Dublin hosting densest concentrations of ISO 20022 implementation specialists. Platform development draws from relational database expertise, cloud infrastructure provisioning, and cybersecurity audit capabilities. Single-source vulnerability permeates hyperscale cloud dependencies in Virginia and Mumbai. Distribution runs through direct vendor sales organizations and specialized system integrators, with unbundled procurement patterns fragmenting channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retail core banking solution market exhibits cyclical recovery characteristics driven by regulatory-mandated modernization waves, with RBI, EBA, and OCC enforcement timelines creating predictable replacement cycles that vendors must align against.
For Market Incumbents: Fortify defensive positions by deepening captive supply of cloud infrastructure capacity in Mumbai and Frankfurt to offset hyperscale dependency exposure. Accelerate DORA and ISO 20022 pre-certification investments to compress procurement timelines against emerging cloud-native challengers. Prioritize progressive modernization toolkits that enable phased transitions without full rip-and-replace disruptions, preserving incumbent relationships during cyclical troughs.
For New Entrants and Emerging Players: Anchor in embedded finance convergence opportunities across retail and logistics verticals, where API-first architectures enable non-bank deposit and lending product deployment. Target tier-two institutions in Poland, Mexico, and Vietnam seeking phased cloud transitions with lowest incumbent switching costs. Pursue white-label banking-as-a-service partnerships with fintech platforms rather than direct core replacement sales to bypass lengthy vendor qualification cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-native specialists possessing proven DORA compliance automation and established progressive modernization revenue streams. Long-term viability hinges on regulatory certification moats that sustain pricing power across multiple enforcement cycles. Monitor RBI master direction implementation velocity as inflection indicator for Indian modernization demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Pre-Certification Investment | Accelerates procurement approvals at tier-one institutions requiring cross-border payment compliance. |
| DORA Compliance Automation Engineering | Captures vendor selection tailwinds from Frankfurt and Paris banking clusters under EBA enforcement. |
| Progressive Modernization Toolkit Development | Enables phased cloud transitions for Polish and Vietnamese regional banks without operational disruption. |
| Embedded Finance API Partnership Expansion | Opens white-space revenue in retail and logistics verticals through banking-as-a-service integration. |
| Implementation Services Unbundling | Responds to Spanish and Dutch regional bank procurement patterns seeking risk distribution. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, vendor contract disclosures, and central bank examination guidelines. Interviews with chief technology officers, risk committee chairs, procurement directors at regional banks, and integration specialists at system integrators inform demand-side validation. Secondary sources include RBI master direction circulars, EBA DORA technical standards, FFIEC examination guidelines, SEC 10-K software revenue disclosures, and cloud infrastructure capex reports. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate banking IT spend estimates anchor value projections.
Segmentation dimensions modeled span service type, deployment architecture, end-user category, and functional feature maturity across the projection horizon. Analytical framework incorporates payment processing volume growth, account management module replacement cycles, and loan origination automation penetration. CAGRs derive from regression analysis of historical modernization spend against regulatory enforcement timelines. Forecast inputs include datacenter exit economics trajectories in Germany and Brazil, plus ISO 20022 compliance deadline clustering effects.
Material uncertainties — regulatory delay, cloud sovereignty rule fragmentation, and specialized engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding enforcement consistency and technology adoption curve stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Workforce Management Software Market
Software & Services
Vending Software Market
Software & Services
Batch Management Software Market
Software & Services
Construction Suites Software Market
Software & Services
Kennel Management Software Market
Software & Services
Global Diagram Software Market
Software & Services
House Cleaning App Market
Software & Services
Global Online Assessment Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Lighting Control Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
PAC Programming Software Market
Software & Services
Productivity Management Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Courier Software Market