
 Global Retail Sourcing and Procurement Software Market | 2026-2036
Global Retail Sourcing and Procurement Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail Sourcing and Procurement Software Market Foresight
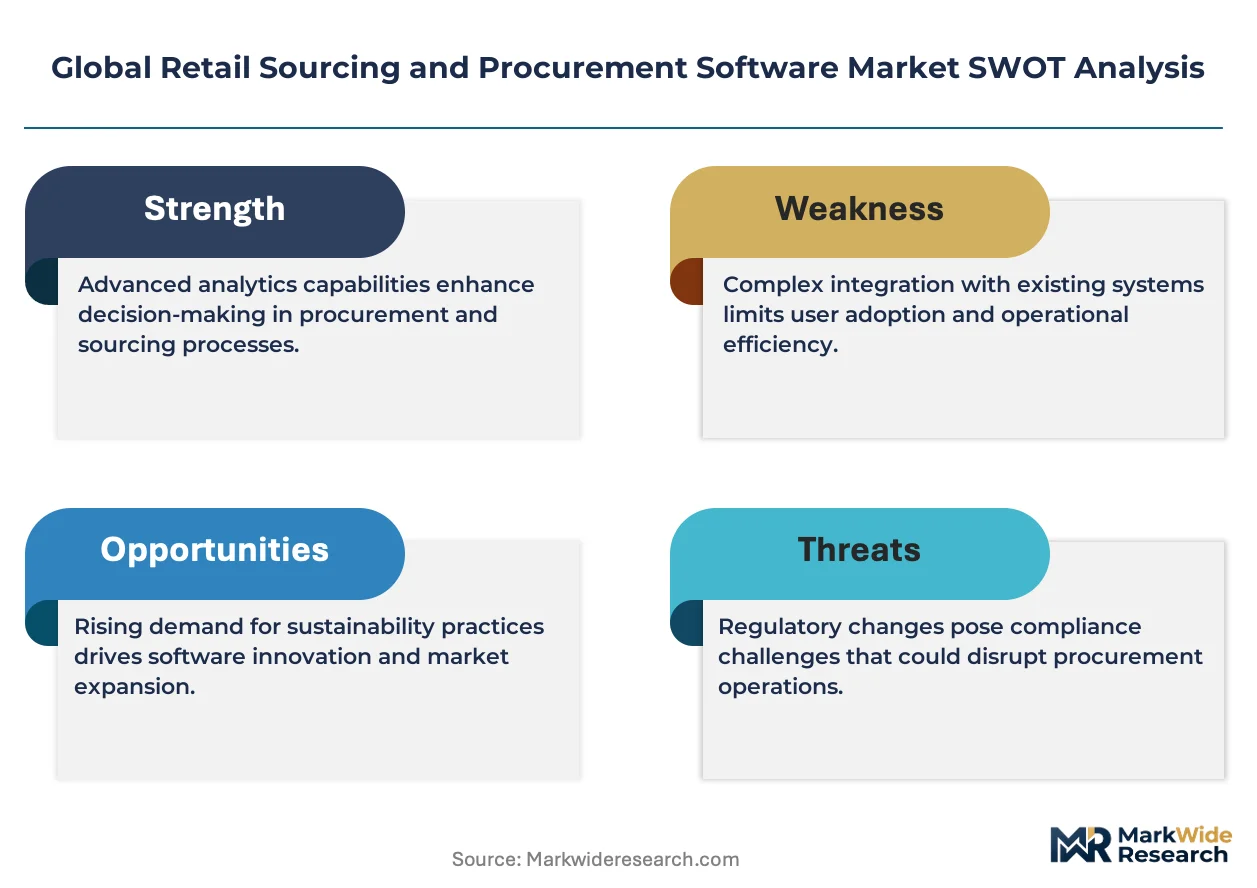
Subscription-based supplier onboarding and compliance scoring is decoupling procurement software from perpetual license models. SAP Ariba leverages its network effect to anchor enterprise retail accounts across Europe. Coupa Software competes through spend analytics specialization, while Ivalua dominates complex manufacturing-linked retail supply chains with deep configuration tools.
Retail sourcing and procurement software comprises modular applications for supplier discovery, contract lifecycle management, purchase order orchestration, and invoice reconciliation, typically delivered through multi-tenant cloud architectures with API-first integration protocols. Its primary commercial purpose is to reduce procurement cycle times and enforce compliance across geographically dispersed supplier bases. Cloud-based deployment leads solution adoption as retail chains retire on-premise ERP modules, while supplier management and risk management segments capture disproportionate investment as tariff volatility and ESG auditing requirements intensify. Spend analysis functions mature fastest in grocery and apparel retail, where margin compression demands granular cost visibility.
FDA food safety traceability rules, EU CSRD supply chain disclosure requirements, and Japan METI's supply chain resilience guidelines collectively mandate auditable procurement documentation, directly expanding software demand. GDPR and equivalent data localization standards in Germany and Japan shape vendor selection criteria for cloud-hosted platforms. Stakeholders must evaluate whether their procurement data architectures satisfy emerging cross-border compliance obligations before committing to multi-year SaaS contracts.
Market Dynamics
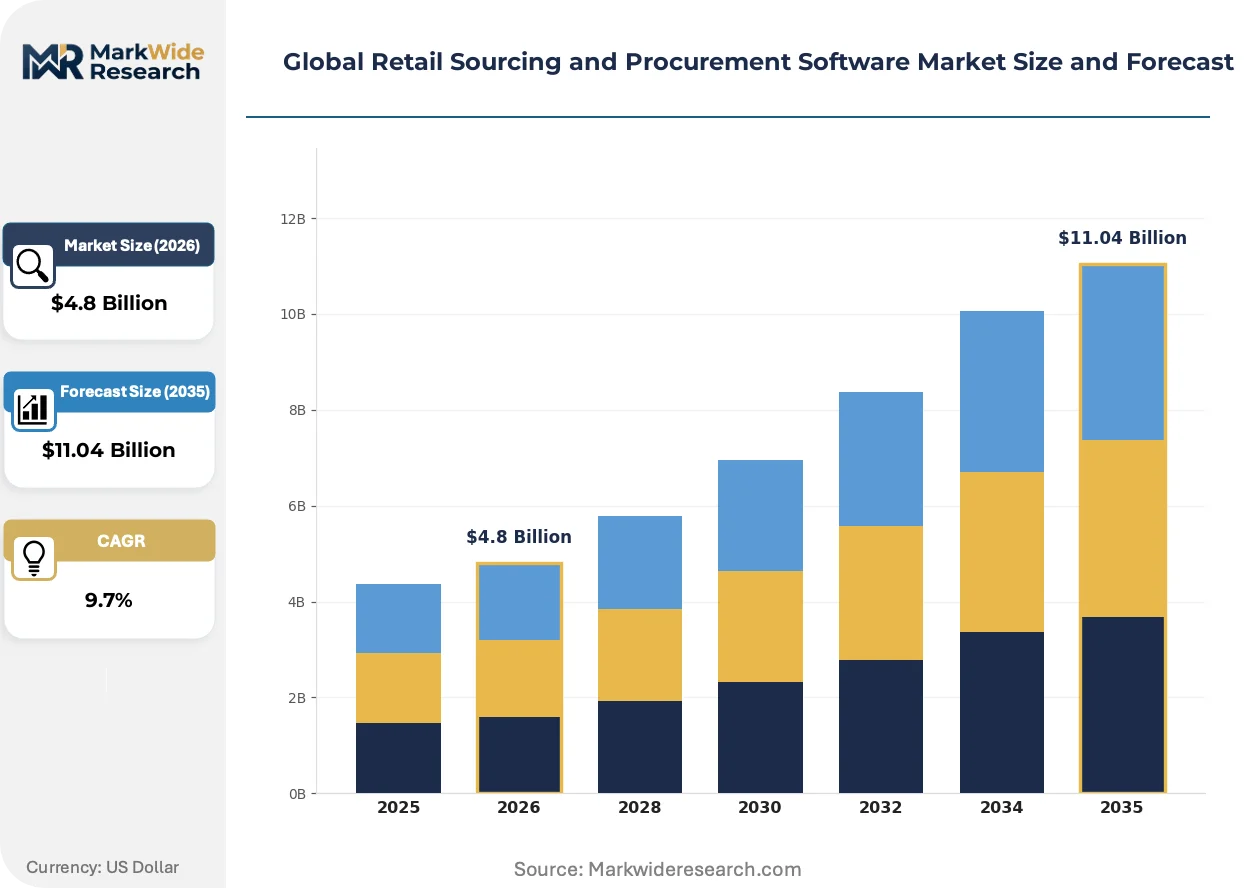
Cloud-native procurement architectures are absorbing enterprise IT budgets as tariff volatility and ESG disclosure mandates force retailers to retire fragmented on-premise ERP modules. The structural pivot toward API-first supplier networks concentrates competitive advantage among vendors offering real-time risk analytics.
Growth Catalysts
- EU CSRD supply chain disclosure:Specialty retailers across Germany and France must deploy auditable procurement documentation systems by statutory deadlines, directly expanding software procurement cycles.
- Omnichannel inventory synchronization:Apparel and grocery operators require unified supplier visibility across physical and digital channels, accelerating modular procurement suite adoption.
- Japan METI resilience guidelines:Japanese retailers face mandatory supply chain mapping requirements, driving demand for risk analytics modules with multi-tier supplier tracing.
Market Restraints
- GDPR data localization friction:German and French procurement data residency requirements fragment cloud hosting architectures, increasing vendor compliance costs and deployment timelines.
- Technical debt in legacy ERP:Mid-market retailers retain heavily customized on-premise procurement modules, creating integration complexity that slows SaaS migration.
- Specialized talent scarcity:Shortages of procurement technologists fluent in both API integration and ESG reporting standards constrain implementation velocity.
Strategic Opportunities
- India PLI scheme alignment:Contract manufacturers serving export markets seek procurement software with built-in duty drawback and origin certification tracking.
- AI-augmented spend classification:Machine learning models trained on retail-specific commodity taxonomies offer differentiation against generic enterprise procurement tools.
- Carbon accounting module bundling:EU Green Deal compliance creates white space for procurement suites with embedded Scope 3 emissions calculation engines.
Industry Challenges
- Multi-tenant security architecture:Retailers handling competitive supplier pricing data demand isolated infrastructure configurations that compromise SaaS economies of scale.
- Cross-border invoice reconciliation:VAT and customs duty variations across sourcing jurisdictions fragment automated payment workflows, requiring jurisdiction-specific rule engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail Sourcing and Procurement Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Spend Analysis, Supplier Management, Contract Management, Order Management, Invoice Management, Risk Management Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Web-Based, Mobile Application: Procurement Automation, Supplier Collaboration, Category Management, Strategic Sourcing, Purchase Order Management, Performance Monitoring End User Segment: Retail Chain Operators, E-Commerce Platforms, Specialty Stores, Departmental Stores, Hypermarkets, Convenience Stores |
| Companies Covered | GEP, Zycus, SAP Ariba, IBM, Jaggaer, Coupa Software, Ivalua, Infor, Oracle Procurement Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail Sourcing and Procurement Software Market Shifts & Advancements
Generative AI is absorbing procurement workflow design, compressing supplier onboarding cycles and automating contract clause extraction. Three interconnected developments are restructuring competitive positioning in retail sourcing technology.
Embedded supplier risk scoring is absorbing procurement decision-making. Machine learning models aggregate credit data, ESG ratings, and geopolitical indicators into dynamic supplier health dashboards. Mid-market apparel retailers in the United States and Germany deploy these tools to pre-qualify vendors before purchase order authorization. The technology is absorbing traditional manual due diligence processes, compressing sourcing cycle times by eliminating sequential approval stages.
EU CSRD mandatory supply chain disclosure is forcing documentation architecture redesign. Retailers must maintain auditable records linking finished goods to specific supplier facilities across multiple tiers. German and French operators invest in blockchain-anchored traceability layers to satisfy statutory evidence requirements. Specialty food retailers face the steepest compliance burden under parallel FDA food safety traceability rules.
Subscription-based supplier network access is displacing perpetual license procurement. Retailers pay per onboarded supplier rather than fixed software fees, aligning vendor costs with actual sourcing scale. Grocery and home goods operators in Japan and the United States favor this model for seasonal supplier rotation. The shift concentrates vendor revenue quality on network retention metrics rather than upfront implementation fees.
Global Retail Sourcing and Procurement Software Market Segmentation
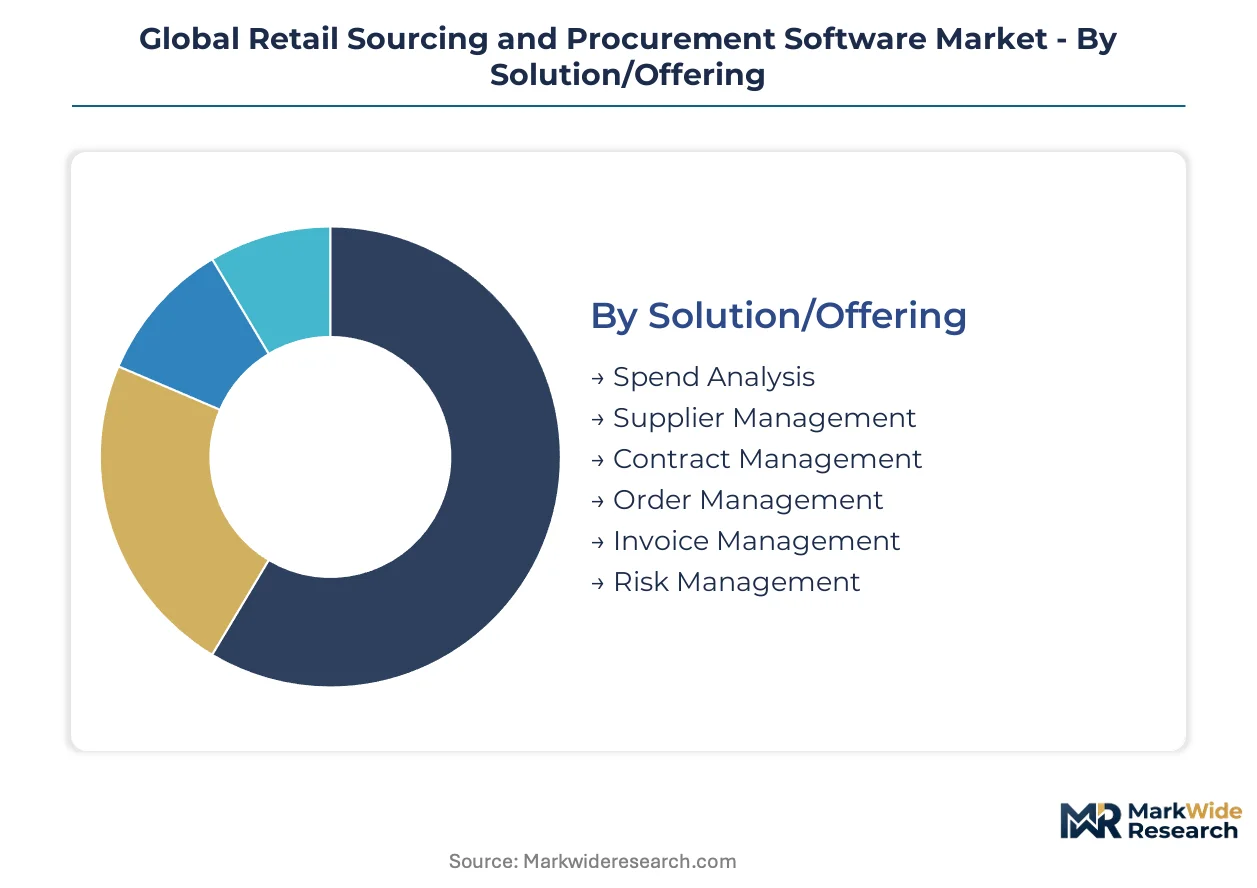
Retail procurement software segments diverge sharply by technical architecture and operational depth. Deployment models determine integration complexity, while solution modules map directly to compliance mandates and margin pressure points across grocery, apparel, and home goods operations.
Solution/Offering:
Standardized SaaS modules compete against deeply configurable enterprise suites across this category, with customization premiums widening as ESG disclosure rules intensify audit trail requirements.
- Spend Analysis:Machine learning models classify procurement transactions against retail-specific commodity taxonomies, compressing cost visibility cycles for margin-pressured grocery and apparel operators in Germany and Japan. Demand concentrates among omnichannel retailers reconciling physical and digital channel procurement data under unified dashboards.
- Supplier Management:Multi-tier supplier onboarding platforms with embedded ESG scoring pre-qualify vendors before purchase order authorization. Specialty retailers across France and the United States deploy these tools to satisfy EU CSRD and FDA traceability documentation mandates.
- Contract Management:Clause extraction engines automate agreement renewal workflows.
- Order Management:Purchase order orchestration modules synchronize inventory positions across fragmented supplier networks.
- Invoice Management:Three-way matching systems reconcile goods receipts against purchase orders and supplier invoices.
- Risk Management:Geopolitical and credit data aggregation tools map supply chain vulnerability under Japan METI resilience guidelines.
Most installed capacity flows through Supplier Management. Expansion is steepest in Risk Management.
Deployment:
Cost tier separation between capital-intensive on-premise infrastructure and operational-expense SaaS models shapes vendor selection, with mid-market retailers trapped between technical debt and cloud migration timelines.
- Cloud-Based:Multi-tenant architectures with API-first integration protocols absorb enterprise IT budgets as tariff volatility forces retirement of fragmented legacy ERP modules. North American specialty retailers accelerate adoption to comply with cross-border ESG disclosure frameworks.
- SaaS:Subscription pricing per onboarded supplier displaces perpetual licenses, aligning vendor costs with actual sourcing scale for seasonal supplier rotation in grocery and home goods.
- On-Premise:Heavily customized legacy procurement modules constrain mid-market migration velocity.
- Hybrid:Split architectures isolate competitive pricing data while leveraging cloud analytics.
- Web-Based:Browser-accessible procurement portals serve distributed buying teams.
- Mobile:Field purchasing applications enable real-time supplier communication.
Cloud-Based deployments capture the majority of new implementations. SaaS is climbing the fastest as procurement technologists fluent in API integration remain scarce.
Application:
Customer type stratification separates transactional automation tools for high-volume operators from strategic sourcing platforms serving complex category management needs.
- Procurement Automation:Workflow engines compress requisition-to-payment cycles through automated approval routing and catalog management. Hypermarkets in the United States deploy these systems to manage high-frequency replenishment across thousands of SKUs.
- Strategic Sourcing:RFP orchestration and bid optimization modules support complex negotiations for private-label development. Departmental stores in Germany utilize these tools for seasonal supplier selection under EU Green Deal carbon accounting requirements.
- Supplier Collaboration:Shared forecasting portals align production schedules with demand signals.
- Category Management:Commodity intelligence platforms aggregate market pricing and supply availability.
- Purchase Order Management:Multi-channel order consolidation reduces manual reconciliation overhead.
- Performance Monitoring:Scorecard systems track delivery reliability and quality metrics.
Procurement Automation holds the largest installed base. Strategic Sourcing shows the steepest expansion trajectory as tariff volatility demands scenario modeling capabilities.
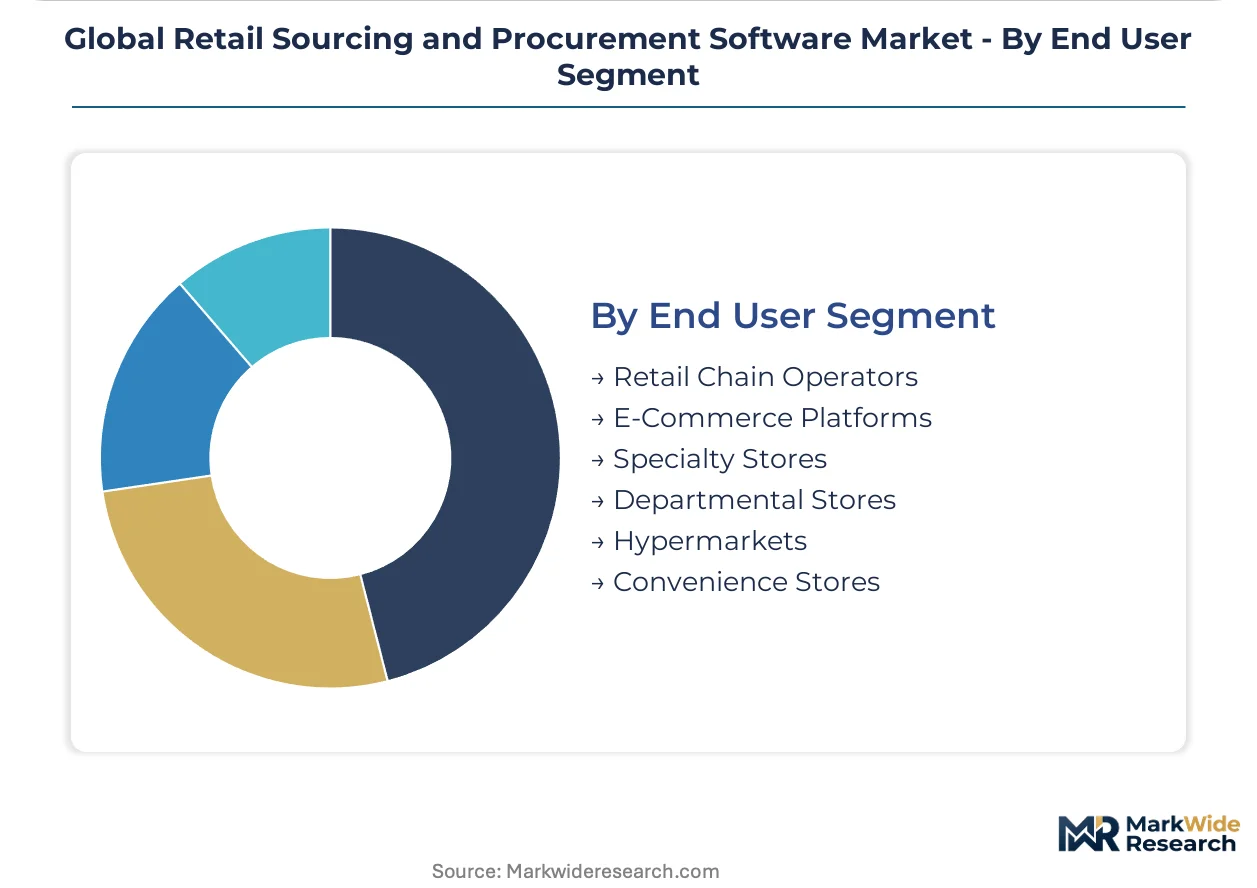
End User Segment:
Volume concentration varies dramatically across retail formats, with e-commerce platforms demanding real-time API integration while convenience stores prioritize mobile-first simplicity.
- E-Commerce Platforms:API-native procurement suites synchronize drop-ship supplier inventory with consumer-facing stock positions, requiring millisecond-latency data exchange across fragmented fulfillment networks in Japan and the United States.
- Retail Chain Operators:National grocery and apparel chains deploy modular procurement suites with risk analytics for multi-tier supplier tracing under FDA and EU CSRD mandates.
- Specialty Stores:Curated assortments drive supplier relationship intensity over transaction volume.
- Departmental Stores:Complex private-label portfolios require contract lifecycle management depth.
- Hypermarkets:High-SKU environments demand automated catalog management and three-way matching.
- Convenience Stores:Rapid replenishment cycles favor mobile purchasing applications.
Retail Chain Operators command the deepest procurement software penetration. E-Commerce Platforms are expanding most quickly as marketplace models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan pursue procurement digitization through divergent regulatory pathways, while the United States leverages scale advantages in cloud-native deployment. These three markets anchor software demand as compliance mandates and omnichannel complexity reshape investment priorities.
United States
Specialty retailers and grocery chains drive cloud procurement adoption to satisfy FDA food safety traceability mandates. The FDA's FSMA Rule 204 requires granular supplier documentation for high-risk foods. California-based omnichannel operators deploy API-first suites to synchronize drop-ship inventory across fragmented fulfillment networks.
Germany
EU CSRD disclosure requirements force mid-market retailers to replace legacy ERP modules with auditable procurement documentation systems. GDPR data localization rules fragment cloud hosting architectures, elevating vendor compliance costs. The Rhine-Ruhr industrial corridor concentrates demand for supplier risk analytics among automotive-linked retail supply chains.
Japan
METI supply chain resilience guidelines mandate multi-tier supplier mapping for retailers and their contract manufacturers. Japanese grocery and home goods operators favor subscription-based supplier onboarding to accommodate seasonal vendor rotation. The Kanto region around Tokyo anchors SaaS procurement adoption among e-commerce platforms requiring millisecond-latency inventory synchronization.
France
EU Green Deal carbon accounting requirements and CSRD parallel disclosure obligations intensify software procurement cycles for apparel and luxury retailers. ANSM and CNIL data governance standards shape vendor selection criteria. The Île-de-France region, encompassing Paris, concentrates strategic sourcing platform deployment among departmental stores managing complex private-label portfolios.
India
PLI scheme incentives for contract manufacturers serving export markets generate demand for procurement software with embedded duty drawback and origin certification tracking. The DGFT's documentation requirements for export-oriented units drive adoption. Maharashtra and Gujarat industrial clusters anchor implementation among textile and electronics contract manufacturers integrating with global retail supply chains.
Global Retail Sourcing and Procurement Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors and vertical SaaS providers occupying distinct competitive tiers. The market structure concentrates around network-effect platforms, analytics specialists, and deeply configurable suites serving complex supply chains. Three archetypes dominate: procurement network orchestrators, spend analytics pure-plays, and manufacturing-linked configuration specialists. Competitive dynamics center on API ecosystem expansion and ESG compliance module bundling as primary differentiation vectors.
Within the network-orchestrator tier, SAP Ariba leverages its installed base to anchor enterprise retail accounts across Europe. Coupa Software occupies a position exemplifying spend analytics specialization, while Ivalua represents the manufacturing-linked configuration archetype with deep toolsets for multi-tier supplier tracing. These three entities collectively illustrate how vendor selection criteria have shifted toward real-time risk visibility and cross-border compliance architecture.
| Leading Market Players |
|---|
| GEP |
| Zycus |
| SAP Ariba |
| IBM |
| Jaggaer |
| Coupa Software |
| Ivalua |
| Infor |
| Oracle Procurement Cloud |
| Others |
Supply & Pricing Matrix
Procurement technologists concentrated in Bangalore and the San Francisco Bay Area command wage premiums that widen pricing-tier spreads between enterprise suites and mid-market SaaS offerings. Labor-cost differentials in these talent hubs force vendors to stratify subscription rates by implementation complexity and support tier.
Pricing Analysis
Capacity additions in India and Eastern Europe are reshaping price floors for implementation services, compressing deployment cost premiums that historically favored North American systems integrators. Subscription pricing stratifies across premium, standard, and economy tiers based on API integration depth and ESG module bundling. Pricing pressure stems from mid-market retailers demanding per-supplier onboarding models that displace fixed license fees. Hypermarket chains exhibit highest price sensitivity due to thin margin structures, while luxury departmental stores absorb premium tiers for bespoke configuration.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate vendor participation in enterprise retail procurement, filtering cloud-native providers from legacy on-premise resellers. Software development concentrates in the United States, India, and Germany, with implementation services drawing from Poland and the Philippines. Cloud infrastructure dependencies rest on hyperscaler data centers in Frankfurt, Tokyo, and Virginia. Single-source vulnerability runs through API gateway providers that orchestrate multi-tenant architectures. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory disclosure mandates create durable replacement cycles for legacy ERP procurement modules. Compliance-driven spending proves recession-resistant across grocery and apparel retail.
For Market Incumbents: Lock in enterprise accounts through embedded carbon accounting modules that satisfy EU CSRD and Japan METI requirements ahead of statutory deadlines. Deepen API ecosystem partnerships to defend against vertical SaaS entrants targeting specialty retail niches. Prioritize data residency architectures that neutralize GDPR localization friction in German and French procurement cycles.
For New Entrants and Emerging Players: API-first supplier onboarding portals offer the lowest competitive density for mid-market grocery chains in Japan and the United States. Target private-label apparel manufacturers seeking origin certification tracking for EU Green Deal compliance. Pursue channel partnerships with regional systems integrators rather than direct field sales to compress customer acquisition costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among spend analytics pure-plays lacking risk management module depth. The five-to-ten year viability window favors vendors with multi-tenant architectures and recurring revenue above eighty percent. Watch for inflection when FDA issues final food traceability enforcement guidance triggering accelerated replacement of legacy documentation systems.
| Strategic Initiative | Industry Significance |
|---|---|
| ESG Module Bundling | Embedded Scope 3 engines satisfy EU CSRD disclosure mandates for German apparel retailers. |
| API Ecosystem Expansion | Native integration with SAP Ariba and Coupa networks accelerates enterprise procurement cycles. |
| Carbon Accounting Integration | Real-time emissions tracking aligns with Japan METI resilience guidelines for supply chain mapping. |
| Acquisition of Specialist Firm | Machine learning spend classification targets grocery margin compression in United States hypermarkets. |
| Geographic Expansion | India PLI scheme alignment captures contract manufacturer demand for duty drawback automation. |
Research Methodology
Bottom-up retail chain modeling reconciled against top-down cloud procurement deployment tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at omnichannel retailers and software vendors combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of SaaS subscription growth and on-premise ERP retirement patterns informed the projection framework. The model segments by deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern. CAGRs derive from fitted growth curves applied to disclosed vendor revenue ranges and procurement software spending surveys across the analysis window. Industry-specific inputs include ESG disclosure deadline schedules and FDA enforcement timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for generative AI workflow automation would alter the outlook for implementation service revenues. Forecasts reflect underlying assumptions about regulatory enforcement intensity and cloud migration velocity. A model refresh is warranted upon material change in EU CSRD implementation guidance or FDA food traceability enforcement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Big Data Software Market
Software & Services
Global Presentation Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
User Research Repositories Software Market
Software & Services
Global Content Management Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Transient Analysis Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Document Capture Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Procure to Pay Software Market