
 Serverless Computing Market | 2026-2036
Serverless Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Serverless Computing Market Intelligence
GDPR's data-residency mandates are repositioning how European enterprises evaluate serverless providers. Amazon Web Services (AWS) anchors its advantage through Lambda's execution-environment specialization across multiple sovereign regions. Microsoft competes by extending Azure Functions' enterprise-policy integration with Active Directory ecosystems. Google Cloud differentiates via its Knative-based open-source portability layer for containerized workloads.
Serverless computing abstracts infrastructure provisioning by executing code in ephemeral, event-triggered containers measured in millisecond billing increments. The architecture eliminates persistent server management, routing compute resources to functions only upon invocation through API gateways, message queues, or scheduled triggers. Public cloud deployment leads volume adoption, though hybrid cloud configurations are capturing margin pools from regulated industries requiring on-premises data sovereignty. Real-time data processing applications are outpacing web application growth as streaming analytics and event-driven architectures displace batch workloads.
FDA guidelines on software-as-a-medical-device and HIPAA's business-associate requirements shape how healthcare adopters configure serverless audit trails and encryption standards. The EU AI Act's risk-classification framework is forcing providers to document automated decision pathways within function-as-a-service pipelines. Stakeholders must monitor evolving national data-localization statutes to determine whether multi-cloud orchestration or single-provider regional replication delivers compliant latency at lower total cost of ownership.
Market Dynamics
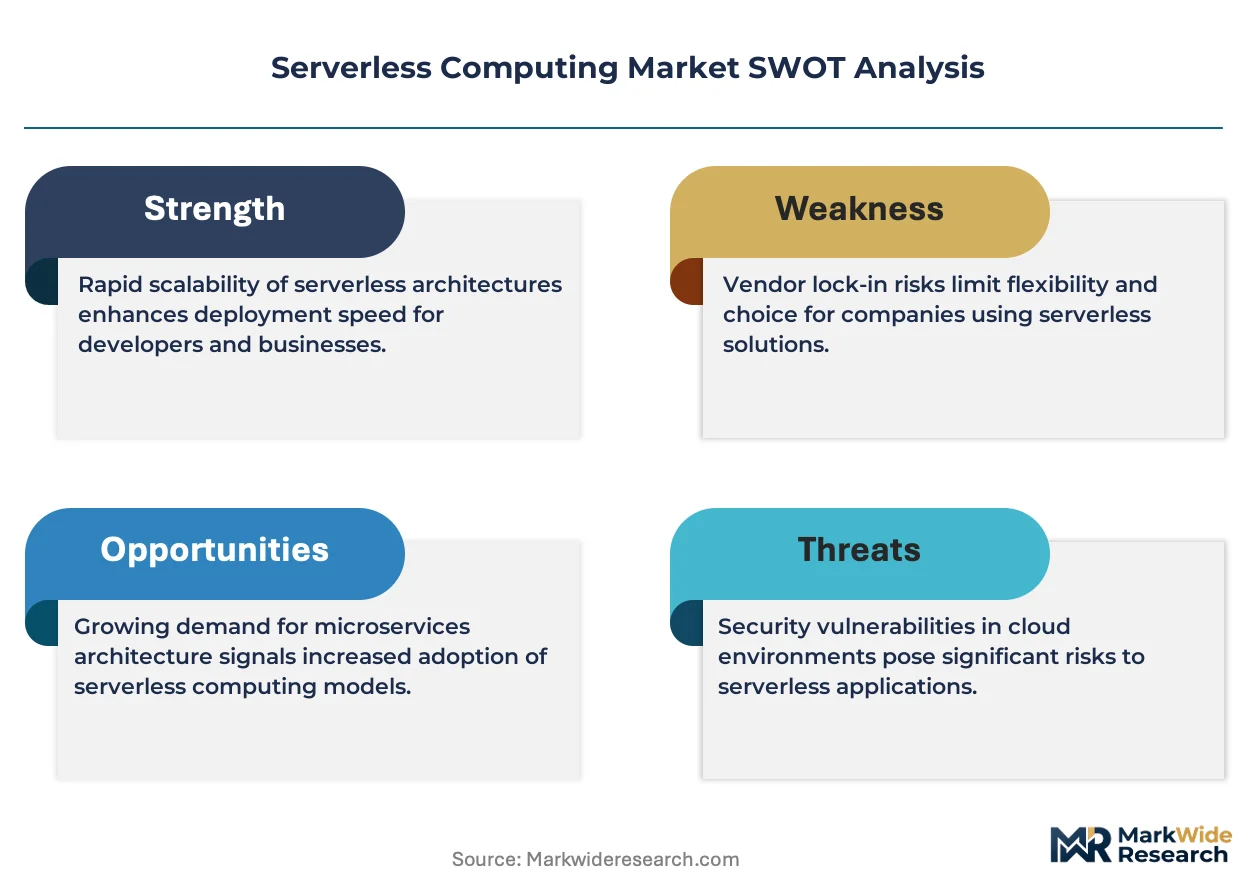
Container-to-function interoperability standards are collapsing migration friction between Kubernetes and serverless runtimes, forcing hyperscalers to compete on execution-environment specialization rather than proprietary lock-in.
Growth Catalysts
- HIPAA business-associate requirements:Healthcare enterprises are configuring serverless audit trails and encryption standards to satisfy federal privacy mandates, expanding compliant workload migration.
- Financial services transaction processing:Real-time payment networks and fraud detection systems are driving millisecond-billing function deployment across retail and investment banking.
- United States data center density:Hyperscaler infrastructure concentration in Northern Virginia, Oregon, and Ohio is compressing latency for event-driven compute at enterprise scale.
Market Restraints
- Cold-start latency thresholds:Ephemeral container initialization delays persist for Java and .NET runtimes, limiting serverless viability for sub-100-millisecond response requirements.
- Hyperscaler concentration risk:AWS Lambda, Azure Functions, and Google Cloud Functions control dominant execution-environment market positions, creating single-provider dependency for critical workloads.
- GDPR data-residency compliance costs:European enterprises face elevated engineering overhead to maintain function-state isolation across sovereign cloud regions.
Strategic Opportunities
- India's PLI scheme for cloud infrastructure:Domestic data center investments are creating localized serverless capacity for financial services and e-commerce platforms requiring in-country data processing.
- Knative-based container portability:Open-source abstraction layers are enabling workload migration between cloud providers without function-rewrite penalties.
- EU AI Act automated decision documentation:Risk-classification frameworks are mandating function-as-a-service pipeline auditability, creating compliance-tooling demand.
Industry Challenges
- Distributed systems engineering scarcity:Organizations struggle to source talent proficient in event-driven architecture patterns, observability instrumentation, and chaos engineering for ephemeral compute.
- Legacy mainframe integration complexity:Financial institutions face protracted API gateway configuration to bridge COBOL transaction systems with serverless microservices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serverless Computing Market |
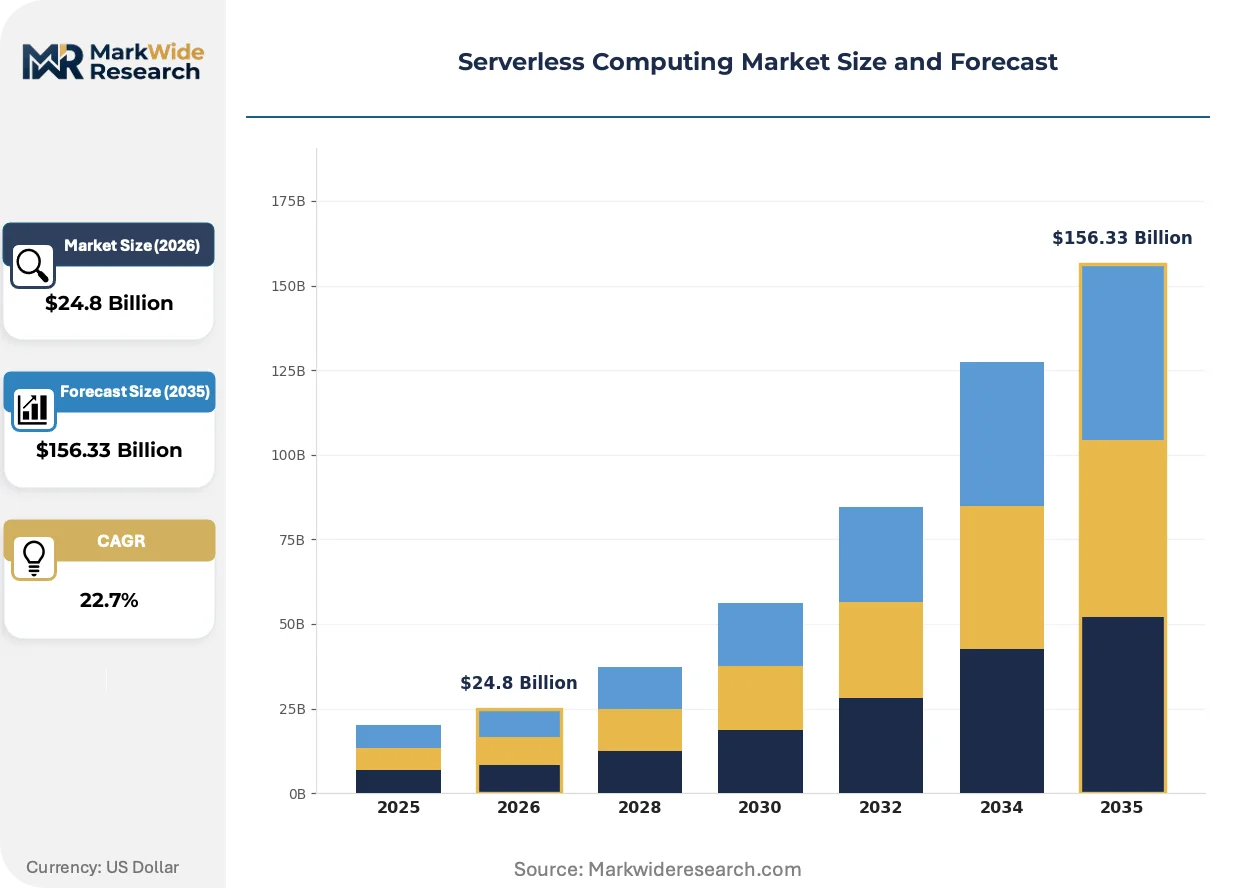
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $156.33 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Application: Web Applications, Real-Time Data Processing, Mobile Backends, IoT Backends, Chatbots Industry Vertical: Information Technology, Telecommunications, Media & Entertainment, Education, Manufacturing Pricing Model: Pay-As-You-Go, Subscription-Based, Consumption-Based, Tiered Pricing |
| Companies Covered | Alibaba Cloud, IBM, Amazon Web Services (AWS), AWS Lambda, Tencent Cloud, Microsoft, Oracle, IBM Cloud, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serverless Computing Market Strategic Shifts & Innovations
Event-driven architectures are displacing batch processing across streaming analytics pipelines, forcing infrastructure vendors to optimize for sub-second billing granularity and stateful function persistence.
WebAssembly (Wasm) runtimes are expanding into edge serverless deployments by enabling near-native execution speed in resource-constrained environments. Manufacturing and logistics operators are adopting Wasm-based functions for shop-floor telemetry processing at 10-50 millisecond latencies. This expansion is compressing the performance gap between edge devices and centralized cloud execution, enabling real-time anomaly detection without round-trip latency penalties.
The EU AI Act's risk-classification framework is mandating automated decision pathway documentation within function-as-a-service pipelines. Healthcare and financial services adopters must now embed explainability logging and human-in-the-loop checkpoints at the function orchestration layer. German automotive manufacturers and French insurance platforms are reconfiguring their serverless CI/CD pipelines to capture model-version provenance and inference-audit trails before production deployment.
Consumption-based billing models are displacing reserved-instance commitments among mid-market enterprises with unpredictable workload patterns. Retail and media companies are unbundling long-term cloud contracts in favor of per-invocation pricing that aligns infrastructure costs with transaction volume volatility. This pattern is most visible in the United States, where seasonal e-commerce spikes and streaming-event surges reward elastic capacity over provisioned infrastructure.
Serverless Computing Market Segmentation
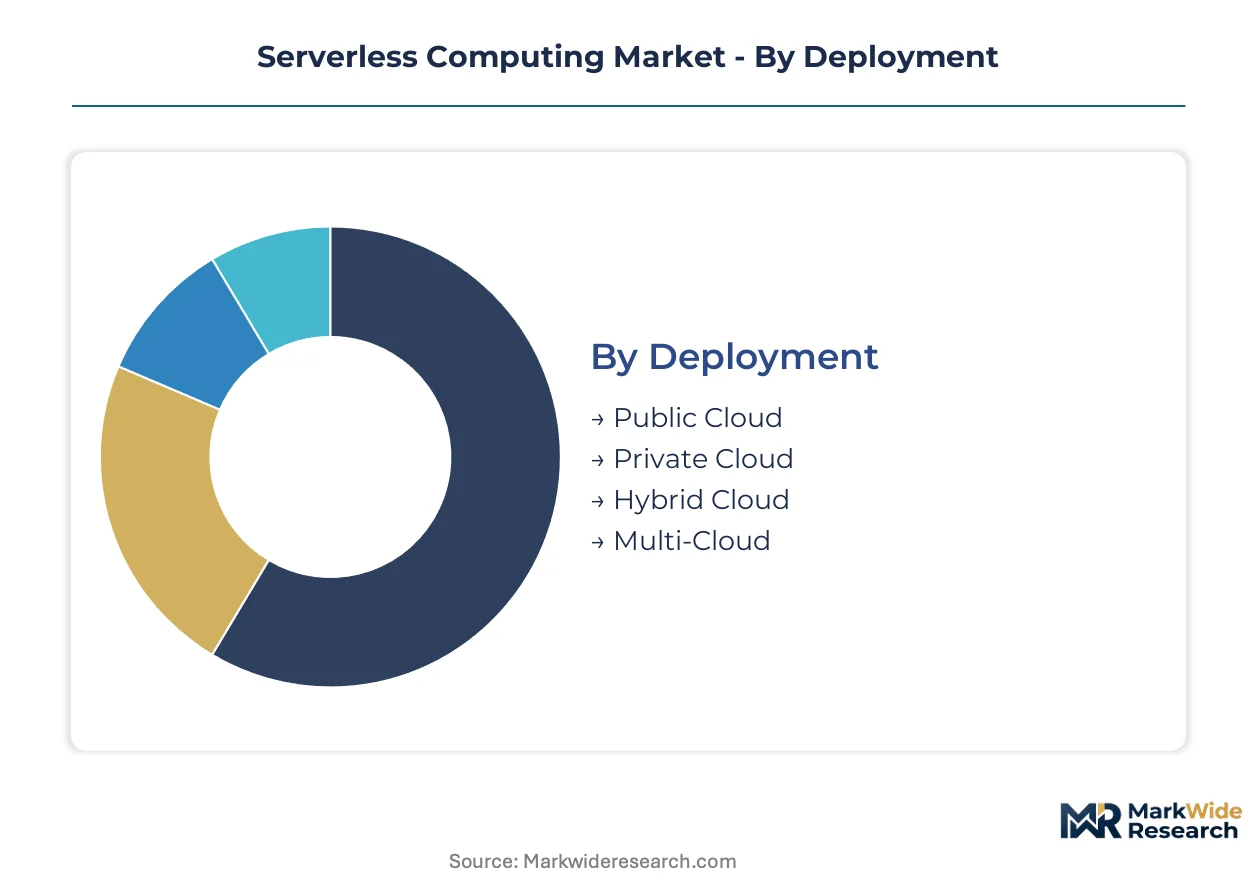
Serverless computing segments reflect divergent infrastructure control philosophies and billing economics. Deployment models determine sovereignty-versus-agility tradeoffs, while application types reveal where event-driven architectures displace persistent compute. Pricing structures separate hyperscaler-native adopters from enterprises seeking cost predictability.
Deployment:
Standardized hyperscaler environments compete with customizable sovereignty configurations across this spectrum.
- Public Cloud:Ephemeral functions execute on shared hyperscaler infrastructure with millisecond billing granularity. Financial services firms in the United States deploy Lambda and Azure Functions for real-time fraud detection, trading latency tolerance against operational overhead elimination.
- Hybrid Cloud:Workload orchestration spans on-premises Kubernetes and public serverless runtimes through unified control planes. German automotive manufacturers leverage this model to retain powertrain telemetry within factory boundaries while bursting analytics to cloud functions.
- Private Cloud:Function-as-a-service platforms operate within single-tenant data centers governed by enterprise security policies. Healthcare systems subject to HIPAA business-associate requirements favor this deployment for patient-data processing pipelines.
- Multi-Cloud:Container-to-function interoperability standards enable workload portability across AWS, Azure, and Google Cloud without vendor lock-in. European enterprises navigating GDPR data-residency mandates adopt this approach to distribute functions across sovereign regions.
Most installed capacity flows through Public Cloud. Expansion is steepest in Hybrid Cloud.
Application:
Volume concentration shifts from request-response web workloads toward streaming data pipelines.
- Real-Time Data Processing:Event-triggered functions ingest, transform, and route streaming telemetry from connected devices and financial market feeds. Retail banks in the United States deploy sub-second billing functions for payment authorization and anomaly detection at transaction scale.
- Web Applications:Stateless API backends serve dynamic content through auto-scaling function pools triggered by HTTP requests. Media companies replace provisioned server fleets with consumption-based compute for unpredictable traffic spikes.
- IoT Backends:Device telemetry ingestion and command dispatch operate through message-queue-triggered functions. Manufacturing operators in Japan process shop-floor sensor streams at edge-adjacent latencies.
- Mobile Backends:User authentication, push notification routing, and data synchronization execute as ephemeral functions. Telecommunications providers leverage this pattern for subscriber-facing application infrastructure.
- Chatbots:Natural language processing and conversational state management deploy as orchestrated function sequences. Customer service platforms integrate serverless dialogue handling with existing CRM systems.
Transaction volume concentrates in Real-Time Data Processing. Developer activity is expanding most quickly in IoT Backends.
Industry Vertical:
Margin profiles diverge between regulated data-sovereignty sectors and latency-sensitive digital-native industries.
- Information Technology:Software vendors internalize serverless architectures for SaaS platform engineering and DevOps automation. Cloud-native enterprises in the United States drive consumption through CI/CD pipeline modernization and microservice decomposition.
- Telecommunications:Network function virtualization and subscriber data management migrate to event-driven compute. European operators reconfigure billing and provisioning systems for 5G service agility.
- Manufacturing:Predictive maintenance algorithms and quality-control vision systems deploy at production-line edge locations. German industrial firms integrate serverless inference with existing SCADA infrastructure.
- Media & Entertainment:Content personalization, transcoding pipelines, and real-time audience analytics scale elastically with broadcast events. Streaming platforms favor consumption billing over reserved capacity for unpredictable viewership patterns.
- Education:Learning management systems and assessment platforms handle enrollment surges through auto-scaling functions. Institutional procurement prioritizes cost predictability over millisecond-latency optimization.
Revenue concentration sits with Information Technology. Deployment velocity is climbing the fastest in Manufacturing.
Pricing Model:
Enterprise procurement preferences separate predictable-commitment buyers from variable-workload optimizers.
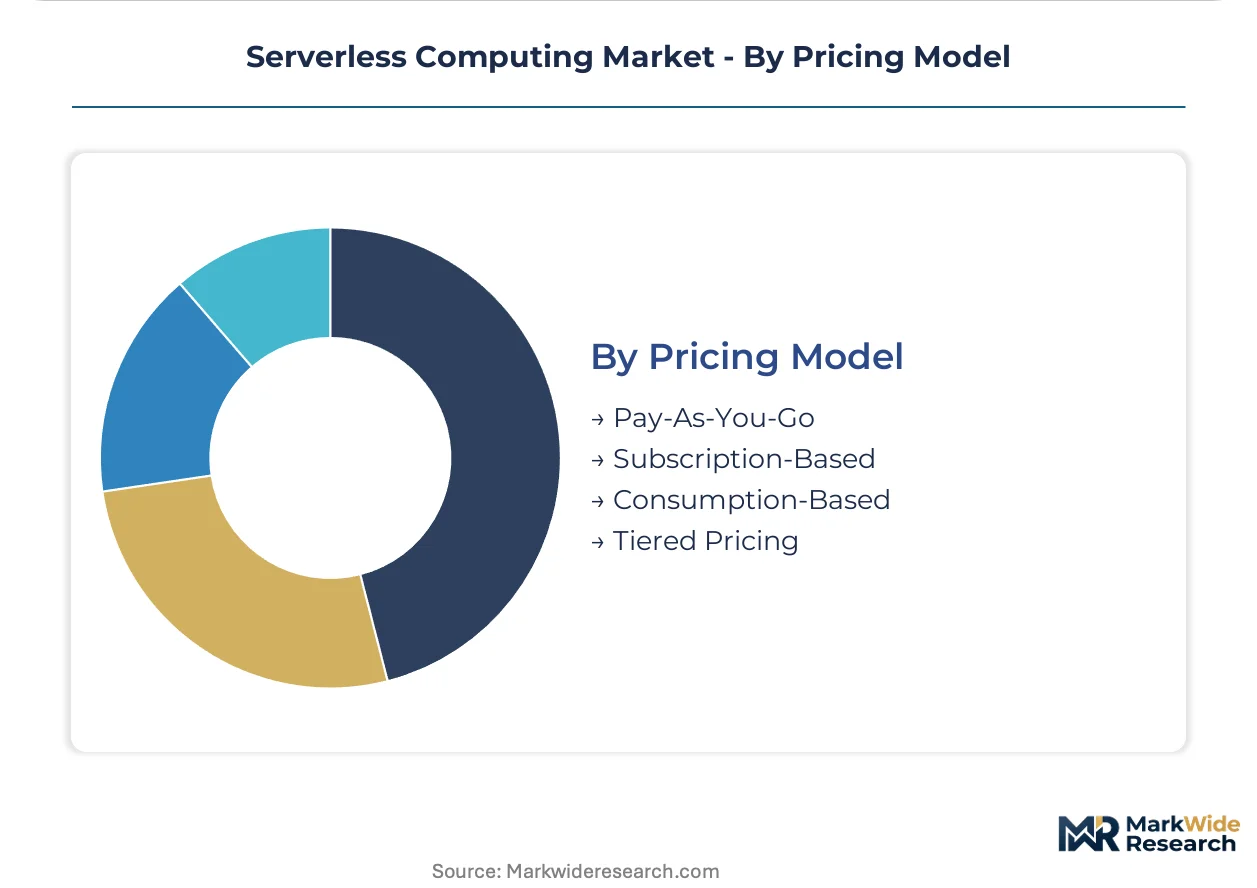
- Pay-As-You-Go:Per-invocation billing aligns infrastructure expenditure with actual compute consumption. United States e-commerce platforms favor this model for seasonal transaction volatility.
- Consumption-Based:Aggregated usage tiers with volume discounts accommodate mid-market enterprises with moderate predictability. Media companies balance cost control against traffic spike tolerance.
- Subscription-Based:Fixed monthly fees for defined function concurrency limits suit organizations with steady-state workloads. Healthcare systems prioritize budget certainty over marginal cost optimization.
- Tiered Pricing:Performance-grade differentiation separates standard from premium execution environments with guaranteed cold-start latency. Financial services firms pay premiums for sub-100-millisecond response commitments.
Contract value concentrates in Pay-As-You-Go. Enterprise migration is gaining share fastest in Consumption-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native developer density in Northern Virginia, Seattle, and San Francisco anchors the United States' serverless workforce concentration. Germany's industrial software engineering clusters and India's SaaS talent pipelines represent complementary talent reservoirs driving regional adoption patterns.
United States
Financial services firms in New York and Chicago deploy Lambda and Azure Functions for real-time fraud detection and payment authorization. HIPAA business-associate requirements shape healthcare serverless configurations at Cleveland Clinic and Mayo Clinic. Hyperscaler data center density in Northern Virginia compresses latency for event-driven compute serving enterprise workloads.
Germany
Automotive manufacturers in Stuttgart and Munich reconfigure serverless CI/CD pipelines to satisfy EU AI Act automated decision documentation mandates. GDPR data-residency compliance costs elevate engineering overhead for function-state isolation across sovereign cloud regions. Industrial software clusters in Baden-Württemberg integrate serverless inference with existing SCADA infrastructure.
India
Domestic fintech platforms in Mumbai and Bangalore leverage the PLI scheme for cloud infrastructure to localize serverless capacity. RBI data localization requirements drive in-country function deployment for payment processing. SaaS engineering talent in Hyderabad and Pune accelerates consumption-based billing adoption among mid-market enterprises.
Japan
Manufacturing operators in Nagoya and Osaka process shop-floor sensor streams through message-queue-triggered functions at edge-adjacent latencies. METI industrial digitalization initiatives subsidize serverless migration for predictive maintenance algorithms. Telecommunications providers in Tokyo reconfigure billing systems for 5G service agility through event-driven compute.
United Kingdom
Media companies in London unbundle long-term cloud contracts for per-invocation pricing aligned with streaming-event surges. Financial Conduct Authority operational resilience requirements shape serverless audit trail configurations for investment banks. Fintech clusters in Manchester and Edinburgh adopt Knative-based portability layers to mitigate hyperscaler concentration risk.
Serverless Computing Market Key Industry Players
The competitive structure tilts toward hyperscaler dominance with execution-environment specialization as the primary differentiation vector. Three players control dominant market positions in function-as-a-service runtimes, creating tiered access based on cold-start latency guarantees and sovereign region coverage. Strategic archetypes separate infrastructure-native hyperscalers, enterprise-legacy integrators, and open-source portability specialists. Competitive moves concentrate on container-to-function interoperability standards and regional data center expansion to satisfy data-residency mandates.
Among hyperscaler-native providers, Amazon Web Services, Microsoft, and Google Cloud exemplify the infrastructure-dominant archetype through specialized execution environments and millisecond-billing granularity. IBM and Oracle occupy positions bridging enterprise legacy systems with serverless abstraction layers. Alibaba Cloud and Tencent Cloud represent geography-anchored challengers leveraging domestic data center density and regulatory alignment in Asia-Pacific markets. Open-source portability momentum through Knative-based standards is compressing differentiation space, forcing incumbents to compete on execution performance rather than proprietary lock-in.
| Leading Market Players |
|---|
| Alibaba Cloud |
| IBM |
| Amazon Web Services (AWS) |
| AWS Lambda |
| Tencent Cloud |
| Microsoft |
| Oracle |
| IBM Cloud |
| Google Cloud |
| Others |
Cost & Logistics Intelligence
Hyperscaler data center energy costs in Northern Virginia and Oregon cascade through millisecond-billing tiers, compressing margins for standard execution environments while premium cold-start guarantees capture price inelastic demand from financial services firms.
Pricing Analysis
Bundled compute-storage-networking packages dominate enterprise procurement, though unbundled function-as-a-service pricing gains traction among developer-centric adopters. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed sub-100-millisecond response tiers from best-effort execution pools. Price differentiation hinges on cold-start latency certification and sovereign region coverage breadth. Pricing pressure stems from Knative-based portability standards that collapse switching costs. Healthcare systems exhibit lowest price sensitivity due to HIPAA compliance requirements, while retail e-commerce platforms drive hardest per-invocation rate negotiations.
Supply Chain Analysis
Reverse-logistics flows for decommissioned server hardware remain underdeveloped, with hyperscalers prioritizing component reuse over third-party refurbishment channels. Supply concentrates in the United States, Ireland, and Singapore for hyperscale data center infrastructure. Silicon fabrication draws from Taiwan and South Korea, while rare earth elements for magnetic components rest on Chinese processing capacity. Single-source vulnerability in advanced node semiconductors threatens execution environment scaling. Distribution runs through direct hyperscaler procurement with minimal intermediary channel presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serverless computing functions as a stable compounder, with event-driven architecture migration providing durable expansion across regulated and digital-native sectors alike.
For Market Incumbents: Deepen execution environment specialization around sub-100-millisecond cold-start guarantees to defend against Knative-based portability threats. Expand sovereign region coverage to capture GDPR and RBI data-localization mandates. Invest in vertical integration of chip design for custom inference accelerators that lock in performance-tier differentiation.
For New Entrants and Emerging Players: Launch via consumption-based billing models targeting mid-market manufacturing firms in Germany and Japan with unpredictable predictive maintenance workloads. Penetrate edge serverless deployments for shop-floor telemetry processing where hyperscaler latency commitments falter. Pursue WebAssembly runtime specialization for resource-constrained industrial environments.
For Investors and Strategic Acquirers: Consolidation pressure builds where open-source portability standards commoditize execution environments and compress standalone function-as-a-service margins. Long-term viability favors providers with embedded platform ecosystems or vertical-specific compliance tooling. Target acquisition profiles emphasize EU AI Act audit-trail automation capabilities. Monitor container-to-function interoperability standard adoption rates as inflection indicator for pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Execution Environment Specialization | AWS Lambda's millisecond-billing granularity anchors competitive positioning in financial services fraud detection. |
| Sovereign Region Expansion | Microsoft's Azure Functions deployment across German and Indian data centers satisfies RBI and GDPR localization mandates. |
| Open-Source Portability Investment | Google Cloud's Knative-based abstraction layer collapses migration friction and pressures proprietary lock-in strategies. |
| Edge Serverless Deployment | WebAssembly runtime expansion into Japanese manufacturing facilities enables 10-50 millisecond shop-floor telemetry processing. |
| Compliance Tooling Integration | EU AI Act risk-classification frameworks mandate automated decision documentation within function-as-a-service pipelines. |
Research Approach
Coverage spans the United States, Germany, India, Japan, and the United Kingdom, with primary inputs from each market informing demand-side validation. Platform engineering directors, cloud procurement officers, regulatory compliance leads, and DevOps specialists contributed structured interviews. Secondary sources include hyperscaler capex disclosures, SEC filings, EU regulatory filings, and national data center development registries. Bottom-up function invocation volume estimates triangulate against top-down infrastructure capacity deployments.
Granularity-level modeling distinguishes public, hybrid, private, and multi-cloud deployment configurations across the projection horizon. Segmentation dimensions include deployment sovereignty requirements, application latency sensitivity, vertical regulatory exposure, and pricing model preference. CAGRs derive from installed base expansion rates and consumption intensity per enterprise workload. Forecast inputs incorporate FDA software-as-a-medical-device guidance evolution and RBI data localization enforcement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt data-residency mandate expansion or cold-start latency breakthroughs. Forecasts reflect assumptions regarding hyperscaler capacity expansion schedules and interoperability standard adoption curves. Practitioners should monitor EU AI Act implementation timelines and WebAssembly runtime maturation for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud-Based Workload Scheduling Software Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Web Scale IT Market