
 Universal Process Control Market | 2026-2036
Universal Process Control Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Process Control Market Analytics
Sil-rated safety certification tiers is collapsing the gap between legacy process control and modern predictive architectures. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor large-scale refining deployments. Honeywell International Inc. competes through Experion distributed platforms that sustain high-availability chemical operations. Yokogawa Electric Corp. specializes in precision batch control for pharmaceutical manufacturers.
Universal process control encompasses hardware and software systems that regulate continuous or batch industrial operations through feedback loops, typically managing variables within tolerance bands of 0.1% to 0.5%. These systems integrate sensors, controllers, and actuators to maintain temperature, pressure, flow, and level parameters across hazardous and non-hazardous environments. Controllers and sensors capture the dominant share of product-type revenue due to replacement cycles in mature installations. Distributed Control Systems lead technology deployment in large-process industries, while PLC-based architectures gain ground in modular manufacturing automation. Oil and gas end users drive the largest absolute spend, though pharmaceuticals generates superior margins because of validation-intensive requirements.
FDA 21 CFR Part 11 and EU MDR impose traceability and electronic record standards that shape control-system architecture in regulated industries. EPA emissions monitoring rules and EU F-Gas Regulation force leak-detection integration into process control loops. OSHA process safety management mandates drive upgrade cycles in US chemical facilities. Stakeholders must weigh the capital cost of retrofitting legacy DCS platforms against the operational risk of deferred compliance investments.
Market Dynamics
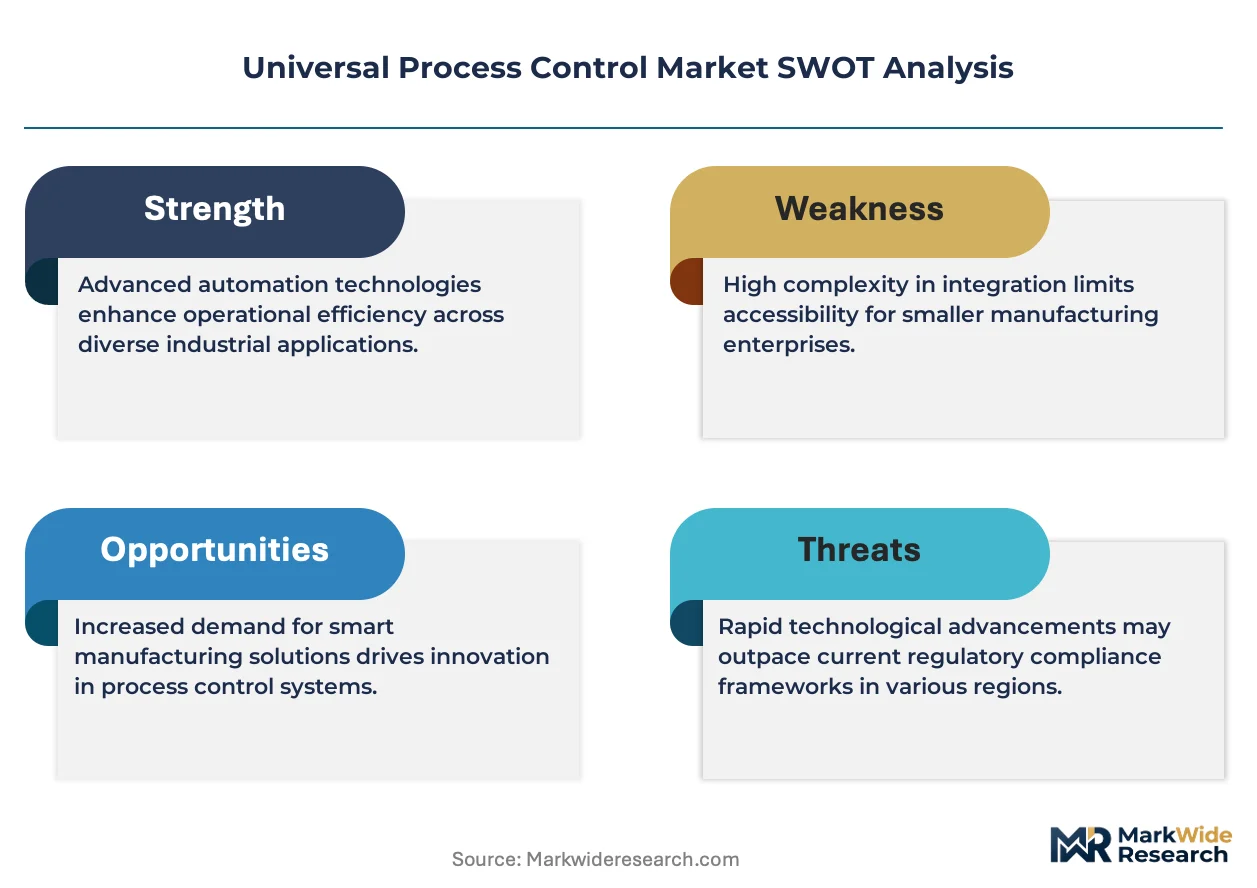
Digital twin architectures are compressing the feedback loop between physical process control and predictive optimization, forcing incumbents to reengineer legacy DCS platforms or cede share to software-native entrants.
Growth Catalysts
- EU F-Gas Regulation:Mandatory leak-detection integration into refrigeration and chemical process loops drives replacement of pneumatic controllers with electronic alternatives across German and French industrial clusters.
- Pharmaceutical validation intensity:FDA 21 CFR Part 11 traceability requirements expand addressable hardware spend per installation as batch records demand redundant sensor arrays and encrypted data historians.
- Modular manufacturing adoption:Specialty chemical producers in China deploy PLC-based skid-mounted units that bypass traditional DCS procurement cycles, accelerating controller refresh rates.
Market Restraints
- Semiconductor input volatility:Controller ASIC and sensor MEMS fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction and foundry allocation constraints.
- Legacy protocol entrenchment:Proprietary fieldbus standards from 1990s DCS installations create switching costs that extend replacement cycles beyond technical obsolescence.
- Substitute automation architectures:Edge AI inference engines at the sensor level threaten to collapse discrete controller hardware into consolidated compute nodes.
Strategic Opportunities
- India PLI scheme for specialty chemicals:Greenfield capacity under production-linked incentives lacks installed DCS base, creating open competitive field for integrated control vendors.
- Carbon capture integration:MEE dual carbon compliance mandates in China require new pressure-loop control architectures for amine scrubbing and compression trains.
- 5G-TSN convergence:Time-sensitive networking over private wireless enables wireless sensor meshing in hazardous zones previously requiring hardwired intrinsic safety barriers.
Industry Challenges
- Functional safety engineer scarcity:TÜV-certified SIL design capacity concentrates in Germany and the United States, constraining project velocity for complex pharmaceutical installations.
- Retrofit integration complexity:Brownfield DCS migrations demand simultaneous maintenance of legacy I/O mapping and modern OPC-UA data architectures, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Process Control Market |
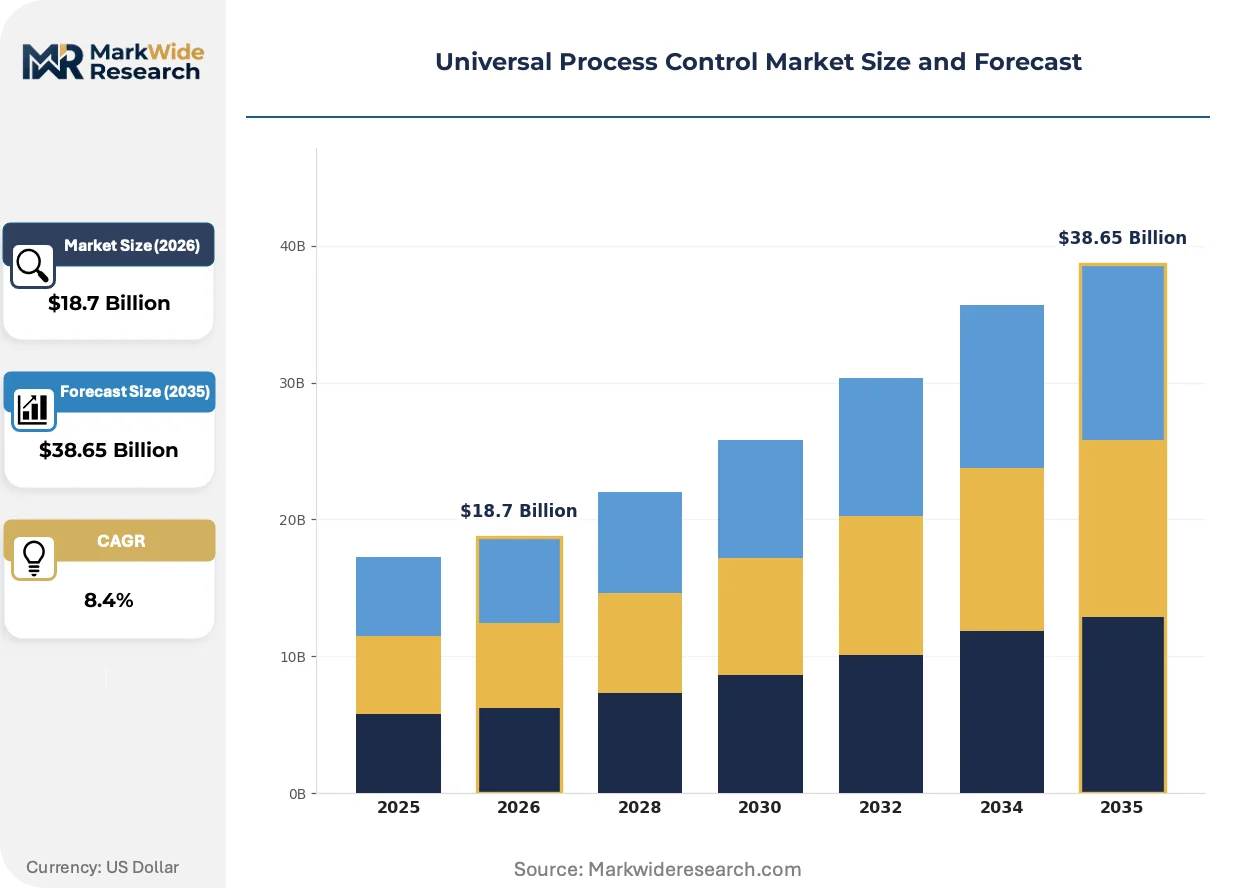
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Sensors, Actuators, Software Technology: PID Control, Distributed Control Systems, PLC, SCADA Application: Manufacturing Automation, Process Optimization, Energy Management, Quality Control End User: Oil & Gas, Chemicals, Pharmaceuticals, Food & Beverage |
| Companies Covered | ABB, Emerson Electric Co., Honeywell International Inc., Schneider Electric, Siemens, Yokogawa Electric Corp., Bürkert Fluid Control Systems, JUMO, Omega Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Process Control Market Evolving Landscape
Control system intelligence is migrating from centralized DCS cabinets toward distributed edge nodes, redefining hardware boundaries and vendor competitive moats.
Edge-native control runtimes are fragmenting the traditional DCS software stack. These lightweight execution environments deploy directly on IP-rated field devices, executing PID loops without upstream controller dependency. Oil and gas midstream operators in the Permian Basin pilot these architectures to reduce marshalling cabinet footprint. The technology is fragmenting hardware procurement into separately sourced compute, I/O, and networking tiers.
REACH authorization timelines for per- and polyfluoroalkyl substances are compressing seal and gasket material options in European process installations. Chemical-resistant elastomer shortages force requalification of valve actuator specifications, extending engineering procurement cycles. Pharmaceutical manufacturers in Ireland and Switzerland accelerate fluoropolymer inventory builds ahead of sunset dates.
Lifecycle service contracting is displacing transactional hardware procurement in large-process industries. Refining operators in the United States negotiate availability-guaranteed performance contracts that bundle controller replacement, calibration labor, and spare parts logistics into fixed annual fees. This shift transfers operational risk to vendors while compressing upfront capital recognition into recurring revenue streams.
Universal Process Control Market Segmentation
Segmentation in universal process control reveals how procurement authority splits between capital-project engineering teams and operational technology managers. Hardware-software bundling decisions, regulatory validation requirements, and brownfield retrofit constraints all vary sharply across these dimensions.
Product Type:
Controllers and sensors move through direct OEM channels to large-process industries, while actuators and software increasingly route through system integrators serving modular manufacturing.
- Controllers:These units execute PID algorithms and advanced regulatory control with cycle times measured in milliseconds. Demand concentrates in German chemical clusters where EU F-Gas Regulation mandates electronic controller replacement of pneumatic legacy systems. TÜV-certified SIL configurations command price premiums.
- Sensors:Temperature, pressure, flow, and level transmitters form the measurement layer with tolerance bands of 0.1% to 0.5%. Pharmaceutical manufacturers in Ireland drive redundant sensor array deployments to satisfy FDA 21 CFR Part 11 traceability mandates.
- Actuators:Valve positioners and motor drives translate control signals into physical action. REACH authorization timelines for per- and polyfluoroalkyl substances compress seal material options in European installations.
- Software:Configuration, historian, and optimization platforms execute on industrial servers or edge nodes. Lifecycle service contracting displaces perpetual licenses in US refining.
Controllers dominate installed base. Sensors are where expansion concentrates.
Technology:
Cost tiering separates monolithic DCS platforms from modular PLC architectures, with hybrid SCADA deployments bridging brownfield gaps.
- PID Control:Foundational proportional-integral-derivative algorithms underpin all higher-order control strategies. Single-loop and cascade configurations persist across mature installations in US Gulf Coast chemical facilities.
- Distributed Control Systems:Centralized architectures with redundant controllers and dedicated I/O cabinets serve continuous processes. Large refining complexes in China deploy these for amine scrubbing pressure-loop control under MEE dual carbon mandates.
- PLC:Programmable logic controllers with modular I/O suit batch and discrete manufacturing. Specialty chemical producers in India deploy PLC-based skid-mounted units under PLI scheme greenfield capacity.
- SCADA:Supervisory layers aggregate data from heterogeneous subsystems for visualization and historization. Midstream oil and gas operators in the Permian Basin pilot edge-native SCADA to reduce marshalling footprint.
Distributed Control Systems anchor large-process revenue. PLC is climbing the fastest.
Application:
Volume concentration follows end-user capital intensity, with process optimization and energy management commanding premium pricing in carbon-constrained jurisdictions.
- Manufacturing Automation:Discrete and batch sequencing for assembly and packaging lines. Food and beverage facilities in Switzerland deploy these for hygienic zone control.
- Process Optimization:Advanced regulatory control and real-time optimization of continuous units. Carbon capture integration in China requires new control architectures for compression trains.
- Energy Management:Steam, electricity, and fuel optimization across multi-unit sites. EU Green Deal emissions targets drive adoption in German industrial clusters.
- Quality Control:In-process analytical feedback for batch release decisions. Pharmaceutical validation intensity expands hardware spend per installation in FDA-regulated facilities.
Manufacturing Automation holds broadest unit volume. Process Optimization is gaining share fastest.
End User:
Margin structure inverts between oil and gas volume leadership and pharmaceutical validation premiums.
- Oil & Gas:Upstream, midstream, and downstream operations with hazardous area classifications. US refining operators negotiate availability-guaranteed performance contracts bundling hardware and services.
- Chemicals:Continuous and batch production of commodity and specialty materials. French industrial clusters replace pneumatic controllers under EU F-Gas leak-detection mandates.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU MDR impose traceability and electronic record standards. Functional safety engineer scarcity in Germany and the United States constrains project velocity.
- Food & Beverage:Hygienic process control with CIP/SIP validation requirements. Irish and Swiss manufacturers accelerate fluoropolymer inventory builds.
Oil & Gas dominates absolute spend. Pharmaceuticals is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller and sensor fabrication clusters in Taiwan and South Korea expose lead times to foundry allocation constraints. Demand concentrates in Germany, the United States, and China as industrial automation investments accelerate. Regulatory divergence across jurisdictions shapes procurement specifications and validation requirements.
United States
OSHA process safety management mandates drive upgrade cycles in Gulf Coast chemical facilities. EPA emissions monitoring rules force leak-detection integration into control loops. Refining operators in Texas negotiate availability-guaranteed performance contracts bundling hardware and services.
Germany
EU F-Gas Regulation mandates electronic controller replacement of pneumatic legacy systems in chemical clusters. TÜV-certified SIL configurations command price premiums for safety-critical applications. The Rhine-Ruhr industrial corridor hosts concentrated demand for validated pharmaceutical control systems.
China
MEE dual carbon compliance mandates require new pressure-loop control architectures for amine scrubbing and compression trains. Specialty chemical producers deploy PLC-based skid-mounted units that bypass traditional DCS procurement cycles. Yangtze River Delta manufacturing hubs accelerate controller refresh rates.
India
PLI scheme greenfield capacity for specialty chemicals lacks installed DCS base, creating open competitive field for integrated control vendors. Modular manufacturing adoption accelerates among domestic chemical producers. Gujarat and Maharashtra industrial corridors concentrate greenfield automation investment.
Switzerland
Swissmedic validation requirements and EU MDR traceability standards expand hardware spend per pharmaceutical installation. REACH authorization timelines for fluoropolymer substances compress seal material options. Basel-area manufacturers accelerate inventory builds ahead of sunset dates.
Universal Process Control Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the universal process control market. The installed base concentrates around diversified industrial automation conglomerates with decades of field-proven DCS architectures. Three archetypes dominate: full-stack platform vendors, specialized safety-system integrators, and modular component suppliers. Competitive moves center on lifecycle service contracting displacing transactional hardware sales and edge-native runtime development fragmenting traditional software stacks.
Among diversified platform vendors, Emerson Electric Co., Honeywell International Inc., and Yokogawa Electric Corp. exemplify the full-stack archetype with integrated hardware-software portfolios spanning sensing through optimization layers. These entities anchor large-process industry deployments through availability-guaranteed performance contracts. Specialists in precision batch control and safety-certified architectures occupy adjacent competitive positions, while regional component fabricators compete on modular skid integration for greenfield chemical capacity.
| Leading Market Players |
|---|
| ABB |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Schneider Electric |
| Siemens |
| Yokogawa Electric Corp. |
| Bürkert Fluid Control Systems |
| JUMO |
| Omega Engineering |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation gates both supplier qualification and price differentiation simultaneously, as electronic controller certification requirements fragment vendors into TÜV-certified premium tiers versus uncertified economy alternatives. Pharmaceutical validation intensity under FDA 21 CFR Part 11 further stratifies procurement, with redundant sensor arrays and encrypted data historians commanding substantial hardware premiums over standard configurations.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across the universal process control market, separating validated pharmaceutical installations from standard industrial deployments. Three-tier pricing structure across premium, standard, and economy levels reflects SIL certification grade and after-sales service bundling. Cost compression in economy-tier pneumatic replacements intensifies because of foundry allocation constraints on controller ASICs. Specialty chemical producers in China exhibit highest price sensitivity, while pharmaceutical manufacturers in Ireland and Switzerland accept premium pricing for traceability compliance.
Supply Chain Analysis
Strategic stockpiling of fluoropolymer seals and gaskets dominates inventory strategy ahead of REACH authorization sunset dates, contrasting with just-in-time sensor procurement for standard industrial applications. Controller ASIC and sensor MEMS fabrication concentrates in Taiwan, South Korea, and Japan, drawing from silicon wafer and rare earth processing inputs. Single-source vulnerability in Taiwan foundry capacity exposes lead times to geopolitical friction. Distribution runs through direct OEM channels for large-process industries and system integrators for modular manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle service contracting expands faster than hardware transactional sales, as availability-guaranteed performance contracts transfer operational risk to vendors while compressing upfront capital recognition into recurring revenue streams.
For Market Incumbents: Compound defensive positioning through backward integration into sensor MEMS fabrication and captive supply of TÜV-certified SIL design capacity in Germany and the United States. Edge AI inference engines at the sensor level threaten to collapse discrete controller hardware into consolidated compute nodes, demanding rapid reengineering of legacy DCS platforms or ceding share to software-native entrants. Prioritize certification investment in pharmaceutical traceability architectures to defend margin position against modular PLC vendors. For New Entrants and Emerging Players: Lead with greenfield DCS deployment opportunities in India's PLI scheme specialty chemical capacity, where absence of installed base creates open competitive field. Target PLC-based skid-mounted integration for modular manufacturing adoption among domestic chemical producers in Gujarat and Maharashtra industrial corridors. Pursue system integrator partnerships as primary go-to-market angle to bypass entrenched direct OEM relationships. For Investors and Strategic Acquirers: MEE dual carbon compliance mandates reshape the acquisition landscape, as pressure-loop control architecture demand for amine scrubbing and compression trains creates specialized vendor targets. Five-to-ten year viability favors safety-certified architecture specialists with TÜV SIL design capacity and pharmaceutical validation expertise over commodity controller fabricators. Watch for functional safety engineer scarcity crossing critical thresholds as inflection indicator for deal timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contracting | Availability-guaranteed performance contracts bundle hardware replacement and calibration labor for US refining operators. |
| Edge-Native Control Runtime Development | Lightweight execution environments on IP-rated field devices reduce marshalling cabinet footprint in Permian Basin pilots. |
| Backward Integration into Sensor Fabrication | In-house MEMS production mitigates Taiwan foundry allocation constraints and geopolitical lead time exposure. |
| Pharmaceutical Validation Architecture Investment | Redundant sensor arrays and encrypted data historians satisfy FDA 21 CFR Part 11 traceability mandates in Irish installations. |
| 5G-TSN Convergence Partnership | Time-sensitive networking over private wireless enables wireless sensor meshing in hazardous zones previously requiring hardwired barriers. |
Research Methodology
A spread of perspectives from plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and regulatory submission databases. Bottom-up project pipeline enumeration and top-down industrial automation spend estimates underwent iterative reconciliation.
Segmentation dimensions modeled include product type tier, technology architecture, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs derived from annualized growth rate calculations applied to segment-level baseline values. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance timelines and MEE dual carbon mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained industrial automation investment acceleration or stable geopolitical conditions in East Asian semiconductor fabrication would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and foundry capacity allocation. Revision becomes warranted when functional safety engineer scarcity or fluoropolymer material authorization delays cross thresholds affecting project velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Postal Automation System Market
Automation
Process Control Systems for Steel Market
Automation
Smart Home Automation Market
Automation
Global Business Process Automation Software Market
Automation
Global Door and Window Automation Market
Automation
Global Warehouse Execution System Market
Automation
Micro Fulfillment Market
Automation
US Workload Scheduling and Automation Market
Automation
Home Automation Market
Automation
Europe Laboratory Automation Market
Automation
Pneumatic Tube System Market
Automation
Global Smart Vending Machines Market
Automation
Cognitive Process Automation Market
Automation
North America Home Automation Systems Market
Automation
Laboratory Automation Market
Automation
Global Cloud Automation Market