
 Carpet and Rug Shampoo Market | 2026-2036
Carpet and Rug Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet and Rug Shampoo Market Analysis
China is reshaping supply dynamics through expanded aerosol and liquid concentrate manufacturing clusters in Guangdong and Zhejiang provinces. Bissell Inc. leverages its captive appliance ecosystem to bundle detergent sales with extraction equipment placements. The Clorox Company anchors North American retail shelf space through multi-channel distribution spanning mass merchants and e-commerce platforms. Rug Doctor competes in the rental-channel segment, sustaining recurring revenue through proprietary formula lock-in at supermarket and home improvement locations.
Carpet and rug shampoo comprises aqueous and solvent-based formulations engineered to emulsify particulate soils, neutralize pet and organic odors, and restore pile fiber resilience through pH-balanced surfactant systems. These products deploy enzymatic or oxygenated bleach chemistries to break protein and synthetic stains without compromising dye stability or backing adhesives. Liquid cleaners dominate residential replenishment cycles due to compatibility with both spray applicators and extraction machines, while concentrates capture institutional procurement where dilution economics govern total cost of ownership. Commercial cleaning applications outpace residential growth as facility management contracts consolidate vendor relationships and specify performance-based purchasing agreements.
The U.S. EPA regulates volatile organic compound content under 40 CFR 59, while the EU REACH framework restricts specific preservative and fragrance allergen concentrations in consumer cleaning products. California's Cleaning Product Right to Know Act mandates ingredient disclosure down to one percent concentration, compelling reformulation transparency across multi-state distribution networks. Stakeholders must monitor evolving state-level chemical restriction cascades and certification program proliferation to anticipate compliance cost trajectories and channel access requirements.
Market Dynamics
The U.S. EPA Safer Choice program is forcing surfactant reformulation across professional-grade cleaning chemistries, compressing time-to-market for legacy petroleum-based formulations while expanding biodegradable ingredient procurement.
Growth Catalysts
- REACH framework restrictions:The EU ECHA is tightening preservative and fragrance allergen limits, accelerating manufacturer migration toward plant-derived surfactant systems.
- Hospitality sector consolidation:Branded hotel chains are standardizing performance-based vendor contracts that specify extraction-compatible concentrated formulations.
- Enzymatic chemistry advances:Protein-targeting enzyme blends now neutralize pet odors without compromising carpet dye stability, expanding residential application scope.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and linear alkylbenzene price swings compress margin predictability for aqueous concentrate producers.
- Guangdong manufacturing concentration:Aerosol and liquid concentrate production clusters in southern China create single-source vulnerability for North American private-label brands.
- California Right to Know Act:Ingredient disclosure mandates down to one percent concentration impose reformulation costs that cascade through multi-state distribution networks.
Strategic Opportunities
- India commercial real estate expansion:Underpenetrated facility management markets in Bengaluru and Mumbai offer first-mover positioning for extraction-machine-compatible concentrates.
- E-commerce subscription channels:Direct-to-consumer replenishment models bypass mass-merchant slotting fees while capturing lifetime value data.
- ISO 14001 certification tailwinds:Corporate sustainability mandates are elevating certified green chemistry premiums in institutional procurement specifications.
Industry Challenges
- Formulation chemist scarcity:Expertise in pH-balanced surfactant systems compatible with diverse carpet backings is concentrating among a shrinking pool of specialized talent.
- Legacy extraction equipment incompatibility:New low-foam concentrates require recalibration of installed rental-machine fleets, creating adoption friction at supermarket and home improvement locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet and Rug Shampoo Market |
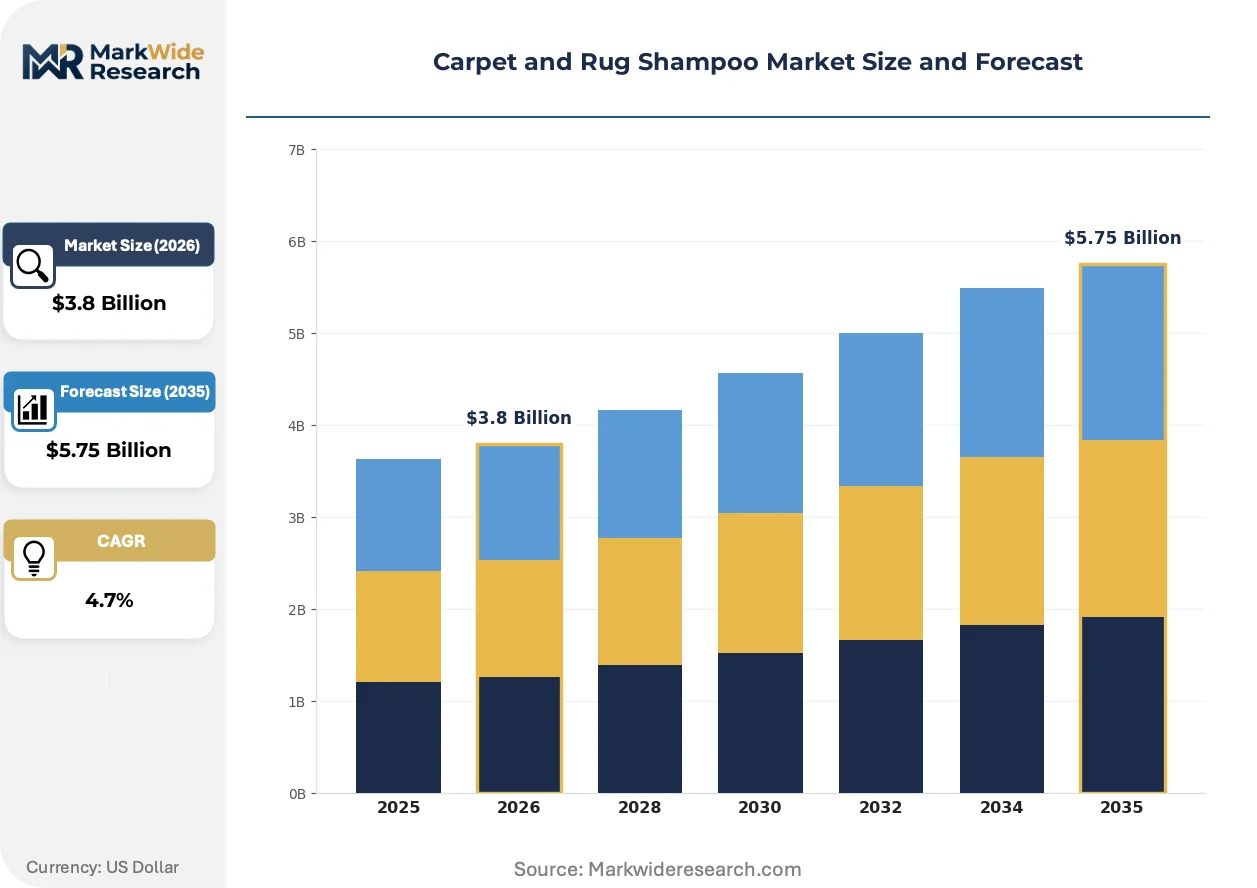
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Foam Cleaners, Powder Cleaners, Concentrates Application: Residential Cleaning, Commercial Cleaning, Automotive Cleaning, Industrial Cleaning Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Households, Cleaning Services, Hotels, Educational Institutions |
| Companies Covered | Bissell Inc., The Clorox Company, Rug Doctor, Reckitt Benckiser Group, Zep Inc., Bio-Kleen, Procter & Gamble, Sprayway Inc., Hoover, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet and Rug Shampoo Market Emerging Trajectories
Sensor-enabled dosing systems and connected appliance ecosystems are digitizing how cleaning chemistries are consumed, measured, and replenished across residential and commercial installations.
Smart dispensing technology is digitizing concentrate consumption through IoT-enabled extraction machines that automatically reorder formulations based on usage telemetry. Hospitality procurement teams are piloting these systems in flagged hotel properties to eliminate manual inventory management. The technology is digitizing traditional distributor relationships by shifting replenishment authority from facilities staff to algorithmic triggers.
The U.S. EPA 40 CFR 59 volatile organic compound limits are compressing solvent-based formulation shelf space while elevating water-based enzymatic alternatives in retail assortments. Manufacturers serving the California market must now reconcile federal VOC ceilings with state-level ingredient disclosure mandates that exceed federal stringency. Professional cleaning service contracts in the Sun Belt are specifying EPA Safer Choice-certified products to preempt liability exposure.
Facility management consolidation is compressing vendor lists and extending performance-guarantee clauses into multi-year agreements. Third-party service providers are displacing in-house janitorial teams at commercial office complexes and healthcare facilities. This concentration is most visible in Texas and Florida metropolitan areas where property management firms are standardizing chemistry specifications across entire portfolios.
Carpet and Rug Shampoo Market Segmentation
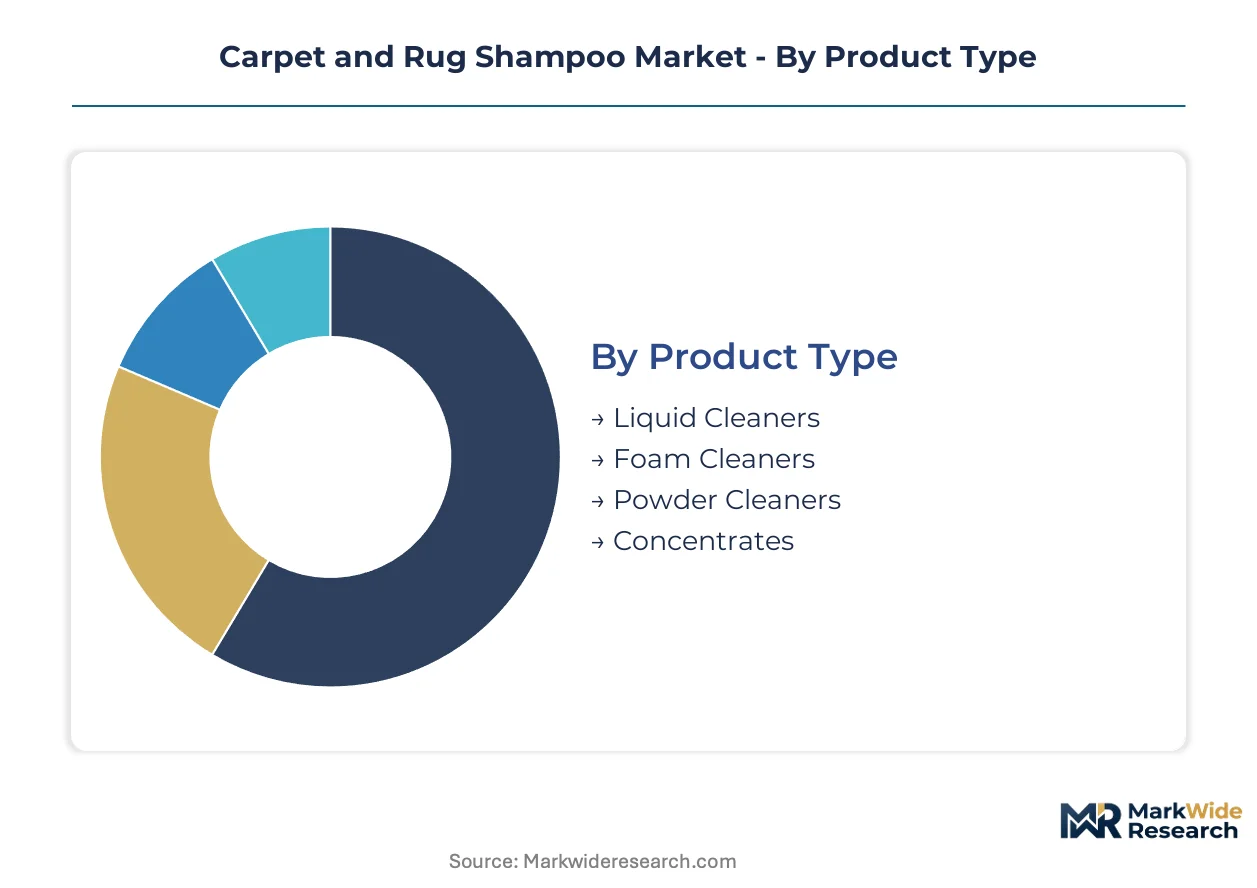
Segmentation in carpet and rug shampoo markets exposes divergent margin structures and replenishment cadences across formulation chemistries and procurement channels. Understanding these divides clarifies where formulation R&D investments concentrate versus where distribution partnerships yield recurring revenue.
Product Type:
After-sales service intensity varies sharply across these categories, with concentrates demanding technical training for dilution calibration while liquid cleaners require minimal post-purchase support.
- Liquid Cleaners:Aqueous surfactant systems with pre-calibrated pH buffers dominate residential replenishment due to compatibility with spray applicators and extraction machines. Demand concentrates in Sun Belt metropolitan areas where high carpet penetration drives repeat purchase cycles.
- Concentrates:High-active-ingredient formulations requiring dilution economics govern institutional procurement, particularly in facility management contracts consolidating vendor relationships. The steepest expansion trajectory appears here as performance-based purchasing agreements specify extraction-compatible concentrated formulations.
- Foam Cleaners:Low-moisture aerosolized systems target spot treatment applications where rapid drying prevents mold risk in humid climates.
- Powder Cleaners:Absorbent dry compounds serve interim maintenance between wet extraction cycles, capturing budget-conscious household segments.
By volume, liquid cleaners lead. By growth pace, concentrates are climbing fastest.
Application:
Cost tier stratification separates premium professional-grade formulations from economy retail alternatives, with commercial contracts commanding price premiums for performance guarantees.
- Commercial Cleaning:Facility management contracts specify pH-balanced surfactant systems compatible with diverse carpet backings, consolidating vendor relationships across property portfolios. Procurement concentrates in Texas and Florida metropolitan areas where third-party service providers displace in-house janitorial teams.
- Residential Cleaning:Enzymatic chemistry advances neutralize pet odors without compromising dye stability, expanding application scope in pet-owning households. This segment captures steady replenishment demand through spray applicator compatibility.
- Automotive Cleaning:Compact formulations serve detailing shops and rental fleet maintenance with rapid-drying specifications for vehicle interiors.
- Industrial Cleaning:Heavy-duty solvent-based systems address manufacturing facility requirements, though U.S. EPA 40 CFR 59 VOC limits compress shelf space for these formulations.
Commercial cleaning commands the highest contract values. Residential cleaning generates the most frequent purchase cycles.
Distribution Channel:
Customer type concentration shapes channel economics, with institutional buyers favoring direct procurement while households fragment across retail touchpoints.
- Direct Sales:Professional cleaning services and hospitality procurement teams source concentrated formulations through vendor-managed inventory agreements, eliminating manual stock management. Branded hotel chains standardize these channels for performance-based contracts.
- Online Retail:Subscription replenishment models bypass mass-merchant slotting fees while capturing lifetime value data, with sensor-enabled dosing systems triggering automatic reorder.
- Supermarkets:Rental-channel placement at home improvement locations sustains recurring revenue through proprietary formula lock-in.
- Specialty Stores:Independent flooring retailers offer technical consultation for premium extraction equipment bundles.
Direct sales yield the highest margins per transaction. Online retail is expanding most quickly as IoT-enabled systems digitize replenishment authority.
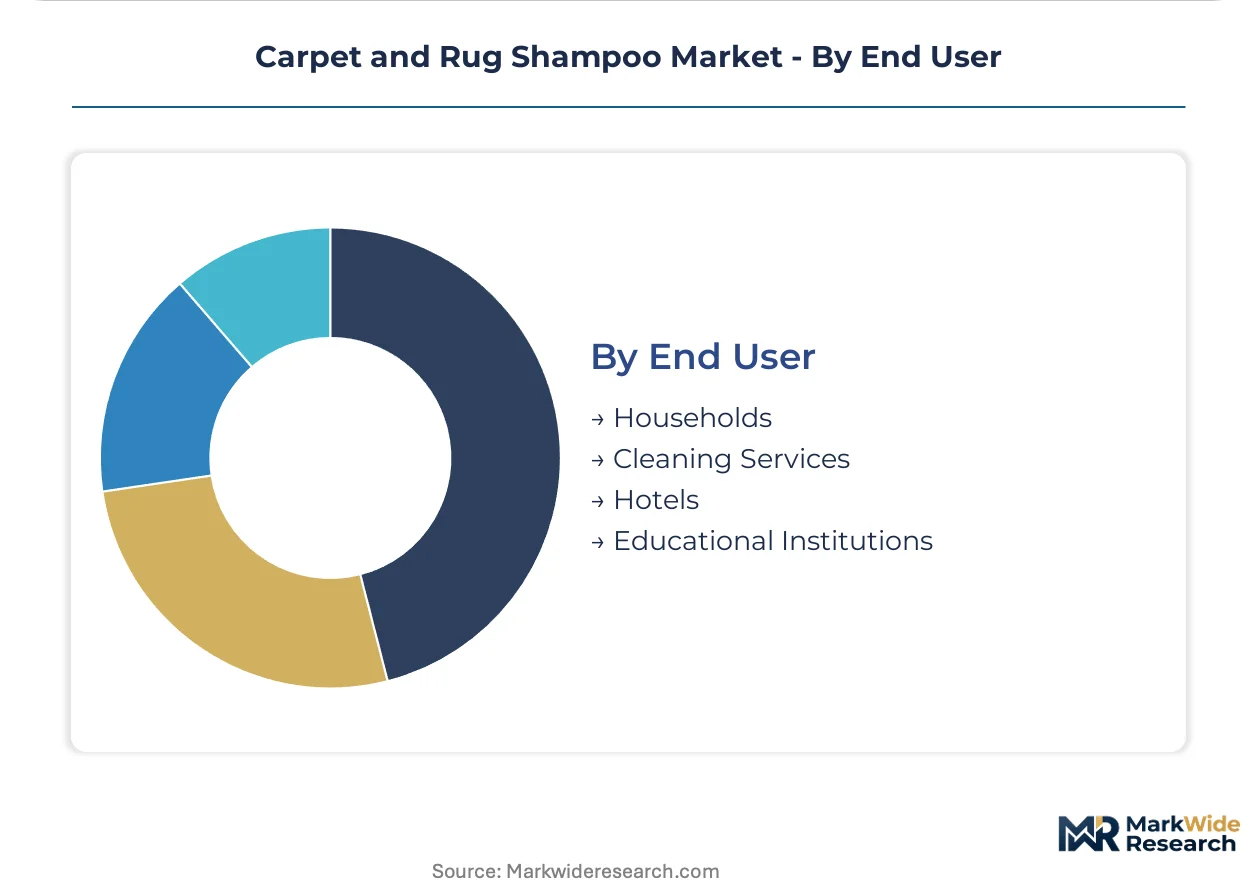
End User:
Supply concentration in Guangdong and Zhejiang manufacturing clusters differentially serves these end users, with private-label brands vulnerable to single-source disruption.
- Cleaning Services:Third-party providers specify EPA Safer Choice-certified products to preempt liability exposure, particularly in Sun Belt professional service contracts. These stakeholders drive demand for biodegradable surfactant systems.
- Hotels:Flagged properties pilot smart dispensing technology shifting replenishment authority from facilities staff to algorithmic triggers, standardizing chemistry specifications across entire portfolios.
- Households:Pet-owning demographics seek enzymatic odor neutralization without compromising carpet dye stability.
- Educational Institutions:Budget-constrained procurement favors economy-tier concentrates with dilution flexibility across campus facilities.
Cleaning services represent the largest volume purchasers. Hotels are adopting technology-enabled procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American import volumes for aerosol concentrate packaging, while Guangzhou Port throughput shapes raw surfactant feedstock availability across Pacific supply chains.
United States
Sun Belt metropolitan areas including Dallas-Fort Worth and Phoenix drive concentrated demand for extraction-machine-compatible formulations. The U.S. EPA Safer Choice program mandates surfactant disclosure thresholds that accelerate biodegradable chemistry migration. Manufacturing clusters in Ohio and Georgia supply private-label brands to mass-merchant retail channels.
China
Guangdong and Zhejiang provinces host expanded aerosol and liquid concentrate manufacturing serving North American private-label procurement. The Ministry of Ecology and Environment enforces dual carbon goals that compress petrochemical-based formulation capacity. Shenzhen-based producers are piloting sensor-enabled dosing systems for hospitality export contracts.
Germany
Facility management consolidation across Bavaria and North Rhine-Westphalia standardizes performance-based chemistry specifications. The ECHA REACH framework restricts preservative concentrations below levels common in legacy formulations. Cologne industrial clusters supply enzymatic concentrates meeting EU fragrance allergen limits.
India
Bengaluru and Mumbai commercial real estate expansion creates first-mover positioning for extraction-machine-compatible concentrates. The Bureau of Indian Standards governs surfactant labeling requirements for institutional cleaning products. Maharashtra chemical processors are scaling dilution-economy formulations for budget-constrained educational procurement.
United Kingdom
London property management firms consolidate vendor relationships across Greater Southeast office portfolios. The UK Environment Agency enforces volatile organic compound limits under parallel frameworks to EU directives. Manchester distribution hubs coordinate replenishment logistics for hospitality chains operating across Northern England.
Carpet and Rug Shampoo Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in surfactant supply and concentrate formulation. The market structure exhibits moderate consolidation, with branded consumer players anchoring retail shelf space and professional-grade suppliers locking rental-channel placements. Three archetypes dominate: captive appliance-detergent bundlers, multi-channel mass-market deployers, and rental-channel formula lock-in specialists. Competitive moves concentrate on strategic partnerships with extraction equipment manufacturers and geographic expansion into underpenetrated facility management markets.
Among North American platform integrators, Bissell Inc. and The Clorox Company occupy positions spanning consumer retail and institutional procurement channels. Bissell exemplifies the captive ecosystem archetype through appliance-detergent bundling strategies. The Clorox Company anchors multi-channel mass-market presence across mass merchants and e-commerce platforms. Rug Doctor represents the rental-channel specialist model, sustaining recurring revenue through proprietary formula placement at supermarket and home improvement locations.
| Leading Market Players |
|---|
| Bissell Inc. |
| The Clorox Company |
| Rug Doctor |
| Reckitt Benckiser Group |
| Zep Inc. |
| Bio-Kleen |
| Procter & Gamble |
| Sprayway Inc. |
| Hoover |
| Others |
Supply Flow & Price Mechanics
Guangdong province's aerosol and liquid concentrate manufacturing clusters anchor global formulation capacity, with capacity utilization swings in Shenzhen and Dongguan directly transmitting into North American private-label pricing power. When Chinese environmental enforcement tightens under dual carbon goals, U.S. procurement teams face compressed margin negotiation windows.
Pricing Analysis
Volume-discount tiering separates institutional concentrates from retail liquid cleaners from economy powder compounds. Pricing stratifies across premium, standard, and economy tiers based on EPA Safer Choice certification status and dilution-economy ratios for commercial buyers. Cost compression in the standard tier is intensifying because Guangdong feedstock volatility cascades through multi-state distribution networks. Educational institutions and budget-conscious households exhibit highest price sensitivity, while flagged hotel chains accept premium positioning for performance-guaranteed extraction compatibility.
Supply Chain Analysis
Export-control scrutiny on surfactant process technologies limits technology transfer into Indian and Southeast Asian manufacturing greenfields, preserving Chinese cost advantages. Raw material flows draw from ethylene oxide crackers in Texas and Zhejiang, linear alkylbenzene sulfonate producers in Louisiana and Rotterdam, and enzymatic additive specialists in Denmark. Single-source vulnerability concentrates in Guangdong aerosol packaging clusters, where North American private-label brands lack qualified secondary sources. Distribution runs through Port of Long Beach import consolidation, Ohio and Georgia blending facilities, and mass-merchant regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Appliance-detergent bundling ecosystems are redefining competitive moats as Bissell's captive chemistry lock-in demonstrates platform economics at scale. Interoperability between smart dispensing hardware and proprietary concentrate replenishment is shifting procurement authority from facilities staff to algorithmic triggers.
For Market Incumbents: Insulate rental-channel placements by recalibrating legacy extraction equipment for next-generation low-foam concentrates, preempting adoption friction at supermarket locations. Deepen backward integration into surfactant feedstocks through Ohio and Georgia manufacturing cluster expansion, reducing exposure to Guangdong price volatility. EPA Safer Choice certification investment represents the critical defensive lever against biodegradable chemistry mandates.
For New Entrants and Emerging Players: Pursue white-space positioning in India's underpenetrated facility management markets, specifically Bengaluru and Mumbai commercial real estate expansion corridors where extraction-machine-compatible concentrates lack established vendor relationships. Target educational institution procurement through dilution-economy formulations meeting Bureau of Indian Standards labeling requirements. Direct-to-consumer subscription channels bypass mass-merchant slotting fee barriers while capturing lifetime value data.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rental-channel formula lock-in specialists with supermarket and home improvement placement depth. Long-term viability across the projection horizon hinges on smart dispensing technology integration capability and hospitality procurement relationship density. Acquisition priorities center on mid-tier concentrate formulators with EPA Safer Choice certification pipelines. The signal to monitor is hospitality pilot deployment rates for IoT-enabled replenishment systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Dispensing Technology Integration | IoT-enabled extraction machines shift replenishment authority from facilities staff to algorithmic triggers in flagged hotel properties. |
| Backward Integration into Surfactant Feedstocks | Ohio and Georgia manufacturing clusters reduce Guangdong price volatility exposure for North American private-label brands. |
| EPA Safer Choice Certification Investment | Biodegradable chemistry migration preempts liability exposure in Sun Belt professional service contracts. |
| Direct-to-Consumer Subscription Launch | Automatic reorder models bypass mass-merchant slotting fees while capturing lifetime value data from pet-owning households. |
| India Facility Management Market Entry | Bengaluru and Mumbai commercial real estate expansion offers first-mover positioning for extraction-machine-compatible concentrates. |
Methodological Framework
Operator-level perspectives from hospitality procurement directors, facility management contract specialists, chemical formulation R&D leads, and mass-merchant category buyers anchored the qualitative base. Secondary validation drew from U.S. EPA 40 CFR 59 regulatory filings, EU ECHA REACH restriction updates, Bureau of Indian Standards surfactant labeling guidelines, and customs trade data tracking Guangdong export volumes. Bottom-up concentrate consumption modeling triangulated against top-down hospitality sector procurement spend analysis.
Scenario-bracketing around petrochemical feedstock volatility and regulatory enforcement intensity shaped the analytical framework across the analysis window. Segmentation dimensions encompassed formulation chemistry type, application intensity tier, distribution channel structure, and end-user procurement sophistication. CAGRs derived from installed extraction equipment base growth, replacement cycle timing, and concentrate dilution ratio adoption curves. Forecast inputs incorporated EPA Safer Choice certification penetration rates and smart dispensing hardware deployment timelines.
Sensitivities concentrate around Guangdong manufacturing disruption scenarios and California Right to Know Act enforcement cascades. Forecasts reflect assumptions on hospitality sector consolidation velocity and enzymatic chemistry cost reduction trajectories. Material shifts in U.S.-China trade policy affecting surfactant precursor tariffs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Cleaning Appliance Market