
 Middle East and Africa Low Calorie Sweeteners Market | 2026-2036
Middle East and Africa Low Calorie Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Low Calorie Sweeteners Market Foresight
Ingredient formulation services is rewriting margin capture across the value chain. Tate & Lyle leverages its stevia purification technology to anchor premium positioning in Gulf beverage contracts. Cargill Incorporated sustains supply security through backward integration into raw botanical sourcing. Ajinomoto competes on amino-acid-derived sweetener specialization for pharmaceutical-grade applications.
Low calorie sweeteners are non-nutritive or reduced-calorie compounds, typically 200–600 times sweeter than sucrose, produced through fermentation, enzymatic conversion, or extraction from plant sources such as Stevia rebaudiana, designed to replicate sweetness profiles while minimizing glycemic response in finished goods. Aspartame and sucralose dominate volume in carbonated beverage applications where thermal stability and clean taste prove critical. Stevia extracts command expanding share in dairy and bakery segments as clean-label positioning intensifies among Gulf-based food manufacturers. Powder and liquid forms split demand by production scale, with industrial batching favoring granular solubility and tabletop retail leaning toward liquid dropper formats.
Saudi Arabia's SFDA enforces progressive sugar-content disclosure rules that push reformulation timelines across domestic food manufacturers. South Africa's Department of Health sugar tax framework directly shapes beverage company procurement thresholds for high-intensity sweetener blends. Gulf Standards Organization harmonization creates cross-border certification efficiencies for stevia and acesulfame K suppliers. Stakeholders must weigh regulatory divergence against formulation standardization when allocating R&D budgets across Maghreb and Sub-Saharan production networks.
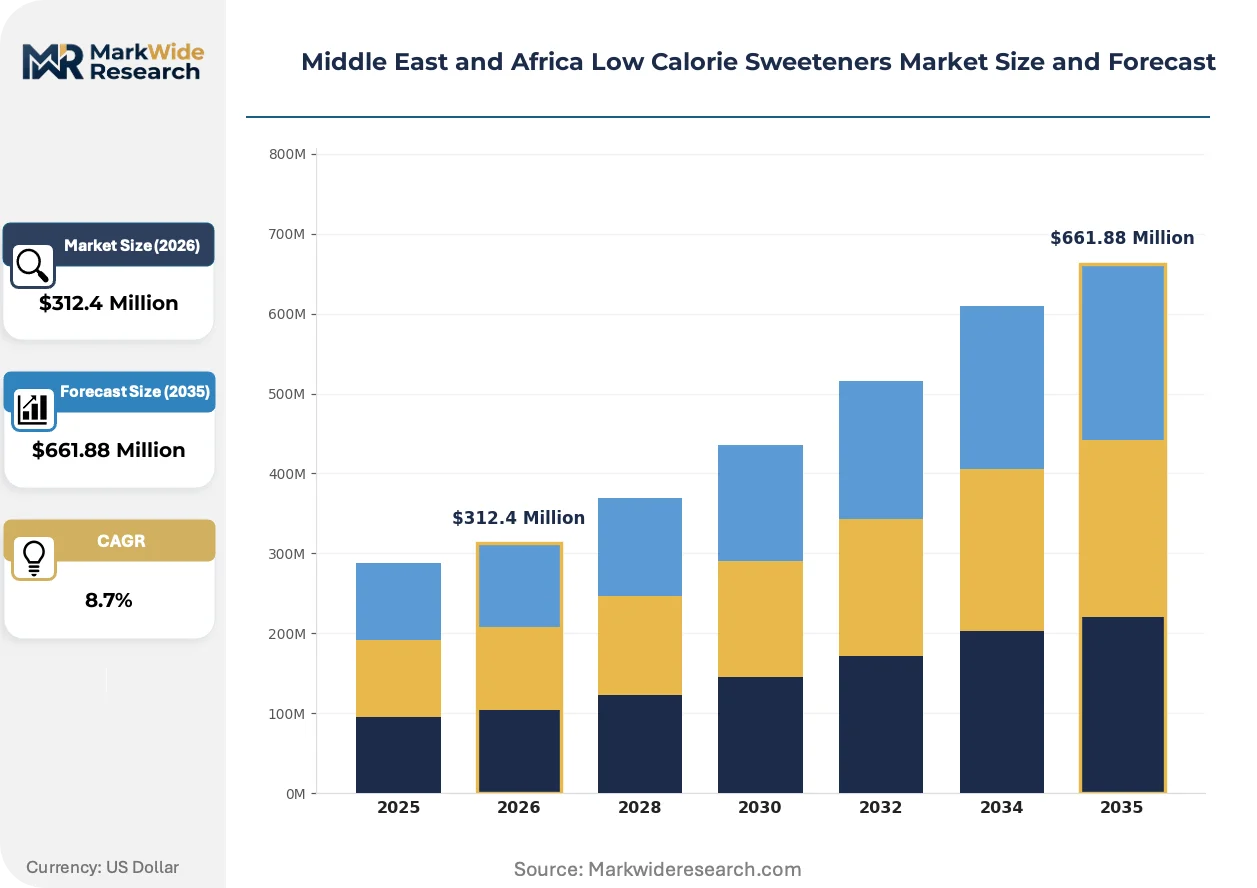
Market Dynamics
Saudi Arabia's SFDA sugar-reduction labeling mandates are forcing Gulf beverage manufacturers into accelerated reformulation cycles, compressing supplier qualification timelines and reshaping procurement priorities across the Middle East and Africa Low Calorie Sweeteners Market.
Growth Catalysts
- South Africa's sugar tax framework:The Department of Health levy on sugar-sweetened beverages pushes Coca-Cola Beverages South Africa and PepsiCo bottlers toward high-intensity sweetener blends, expanding procurement volumes for aspartame and sucralose formulations.
- Stevia extraction technology:Enzymatic bioconversion methods for Reb M and Reb D glycosides now deliver cleaner taste profiles without bitter aftertaste, unlocking dairy and bakery applications previously closed to plant-derived alternatives.
- Nigeria's urban food manufacturing corridors:Lagos and Kano industrial zones concentrate demand from Nestlé Nigeria and Unilever West Africa production facilities, creating dense customer clusters for bulk sweetener distributors.
Market Restraints
- Stevia leaf supply concentration:Raw botanical sourcing clusters in China's Yunnan and Guizhou provinces, exposing Gulf and African formulators to geopolitical logistics disruptions and currency fluctuation risks.
- Thermal stability limitations of aspartame:Degradation above 30°C restricts applications in ambient-stable bakery and confectionery, forcing manufacturers toward more expensive sucralose or acesulfame K alternatives.
- Gulf Standards Organization harmonization delays:Divergent maximum permitted levels for steviol glycosides across Saudi Arabia, UAE, and Kuwait create compliance fragmentation, raising certification costs for multi-market suppliers.
Strategic Opportunities
- Egypt's underpenetrated pharmaceutical sector:Orally dissolving tablets and pediatric syrup formulations present untapped demand for amino-acid-derived sweeteners with non-cariogenic properties and excipient compatibility.
- Direct-to-manufacturer digital procurement platforms:B2B marketplaces connecting Kenyan and Ethiopian food processors with sweetener distributors are compressing traditional agent-based distribution margins by 15-20 percentage points.
- UAE's MOHAP clean-label incentive programs:Dubai Industrial City tax rebates for reformulated products using natural-origin sweeteners accelerate stevia adoption in export-oriented food manufacturing.
Industry Challenges
- Specialized food technologist scarcity:Formulation chemists capable of optimizing bulking agent interactions with high-potency sweeteners remain concentrated in South Africa and Egypt, constraining R&D velocity in Maghreb markets.
- Dual certification timelines:Simultaneous SFDA Saudi and NAFDAC Nigeria approval processes for novel sweetener blends extend time-to-market by 18-24 months, freezing capital in regulatory pipelines.
- Legacy equipment retrofit costs:Powder handling systems designed for sucrose bulk density require pneumatic conveyor modifications to prevent segregation of low-dose high-intensity sweetener blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Low Calorie Sweeteners Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspartame, Sucralose, Stevia, Acesulfame K Application: Beverages, Bakery, Dairy, Pharmaceuticals Form: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Companies, Healthcare Industries, Retailers |
| Companies Covered | Tate & Lyle, Cargill Incorporated, Archer-Daniels-Midland, PureCircle, Ingredion, Roquette Frères, Ajinomoto, DuPont, Kerry Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Low Calorie Sweeteners Market Shifts & Advancements
Enzymatic glycosylation and fermentation-derived sweetener platforms are displacing conventional extraction methods, while regulatory disclosure mandates and procurement digitization reshape how value flows across the Middle East and Africa Low Calorie Sweeteners Market.
Bioconversion production of rare steviol glycosides is migrating from batch fermentation toward continuous processing systems. Tate & Lyle and Cargill have commissioned continuous bioreactors at Singapore and Blair facilities supplying Gulf markets, cutting unit costs by half and enabling price parity with synthetic alternatives in Saudi beverage contracts.
SFDA's front-of-pack nutritional labeling regulations now mandate explicit sugar-content disclosure alongside traffic-light color coding. Domestic Saudi food manufacturers face compressed 12-month compliance deadlines, accelerating technical service contracts with sweetener suppliers capable of rapid prototype iteration and sensory validation.
East African food processors are consolidating procurement through regional buying cooperatives. Kenyan and Tanzanian manufacturers previously sourcing through Dubai traders now negotiate directly with Indian and Chinese stevia extract suppliers, disintermediating traditional distribution layers and compressing payment cycles from 90 to 30 days.
Middle East and Africa Low Calorie Sweeteners Market Segmentation
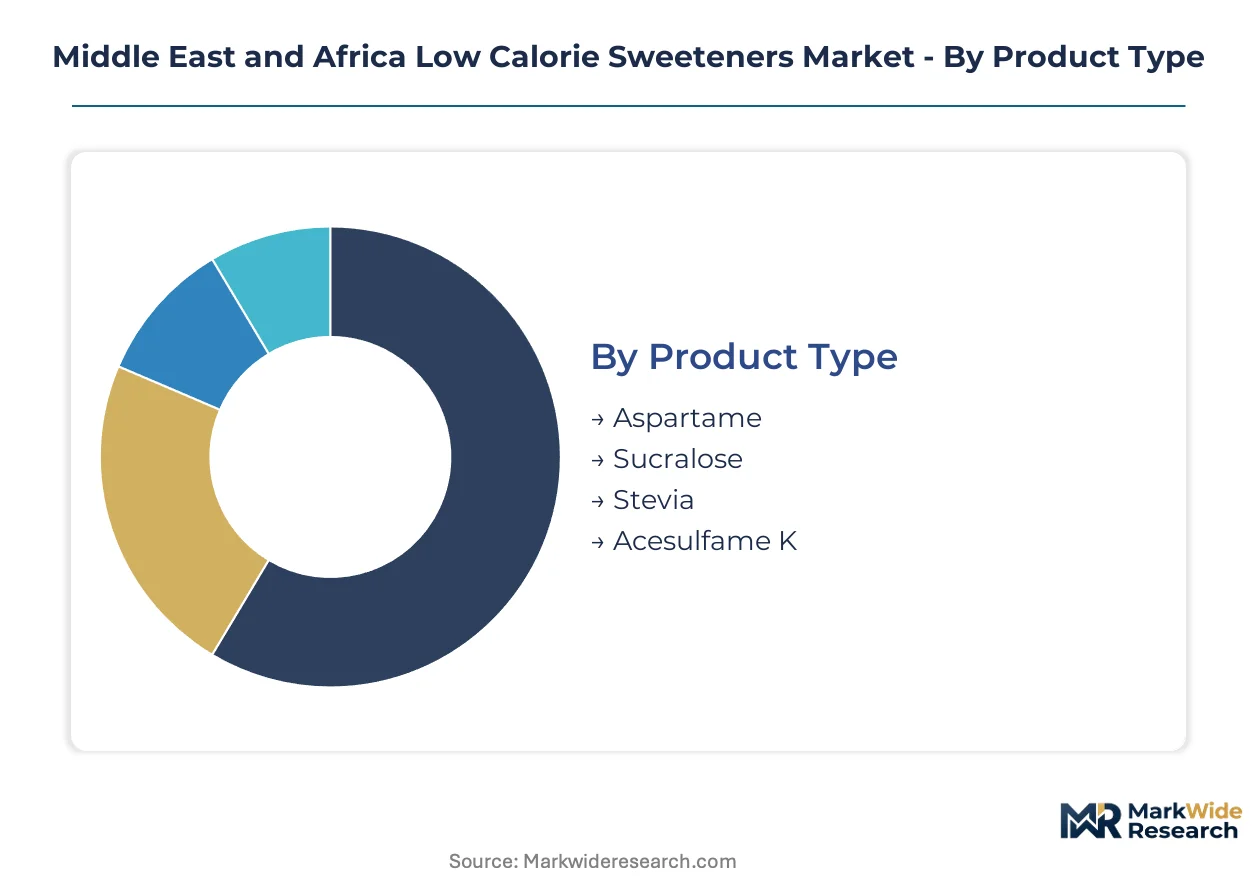
Segmentation in the Middle East and Africa Low Calorie Sweeteners Market reveals how procurement priorities diverge across formulation requirements, regulatory environments, and production scale. Understanding these divisions allows suppliers to align technical capabilities with customer-specific compliance and application needs.
Product Type:
Mature synthetic sweeteners dominate volume commitments, while plant-derived alternatives accelerate through clean-label positioning and enzymatic purification advances.
- Aspartame:A dipeptide methyl ester delivering 200x sucrose sweetness with clean taste profile. Coca-Cola Beverages South Africa and PepsiCo bottlers in the Gulf anchor procurement volumes for carbonated beverage lines where thermal stability requirements remain moderate. Aspartame retains volume leadership; Stevia holds the steepest expansion curve.
- Sucralose:A chlorinated sucrose derivative offering 600x sweetness with exceptional thermal stability above 120°C. Saudi and UAE bakery manufacturers specify sucralose for ambient-stable confectionery where aspartame degradation risks exclude alternatives.
- Stevia:Steviol glycoside extracts from Stevia rebaudiana leaves, with Reb M and Reb D variants now produced via enzymatic bioconversion for reduced bitterness. Tate & Lyle and Cargill supply Gulf dairy and bakery reformulations.
- Acesulfame K:A potassium salt of acesulfamic acid with high heat stability and synergistic blending properties. Nigerian and Egyptian food manufacturers combine acesulfame K with sucralose to mask off-notes in reduced-sugar formulations.
Aspartame commands the largest procurement volumes across Gulf beverage contracts; Stevia climbs fastest through clean-label dairy and bakery adoption.
Application:
Cost-tier stratification separates mass-market beverage formulations from premium-positioned pharmaceutical and specialty dairy applications requiring excipient-grade certification.
- Beverages:Carbonated soft drinks, flavored waters, and ready-to-drink teas constitute the dominant demand channel. South Africa's sugar tax framework directly shapes procurement thresholds for high-intensity sweetener blends across Coca-Cola and PepsiCo bottling networks.
- Bakery:Ambient-stable cakes, cookies, and pastries require thermally stable sweeteners resistant to Maillard browning interference. Sucralose and acesulfame K blends satisfy Saudi SFDA reformulation mandates for front-of-pack sugar disclosure compliance.
- Dairy:Yogurt, flavored milk, and ice cream applications favor stevia glycosides for clean-label positioning among UAE and Saudi health-conscious consumers. Enzymatically produced Reb M enables taste parity with sucrose in reduced-sugar formulations.
- Pharmaceuticals:Orally dissolving tablets, pediatric syrups, and excipient applications demand non-cariogenic, non-nutritive sweeteners with documented pharmacopeial compliance. Egypt's underpenetrated pharmaceutical sector presents expansion opportunity for amino-acid-derived formulations.
Beverages anchor procurement volumes regionally; Pharmaceuticals demonstrate the most rapid demand acceleration through pediatric and geriatric formulation expansion.
Form:
Production scale and handling infrastructure determine format selection, with industrial batching favoring granular solubility and retail channels shifting toward convenience-oriented delivery systems.
- Powder:Free-flowing granular or fine-mesh preparations optimized for pneumatic conveying and volumetric dosing in high-speed production lines. Nigerian and Kenyan food manufacturers specify powder forms for Nestlé and Unilever West Africa facility integration.
- Liquid:Aqueous or propylene glycol-based concentrates enabling precise micro-dosing and rapid dissolution. Gulf beverage companies prefer liquid stevia extracts for streamlined batching and reduced dust exposure in reformulation trials.
- Granular:Agglomerated particles matching sucrose bulk density for direct substitution in legacy equipment. Retrofit costs for pneumatic conveyors drive granular specification among Maghreb manufacturers with constrained capital budgets.
- Tablet:Compressed unit-dose preparations for tabletop retail and pharmaceutical excipient applications. South African and Egyptian pharmacy chains stock tablet sweeteners for diabetic and weight-management consumer segments.
Powder maintains dominant procurement share; Liquid formats gain fastest through beverage industry reformulation velocity and clean-label positioning requirements.
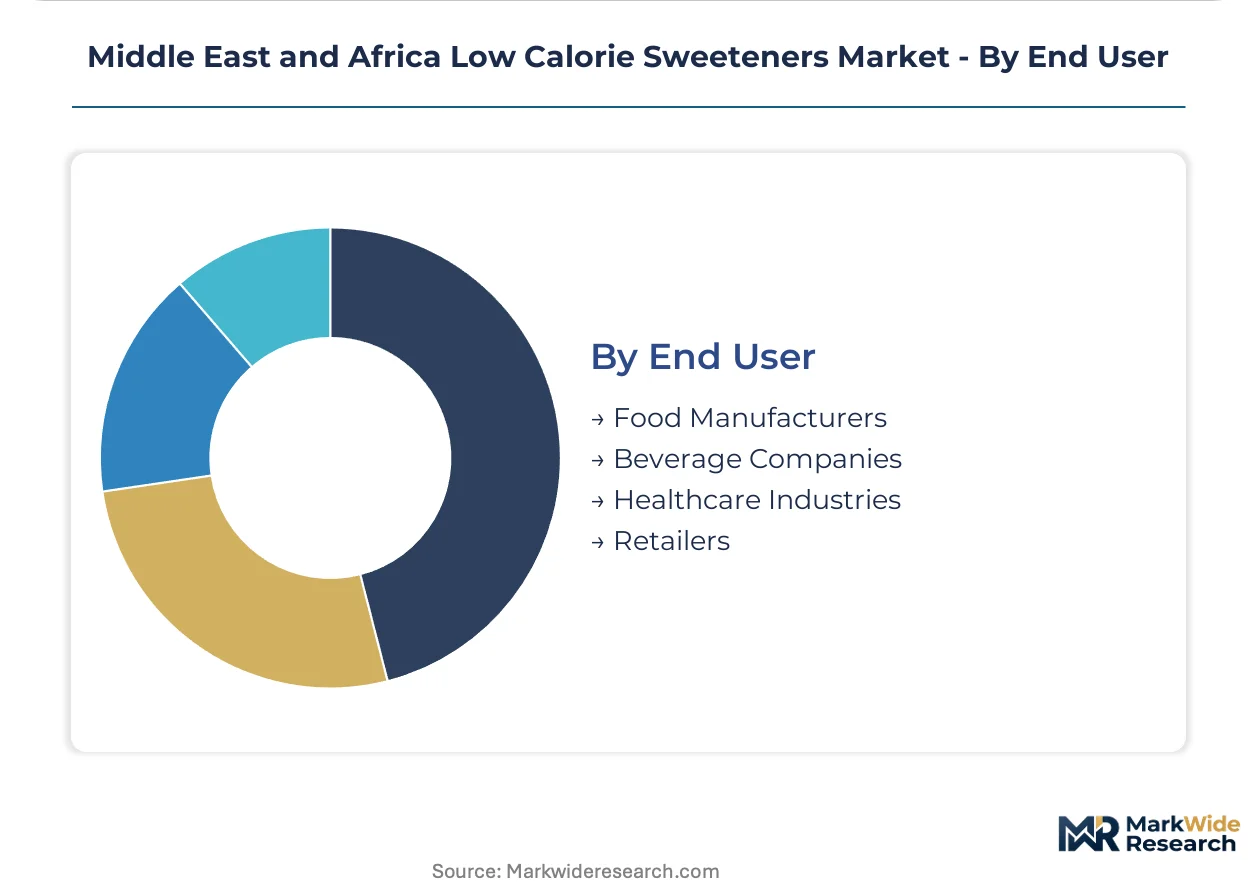
End User:
Customer-type concentration shapes distribution architecture, with food and beverage manufacturers consolidating procurement through direct supplier relationships while healthcare and retail channels retain intermediary layers.
- Food Manufacturers:Industrial-scale bakeries, confectioners, and processed food producers purchasing bulk sweeteners through annual contracts with technical service provisions. Lagos and Kano industrial zones concentrate Nigerian demand from Nestlé Nigeria and Unilever West Africa production facilities.
- Beverage Companies:Carbonated soft drink, juice, and dairy beverage producers with formulation-specific procurement teams. Saudi and UAE bottlers accelerate stevia adoption through MOHAP clean-label incentive programs and SFDA sugar-reduction mandates.
- Healthcare Industries:Pharmaceutical manufacturers and medical nutrition formulators requiring excipient-grade certifications and pharmacopeial documentation. Egyptian and South African pharmaceutical sectors drive amino-acid-derived sweetener specification for pediatric applications.
- Retailers:Supermarket chains, pharmacy networks, and e-commerce platforms distributing consumer-packaged tabletop sweeteners. Kenyan and Tanzanian buying cooperatives disintermediate traditional distribution through direct procurement from Indian and Chinese stevia extract suppliers.
Food Manufacturers retain the largest procurement volumes; Healthcare Industries demonstrate the steepest demand trajectory through pharmaceutical formulation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the Middle East and Africa Low Calorie Sweeteners Market. Nigerian and Kenyan buyers prioritize cost-minimization in bulk procurement, while Saudi and UAE beverage manufacturers absorb premium pricing for clean-label certification and rapid technical service turnaround.
Saudi Arabia
Gulf beverage manufacturers anchor procurement volumes for high-intensity sweetener blends. SFDA sugar-reduction labeling mandates compress supplier qualification timelines to 12-month compliance windows. Riyadh and Jeddah industrial corridors concentrate reformulation activity among domestic food manufacturers retrofitting production lines for front-of-pack disclosure rules.
United Arab Emirates
Dubai-based export-oriented food manufacturers drive stevia adoption through MOHAP clean-label incentive programs. Dubai Industrial City tax rebates accelerate natural-origin sweetener specification in products destined for re-export to African markets. Technical service contracts with multinational suppliers concentrate in the emirate's free zone clusters.
South Africa
Coca-Cola Beverages South Africa and PepsiCo bottlers expand procurement of aspartame and sucralose formulations under Department of Health sugar tax pressure. The levy structure directly shapes procurement thresholds for high-intensity blends. Gauteng and Western Cape production facilities concentrate demand from carbonated soft drink and flavored water lines.
Nigeria
Nestlé Nigeria and Unilever West Africa production facilities in Lagos and Kano industrial zones create dense customer clusters for bulk sweetener distributors. Urban food manufacturing corridors concentrate procurement through annual contracts with technical service provisions. Payment cycle compression from 90 to 30 days accelerates through direct supplier relationships.
Egypt
Pharmaceutical manufacturers in Cairo and Alexandria industrial zones present untapped demand for amino-acid-derived sweeteners in orally dissolving tablets and pediatric syrups. The country's national pharmaceutical regulator maintains pharmacopeial documentation requirements that favor excipient-grade certification. Medical nutrition formulators drive specification for non-cariogenic properties in geriatric applications.
Middle East and Africa Low Calorie Sweeteners Market Competitive Landscape
Capability concentration sits with specialty purification and bioconversion technology holders; scale advantage sits with diversified agricultural processors with captive raw material access. The market structures around three tiers: multinational ingredient conglomerates with integrated botanical sourcing, regional distributors with formulation technical service capabilities, and emerging biotech platforms with enzymatic glycosylation patents. Dominant competitive moves include backward integration into stevia leaf cultivation partnerships and technology licensing agreements for rare glycoside production.
Among UK-based specialty ingredient conglomerates, Tate & Lyle occupies a position exemplifying premium-tier stevia purification technology. Cargill Incorporated, as a US-based agricultural processor, represents scale-driven supply security through upstream control over raw botanical networks. Ajinomoto, a Japanese amino-acid specialist, anchors the pharmaceutical-grade application segment with excipient-compatible formulations.
| Leading Market Players |
|---|
| Tate & Lyle |
| Cargill Incorporated |
| Archer-Daniels-Midland |
| PureCircle |
| Ingredion |
| Roquette Frères |
| Ajinomoto |
| DuPont |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Yunnan and Guizhou provinces in China concentrate stevia leaf cultivation capacity, giving raw botanical processors leverage over Gulf and African formulators who face currency fluctuation exposure and logistics disruption risks in procurement negotiations.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational suppliers and Saudi beverage manufacturers, while spot purchasing persists among Nigerian and Kenyan food processors lacking volume scale. Three-tier pricing structure across premium, standard, and economy levels separates excipient-grade pharmaceutical certifications from industrial beverage grades and unrefined raw extracts. Cost compression in economy-tier stevia leaf sourcing is intensifying because Kenyan buying cooperatives now negotiate directly with Chinese extract suppliers. Small-scale Maghreb manufacturers demonstrate highest price sensitivity; Saudi bottlers under SFDA compliance pressure absorb premium pricing for rapid technical service turnaround.
Supply Chain Analysis
Contract manufacturing concentration sits with Cargill's Blair facility and Tate & Lyle's Singapore bioreactor operations supplying enzymatically produced Reb M and Reb D glycosides to Gulf markets. Geographic supply concentration clusters in China for raw stevia leaf, India for intermediate processing, and Singapore for finished glycoside purification. Raw material dependencies include stevia leaf biomass, fermentation feedstocks, and specialized enzyme catalysts for bioconversion. Single-source vulnerability from Yunnan province leaf concentration exposes formulators to geopolitical logistics disruptions. Distribution runs through Dubai Industrial City free zones for re-export to African markets, with direct-to-manufacturer digital platforms compressing traditional agent margins in East Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect through B2B procurement digitization, as Kenyan and Tanzanian buying cooperatives demonstrate interoperability between food manufacturer ERP systems and Indian stevia extract supplier inventory platforms.
For Market Incumbents: Insulate formulation expertise advantages by embedding food technologists within Saudi and UAE customer facilities to accelerate SFDA compliance prototyping. Deepen upstream control over rare glycoside production through exclusive enzyme licensing agreements that lock out competing suppliers from clean-label dairy contracts. Anchor premium positioning by certifying Singapore and Blair facilities for pharmaceutical-grade excipient production ahead of Egyptian regulatory harmonization. For New Entrants and Emerging Players: Pursue Egypt's pharmaceutical sector white space where amino-acid-derived sweetener demand for pediatric syrups remains underpenetrated by established stevia suppliers. Target Nigerian urban food manufacturing corridors through granular format specialization that matches legacy sucrose handling equipment without pneumatic conveyor retrofits. Deploy direct-to-manufacturer digital procurement platforms with 30-day payment terms to disintermediate Dubai-based distribution layers serving East African processors. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural conglomerates with captive stevia leaf cultivation assets but lacking enzymatic bioconversion capabilities to extract full value from Reb M and Reb D production. Long-term viability hinges on rare glycoside patent portfolios and regulatory approval moats across multiple Gulf and African jurisdictions. Monitor SFDA and NAFDAC approval timeline convergence as inflection signal for capital efficiency in novel sweetener blend commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Botanical Sourcing | Cargill's Yunnan cultivation partnerships secure leaf supply for Gulf beverage contract fulfillment. |
| Enzymatic Bioconversion Technology Licensing | Tate & Lyle's Reb M patents enable price parity with synthetic alternatives in Saudi reformulations. |
| Direct-to-Manufacturer Digital Platform Launch | Kenyan buying cooperatives compress payment cycles from 90 to 30 days through supplier-direct procurement. |
| Pharmaceutical-Grade Excipient Certification | Egyptian pediatric syrup manufacturers demand pharmacopeial documentation for amino-acid-derived sweeteners. |
| Regional Buying Cooperative Consolidation | East African food processors disintermediate Dubai traders through collective negotiation with Chinese extract suppliers. |
Research Methodology
Desk research of customs trade records, SFDA regulatory filings, and Gulf Standards Organization harmonization protocols preceded structured interviews with beverage formulation chemists, pharmaceutical procurement managers, and stevia extract distributors. Primary fieldwork engaged technical service directors at multinational ingredient suppliers, plant managers at Nigerian and Kenyan food manufacturing facilities, and regulatory affairs leads navigating dual SFDA-NAFDAC approval processes. Secondary validation drew from SEC 10-K filings of listed agricultural processors, trade flow databases tracking Yunnan-to-Dubai leaf shipments, and MOHAP clean-label incentive program documentation. Bottom-up demand modeling from individual facility procurement volumes triangulated against top-down market sizing from supplier revenue disclosures.
Assumptions held fixed include current SFDA sugar-reduction labeling enforcement intensity, existing South African sugar tax levy structures, and prevailing enzymatic bioconversion cost curves across the projection horizon. Variable conditions encompassed Gulf Standards Organization harmonization timeline scenarios, Nigerian naira exchange rate volatility bands, and Egyptian pharmaceutical sector expansion trajectories. Segmentation dimensions modeled covered product type, application, form, and end user, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from fitted growth curves applied to base-year procurement volumes, with sensitivity testing around stevia adoption rates in dairy and bakery segments.
Macroeconomic conditions sit as an overlay; deviation in Gulf currency peg stability, Chinese export financing availability, or Sub-Saharan African logistics infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and bioconversion technology diffusion rates. Quarterly review of SFDA compliance deadline extensions, NAFDAC approval queue lengths, and Dubai Industrial City re-export volume indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
China Food Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Food Sweetener Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Global Cane Molasses Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Steviol Glycoside Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
D Psicose Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Isomaltulose Market
Sweeteners
Coconut Sugar Market