
 Global Black Pepper Market | 2026-2036
Global Black Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Black Pepper Market Analysis
Pharmaceutical applications for piperine-based bioenhancers is decoupling from traditional spice consumption patterns, creating parallel value chains for standardized extracts. McCormick and Company Inc leverages its retail distribution density across North American grocery channels to sustain premium positioning for branded pepper products. Olam International Limited anchors global procurement volumes through direct farm partnerships in Vietnam and Brazil, while Synthite Industries Private Ltd specializes in oleoresin and essential oil extraction for industrial flavor houses.
Black pepper comprises the dried fruit of Piper nigrum, typically containing 1-9% piperine alkaloid by weight alongside volatile oils that determine aromatic intensity; steam distillation and solvent extraction yield standardized oleoresins for controlled industrial dosing. Ground pepper and extracts lead value capture within the product type dimension, with extracts commanding margin premiums due to pharmaceutical-grade purification requirements. The end user segmentation shows pharmaceutical and nutraceutical buyers outpacing food industry volume growth, driven by piperine's documented role in enhancing bioavailability of curcumin and other therapeutic compounds.
India's FSSAI enforces maximum residue limits for aflatoxins and pesticide contaminants in spice exports, while the USDA's National Organic Program and EU REACH framework govern import eligibility for processed derivatives across Western markets. Vietnam's Plant Protection Department and Indonesia's national standards body administer parallel phytosanitary certification regimes that determine market access for whole and ground shipments. Stakeholders must monitor evolving maximum residue limit harmonization between Codex Alimentarius and major importing jurisdictions to anticipate compliance cost shifts across the value chain.
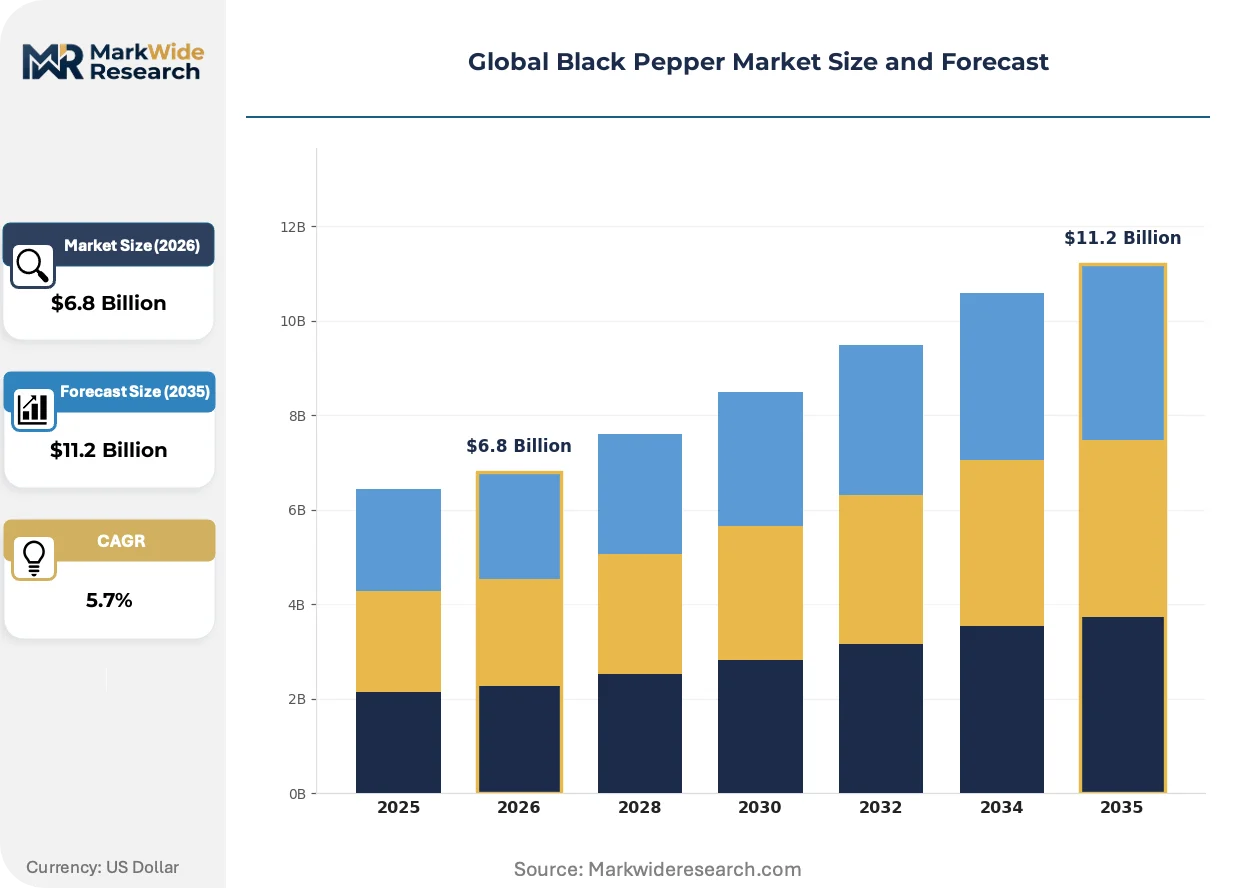
Market Dynamics
Pharmaceutical-grade piperine extraction is bifurcating the black pepper value chain, creating parallel procurement standards that favor centralized processing facilities over traditional smallholder networks. Mechanized harvesting systems in Vietnam and Indonesia are compressing labor costs while concentrating supply ownership among integrated processors.
Growth Catalysts
- Pharmaceutical bioavailability demand:Piperine's role in enhancing curcumin absorption is expanding contract volumes for standardized extracts. Nutraceutical formulators in North America and Western Europe are specifying alkaloid content minimums that favor dedicated extraction facilities.
- FSSAI clean-label mandates:India's 2023 contaminant caps for aflatoxins and pesticide residues are forcing upstream consolidation. Exporters must now certify through accredited laboratories, disqualifying informal collectors.
- Steam distillation technology:Continuous-flow systems are reducing solvent use in oleoresin production. Industrial flavor houses are qualifying Vietnamese processors with in-house distillation capacity.
Market Restraints
- Input cost volatility:Labor shortages during Vietnamese harvest seasons spike wage rates unpredictably. Smallholders lack storage infrastructure to time sales against price dips.
- Supply concentration risk:Vietnam and Indonesia together account for the majority of exportable volume. Weather anomalies in either archipelago disrupt global availability within weeks.
- Substitution threat:Synthetic piperine from chemical manufacturers competes on price for non-pharmaceutical applications. Food-grade buyers increasingly accept laboratory-derived alternatives.
Strategic Opportunities
- Brazilian cultivation expansion:Bahia and Espírito Santo provinces offer underutilized acreage with favorable rainfall patterns. Investors are establishing irrigated estates with integrated drying facilities.
- EU REACH registration tailwinds:Pre-registered piperine derivatives gain expedited market access. Exporters with existing dossiers capture share from non-compliant competitors.
- Direct-to-manufacturer channels:Blockchain-traceable shipments bypass traditional auction houses. Pharmaceutical buyers are contracting dedicated harvests with genomic verification of Piper nigrum cultivars.
Industry Challenges
- Phytosanitary certification timelines:Indonesia's national standards body requires sequential laboratory testing that extends shipping schedules by 4-6 weeks. Perishability losses accumulate during documentation delays.
- Organic transition capex:Three-year conversion periods for FSSAI organic recognition demand working capital reserves. Smallholders lack balance sheet capacity to bridge revenue gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Black Pepper Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Pepper, Ground Pepper, Oil, Extract End User: Food Industry, Cosmetic Sector, Pharmaceutical Industry, Nutraceuticals Packaging Type: Bags, Bottles, Jars, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Everest Food Products Pvt Ltd, Baria Pepper Co Ltd, Olam International Limited, Robertet SA, Kancor Ingredients Limited, McCormick and Company Inc, Phuc Sinh Corporation, Truong Thinh Agricultural Product Processing Co. Ltd., Synthite Industries Private Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Black Pepper Market Emerging Trajectories
Processing technology and regulatory harmonization are compressing traditional supply hierarchies while pharmaceutical purity standards penetrate food-grade channels. Buyers are consolidating vendor lists around integrated processors with captive laboratory capabilities.
Mechanical harvesters with optical sorting are automating berry selection in Vietnamese estates. Large-scale plantation operators are retrofitting equipment originally developed for coffee cherry harvesting. Labor cost arbitrage is narrowing as machines achieve 85% recovery rates of ripe peppercorns, compressing the wage advantage that previously sustained manual collection networks.
REACH registration deadlines for piperine-containing mixtures are forcing European importers to document supply chain substance volumes. Industrial users of oleoresin must now register downstream uses or face import suspension. German and Dutch flavor houses are consolidating procurement around pre-registered Vietnamese suppliers, marginalizing traders without regulatory affairs capabilities.
Certification-driven procurement is displacing spot-market purchasing among North American nutraceutical brands. Buyers are specifying USDA Organic or EU Organic recognition as table stakes, then layering FSSAI export clearance and third-party mycotoxin testing. This multi-certification requirement favors processors with in-house quality laboratories, squeezing traders who rely on external testing facilities.
Global Black Pepper Market Segmentation
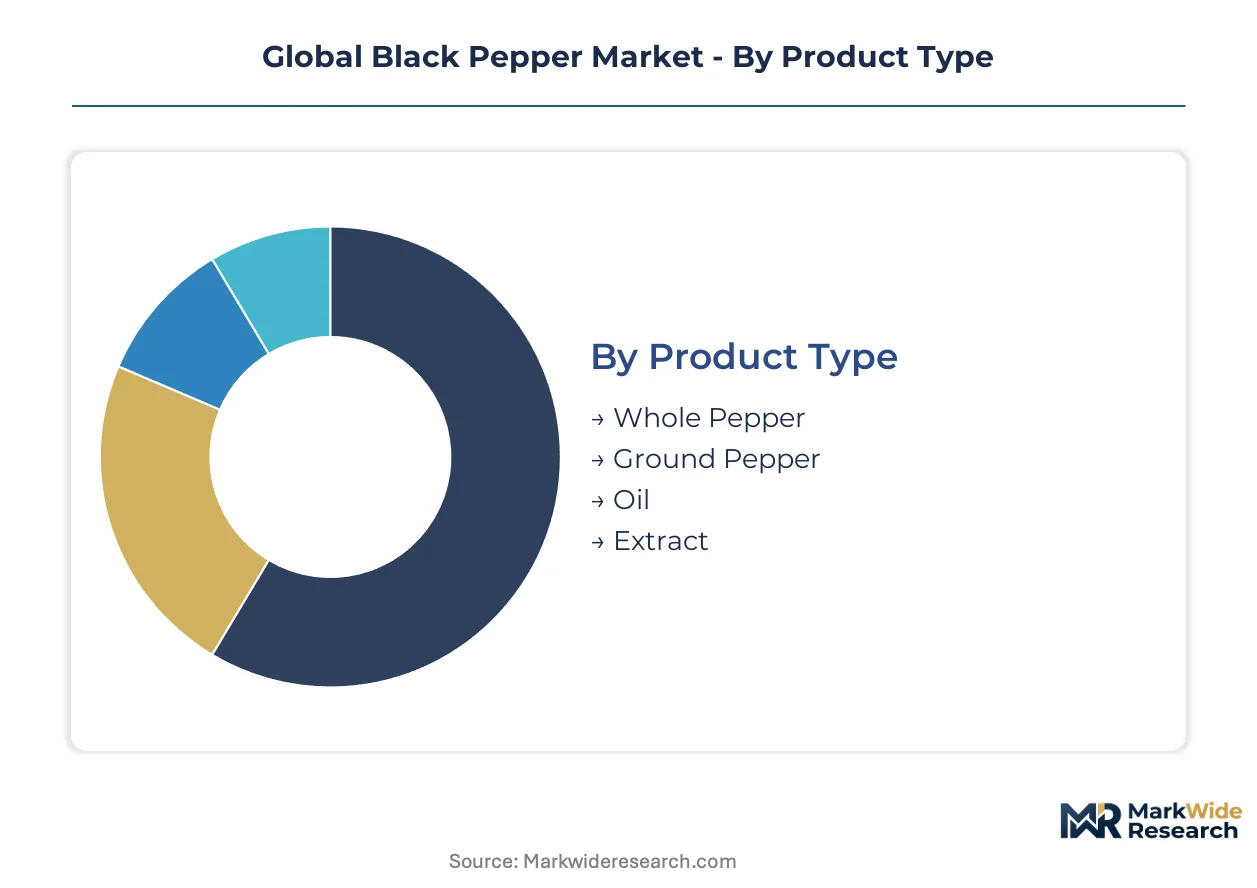
Segmentation in black pepper markets separates commodity-grade volume from pharmaceutical-grade precision. Each category carries distinct certification burdens and margin structures that reshape procurement patterns across industrial buyers.
Product Type:
Standardization intensity varies sharply across this category, from bulk agricultural commodities to refined alkaloid specifications.
- Extract:Piperine concentrates undergo solvent extraction and chromatographic purification to achieve 95%+ alkaloid standardization. Pharmaceutical formulators in Germany and the United States are contracting dedicated extraction facilities in Vietnam to secure REACH-compliant supply chains for curcumin bioenhancement applications.
- Ground Pepper:Roller-milled particles with controlled mesh sizing dominate food manufacturing procurement. Industrial spice houses in India specify FSSAI-certified grinding operations with metal detection and microbial testing protocols to satisfy export clearance requirements.
- Whole Pepper:Dried berry preservation for premium culinary applications and visual quality assessment.
- Oil:Steam-distilled volatile fractions for flavoring and aromatherapy applications.
Most installed capacity flows through Ground Pepper. Expansion is steepest in Extract.
End User:
Cost tier stratification separates commodity food buyers from premium pharmaceutical procurement with divergent specification tolerances.
- Pharmaceutical Industry:Piperine extraction for bioavailability enhancement demands USP-grade purity with documented heavy metal and solvent residue testing. CDSCO-registered Indian laboratories are certifying batches for export to FDA-regulated facilities, where alkaloid content minimums now exceed food-grade standards by an order of magnitude.
- Food Industry:Volume procurement of whole and ground pepper for seasoning blends and processed food manufacturing. Mass-market buyers prioritize price stability over cultivar traceability, sourcing through Vietnamese auction houses with minimal laboratory documentation.
- Nutraceuticals:Dietary supplement formulations combining piperine with turmeric and other botanical extracts.
- Cosmetic Sector:Essential oil fractions for fragrance compounding and topical applications.
Food Industry absorbs the greatest volume share. Nutraceuticals are gaining share fastest.
Packaging Type:
Customer type alignment determines format selection, from industrial bulk to retail-ready presentation.
- Bags:Multi-layer laminated sacks with moisture barriers for 25-50kg industrial shipments. Vietnamese processors are qualifying FIBC designs with integrated QR traceability for pharmaceutical buyers requiring harvest-to-destination documentation.
- Jars:Glass and PET containers with tamper-evident closures for premium retail positioning.
- Bottles:Dispensing formats for ground pepper and oil products in consumer channels.
- Sachets:Single-serve portions for foodservice and institutional catering applications.
Bag shipments dominate industrial procurement. Jar formats command the highest unit margins in North American retail.
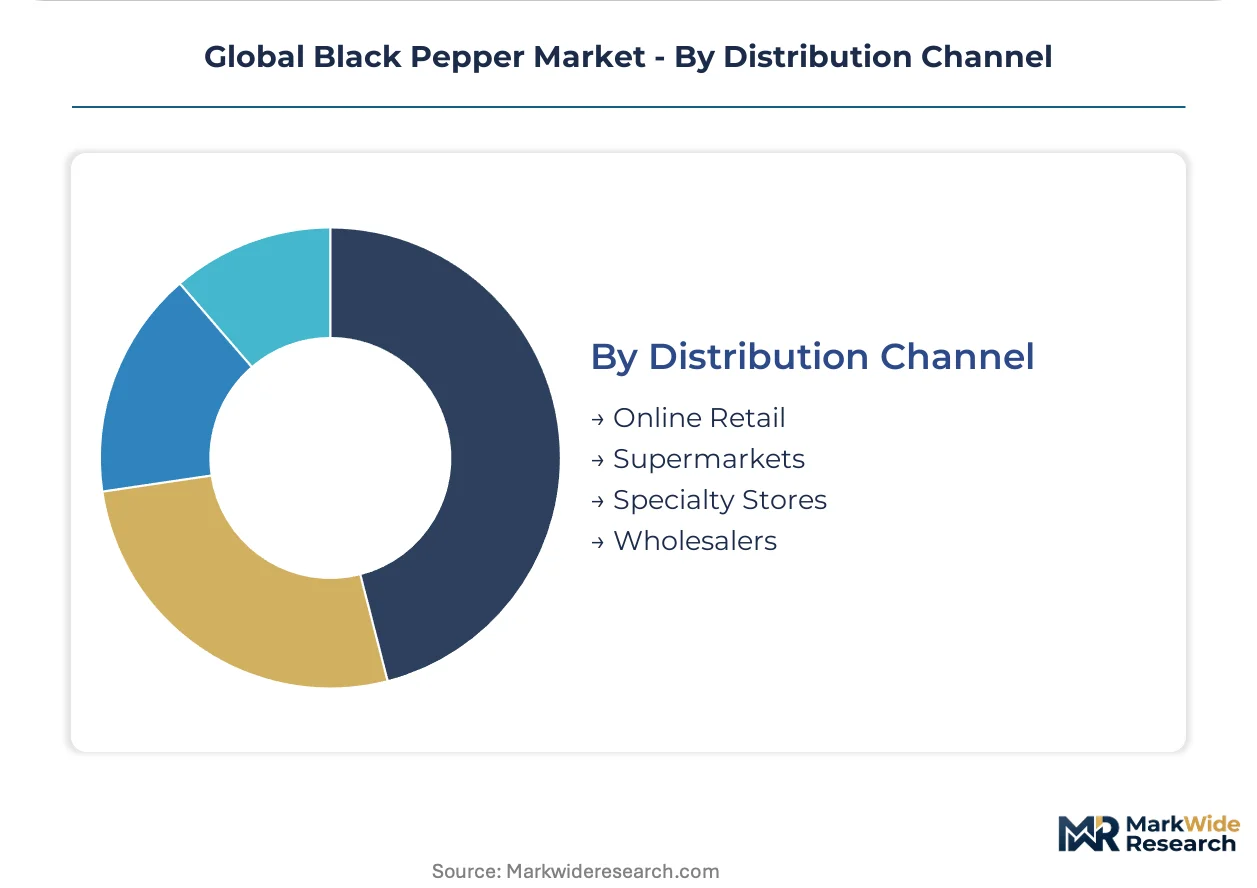
Distribution Channel:
Supply concentration patterns favor integrated processors with direct laboratory capabilities over fragmented trading networks.
- Wholesalers:Consolidated procurement from Vietnamese and Indonesian auction houses for redistribution to industrial processors. Traditional traders face margin compression as pharmaceutical buyers bypass intermediaries for blockchain-traceable direct contracts.
- Supermarkets:Branded retail placement with organic and fair-trade certification requirements.
- Online Retail:Direct-to-consumer channels for specialty cultivars and small-batch producers.
- Specialty Stores:Premium positioning for single-origin and terroir-differentiated peppercorns.
Wholesalers still handle the majority of export volume. Online Retail shows the steepest expansion trajectory among consumer-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting investment toward jurisdictions with lower compliance friction. Brazil and Vietnam attract capital as India's FSSAI mandates tighten traceability requirements. Processing capacity migrates to regions where mechanization offsets labor cost volatility.
Vietnam
Pharmaceutical-grade extraction contracts from German and Dutch buyers are concentrating in Binh Phuoc and Dak Lak provinces. The Plant Protection Department administers phytosanitary certification that determines EU market eligibility. Central Highlands processing clusters now integrate steam distillation with blockchain harvest documentation.
Indonesia
Lampung and Bangka-Belitung islands supply whole pepper volumes to Middle Eastern and Asian spice traders. The national standards body enforces sequential laboratory testing that extends export timelines. Kalimantan estates are retrofitting coffee harvesting equipment for mechanized peppercorn collection.
India
Kerala and Karnataka smallholders face displacement as FSSAI contaminant caps disqualify informal collection networks. CDSCO-registered laboratories certify batches for FDA-regulated pharmaceutical facilities. Kochi processing hubs are consolidating around integrated grinding and testing operations.
Brazil
Bahia and Espírito Santo provinces offer underutilized acreage with favorable rainfall patterns for new estate development. ANVISA alignment with USP standards facilitates pharmaceutical-grade export eligibility. Irrigated plantations with captive drying infrastructure are attracting private equity cultivation finance.
United States
North American nutraceutical brands are specifying USDA Organic recognition as baseline procurement criteria. FDA enforcement of cGMP for dietary supplements elevates documentation burdens on imported extracts. New Jersey and California flavor houses are consolidating vendor lists around REACH-registered Vietnamese suppliers.
Global Black Pepper Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. Food-grade channels favor volume processors with auction house relationships, while pharmaceutical procurement concentrates among integrated extractors with captive laboratory capabilities. Three archetypes dominate: estate operators with mechanized harvesting, toll processors with distillation capacity, and branded retailers with North American grocery density. Competitive moves center on backward integration into cultivation and pre-registration of piperine derivatives under EU REACH.
Among Vietnam-based processors, Phuc Sinh Corporation and Truong Thinh Agricultural Product Processing Co. Ltd. exemplify the estate-integrated archetype with mechanized harvesting infrastructure. McCormick and Company Inc anchors the branded retail tier through North American grocery channel positioning. Olam International Limited and Synthite Industries Private Ltd represent distinct specialization vectors—global procurement consolidation versus oleoresin extraction for industrial flavor applications.
| Leading Market Players |
|---|
| Everest Food Products Pvt Ltd |
| Baria Pepper Co Ltd |
| Olam International Limited |
| Robertet SA |
| Kancor Ingredients Limited |
| McCormick and Company Inc |
| Phuc Sinh Corporation |
| Truong Thinh Agricultural Product Processing Co. Ltd. |
| Synthite Industries Private Ltd |
| Others |
Supply Flow & Price Mechanics
Manual harvesting labor concentrated in Vietnam's Central Highlands and Indonesia's Lampung region feeds directly into pricing-tier spreads, with wage differentials between mechanized estates and smallholder networks creating a 40-60% gap between commodity-grade and pharmaceutical-grade pepper valuations. This workforce stratification compresses margins for traditional collectors while rewarding processors who integrate mechanical harvesting with captive drying infrastructure.
Pricing Analysis
Distributor margins on pharmaceutical-grade extracts run 15-25% above food-grade channels, with three-tier pricing structure across premium, standard, and economy levels anchored by certification intensity. FSSAI-compliant lots with third-party mycotoxin documentation command substantial premia over auction-house spot purchases. Pricing pressure stems from synthetic piperine competition in non-pharmaceutical applications. Food manufacturers exhibit highest price sensitivity; nutraceutical formulators prioritize alkaloid standardization over unit cost.
Supply Chain Analysis
Harvest labor availability in Vietnam's Binh Phuoc province and Indonesia's Bangka-Belitung islands fluctuates seasonally, constraining throughput at peak collection periods. Supply draws from Vietnamese mechanized estates, Indonesian smallholder networks, and emerging Brazilian plantations in Bahia. Raw material dependencies include irrigation infrastructure, drying equipment, and solvent supplies for extraction. Single-source vulnerability concentrates in Vietnamese export corridors. Distribution runs through integrated processors with direct laboratory capabilities, bypassing traditional auction houses for pharmaceutical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Brazil's ANVISA-aligned regulatory environment and underutilized acreage offer cost advantages against India's tightening FSSAI compliance burdens.
For Market Incumbents: Hedge against Vietnamese supply concentration by establishing parallel procurement corridors in Brazil's Espírito Santo province. Synthetic piperine substitution in food-grade channels demands defensive backward integration into extraction capacity. Prioritize REACH pre-registration for piperine derivatives to lock in European market access before competitor dossier submissions. For New Entrants and Emerging Players: Direct-to-manufacturer e-procurement platforms offer the lowest-friction entry vector for traceable, small-batch specialty cultivars. Target North American nutraceutical brands with blockchain-verified organic certification as the most penetrable buyer segment. Lead with genomic verification of Piper nigrum cultivars to differentiate from commodity auction supply. For Investors and Strategic Acquirers: Pharmaceutical formulators are the most active acquirer in this space, seeking captive extraction capacity for bioavailability-enhancement applications. Over a multi-year horizon, vertically integrated estate operators with mechanized harvesting and in-house distillation represent the highest-viability acquisition archetype. Monitor EU REACH registration deadlines as the critical inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Mechanized estates in Vietnam's Central Highlands capture labor-cost compression and quality standardization. |
| REACH Pre-registration | Expedited EU market access for piperine derivatives marginalizes non-compliant Vietnamese competitors. |
| Blockchain Traceability Implementation | Pharmaceutical buyers in Germany and the Netherlands now mandate harvest-to-destination documentation. |
| Steam Distillation Capacity Expansion | Continuous-flow systems reduce solvent use and qualify processors for industrial flavor-house contracts. |
| Organic Certification Investment | USDA Organic recognition serves as table stakes for North American nutraceutical procurement. |
Methodological Framework
Direct dialogue with estate operations managers, extraction facility technical directors, pharmaceutical procurement leads, and FSSAI-registered laboratory supervisors grounded the qualitative foundation. Secondary validation drew from Vietnam Plant Protection Department export records, Indian customs trade data, USDA National Organic Program certification databases, and EU REACH substance volume registrations. Bottom-up cultivation area estimates and top-down import value triangulation reconciled volume and value outputs.
Segmentation-level projections across product type, end user, packaging format, and regional production hub informed the analytical framework across the modeling period. CAGRs derived from historical trade flow analysis and forward-looking capacity expansion announcements. Key inputs included mechanization adoption curves in Vietnamese processing clusters and FSSAI contaminant cap implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for mechanical harvesting equipment retrofitted from coffee cherry systems would alter the outlook. Forecasts reflect assumptions regarding regulatory harmonization between Codex Alimentarius and major importing jurisdictions. Material deviation in REACH enforcement intensity or Vietnamese labor migration patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Peppermint Extract Market