
 Plastic Spice Jars Market | 2026-2036
Plastic Spice Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Spice Jars Market Outlook
North American blow-molding capacity for food-grade polypropylene is decoupling from traditional dairy and condiment lines to serve spice jar contracts. Berry Global Inc. leverages its multi-site extrusion footprint to anchor regional supply for retail spice brands. Pretium Packaging LLC sustains competitiveness through specialized barrier technologies that extend shelf stability for volatile compounds. Graham Packaging Company dominates the large-format segment with scaled hot-fill compatible jar platforms.
Plastic spice jars are injection- or blow-molded polyethylene terephthalate or polypropylene containers, typically featuring 38mm to 63mm neck finishes, designed for dry spice storage, moisture protection, and retail shelf visibility. Airtight jars with induction-sealed closures command premium positioning due to oxidation-sensitive spice preservation requirements. Screw cap configurations occupy the highest volume tier across wholesale and supermarket channels, while flip top formats are accelerating in online retail where single-hand dispensing drives consumer preference.
FDA food-contact substance regulations govern resin selection and additive migration limits for domestic U.S. spice packaging, while EPA guidelines on post-consumer recycled content influence converter sourcing strategies. ISO 22000 and HACCP frameworks shape quality protocols for export-oriented manufacturers supplying regulated markets. Stakeholders must monitor evolving extended producer responsibility legislation and bio-based resin certification standards as these will determine material cost structures and market access conditions.
Market Dynamics
California's SB 54 recycled-content mandates and New York's extended producer responsibility legislation are forcing converters to requalify resin formulations ahead of statutory deadlines, compressing R&D cycles across North American blow-molding operations.
Growth Catalysts
- Specialty food brand expansion:Private-label spice line proliferation by North American retailers is pulling container procurement volumes upward. Gourmet and ethnic seasoning portfolios require differentiated jar geometries that favor regional converter capabilities.
- India's processing cluster scale:Tamil Nadu and Gujarat spice processing hubs sustain substantial jar consumption through domestic packaging and export fulfillment. FSSAI food safety compliance requirements standardize quality thresholds for outbound shipments.
- Barrier technology maturation:Oxygen-scavenging additives and multilayer coextrusion are extending shelf stability for volatile spice compounds. Premium positioning for oxidation-sensitive products commands price premiums across retail channels.
Market Restraints
- Post-consumer recycled resin availability:FDA food-contact clearance for rPET and rPP remains limited to specific certified streams. Collection infrastructure gaps constrain supply scale for compliant spice jar production.
- Polypropylene feedstock volatility:Propylene monomer pricing tied to refinery output swings creates margin compression for injection molders. Energy cost pass-through mechanisms lag input spikes by one to two quarters.
- Glass jar substitution in premium segments:Specialty spice brands seeking tactile differentiation migrate toward amber glass for perceived quality signaling. Plastic faces ceiling effects in gift and artisan positioning tiers.
Strategic Opportunities
- Bio-based resin certification pathways:USDA BioPreferred and ASTM D6866 compliance frameworks open federal procurement and sustainability-positioned retail channels. Early certification creates first-mover access to ESG-mandated buyers.
- Single-serve and sampler formats:Online spice subscription services are driving demand for sub-50ml jar configurations. Direct-to-consumer fulfillment favors lightweight, shatter-resistant plastic over glass for shipping economics.
- Flip-top closure acceleration:One-handed dispensing mechanisms are displacing traditional screw caps in e-commerce channels. Consumer convenience preferences in digital-native purchasing environments favor ergonomic innovation.
Industry Challenges
- HACCP and ISO 22000 certification timelines:Export-oriented manufacturers face 12-to-18-month qualification periods for regulated market access. Auditor availability bottlenecks delay facility approvals.
- Induction sealing equipment retrofit costs:Legacy filling lines require capital expenditure for airtight closure integration. Mid-tier processors face upgrade-or-exit decisions as retail specifications tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Spice Jars Market |
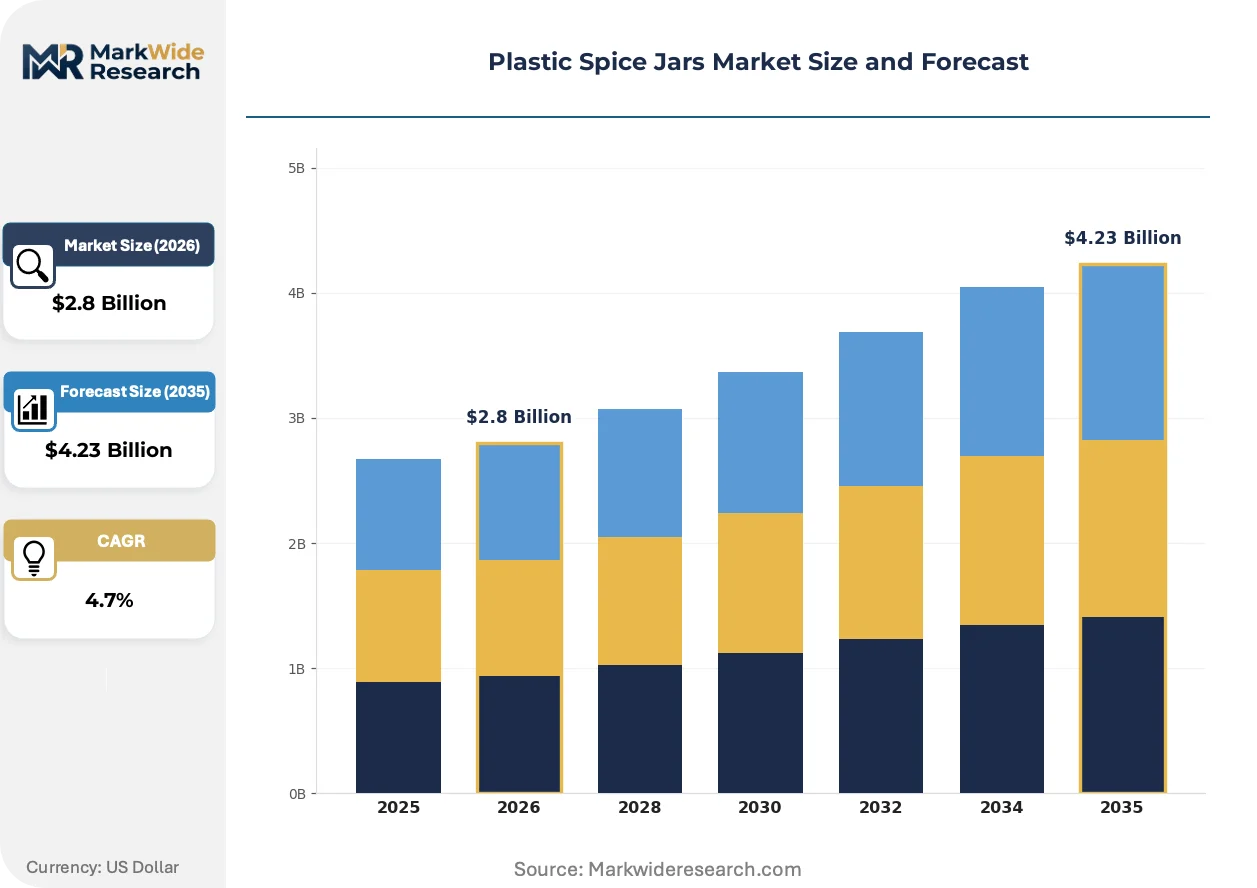
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Jars, Airtight Jars, Mini Jars, Custom Jars Capacity: 100ml, 250ml, 500ml, 1L Closure Type: Screw Cap, Flip Top, Pump Dispenser, Snap-On Lid Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Graham Packaging Company, Pretium Packaging LLC, Berry Global Inc., Berlin Packaging, Greiner Packaging, Amcor Plc, Plastipak Holdings, Inc., The Cary Company, ALPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Spice Jars Market Strategic Shifts
Material science advances and regulatory compliance automation are converging to redefine competitive differentiation in spice jar manufacturing. Converters are racing to integrate sustainability credentials without compromising barrier performance.
Monolayer-to-multilayer coextrusion migration is rewriting cost-performance tradeoffs for oxygen-sensitive spice preservation. Premium organic and single-origin brands are adopting five-layer EVOH barrier structures at accelerated pace. This technology is compressing the shelf-life gap between conventional plastics and metalized films while maintaining PET recyclability streams.
REACH SVHC disclosure requirements and EU Packaging and Packaging Waste Regulation amendments are mandating granular substance tracking across supply chains. European spice importers now demand full material composition documentation from Asian converters. Small-to-mid tier manufacturers lacking compliance infrastructure face market exclusion from the EU-27 trading bloc.
Direct sourcing from blow molders is displacing distributor-mediated procurement among large North American spice packers. Volume consolidation among retail private-label programs favors long-term converter contracts with dedicated capacity guarantees. This pattern is most visible in California and Texas processing corridors where co-located molding and filling operations minimize logistics friction.
Plastic Spice Jars Market Segmentation
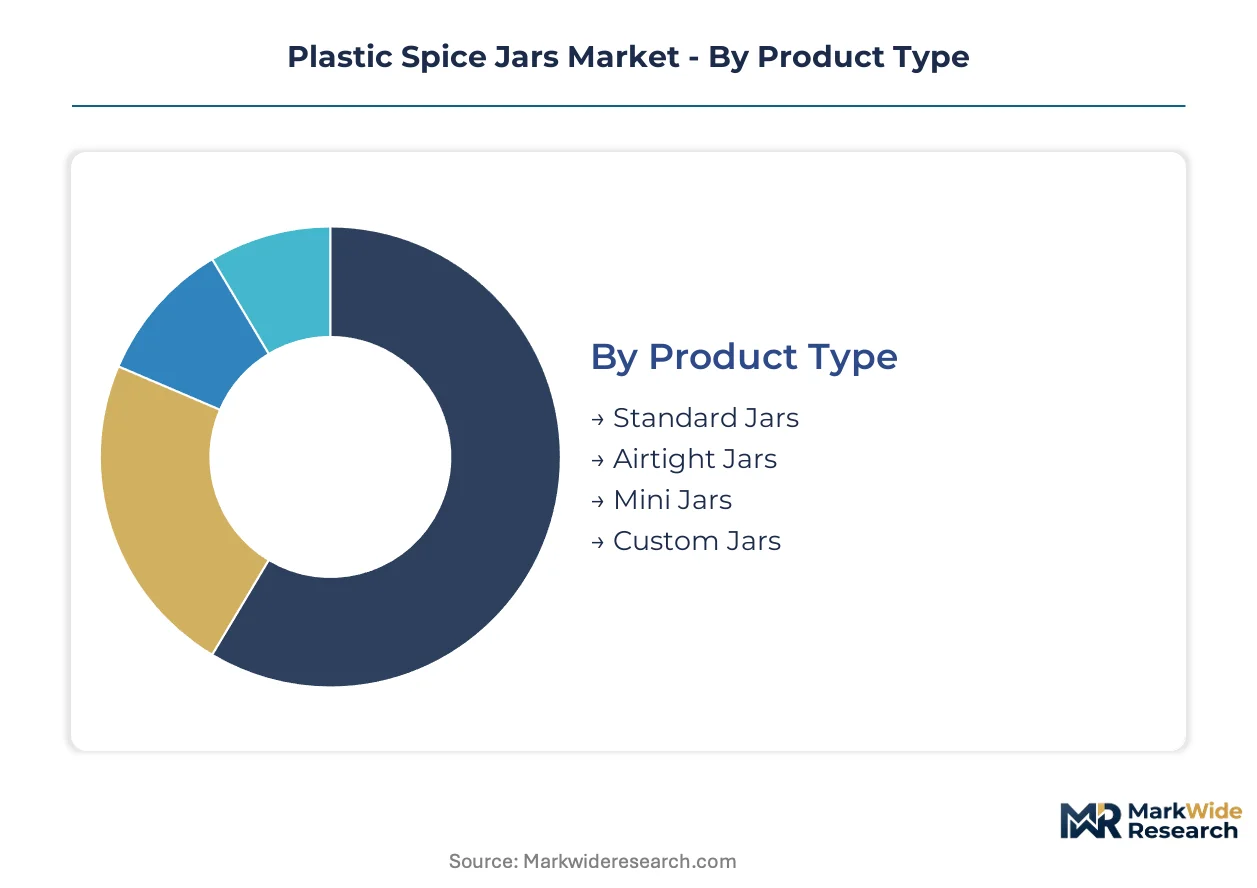
Segmentation in plastic spice jars reveals how converter investments align with shelf-life requirements, dispensing ergonomics, and channel-specific logistics. Each dimension carries distinct capital commitments and margin profiles that shape procurement negotiations between molders and spice packers.
Product Type:
Capital intensity peaks with multilayer barrier structures, where coextrusion equipment and oxygen-scavenging additive systems demand the heaviest upfront outlays.
- Airtight Jars:Five-layer EVOH barrier constructions with induction-sealed closures preserve volatile compounds in premium organic spice lines. California and New York private-label programs specify these configurations for extended shelf stability. FDA food-contact compliance for the scavenger additives extends qualification timelines.
- Standard Jars:Monolayer PET or PP containers with basic screw-cap sealing serve mass-market supermarket tiers. India’s Tamil Nadu processing clusters procure these at highest volume for domestic turmeric and chili powder packaging.
- Mini Jars:Sub-100ml configurations target sampler and travel formats.
- Custom Jars:Proprietary geometries for gourmet brand differentiation require dedicated mold fabrication.
Airtight jars absorb the bulk of installed coextrusion capacity; mini jars are expanding most quickly through e-commerce subscription channels.
Capacity:
Volume concentration determines blow-molding line economics, with 500ml formats achieving optimal machine utilization rates across converter footprints.
- 500ml:The workhorse specification for North American retail private-label programs balances material efficiency with household consumption patterns. Berry Global Inc. and Graham Packaging Company anchor regional supply for this tier. Hot-fill compatibility requirements drive resin selection toward clarified PP grades.
- 250ml:Mid-size formats dominate ethnic seasoning and specialty blends where turnover rates exceed standard pantry staples. Gujarat export processors favor this capacity for FSSAI-compliant outbound shipments to Middle Eastern markets.
- 100ml:Compact formats for premium single-origin spices and gift sets.
- 1L:Foodservice and institutional bulk packaging for restaurant supply chains.
500ml containers anchor converter utilization rates; 100ml formats are climbing the fastest through direct-to-consumer fulfillment models.
Closure Type:
Dispensing mechanism selection reflects channel-specific consumer behavior, with ergonomic innovation commanding tooling premiums.
- Screw Cap:Universal threading across 38mm to 63mm neck finishes dominates wholesale and supermarket procurement. Pretium Packaging LLC sustains competitiveness through tamper-evident band integration. Legacy filling lines accommodate this format without capital retrofit.
- Flip Top:One-handed dispensing mechanisms are displacing traditional closures in online retail environments. California-based spice subscription services specify these for unboxing experience differentiation. Hinge durability testing extends validation protocols.
- Pump Dispenser:Metered output for liquid spice blends and marinades.
- Snap-On Lid:Cost-minimized solutions for institutional and foodservice channels.
Screw caps retain the largest installed tooling base; flip tops are gaining share fastest among digital-native spice brands.
Distribution Channel:
Channel selection dictates packaging specifications, with shipping durability and shelf presentation requirements diverging sharply.
- Supermarkets:Retail-ready configurations with label adhesion optimized for high-humidity dairy aisles. Graham Packaging Company’s large-format platforms serve this channel through direct store delivery networks. Palletization efficiency drives secondary packaging design.
- Online Retailers:Lightweight, shatter-resistant plastic configurations displace glass for shipping economics. Texas and California co-located molding and filling operations minimize logistics friction for this channel. Drop-test certification requirements exceed retail specifications.
- Specialty Stores:Premium tactile finishes and transparent window panels for artisan positioning.
- Wholesale:Bulk pallet configurations with minimal primary packaging overhead.
Supermarkets absorb the majority of converter volume commitments; online retailers are expanding most quickly through subscription model proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene feedstock availability from Gulf Coast petrochemical corridors anchors North American converter positioning. FDA food-contact compliance requirements and state-level recycled-content mandates reshape procurement patterns across key processing clusters.
United States
Private-label spice line expansion by specialty food brands drives container procurement volumes. California's SB 54 mandates and New York's extended producer responsibility legislation compress R&D cycles for resin requalification. Texas and California co-located molding and filling operations minimize logistics friction for retail fulfillment.
India
Domestic spice processing and export packaging requirements sustain substantial jar consumption across regional hubs. FSSAI food safety compliance standardizes quality thresholds for outbound shipments to regulated markets. Tamil Nadu and Gujarat processing clusters anchor national production capacity for turmeric and chili powder packaging.
Germany
REACH SVHC disclosure requirements and EU Packaging and Packaging Waste Regulation amendments mandate granular substance tracking across supply chains. ECHA compliance frameworks shape converter qualification protocols for European spice importers. Industrial packaging corridors in North Rhine-Westphalia concentrate blow-molding capacity for continental distribution.
China
Export-oriented manufacturing scales to serve international brand procurement through cost-optimized monolayer configurations. GB standards and SAMR food-contact regulations govern resin selection for domestic market access. Yangtze River Delta processing zones cluster converter operations near polymer supply terminals.
Brazil
ANVISA pharmaceutical-grade packaging standards extend to spice jar specifications for cross-category manufacturers. Growing specialty food retail channels pull differentiated container geometries from regional molders. São Paulo state industrial districts concentrate injection-molding capacity for Mercosur distribution.
Plastic Spice Jars Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and barrier technology specialization. The vendor base stratifies across three maturity tiers: integrated multinationals with dedicated food-contact capacity, regional specialists leveraging proximity to spice processing clusters, and niche converters targeting subscription-commerce formats. Consolidation pressure intensifies as retail private-label programs demand long-term capacity guarantees. Dominant competitive moves include backward integration into resin compounding and geographic co-location with filling operations.
Within the integrated multinational tier, Berry Global Inc., Pretium Packaging LLC, and Graham Packaging Company exemplify scale-driven positioning. Berry Global anchors regional supply through multi-site extrusion footprints serving retail spice brands. Pretium occupies a specialization position through barrier technology capabilities. Graham Packaging represents large-format platform dominance with hot-fill compatible configurations. These entities collectively illustrate how converter investments align with shelf-life requirements, dispensing ergonomics, and channel-specific logistics demands.
| Leading Market Players |
|---|
| Graham Packaging Company |
| Pretium Packaging LLC |
| Berry Global Inc. |
| Berlin Packaging |
| Greiner Packaging |
| Amcor Plc |
| Plastipak Holdings, Inc. |
| The Cary Company |
| ALPLA |
| Others |
Value Chain & Pricing Dynamics
Backward integration into resin compounding anchors both supply security and pricing power for North American converters serving retail spice brands. Co-located molding and filling operations in Texas and California compress logistics friction while enabling premium capture for barrier-certified configurations.
Pricing Analysis
Warranty-backed shelf-life guarantees separate multilayer barrier jars from basic monolayer alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and oxygen-scavenging additive inclusion. Price differentiation hinges on FSSAI compliance documentation for India-bound exports and FDA food-contact clearance for domestic U.S. contracts. Cost compression in standard monolayer tiers is intensifying because polypropylene feedstock volatility from Gulf Coast refinery output swings squeezes injection molder margins. Mid-tier private-label buyers exhibit highest price sensitivity; premium organic spice brands prioritize barrier performance over unit cost.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Texas, and Gujarat form hub-and-spoke patterns for continental and export fulfillment. Geographic supply concentration centers on the United States, India, and Germany for converter capacity; China and Brazil serve secondary sourcing roles. Raw material dependencies draw from propylene monomer streams, EVOH barrier resin, and post-consumer recycled PET certified for food contact. Single-source vulnerability runs through FDA-cleared rPET supply streams where collection infrastructure gaps constrain compliant feedstock scale. Distribution runs through direct converter relationships for large North American spice packers and distributor-mediated procurement for mid-tier regional brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multilayer coextrusion technology is displacing monolayer legacy configurations across premium spice packaging tiers. This transition compresses shelf-life performance gaps while rewriting capital deployment priorities for converters and packers alike.
For Market Incumbents: Anchor barrier technology leadership through five-layer EVOH capacity additions in California and Texas corridors. Defend against glass jar substitution in gift segments by accelerating bio-based resin certification under USDA BioPreferred frameworks. Co-locate molding operations with filling lines to lock in long-term private-label contracts as retail consolidation intensifies. For New Entrants and Emerging Players: Oxygen-scavenging additive specialization offers entry into premium organic spice lines where incumbent converters underinvest. Target sub-50ml mini jar formats for direct-to-consumer subscription channels where ergonomic flip-top innovation commands tooling premiums. Pursue FSSAI certification early to access Gujarat and Tamil Nadu export processing clusters before auditor bottlenecks tighten. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated packaging multinationals seeking barrier technology capabilities. Long-term viability favors converters with certified post-consumer recycled resin access and co-located filling partnerships. Watch induction sealing equipment retrofit adoption rates among mid-tier processors as the signal for specification tightening inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Certification | Five-layer EVOH coextrusion capacity secures premium organic spice contracts under FDA food-contact mandates. |
| Backward Integration into Resin Compounding | In-house PP compounding insulates margins from Gulf Coast propylene monomer volatility swings. |
| Co-location with Filling Operations | Texas and California integrated sites minimize logistics friction for retail private-label fulfillment. |
| Bio-based Resin Certification | USDA BioPreferred compliance opens federal procurement and ESG-mandated retail channels. |
| Flip-top Closure Platform Development | One-handed dispensing mechanisms capture e-commerce subscription growth in digital-native spice brands. |
Study Parameters
Multi-period observation of converter capacity utilization, resin pricing spreads, and retail private-label procurement patterns anchored the trend analysis, supplemented by interviews with blow-molding plant managers, spice brand procurement leads, and FDA regulatory affairs specialists. Secondary validation drew from customs trade data, SEC 10-K filings of listed packaging companies, state-level recycled-content mandate documentation, and FSSAI compliance registries. Bottom-up segment sizing triangulated against top-down market value estimates derived from polymer consumption benchmarks.
Input-output matrices mapped resin feedstock availability through converter capacity to end-use spice packaging demand across the projection horizon. Segmentation dimensions modeled include barrier technology tier, closure mechanism type, capacity specification, and regional regulatory cluster. CAGRs were synthesized from volume trajectory analysis and value-per-unit trends. Forecast inputs incorporated propylene monomer pricing elasticity and post-consumer recycled resin supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA recycled-content mandate acceleration or propylene supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Global Oregano Essential Oil Market