
 Sriracha Market | 2026-2036
Sriracha Market Size, Share, and Industry Trends Forecast 2026-2036
Sriracha Market Insights
Premium-grade chili sourcing is rotating toward traceable, single-origin cultivars as buyers demand cleaner labels. Huy Fong Foods leverages its iconic rooster brand and California production base to sustain decades of cult loyalty. McCormick & Company anchors shelf presence through massive retail distribution networks spanning conventional and club channels. Flying Goose specializes in Thai-authentic formulations that compete on heritage credibility against Americanized variants.
Sriracha is a fermented chili-garlic sauce produced from red jalapeño or cayenne peppers, distilled vinegar, garlic, sugar, and salt, with heat levels typically measured at 2,200 Scoville units; manufacturers ferment mash for several days to develop the signature tangy-sweet profile before pasteurization and bottling. The product serves as a tabletop condiment, cooking ingredient, and industrial flavoring agent across food manufacturing and foodservice operations. Classic Sriracha still dominates volume, though organic Sriracha commands disproportionate margin as clean-label households trade up. Foodservice distribution channels are expanding fastest, driven by quick-service restaurants integrating sriracha into proprietary sauces and limited-time offerings.
The FDA enforces acidified food regulations under 21 CFR 114, requiring sriracha processors to file scheduled processes for pH control and thermal treatment. USDA Organic certification, administered by accredited third-party bodies, gates access to the premium tier where unit economics improve significantly. FSMA's supplier verification mandates are forcing smaller brands to invest in documented supply chains or exit retail. Stakeholders must monitor whether clean-label momentum shifts toward no-sugar-added variants, as that formulation pivot could reshape ingredient sourcing and production economics.
Market Dynamics
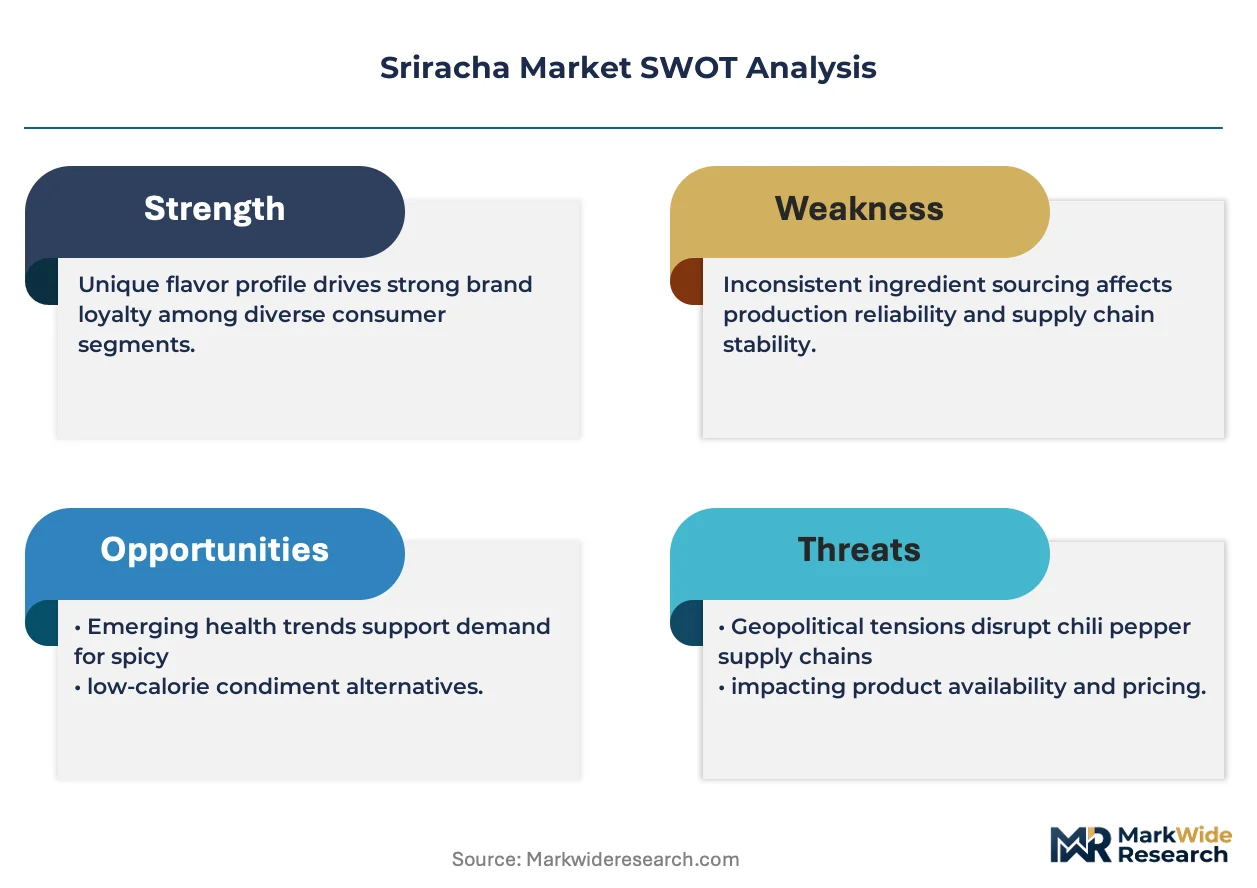
FDA's updated FSMA supplier verification mandates are compressing the vendor base as smaller sriracha brands face documented supply chain requirements they cannot meet, concentrating volume among processors with captive pepper sourcing and in-house fermentation capacity.
Growth Catalysts
- Clean-label certification:USDA Organic accreditation opens premium retail placement and margin expansion for processors willing to absorb third-party audit costs. Certified brands capture shelf space in club and natural channels.
- Quick-service restaurant integration:Chains like Chipotle and Subway have embedded sriracha into proprietary sauces, creating institutional demand that stabilizes offtake volumes. Foodservice distribution channels now outpace retail velocity.
- California jalapeño cultivation:Kern County and Ventura County pepper growers supply Huy Fong Foods with traceable, short-haul raw material that reduces spoilage risk and supports same-day processing claims.
Market Restraints
- Jalapeño supply concentration:California and Mexico account for the bulk of suitable pepper cultivars, leaving processors exposed to drought-driven crop failures and water-right disputes in the Colorado River basin.
- Acidified food compliance:FDA 21 CFR 114 scheduled process filings require specialized thermal treatment equipment that smaller entrants cannot finance, creating a capital barrier to market entry.
- Hot sauce substitution:Tabasco, Cholula, and regional chili crisp alternatives compete for the same tabletop and cooking occasions, limiting sriracha's share of wallet in condiment repertoires.
Strategic Opportunities
- Thailand heritage positioning:Si Racha province origin stories and Thai-authentic formulations command price premiums in European and Asian markets where provenance carries culinary credibility.
- No-sugar-added variants:Keto and diabetic-friendly formulations open access to clean-label households that have exited conventional sriracha due to sucrose content, requiring reformulation of fermentation substrates.
- E-commerce direct-to-consumer:Subscription boxes and specialty food platforms bypass slotting fee barriers in conventional retail, enabling artisanal brands to build tribe followings before seeking mass distribution.
Industry Challenges
- Fermentation science expertise:Commercial-scale mash management requires microbiologists who can stabilize pH and control lactobacillus cultures across batch variability, a skill set concentrated in legacy processors.
- Labeling compliance timelines:FDA nutrition panel updates and added-sugar disclosure mandates force packaging redesigns that consume 12-18 month lead times, delaying reformulation launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sriracha Market |
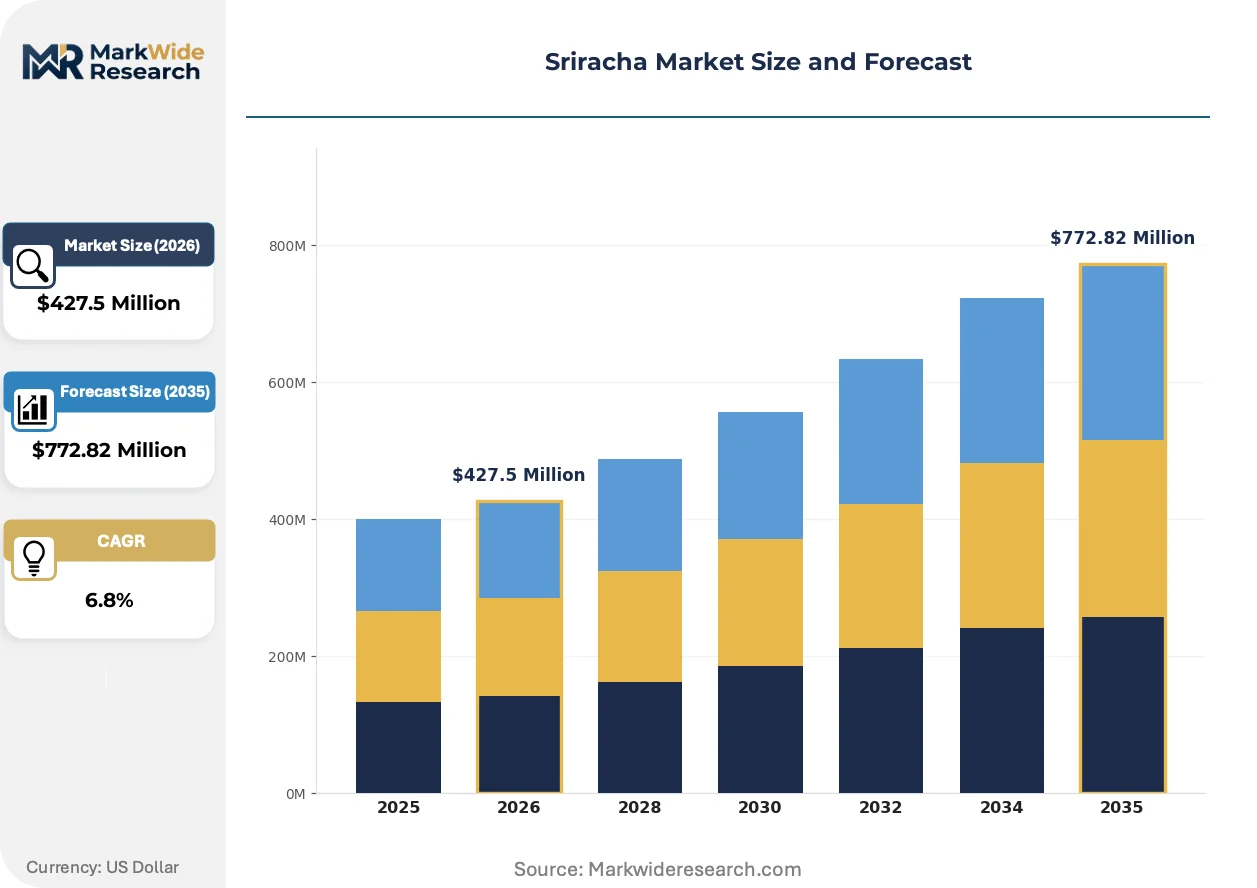
| Market Size in 2026 | $427.5 Million |
| Market Size in 2035 | $772.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Sriracha, Organic Sriracha, Hot Chili Sauce, Sweet Sriracha Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice Packaging Type: Bottles, Jars, Sachets, Bulk Containers End User: Households, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | Flying Goose, McIlhenny Company, Huy Fong Foods, The Kraft Heinz Company, Cholula Food Company, Lee Kum Kee, Sky Valley, McCormick & Company, Sriraja Panich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sriracha Market Trends and Innovations
Automation in mash handling and regulatory digitization are compressing production cycles while clean-label fermentation substrates are opening formulation white space previously locked by traditional recipes.
Continuous fermentation monitoring using IoT pH and temperature sensors is supplanting manual batch sampling in mid-scale sriracha operations. California processors are adopting these systems fastest to maintain FSMA documentation trails. The technology is enabling real-time process adjustments that reduce spoilage rates and compress batch-to-bottle timelines.
EU Green Deal farm-to-fork traceability requirements are reshaping export compliance for American sriracha brands seeking European shelf placement. Processors must now document pepper cultivar origin, agricultural chemical applications, and carbon intensity across the supply chain. Organic-certified variants face the steepest documentation burden but command the price premiums that justify compliance investment.
Home cooking experimentation has shifted sriracha from tabletop drizzle to integrated cooking ingredient, with recipe developers incorporating the condiment into marinades, glazes, and compound butters. Food media channels on YouTube and TikTok are driving this behavioral pivot fastest among millennial and Gen-Z households. This consumption-pattern shift is expanding per-household volume beyond traditional condiment usage rates.
Sriracha Market Segmentation
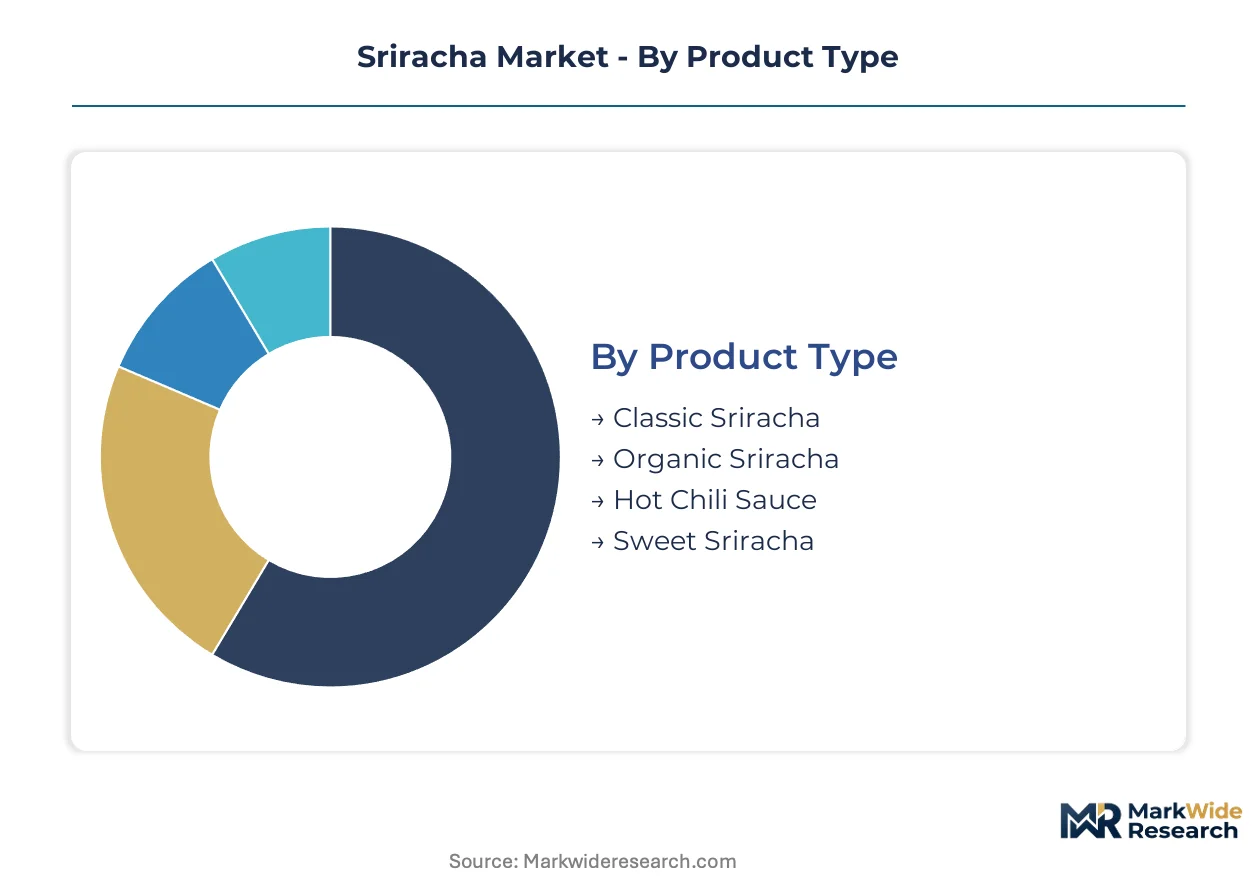
Sriracha's market structure fragments across formulation intensity, procurement channel, and end-use application. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Domestic consumption concentrates in classic and organic variants, while export demand pulls toward heritage-authentic formulations. Thai-origin positioning commands premium placement in European and Asian retail.
- Classic Sriracha:Fermented red jalapeño mash with distilled vinegar, garlic, sugar, and salt delivers the signature 2,200 Scoville heat profile. US households and quick-service chains anchor volume, though drought risk in California and Mexico pepper belts constrains supply security.
- Organic Sriracha:USDA-certified formulations substitute conventional peppers with organically cultivated cultivars and eliminate synthetic processing aids. Club and natural channel placement in the United States drives disproportionate margin expansion despite third-party audit burdens.
- Hot Chili Sauce:Elevated heat variants using habanero or ghost pepper extensions target enthusiast segments.
- Sweet Sriracha:Reduced-acidity profiles with amplified sucrose content compete for younger household palates.
Classic Sriracha holds the largest share; momentum sits with Organic Sriracha.
Distribution Channel:
Channel economics diverge sharply between high-frequency retail replenishment and institutional foodservice contracts. Slotting fee structures favor incumbents with balance sheet depth.
- Supermarkets:Conventional and club retail chains generate baseline velocity through planogram placement. Kroger and Costco volume in the United States stabilizes offtake for processors with national distribution infrastructure.
- Foodservice:Quick-service restaurant integration and contract food manufacturing create institutional demand with multi-year supply agreements. Chipotle and Subway proprietary sauce programs exemplify this channel's volume concentration.
- Online Retail:Amazon and specialty food platforms enable direct-to-consumer trial without slotting fee barriers.
- Specialty Stores:Independent grocers and ethnic food retailers serve heritage-seeking consumers.
Supermarkets maintain volume dominance; Foodservice is climbing the fastest.
Packaging Type:
Format selection tracks end-use scale and consumption occasion frequency. Industrial users prioritize total cost of ownership over unit aesthetics.
- Bottles:Standard PET and glass containers with precision dispensing caps dominate household tabletop placement. Retail shelf visibility and brand recognition drive continued format investment despite higher per-unit logistics cost.
- Bulk Containers:Food manufacturers and contract caterers source 5-gallon pails and drums for ingredient-scale incorporation. Industrial procurement emphasizes lot traceability and pH stability documentation under FDA acidified food regulations.
- Jars:Wide-mouth glass formats serve cooking-ingredient positioning.
- Sachets:Single-serve packets target foodservice portion control and airline catering.
Bottles capture household penetration; Bulk Containers are gaining share fastest in institutional segments.
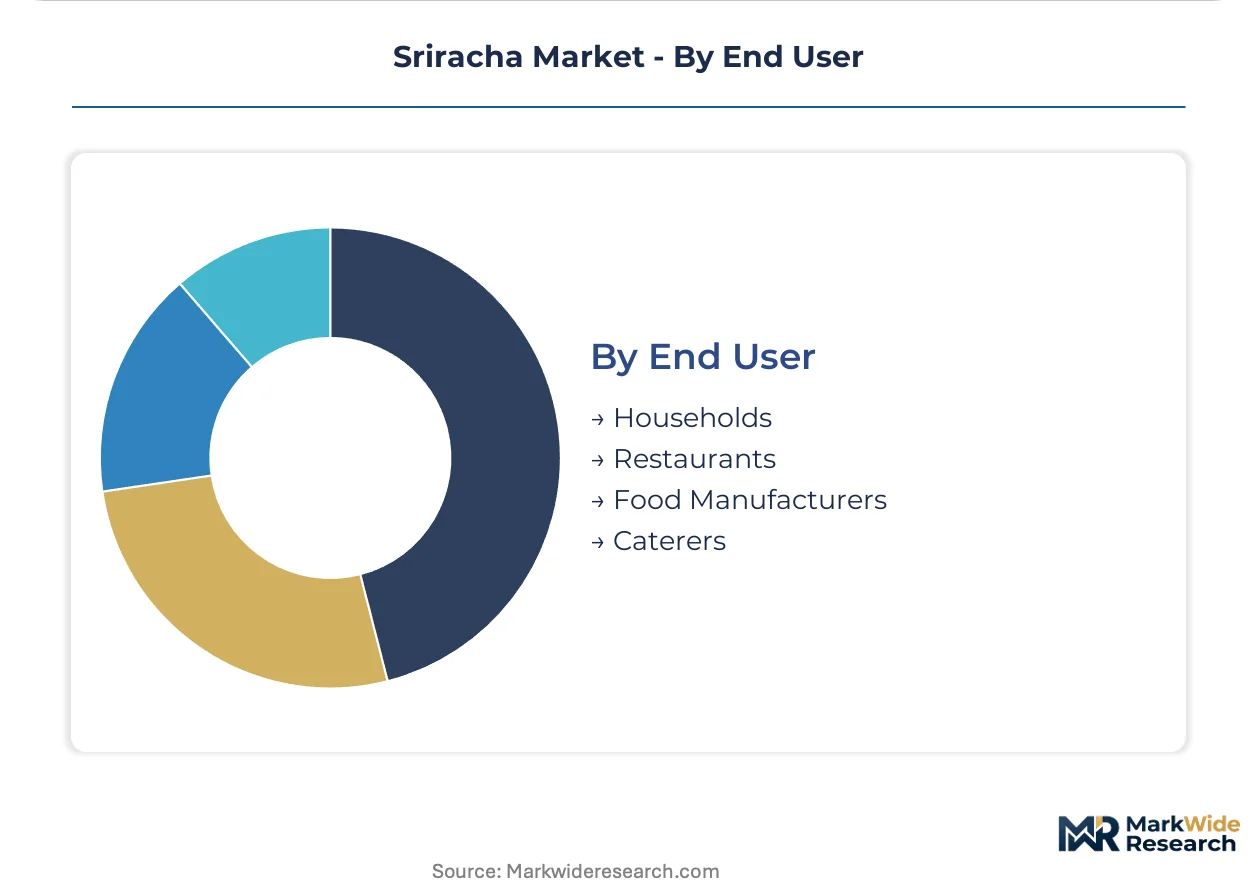
End User:
User segmentation maps directly to formulation complexity and procurement authority. Direct purchasing power varies enormously across the matrix.
- Restaurants:Independent operators and chain accounts specify sriracha for tabletop service and kitchen integration. Menu innovation cycles at Chipotle and Subway drive proprietary formulation demand with customized heat and viscosity profiles.
- Food Manufacturers:Industrial processors incorporate sriracha into snack seasonings, ready-meal sauces, and protein marinades. FSMA supplier verification mandates force documented supply chain transparency that smaller processors cannot satisfy.
- Households:Consumer pantry stocking follows media-driven recipe experimentation on TikTok and YouTube.
- Caterers:Event-scale foodservice demands bulk procurement with flexible delivery scheduling.
Restaurants hold the largest share; Food Manufacturers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai sriracha exports flow primarily toward the United States and European Union, where commercial adoption outpaces domestic Asian markets. This trade corridor shapes production priorities across origin and destination geographies alike.
United States
Quick-service restaurant chains and home cooking experimentation drive volume. FDA 21 CFR 114 acidified food regulations govern pH control and thermal treatment protocols. Huy Fong Foods operates from Irwindale, California, leveraging Kern County jalapeño supply chains for same-day processing.
Thailand
Si Racha province heritage positioning commands premium placement in European and Asian retail channels. Thai FDA regulations align with ASEAN harmonized food safety standards for fermented condiment exports. Chonburi province processors specialize in authentic formulations targeting provenance-seeking consumers.
Germany
Ethnic food retail expansion and clean-label household demand pull imports from both Thai and American sources. EU Green Deal farm-to-fork traceability requirements mandate documented pepper cultivar origin and carbon intensity disclosure. Hamburg and Frankfurt distribution hubs consolidate continental re-export activity.
United Kingdom
Foodservice integration and recipe media influence sustain per-household consumption growth. Food Standards Agency enforcement of retained EU food safety regulations maintains acidified food compliance standards. London metropolitan area retailers anchor national distribution for premium organic variants.
Canada
Cross-border supply chain integration with American processors supports retail and foodservice penetration. Health Canada and CFIA regulations govern acidified food imports with documentation requirements mirroring FDA frameworks. Toronto and Vancouver metropolitan markets concentrate ethnic grocery and natural channel placement.
Sriracha Market Competitive Landscape
Listed leaders compete with private specialists across brand heritage and production scale dimensions. The vendor base concentrates around three tiers: legacy rooster-brand incumbents, diversified condiment conglomerates, and Thai-authentic heritage specialists. Dominant competitive moves include proprietary formulation partnerships with quick-service chains and backward integration into captive pepper cultivation.
Among American processors, Huy Fong Foods exemplifies the cult-brand archetype through California-based production and decades of category-defining presence. McCormick & Company represents the diversified conglomerate model with shelf presence spanning conventional and club retail channels. Flying Goose occupies a position within the Thai-authentic specialist tier, competing on provenance credibility against Americanized formulation variants.
| Leading Market Players |
|---|
| Flying Goose |
| McIlhenny Company |
| Huy Fong Foods |
| The Kraft Heinz Company |
| Cholula Food Company |
| Lee Kum Kee |
| Sky Valley |
| McCormick & Company |
| Sriraja Panich |
| Others |
Pricing and Supply Chain Analysis
California fermentation capacity utilization above 85% anchors price floors for domestic processors while compressing margins for smaller entrants lacking captive pepper supply. Scale advantages at Huy Fong Foods' Irwindale facility translate into procurement leverage over Kern County growers that mid-tier competitors cannot replicate, concentrating volume-based pricing power among legacy operators with in-house mash management.
Pricing Analysis
Conventional fermentation equipment depreciation gaps separate established processors from new entrants facing capital recovery premiums on pH-controlled thermal systems. Three-tier pricing structure across USDA Organic certified, conventional retail, and foodservice bulk separates margin profiles by certification burden and volume commitment. Cost compression in conventional retail tiers stems from drought-driven jalapeño spot market volatility. Quick-service restaurant procurement teams exhibit lowest price sensitivity due to proprietary formulation lock-in, while independent grocers face acute margin pressure from slotting fee structures.
Supply Chain Analysis
Jalapeño cultivar germplasm concentration in California's Central Valley and Mexico's Chihuahua state creates single-source vulnerability for processors dependent on specific heat-profile genetics. Fermentation-grade pepper mash, distilled vinegar supply, and specialized pH monitoring equipment constitute critical input dependencies. Tariff exposure on Mexican agricultural imports threatens cost predictability for cross-border supply arrangements. Distribution runs through foodservice redistribution centers and club retail consolidation hubs that favor pallet-scale procurement minimums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sriracha penetration in European retail and Asian food manufacturing remains below saturation thresholds, creating runway for heritage-positioned entrants and organic-certified specialists alike. Quick-service restaurant sauce program integration continues expanding institutional offtake beyond traditional condiment velocity.
For Market Incumbents: Compound fermentation science expertise through microbiologist retention programs and proprietary lactobacillus culture libraries that emerging competitors cannot license. Deepen backward integration into captive pepper cultivation in Ventura County to insulate against Colorado River basin water-right disputes threatening California supply security. Secure multi-year quick-service restaurant proprietary formulation contracts before Thai-authentic heritage brands penetrate North American foodservice channels. For New Entrants and Emerging Players: E-commerce direct-to-consumer subscription gaps where Huy Fong Foods maintains minimal presence offer white-space access without slotting fee barriers. Target no-sugar-added formulation segments in keto and diabetic-friendly households that have exited conventional sriracha due to sucrose content. Deploy Thailand heritage storytelling through TikTok recipe developer partnerships to build tribe followings before seeking mass retail distribution. For Investors and Strategic Acquirers: Thai-authentic specialists with Si Racha province provenance documentation and EU Green Deal traceability compliance represent priority acquisition targets for premium export positioning. Long-term viability hinges on fermentation science talent concentration and FSMA documentation infrastructure that smaller processors cannot finance independently. Watch for FDA acidified food regulation enforcement intensity as inflection signal for vendor base consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pepper Cultivation | Kern County captive supply secures same-day processing claims against drought risk. |
| USDA Organic Certification Investment | Third-party audit costs unlock club channel placement with disproportionate margin expansion. |
| Quick-Service Restaurant Partnership | Chipotle and Subway proprietary sauce programs stabilize multi-year offtake volumes. |
| E-commerce Direct-to-Consumer Launch | Subscription platforms bypass slotting fees for artisanal brand tribe building. |
| Thailand Heritage Repositioning | Si Racha province origin stories command European retail premium placement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service restaurant procurement directors, fermented condiment plant managers, retail category buyers, and USDA-accredited organic certification auditors. Secondary validation drew from FDA 21 CFR 114 scheduled process filings, USDA Organic integrity database records, EU Green Deal farm-to-fork traceability documentation, and customs trade data on Thai sriracha export flows. Bottom-up volume modeling triangulated against top-down category spend estimates from foodservice redistribution networks.
Across the projection horizon, the analytical framework segmented volume and value by product type, distribution channel, packaging format, and end-user application with particular attention to fermentation substrate differentiation. CAGRs derived from historical velocity trends in club retail and foodservice channels, adjusted for jalapeño supply concentration risk and FSMA compliance cost trajectories. Modeled inputs included California agricultural water allocation forecasts and quick-service restaurant menu innovation cycle frequencies.
Forecasts assume regulatory continuity in FDA acidified food enforcement and EU Green Deal traceability mandates; material policy shifts in either regime would require re-modeling supply chain compliance cost burdens. Drought severity in the Colorado River basin and Thai FDA export certification timelines constitute specific risk factors that could revise volume assumptions. Practitioners should keep alternative scenarios live as climate-driven agricultural disruption patterns and fermentation science labor market tightness evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Dried Spices Market