
 Rutile Market | 2026-2036
Rutile Market Size, Share, and Industry Trends Forecast 2026-2036
Rutile Market Outlook
Australia is rewriting supply dynamics through expanded mineral sands capacity along its western and southeastern coasts. Rio Tinto leverages integrated titanium feedstock operations from mine to pigment precursor. Iluka Resources Limited anchors heavy mineral concentrate output through its Eneabba and Jacinth-Ambrosia sites. Tronox Holdings PLC sustains backward integration into rutile slag and synthetic rutile conversion.
Rutile is a titanium dioxide mineral with a tetragonal crystal structure and TiO₂ content typically exceeding 95%, extracted from heavy mineral sands deposits through gravity and magnetic separation for use as premium pigment feedstock and titanium metal precursor. Synthetic rutile commands widening preference as chloride-route TiO₂ plants seek higher-grade feedstock with lower impurity loads than natural concentrates. Paints and coatings applications dominate volume offtake, while plastics formulations represent the fastest-expanding application segment as polymer producers substitute legacy fillers. Construction end-use absorbs the largest share of pigment-grade material, whereas automotive coatings demand concentrates margin pools in premium sheet and granule forms.
EPA oversight of mining effluent standards and REACH registration requirements for titanium dioxide classifications shape product specifications and market access conditions in North America and Europe. Australia's state-level environmental protection agencies enforce rehabilitation bonds and tailings management protocols that constrain greenfield project timelines. Stakeholders must monitor chloride-versus-sulfide process economics and feedstock substitution thresholds as synthetic rutile capacity decisions determine long-term contract structures.
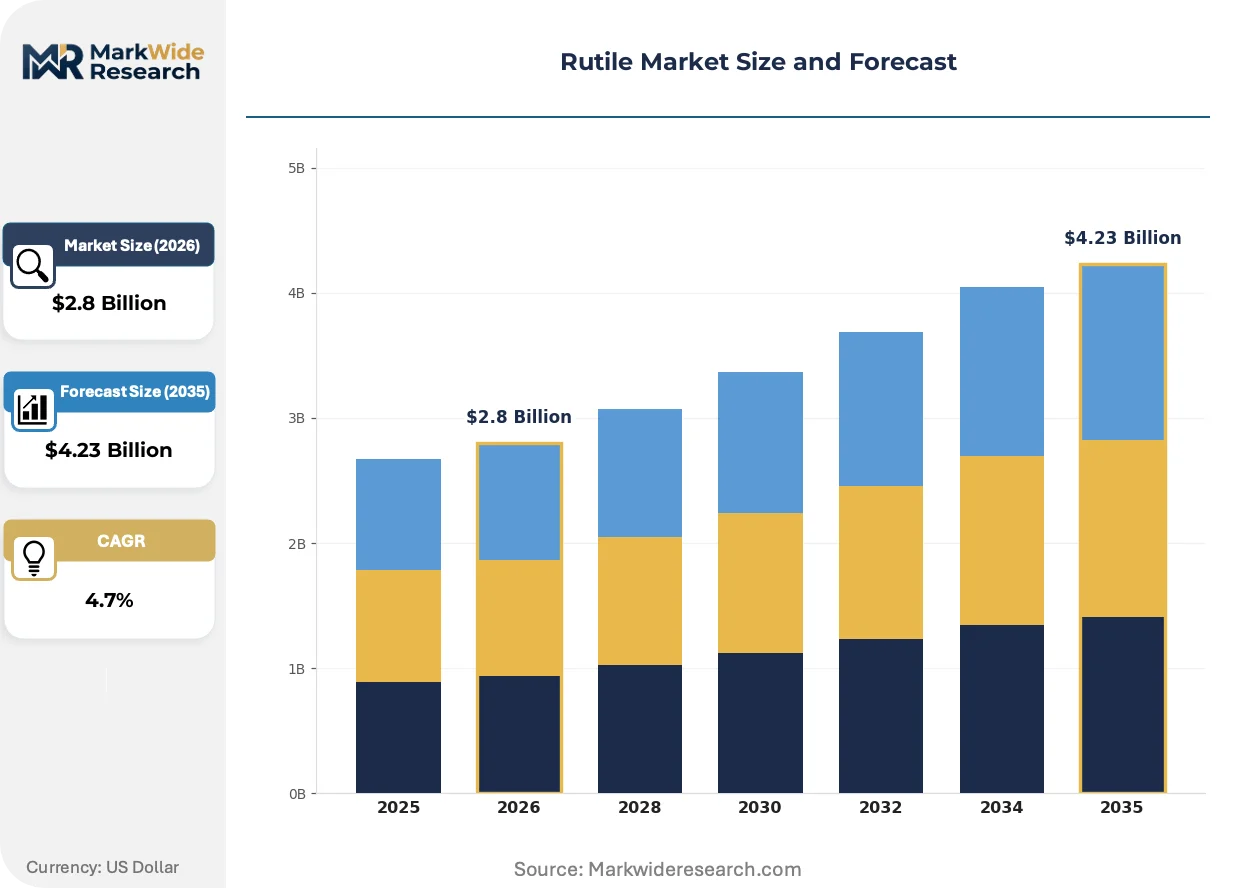
Market Dynamics
Chloride-process titanium dioxide plants are consolidating feedstock procurement around higher-purity synthetic rutile, compressing contract structures for natural concentrate suppliers and rewiring long-term offtake negotiations across the value chain.
Growth Catalysts
- REACH pigment purity mandates:European ECHA thresholds for titanium dioxide feedstock are disqualifying lower-grade ilmenite sources and redirecting volume toward premium rutile channels.
- Plastics compound substitution:Polymer producers in automotive and packaging verticals are replacing legacy calcium carbonate fillers with TiO₂-bearing masterbatches to achieve opacity and UV resistance.
- Sierra Leone extraction expansion:Coastal heavy mineral sands development is diversifying supply origins beyond Australian concentration and adding Atlantic basin logistics options.
Market Restraints
- Natural gas cost volatility:Synthetic rutile conversion via the Becher process consumes substantial thermal energy, exposing margins to feedstock fuel price swings in Western Australia.
- Australian supply concentration:Eneabba and Jacinth-Ambrosia deposits control disproportionate global heavy mineral concentrate output, creating single-jurisdiction disruption risk.
- Ilmenite substitution pressure:Sulfate-route TiO₂ plants in developing markets continue accepting lower-grade feedstock at price discounts that undercut rutile premiums.
Strategic Opportunities
- Indian chloride-route expansion:Domestic TiO₂ producers are evaluating synthetic rutile import substitution as BIS standards tighten and PLI scheme incentives favor integrated feedstock security.
- Titanium metal aerospace demand:Sponge producers for airframe and engine applications require ultra-high-purity rutile as Kroll process feedstock, opening specialty margin pools distinct from pigment economics.
- EU Green Deal carbon border adjustments:Embodied emissions tracking is advantaging Australian and African coastal mining with lower transport footprints versus Chinese ilmenite-slag alternatives.
Industry Challenges
- Heavy mineral sands processing expertise:Gravity and magnetic separation specialists are scarce as veteran plant operators retire without sufficient knowledge transfer to next-generation technical staff.
- Tailings rehabilitation bonding:Australian state environmental protection agencies demand escalating financial assurances that strain junior developer balance sheets and extend project financing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rutile Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rutile TiO2, Natural Rutile, Synthetic Rutile, Pigment Grade Rutile Application: Paints, Plastics, Coatings, Rubber End User: Construction, Automotive, Electronics, Aerospace Form: Powder, Granules, Pellets, Sheets |
| Companies Covered | Rio Tinto, IREL (India) Limited, Sierra Rutile, TOR Minerals, V.V. Mineral, Tronox Holdings PLC, East Minerals, Kerala Minerals & Metals Ltd, Iluka Resources Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rutile Market Strategic Shifts
Feedstock qualification protocols and process chemistry adaptations are compressing the acceptable impurity window for chloride-route TiO₂ production, forcing upstream mineral processors to reengineer beneficiation circuits and thermal treatment stages.
High-temperature fluidized bed chlorination is migrating from traditional natural rutile feedstock toward upgraded synthetic rutile with controlled porosity and surface area. Major chloride-route pigment producers are qualifying these engineered materials to reduce unreacted coke consumption and improve TiCl₄ yield. The shift is compressing demand for conventional natural concentrate grades that lack the tailored physical properties for optimized chlorinator performance.
EPA effluent limitations guidelines for mineral mining are tightening allowable heavy metals discharge from wet separation circuits. US-based heavy mineral sands operations must retrofit closed-loop water systems and deploy advanced flocculation technologies to meet revised permit thresholds. The regulatory pressure is accelerating capital deployment toward zero-liquid-discharge configurations that raise baseline operating costs but secure operating continuity.
Long-term offtake contracting is giving way to shorter-duration agreements with price reopeners indexed to TiO₂ pigment spot markets. Buyers in paints and coatings formulations are resisting fixed-price multi-year commitments given feedstock cost volatility, while suppliers seek volume certainty through minimum tonnage clauses with flexible pricing mechanics. The behavioral shift is most pronounced in European procurement desks managing REACH compliance costs alongside raw material budget uncertainty.
Rutile Market Segmentation
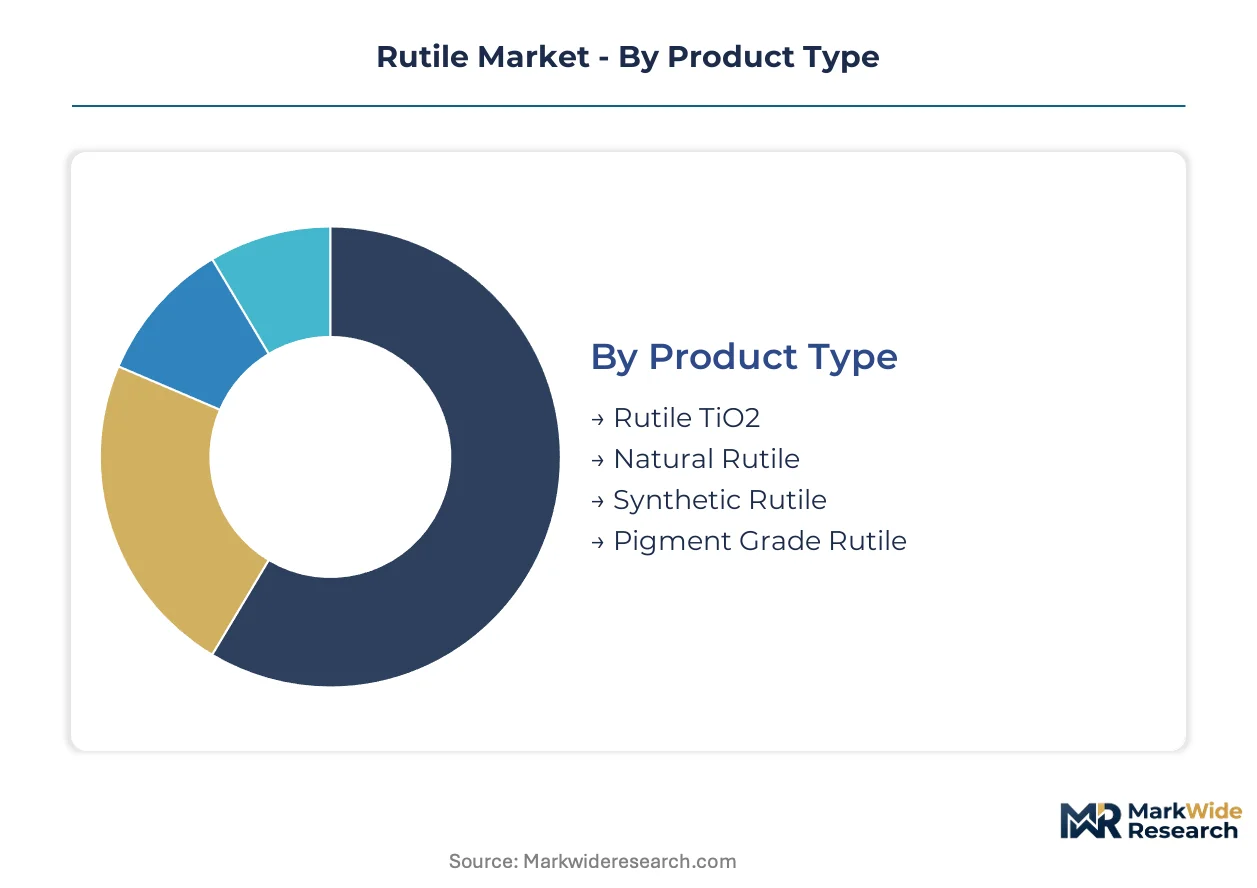
Rutile market segmentation reveals divergent technical specifications and purity thresholds across product categories. Each segment carries distinct qualification protocols that determine access to chloride-route pigment plants or aerospace titanium metal applications.
Product Type:
Mature synthetic rutile conversion technologies coexist with emerging engineered feedstock formats designed for optimized chlorinator performance.
- Synthetic Rutile:Produced via Becher process upgrading of ilmenite to achieve TiO₂ content exceeding 92% with controlled porosity for fluidized bed chlorination. European chloride-route TiO₂ plants concentrate procurement around this grade as REACH compliance tightens impurity thresholds.
- Pigment Grade Rutile:Natural concentrate beneficiated to 95%+ TiO₂ content through gravity and magnetic separation circuits. Australian coastal mining jurisdictions anchor supply concentration for this specification.
- Rutile TiO2:High-purity titanium dioxide derived from rutile feedstock for direct pigment synthesis or metal reduction.
- Natural Rutile:Unupgraded heavy mineral sands concentrate with variable TiO₂ content depending on deposit geology.
Synthetic rutile retains volume leadership in chloride-process procurement; pigment grade rutile holds the steepest expansion curve as REACH mandates displace lower-grade alternatives.
Application:
Cost tier differentiation separates commodity volume applications from specialty formulations commanding technical service premiums.
- Paints:Architectural and industrial formulations absorb the largest pigment-grade rutile volumes. Construction sector demand in coastal mining jurisdictions drives offtake timing.
- Plastics:Polymer masterbatches for automotive and packaging verticals are expanding most quickly as calcium carbonate substitution accelerates for opacity and UV resistance.
- Coatings:Protective and decorative film applications requiring precise particle size distribution and dispersibility characteristics.
- Rubber:Tire and industrial rubber compounding utilizing rutile for reinforcement and color stability.
Paints retain volume leadership across application categories; plastics gains share fastest as polymer formulation standards tighten.
End User:
Customer type segmentation splits between project-driven construction procurement and specification-critical aerospace qualification pathways.
- Construction:Cement, concrete, and architectural coating applications consume the largest pigment-grade material volumes. Australian and African coastal mining operations concentrate supply for this segment.
- Automotive:OEM coatings and polymer interior components demand premium sheet and granule forms with tight lot-to-lot consistency.
- Electronics:Dielectric and capacitor applications utilizing high-purity rutile ceramics.
- Aerospace:Titanium sponge producers for airframe and engine applications require ultra-high-purity rutile as Kroll process feedstock, opening specialty margin pools distinct from pigment economics.
Construction retains volume leadership; aerospace holds the steepest margin expansion trajectory as airframe build rates recover.
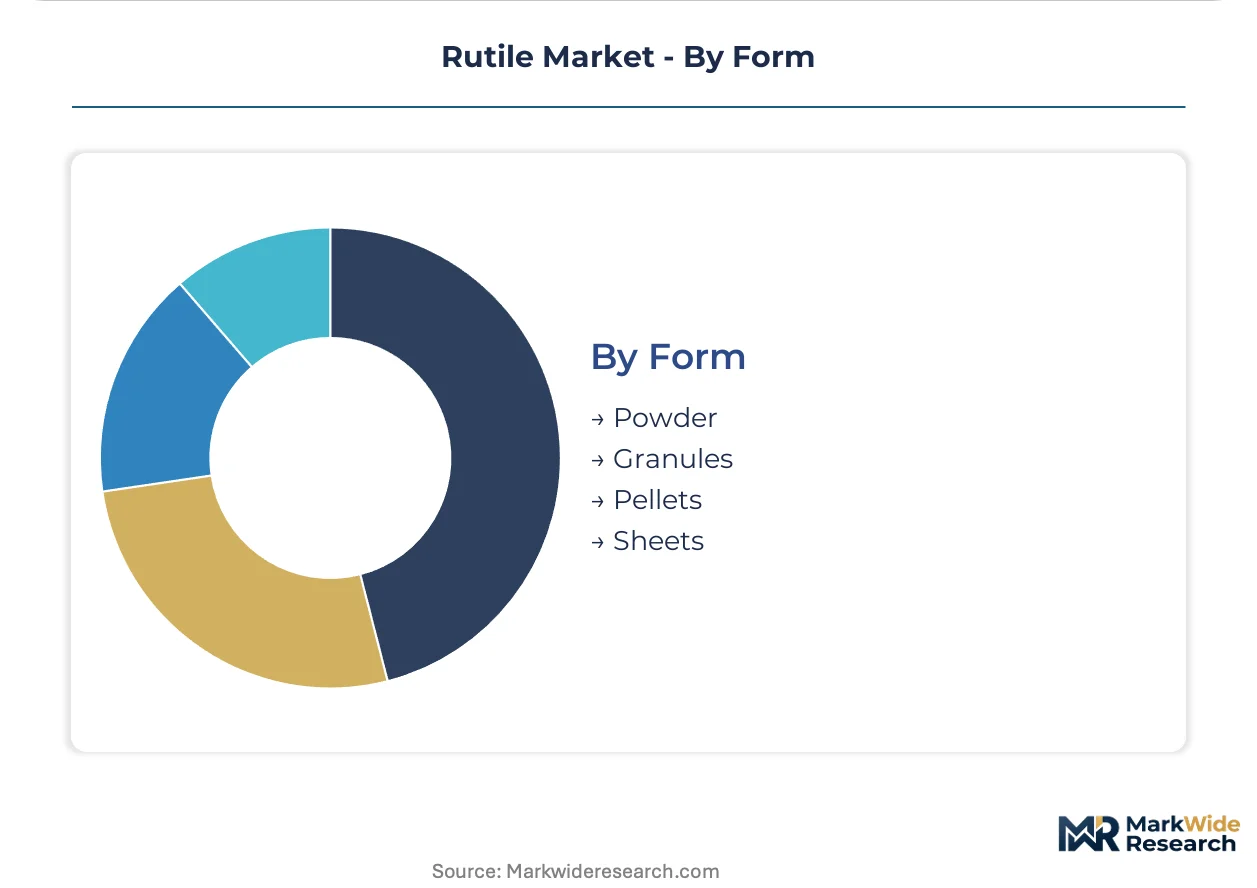
Form:
Supply concentration in powder processing infrastructure shapes availability across physical formats.
- Powder:Standard milled concentrate for bulk pigment synthesis and chemical processing. Gravity and magnetic separation circuits in Australian mineral sands operations produce this format at scale.
- Granules:Sized particulate for controlled chlorinator feed and reduced dusting during handling.
- Pellets:Densified form for pneumatic conveying systems and automated furnace charging.
- Sheets:Specialty format for specific titanium metal reduction processes and laboratory applications.
Powder retains volume leadership; granules gain adoption fastest as chlorination plant automation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitations and REACH pigment purity mandates are reshaping supply chain configurations across major consuming jurisdictions. Coastal mining operations in Australia, Sierra Leone, and India concentrate extraction capacity while regulatory divergence between North American and European standards fragments procurement strategies.
Australia
Western Australian mineral sands output supplies the dominant share of global pigment-grade rutile feedstock. State environmental protection agencies enforce escalating rehabilitation bonds and tailings management protocols that constrain greenfield timelines. The Eneabba and Jacinth-Ambrosia deposits anchor heavy mineral concentrate production for chloride-route TiO₂ plants.
United States
Domestic paint and coatings manufacturers absorb substantial pigment-grade volumes for architectural and industrial formulations. EPA oversight of mining effluent standards is tightening allowable heavy metals discharge from wet separation circuits. Southeastern coastal deposits face retrofit requirements for closed-loop water systems and advanced flocculation technologies.
India
Domestic TiO₂ producers are evaluating synthetic rutile import substitution as BIS standards tighten formulation requirements. The PLI scheme incentivizes integrated feedstock security for chloride-route expansion. IREL and Kerala Minerals & Metals Ltd anchor public-sector mining and downstream processing capacity in coastal Tamil Nadu and Kerala.
Sierra Leone
Atlantic basin heavy mineral sands development is diversifying supply origins beyond Australian concentration. Coastal extraction operations add logistics alternatives for European pigment producers managing REACH compliance costs. Sierra Rutile anchors commercial-scale output from the Southern Province deposits.
Germany
European ECHA thresholds for titanium dioxide feedstock are disqualifying lower-grade ilmenite sources and redirecting volume toward premium rutile channels. Domestic coatings formulators resist fixed-price multi-year commitments given feedstock cost volatility. The EU Green Deal carbon border adjustment mechanism advantages Australian and African coastal mining with lower transport footprints.
Rutile Market Competitive Environment
Capability concentration sits with integrated miners controlling heavy mineral sands beneficiation expertise; scale advantage sits with diversified chemical conglomerates with captive chloride-route TiO₂ capacity. The vendor base stratifies across three tiers: state-affiliated mineral extractors with coastal deposit access, privately held sand mining specialists with gravity separation technical depth, and vertically integrated pigment producers securing backward feedstock control. Dominant competitive moves include synthetic rutile conversion capacity expansion and long-term offtake contracting with price reopeners indexed to TiO₂ pigment spot markets.
Within the integrated mining tier, Rio Tinto and Iluka Resources Limited exemplify the Australian coastal concentration model, while Tronox Holdings PLC represents the pigment-producer-backward-integration archetype with captive feedstock security. IREL anchors state-sector positioning in the Indian subcontinent. These entities occupy positions that reflect divergent strategic bets on natural versus synthetic rutile process economics.
| Leading Market Players |
|---|
| Rio Tinto |
| IREL (India) Limited |
| Sierra Rutile |
| TOR Minerals |
| V.V. Mineral |
| Tronox Holdings PLC |
| East Minerals |
| Kerala Minerals & Metals Ltd |
| Iluka Resources Limited |
| Others |
Value Chain & Pricing Dynamics
Australian coastal mining concentration at Eneabba and Jacinth-Ambrosia deposits funnels premium pigment-grade rutile through a narrow supplier base, concentrating margin capture with integrated miners while downstream chloride-route TiO₂ plants absorb feedstock cost volatility through indexed contract structures.
Pricing Analysis
Atlantic basin logistics from Sierra Leone extraction operations command freight premiums over Australian supply routes into European REACH-compliant markets. Contract-based long-term offtake with price reopeners indexed to TiO₂ pigment spot markets dominates procurement structures, with quality grade and volume scale as the primary price differentiation drivers. Cost compression in synthetic rutile conversion is intensifying because natural gas price volatility in Western Australia squeezes Becher process margins. Sulfate-route TiO₂ plants in developing markets exhibit highest price sensitivity, while aerospace titanium sponge producers accept premium pricing for ultra-high-purity Kroll process feedstock.
Supply Chain Analysis
Iluka Resources and Rio Tinto anchor beneficiation capacity through captive heavy mineral sands operations spanning Western and southeastern Australian coasts. Raw material dependencies center on ilmenite feedstock for synthetic rutile upgrading, natural gas for thermal conversion, and coke reductants for chlorination chemistry. Australian supply concentration creates single-jurisdiction disruption risk from state environmental protection agency enforcement actions. Distribution runs through bulk maritime terminals to chloride-route pigment plants in Germany, India, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for chlorinator feedstock qualification and tailings rehabilitation bonding advisory represent faster-expanding recurring revenue layers than extraction volume growth alone.
For Market Incumbents: Entrench synthetic rutile conversion capacity in Western Australia to capture chloride-process procurement shifts as REACH compliance tightens impurity thresholds. Secure long-term offtake with price reopeners to defend against ilmenite substitution pressure from sulfate-route competitors. Add titanium metal aerospace qualification pathways to diversify beyond pigment economics. For New Entrants and Emerging Players: Indian coastal Tamil Nadu and Kerala deposits offer underpenetration for domestic synthetic rutile production as BIS standards tighten and PLI scheme incentives favor integrated feedstock security. Target chloride-route TiO₂ producers seeking import substitution with engineered feedstock formats optimized for fluidized bed chlorination performance. Pursue joint development agreements with IREL for heavy mineral sands access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mineral sands specialists holding coastal deposit positions but lacking downstream integration capital. Five-to-ten year viability hinges on synthetic rutile process economics outperforming natural concentrate alternatives. Watch for carbon border adjustment mechanism implementation advantaging Australian and African supply over Chinese ilmenite-slag routes.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Rutile Capacity Expansion | Becher process upgrading captures chloride-route procurement shifts as REACH tightens purity thresholds. |
| Long-term Supply Agreement | Indexed price reopeners with European coatings formulators balance volume certainty against margin volatility. |
| Backward Integration into Mining | Captive heavy mineral sands access secures feedstock qualification protocols for aerospace titanium metal applications. |
| Green Manufacturing Transition | Lower transport footprint from Australian and African coastal mining advantages EU Green Deal carbon border adjustments. |
| Joint Venture | Indian state-sector partnerships accelerate PLI scheme capture for domestic chloride-route TiO₂ expansion. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with mineral sands plant managers, procurement leads at chloride-route TiO₂ producers, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, SEC 10-K filings, Australian state environmental protection agency rehabilitation bond disclosures, and ECHA REACH registration databases. Bottom-up capacity and volume estimates triangulated against top-down pigment demand modeling.
Forecast inputs considered product type segmentation across synthetic rutile, pigment grade rutile, and natural concentrate tiers; application splits between paints, plastics, coatings, and rubber compounding; and end-use differentiation across construction, automotive, electronics, and aerospace verticals. CAGRs derived from regression against TiO₂ pigment production trajectories and chloride-route capacity expansion timelines across the projection horizon. Industry-specific inputs included Becher process natural gas cost curves and REACH compliance cost pass-through elasticity.
The forecast holds incumbent behavior within observed patterns; aggressive synthetic rutile capacity additions by state-affiliated mineral extractors or carbon border adjustment mechanism acceleration would shift outcomes. Quarterly review of Australian rehabilitation bond enforcement actions, Sierra Leone extraction licensing progress, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Global Rice Husk Ash Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market