
 Eclinical Solutions and Software Market | 2026-2036
Eclinical Solutions and Software Market Size, Share, and Industry Trends Forecast 2026-2036
Eclinical Solutions and Software Market Foresight
The FDA's 21 CFR Part 11 is broadening the cost-of-entry calculus for eclinical platform vendors, forcing substantial validation investments before commercial deployment. Oracle Corporation leverages its Cerner acquisition heritage to sustain deep integration across hospital and trial site networks. Veeva Systems anchors its position through vault-based architectures that dominate sponsor-CRO collaboration workflows. IQVIA competes by combining proprietary real-world data assets with cloud-native trial infrastructure.
Eclinical solutions and software encompass integrated technology platforms that digitize clinical trial operations through electronic data capture, remote monitoring, and regulatory submission management, typically deployed via validated cloud architectures with audit trails and role-based access controls. These systems serve primarily to reduce trial cycle times, improve data integrity, and enable decentralized patient participation across geographically dispersed sites. Electronic Data Capture systems occupy the largest installed base among product types, though Randomization Software commands premium pricing due to its direct impact on trial validity. Cloud-Based deployment is displacing on-premise alternatives as pharmaceutical sponsors prioritize elastic scaling and reduced IT overhead across multi-site studies.
FDA enforcement of 21 CFR Part 11, EMA's Clinical Trial Regulation framework, and ICH E6(R2) Good Clinical Practice guidelines collectively shape product development roadmaps, mandating audit trails, electronic signatures, and risk-based quality management as baseline capabilities. These regulatory requirements create durable switching costs for installed vendors while raising compliance barriers for new entrants. Stakeholders must monitor evolving FDA guidance on decentralized trials and artificial-intelligence-enabled data analysis to anticipate the next wave of platform certification requirements.
Market Dynamics
Pharmaceutical sponsors are consolidating trial technology stacks around unified data models, forcing vendors to absorb previously separate functions—randomization, safety reporting, and site payments—into single cloud platforms rather than maintaining point solutions.
Growth Catalysts
- FDA 21 CFR Part 11 enforcement:Sponsor validation budgets are expanding to meet electronic signature and audit trail mandates, pulling through platform upgrades across installed bases.
- Decentralized trial infrastructure:Direct-to-patient drug delivery and home health monitoring are creating demand for mobile-enabled data capture and telemedicine-integrated workflows.
- EMA Clinical Trial Regulation convergence:Standardized submission formats across EU member states are reducing protocol amendment cycles and accelerating multinational study startup timelines.
Market Restraints
- Validation cost concentration:Cloud platform qualification for GxP environments consumes eighteen to twenty-four months of pre-revenue engineering, compressing vendor cash conversion cycles.
- Specialized talent scarcity:Clinical data scientists with dual expertise in regulatory science and cloud architecture command compensation premiums that inflate platform development costs.
- Legacy system entrenchment:Sponsor investments in decade-old on-premise EDC installations create contractual friction and data migration risks that delay replacement decisions.
Strategic Opportunities
- Real-world evidence integration:Vendors embedding IQVIA and Flatiron-style data assets into trial platforms can differentiate on protocol feasibility and patient identification.
- Asia-Pacific regulatory alignment:Japan's PMDA and South Korea's MFDS are harmonizing clinical data standards with ICH E6(R3), opening consolidated platform deployment across Northeast Asian sites.
- AI-enabled monitoring:Machine learning algorithms for risk-based quality management are compressing source data verification workloads and expanding per-study margins.
Industry Challenges
- Interoperability fragmentation:Sponsor-CRO data exchange still relies on custom API development despite FHIR and CDISC standards, inflating integration timelines.
- Cybersecurity certification backlog:ISO 27001 and SOC 2 Type II audits face six-month queue delays that stall commercial launches for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eclinical Solutions and Software Market |
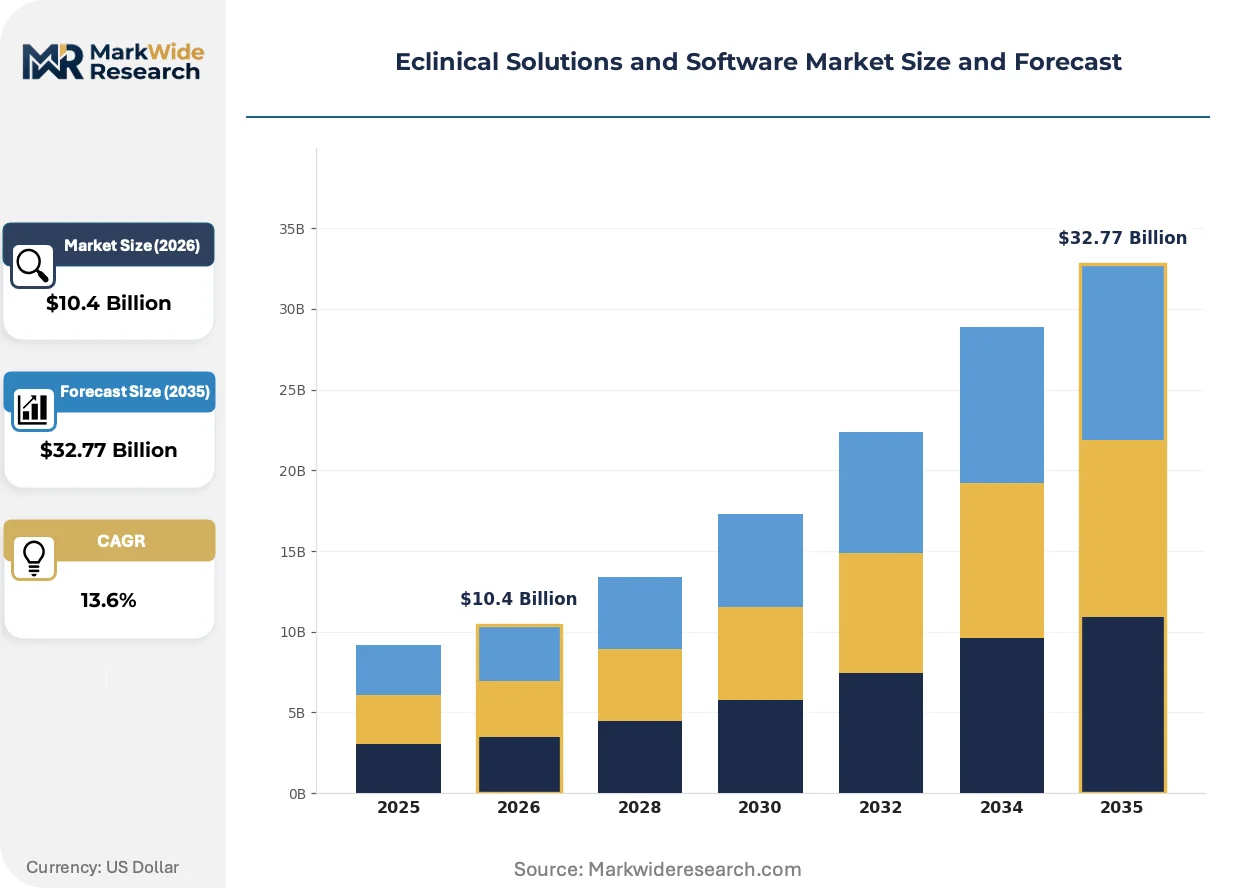
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $32.77 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Trial Management System, E-Source, Electronic Data Capture, Randomization Software End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based Application: Data Management, Regulatory Compliance, Patient Recruitment, Site Monitoring |
| Companies Covered | Oracle Corporation, Veeva Systems, IQVIA, Parexel International Corporation, Medidata Solutions, Clario, Signant Health, Dassault Systèmes, eClinical Solutions LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eclinical Solutions and Software Market Shifts & Advancements
Platform architectures are pivoting from document-centric vaults to data-centric lakehouses, enabling real-time analytics that reshape how sponsors monitor trial integrity and patient safety.
Unified clinical platforms are expanding into adjacent trial execution functions—site feasibility, budget negotiation, and investigator payments—that previously required separate vendor relationships. Mid-tier biotechnology sponsors are adopting these consolidated suites fastest, trading best-of-breed flexibility for reduced vendor management overhead. This convergence is compressing the addressable market for standalone randomization and clinical supply management vendors.
EMA's Clinical Trial Information System (CTIS) portal is mandating structured protocol data submission across all EU member states, forcing platform vendors to rebuild submission modules around the new XML schemas. Sponsors running multinational studies must now synchronize protocol versions across CTIS, FDA IND databases, and national competent authorities simultaneously. Small-to-mid-size CROs serving European biotech sponsors are experiencing the steepest adaptation costs.
Site-centric procurement of eclinical tools is yielding to sponsor-mandated platform standardization that restricts site choice. Academic medical centers and independent investigator sites are losing negotiating leverage as pharmaceutical companies consolidate purchasing power across their trial portfolios. This concentration is most pronounced in oncology studies where sponsor platform decisions now precede site selection in the United States and Germany.
Eclinical Solutions and Software Market Segmentation
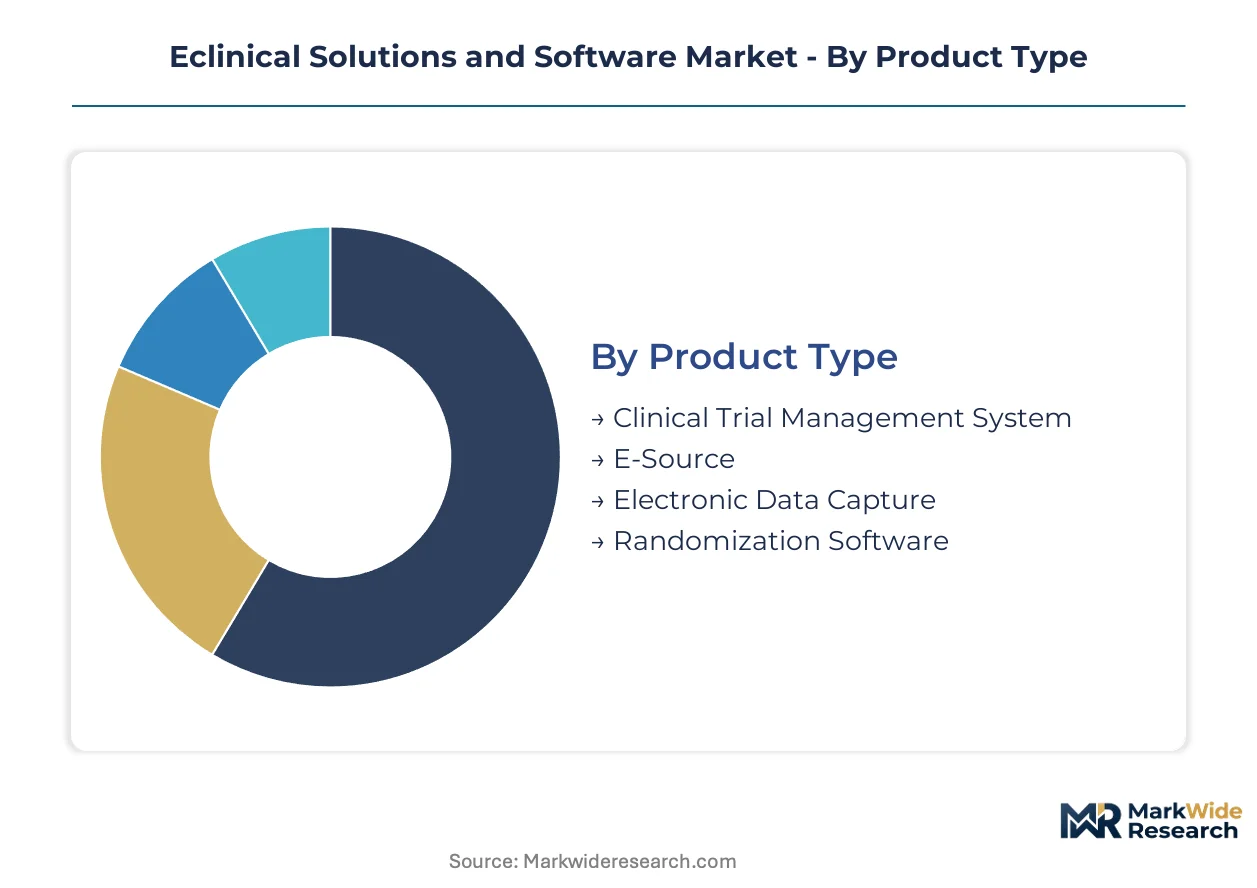
Eclinical platform segmentation reveals how vendor specialization maps against sponsor consolidation strategies. Understanding which segments resist integration versus those becoming absorbed into unified suites determines procurement timing and switching cost exposure.
Product Type:
Standalone modules persist where regulatory validation creates embedded switching costs, while adjacent functions face absorption into broader platforms.
- Clinical Trial Management System:Orchestrates protocol design, site management, and milestone tracking through centralized dashboards. Pharmaceutical sponsors in the United States prioritize CTMS integration with EDC to eliminate reconciliation between separate databases. Volume placements concentrate in CTMS; the faster expansion belongs to Randomization Software.
- E-Source:Captures clinical data directly at the point of care, eliminating transcription errors from paper-to-electronic workflows. Academic medical centers adopt e-source fastest where EHR interoperability with Cerner and Epic systems reduces site burden.
- Electronic Data Capture:Dominates installed base with case report form design, patient data collection, and query management capabilities. EDC deployments span multinational studies requiring CDISC-compliant data structures for FDA and EMA submissions.
- Randomization Software:Drives trial validity through automated patient allocation, stratification, and blinding maintenance. Premium pricing reflects direct impact on regulatory acceptance and statistical integrity.
EDC and CTMS command the largest deployment footprints; e-source is gaining share fastest as direct data capture mandates spread.
End User:
Procurement authority concentrates with sponsors who mandate platform standards across CRO partners, reshaping how vendors allocate sales resources.
- Pharmaceutical Companies:Drive standardization decisions across therapeutic portfolios, forcing CROs onto sponsor-selected platforms. Large-cap sponsors in Germany and the United States negotiate enterprise licenses that span dozens of concurrent studies.
- Biotechnology Firms:Mid-tier biotechs adopt consolidated suites fastest, trading customization flexibility for reduced vendor management overhead and faster study startup.
- Contract Research Organizations:Face margin compression as sponsor-mandated platforms eliminate CRO technology differentiation and require redundant staff training across multiple client systems.
- Academic Institutions:Lose negotiating leverage as sponsor platform decisions precede site selection, particularly in oncology studies where centralized procurement dominates.
Pharmaceutical sponsors capture the deepest volume commitments; biotechnology firms represent the steepest adoption trajectory.
Deployment:
Infrastructure choices reflect sponsor risk tolerance for data residency, validation burden, and elastic scaling demands across study phases.
- Cloud-Based:Elastic scaling and reduced IT overhead attract sponsors running multi-site studies with unpredictable enrollment trajectories. FDA 21 CFR Part 11 validation requirements for cloud architectures consume eighteen to twenty-four months of pre-revenue engineering.
- On-Premise:Persists where data sovereignty requirements or legacy system entrenchment block migration, particularly at established pharmaceutical sponsors with decade-old EDC installations.
- Hybrid:Segments sensitive data on-premise while leveraging cloud analytics for non-identifiable operational metrics, bridging compliance and flexibility demands.
- Web-Based:Browser-accessible deployments reduce site infrastructure requirements and accelerate investigator onboarding across decentralized trial networks.
Cloud deployments anchor current volume; hybrid configurations are climbing fastest as sponsors navigate data residency complexity.
Application:
Functional modules compete for platform embedding based on automation potential and regulatory scrutiny intensity.
- Data Management:Core EDC functionality spanning collection, cleaning, and locking of clinical datasets. Data management modules face the strongest consolidation pressure as sponsors demand unified databases across trial phases.
- Regulatory Compliance:Submission formatting, audit trail maintenance, and eCTD assembly for FDA and EMA portals. EMA's CTIS mandate is forcing rebuilds of submission modules around new XML schemas.
- Patient Recruitment:Screening database matching, referral network management, and retention tracking. Recruitment tools integrate with real-world data assets to improve protocol feasibility forecasting.
- Site Monitoring:Source data verification workflows, risk-based quality indicators, and corrective action tracking. Machine learning algorithms are compressing SDV workloads and expanding per-study margins.
Data management captures the deepest installed base; regulatory compliance modules are expanding most quickly as submission requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Kendall Square in Massachusetts anchor North American eclinical development, drawing FDA-aligned validation engineering talent into concentrated innovation corridors.
United States
Pharmaceutical sponsors in Massachusetts and New Jersey drive enterprise platform consolidation across oncology and rare disease portfolios. FDA 21 CFR Part 11 enforcement mandates eighteen-to-twenty-four-month validation cycles that favor established vendors with Cerner and Epic integration heritage. The Research Triangle Park corridor hosts multiple CRO technology centers where sponsor-mandated standardization reshapes site procurement.
Germany
Heidelberg and Munich-based biotech clusters demand EMA-aligned submission modules for multinational trial execution. The country's national pharmaceutical regulator enforces ICH E6(R2) compliance through rigorous inspection protocols that elevate audit trail requirements. Berlin's digital health startup ecosystem increasingly supplies specialized patient recruitment tools to mid-tier European sponsors.
United Kingdom
London's contract research corridor concentrates demand for unified CTMS-EDC platforms serving global pharmaceutical headquarters. MHRA post-Brexit divergence from EMA systems forces dual-track validation investments by vendors serving UK-EU crossover studies. The Cambridge life sciences cluster accelerates adoption of e-source technologies integrated with NHS hospital networks.
Japan
PMDA harmonization with ICH E6(R3) opens consolidated platform deployment across Tokyo and Osaka trial sites. The regulator's clinical data standards alignment reduces protocol amendment cycles for sponsors running US-Japan parallel development programs. Yokohama's pharmaceutical manufacturing corridor increasingly sources validated cloud architectures for post-marketing surveillance studies.
Switzerland
Basel's pharmaceutical headquarters concentration drives premium pricing acceptance for randomization and clinical supply management modules. Swissmedic's stringent electronic signature requirements sustain validation cost barriers that protect incumbent vendor positions. The Lake Geneva biotech cluster adopts hybrid deployment models balancing data sovereignty with cloud analytics flexibility.
Eclinical Solutions and Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor landscape where regulatory validation investments create durable switching costs. Enterprise software conglomerates leverage hospital network integration and real-world data assets to anchor platform positions. Specialized vault-architecture vendors dominate sponsor-CRO collaboration workflows through document-centric compliance frameworks. Consolidation pressure intensifies as sponsors absorb randomization, safety reporting, and site payment functions into single cloud suites rather than maintaining point solutions.
Within the enterprise conglomerate tier, Oracle Corporation and Dassault Systèmes occupy positions shaped by healthcare IT heritage and industrial software integration respectively. Veeva Systems exemplifies the vault-architecture specialist archetype that dominates sponsor-CRO collaboration workflows. IQVIA represents the data-integrated platform model combining proprietary real-world evidence assets with cloud-native trial infrastructure. These three anchors illustrate how regulatory validation requirements and data asset control determine competitive positioning across sponsor procurement decisions.
| Leading Market Players |
|---|
| Oracle Corporation |
| Veeva Systems |
| IQVIA |
| Parexel International Corporation |
| Medidata Solutions |
| Clario |
| Signant Health |
| Dassault Systèmes |
| eClinical Solutions LLC |
| Others |
Supply & Pricing Matrix
Cloud infrastructure cost indices from hyperscalers cascade through eclinical platform economics, compressing margins for vendors without enterprise scale while validating premium pricing for FDA 21 CFR Part 11-compliant architectures. Validation engineering labor rates in the United States and Germany anchor cost structures that tier pricing across deployment models.
Pricing Analysis
Short lead-time premiums dominate eclinical procurement, with sponsors paying twenty-to-forty percent markups for validated platforms available within six months versus standard eighteen-to-twenty-four-month qualification cycles. SaaS-tiered subscription models stratify across enterprise, mid-market, and emerging biotech tiers, with price differentiation driven by audit trail granularity and EDC-CTMS integration depth. Cost compression in the mid-market tier intensifies as Oracle and Veeva bundle previously standalone randomization modules. Biotechnology firms exhibit highest price sensitivity, while large-cap pharmaceutical sponsors prioritize validation speed over unit economics.
Supply Chain Analysis
Cloud compute supply rests on hyperscaler infrastructure concentrated in the United States, Ireland, and Singapore, with platform vendors tethered to AWS, Azure, and GCP availability zones for GxP-compliant data residency. Specialized inputs include ISO 27001-certified data centers, CDISC-compliant data structure libraries, and FHIR interoperability middleware. Single-source vulnerability in audit trail cryptography modules creates regulatory recertification risks. Distribution runs through direct enterprise sales teams and CRO channel partnerships, with sponsor-mandated procurement consolidating purchasing power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eclinical platform consolidation accelerates as FDA validation cost barriers force subscale vendors toward acquisition or exit. Sponsor demand for unified suites compresses addressable markets for point solutions.
For Market Incumbents: Cement platform positions by embedding real-world data assets from IQVIA-style repositories directly into trial infrastructure, neutralizing emerging entrants lacking proprietary datasets. Absorb randomization and site payment functions into core cloud suites before specialized vendors can defend niche positions. FDA 21 CFR Part 11 recertification cycles for acquired modules create eighteen-month defensive moats against fast-follower competition.
For New Entrants and Emerging Players: EMA's CTIS mandate in Germany and France opens a window for XML-native submission modules that incumbent platforms must rebuild from legacy architectures. Target mid-tier European CROs serving biotech sponsors facing steepest CTIS adaptation costs. Lead with API-first interoperability that bypasses custom integration timelines plaguing established vendor ecosystems.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vault-architecture specialists with embedded sponsor-CRO workflow share in Switzerland and the United Kingdom. Long-term viability hinges on regulatory validation asset durability rather than feature velocity. Watch FDA guidance on AI-enabled data analysis as the inflection trigger for next-wave platform certification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying EDC-CTMS-randomization modules eliminates sponsor reconciliation costs and CRO training redundancy. |
| Regulatory Approval Pathway | FDA 21 CFR Part 11 pre-certification investments create eighteen-to-twenty-four-month competitive moats for validated vendors. |
| Acquisition of Specialist Firm | Absorbing standalone randomization vendors compresses addressable markets while capturing premium pricing maintenance. |
| Geographic Expansion | EMA CTIS-aligned module deployment in Heidelberg and Munich clusters captures multinational trial standardization demand. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure GxP-compliant infrastructure residency for sponsor data sovereignty requirements. |
Research Methodology
Independent corroboration across FDA 510(k) filings, EMA CTIS submission databases, and ClinicalTrials.gov protocol registrations underwrites the qualitative findings on platform adoption patterns. Primary interviews with clinical data management executives, regulatory affairs leads at pharmaceutical sponsors, CRO technology procurement officers, and hospital site investigators combined with secondary validation from SEC 10-K disclosures, hyperscaler healthcare cloud revenue segments, and CDISC implementation metrics. Bottom-up study-level platform deployment counts triangulate against top-down vendor revenue segmentation.
Rate-of-change decomposition across the analysis window separates volume effects from price-mix shifts in SaaS subscription renewals. Segmentation dimensions modeled include deployment model, sponsor size tier, therapeutic area concentration, integration complexity, and regional regulatory cluster alignment. CAGRs derive from logistic adoption curves fitted to historical EDC penetration patterns, with forecast inputs incorporating FDA decentralized trial guidance evolution and EMA CTIS mandate compliance timelines.
Caveats apply where FDA enforcement discretion on AI-enabled monitoring or EMA XML schema revisions could materially shift the outlook. Forecasts embed assumptions on sponsor consolidation velocity and hyperscaler GxP certification pace that warrant sensitivity testing. A small set of named triggers—PMDA harmonization completion, ISO 27001 audit queue normalization, and sponsor platform standardization mandate timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Tableau Services Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Commercial Drone Software Market
Software & Services
Vertical Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Data Conversion Services Market
Software & Services
Classified Platform Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Feed Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Asia-Pacific Database Management Software Market