
 Global Apparel Management Software Market | 2026-2036
Global Apparel Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Apparel Management Software Market Foresight
Cloud infrastructure is rebalancing legacy on-premise economics as apparel enterprises shift compute workloads away from owned data centers. Oracle Corporation leverages its database heritage to anchor enterprise-grade deployments for multi-brand retailers. SAP competes through deep ERP integration that sustains renewal rates among European textile manufacturers. Infor specializes in industry-specific micro-verticals that differentiate its offering from horizontal alternatives.
Apparel management software encompasses integrated digital platforms that coordinate product lifecycle workflows, inventory synchronization, and multi-channel order orchestration through API-connected architectures. These systems execute real-time data exchange across CAD files, BOM tables, and WMS feeds to compress design-to-shelf timelines for fashion enterprises. Cloud-Based deployment leads solution uptake as mid-size brands abandon server maintenance burdens, while Supply Chain modules capture expanding margin pools as nearshoring complicates vendor coordination. E-Commerce Platforms application segments are accelerating fastest as direct-to-consumer channels outpace wholesale reliance among digitally native labels.
The EU AI Act imposes algorithmic transparency requirements on demand forecasting modules sold into Europe, while GDPR mandates govern customer data flows within CRM functions. India's BIS cloud security guidelines and the United States' state-level data privacy patchwork create fragmented compliance terrain that shapes vendor certification roadmaps. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether single-tenant or regional instance architectures better absorb compliance costs.
Market Dynamics
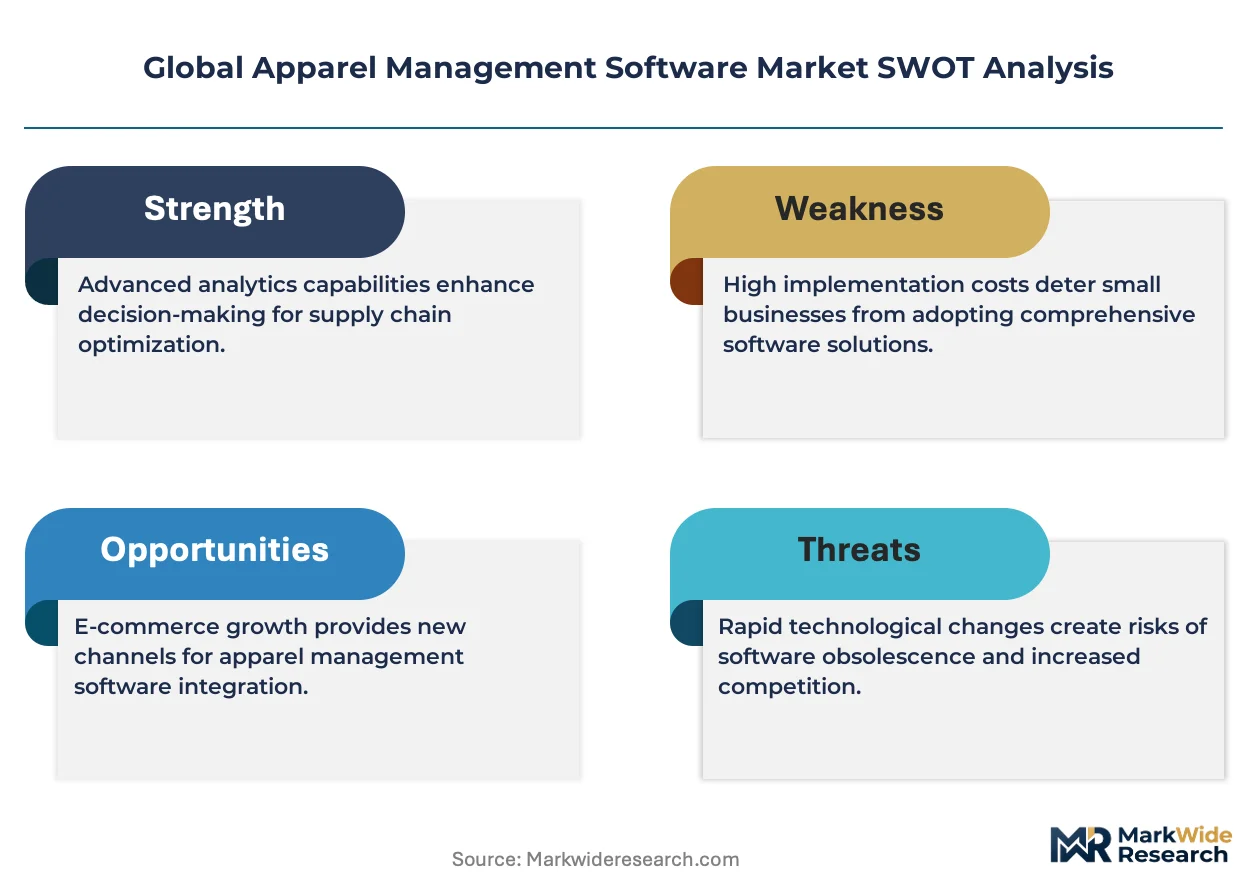
Cloud migration mandates under Europe's GDPR and the EU AI Act are forcing apparel enterprises to rearchitect their data infrastructure, compressing vendor evaluation cycles and elevating compliance certification to a primary procurement criterion alongside functional capability.
Growth Catalysts
- EU AI Act Algorithmic Transparency:Demand forecasting modules sold into Europe must now document training data lineage and decision logic, creating pull for vendors with pre-certified AI governance stacks.
- Nearshoring Vendor Coordination:Supply chain modules capture expanding margin pools as brands relocate production from Asia to Mexico, Turkey, and Portugal, multiplying touchpoints requiring real-time synchronization.
- Direct-to-Consumer Channel Expansion:E-commerce platform segments accelerate as digitally native labels abandon wholesale dependency, requiring API-connected order orchestration across TikTok Shop, Instagram Checkout, and proprietary storefronts.
Market Restraints
- GDPR Data Localization Costs:Customer data flows within CRM functions require regional instance architectures that fragment development roadmaps and inflate operational overhead for multi-territory deployments.
- Legacy ERP Integration Debt:On-premise SAP and Oracle installations at established European textile manufacturers resist cloud-native API architectures, extending implementation timelines.
- Specialized Talent Scarcity:Apparel-specific PLM configuration expertise concentrates in Germany, the United States, and India, creating wage premiums and project bottlenecks elsewhere.
Strategic Opportunities
- India Digital Textile Infrastructure:BIS cloud security guidelines and PLI scheme incentives are catalyzing domestic vendor ecosystems for mid-market brands seeking GDPR-compliant offshore development.
- CAD-to-Production Convergence:Integration between 3D design tools and automated pattern-making is electrifying sample-less development workflows, compressing design-to-shelf timelines from months to weeks.
- Resale and Circular Economy Modules:France's AGEC law and extended producer responsibility frameworks across the EU create mandated demand for product passport and traceability functionality.
Industry Challenges
- Multi-Jurisdiction Compliance Fragmentation:India's BIS guidelines, the United States' state-level privacy patchwork, and the EU AI Act create divergent certification requirements that strain single-tenant architecture economics.
- Real-Time Inventory Synchronization:API-connected architectures must reconcile BOM tables, WMS feeds, and multi-channel order data across disparate legacy systems with inconsistent data standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Apparel Management Software Market |
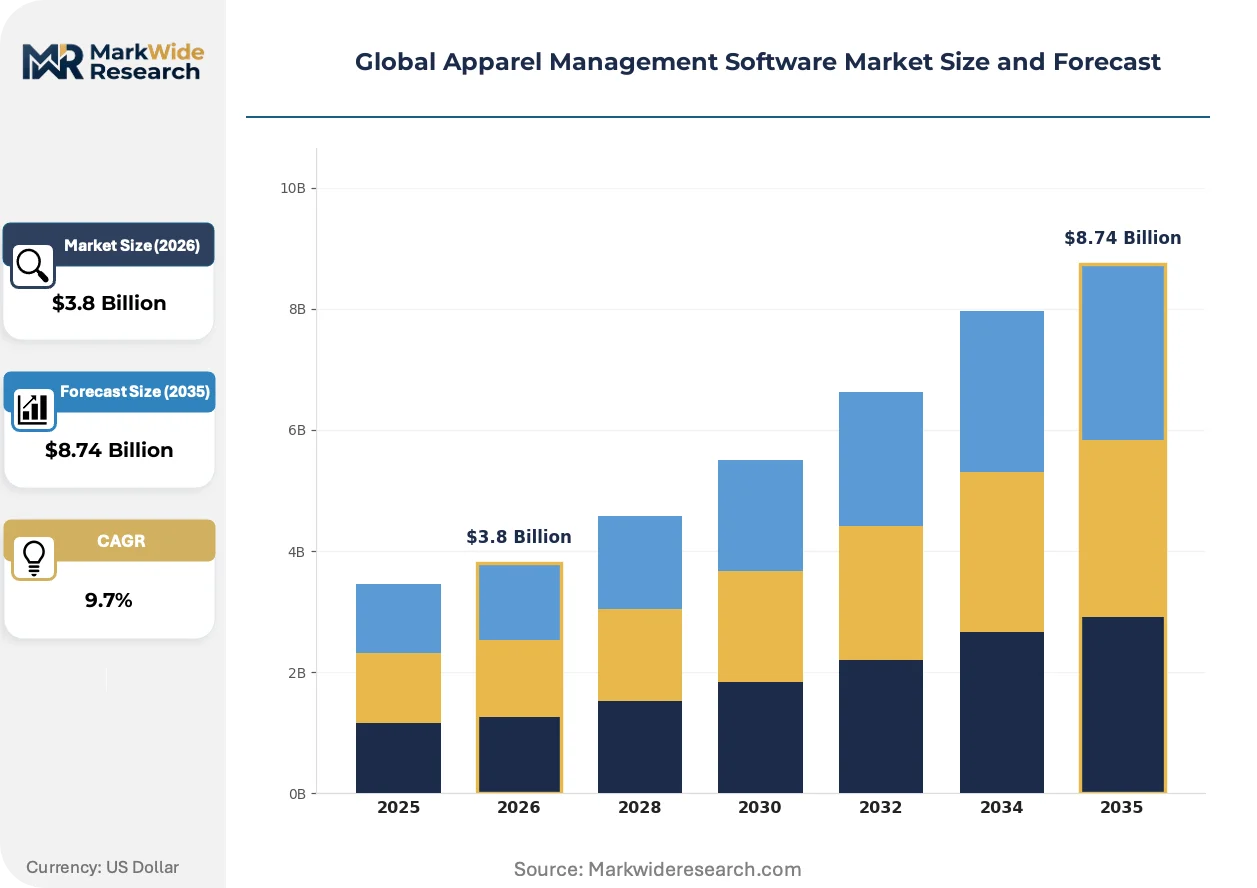
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Type: Inventory Management, Order Processing, Supply Chain, Demand Forecasting, Customer Relationship Management Application: Wholesale Management, Retail Store Operations, E-Commerce Platforms, Warehouse Automation, Quality Control End User: Fashion Brands, Textile Manufacturers, Retail Chains, Logistics Providers, Independent Designers |
| Companies Covered | ApparelMagic, AIMS360 Apparel Software, Apparel Business Systems, Oracle Corporation, SAP, Infor, Microsoft, Computer Generated Solutions, Systech Infovations Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Apparel Management Software Market Shifts & Advancements
Generative AI and edge computing are penetrating apparel workflows at uneven rates, with regulatory pressure in Europe running ahead of technical readiness while Asian manufacturing clusters prioritize speed-to-deployment over governance frameworks.
Embedded AI agents within PLM suites are electrifying pattern optimization and demand sensing capabilities. Mid-market fashion brands in Germany and the United States are piloting these tools at scale, compressing the traditional six-month seasonal planning cycle into continuous replenishment models that respond to social media signals within days.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes forecasting algorithms sold into Europe. Vendors must now maintain model cards and human oversight protocols, reshaping R&D allocation toward explainable AI architectures and away from black-box neural networks in demand planning modules.
Buying committees at digitally native labels are unbundling after-sales service from perpetual licenses, demanding consumption-based pricing tied to order volume rather than seat count. This procurement evolution is most visible in direct-to-consumer verticals across the United States, where CFOs prioritize cash-flow flexibility over capitalized software assets on balance sheets.
Global Apparel Management Software Market Segmentation
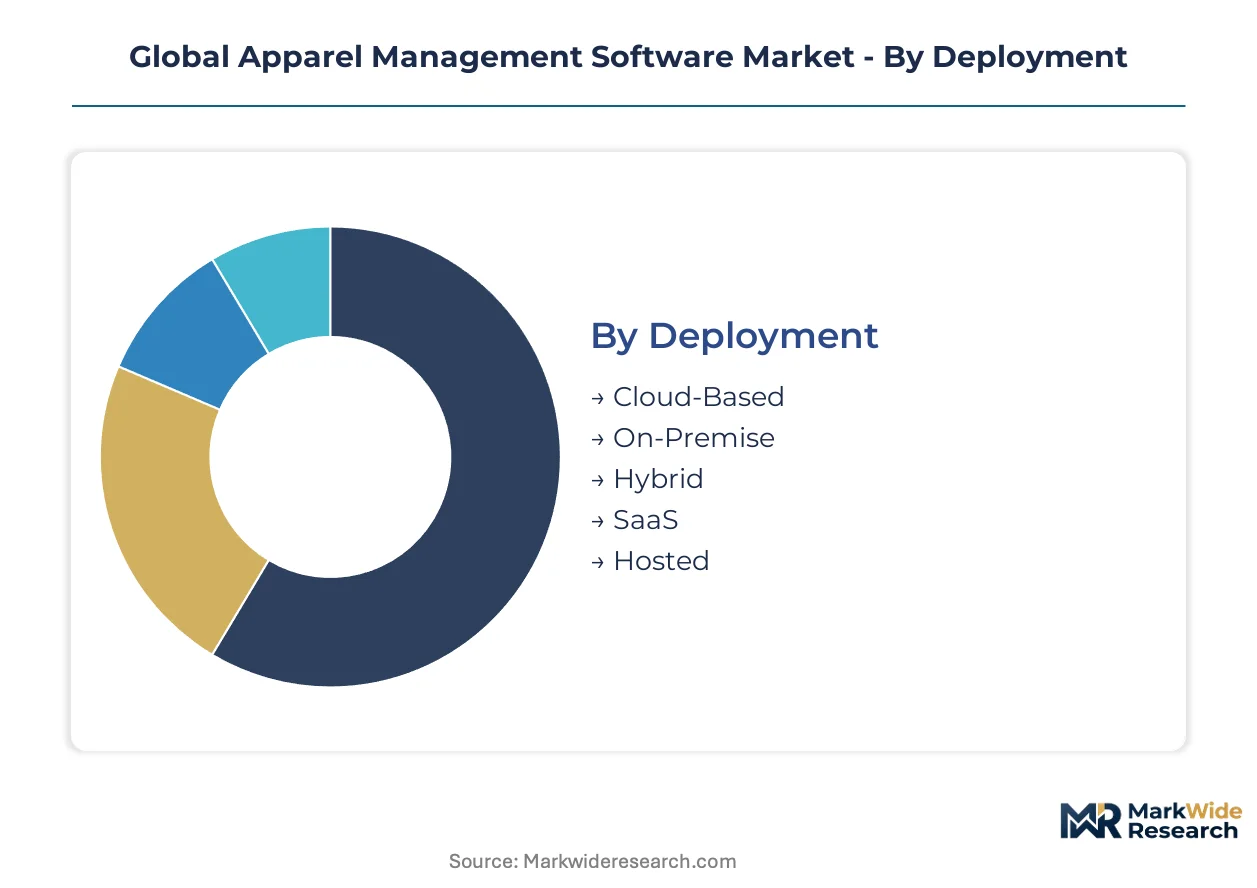
Segmentation in apparel management software reveals how vendor architectures align with customer technical maturity and compliance posture. Deployment models determine infrastructure ownership costs, while solution types map directly to margin capture opportunities across the design-to-retail value chain.
Deployment:
Standalone cloud instances dominate mid-market procurement cycles, whereas embedded on-premise systems persist among European textile manufacturers with legacy ERP integration debt.
- Cloud-Based:Multi-tenant architectures with automatic scaling and GDPR-compliant regional data residency. Demand concentrates among United States digitally native labels seeking consumption-based pricing and rapid TikTok Shop integration without server maintenance burdens.
- On-Premise:Single-tenant installations behind corporate firewalls with full hardware control. German and Italian textile manufacturers favor this model to satisfy internal IT governance policies and maintain direct oversight of proprietary pattern libraries.
- Hybrid:Split workloads across owned data centers and public cloud nodes for sensitive versus elastic operations.
- SaaS:Subscription-delivered functionality with vendor-managed updates and shared infrastructure economics.
- Hosted:Dedicated single-tenant cloud instances managed by third-party providers for brands requiring isolation without capital expenditure.
Cloud-Based leads volumes today; SaaS is gaining share fastest among direct-to-consumer entrants.
Solution Type:
Cost tier stratification separates enterprise suites from point solutions, with integrated platforms commanding premium pricing against modular alternatives.
- Supply Chain:End-to-end visibility platforms coordinating vendor portals, shipment tracking, and customs documentation through API-connected architectures. Nearshoring initiatives into Mexico and Turkey multiply touchpoint complexity, expanding module adoption among United States brands relocating production from Asia.
- Demand Forecasting:Algorithmic engines processing social media signals, weather data, and historical sell-through to optimize buy quantities. The EU AI Act's documentation requirements for high-risk AI systems reshape vendor R&D priorities toward explainable models in France and Germany.
- Inventory Management:Real-time stock synchronization across warehouses, stores, and digital channels with automated replenishment triggers.
- Order Processing:Multi-channel orchestration engines unifying wholesale, retail, and e-commerce order flows into unified fulfillment logic.
- Customer Relationship Management:Segmentation and lifecycle marketing tools with GDPR-governed data handling for European deployments.
Inventory Management anchors current revenue; Demand Forecasting shows steepest expansion trajectory as AI governance frameworks mature.
Application:
Volume concentration follows channel shift velocity, with digital-first applications outpacing traditional wholesale and retail operations in new license growth.
- E-Commerce Platforms:API-native order management connecting proprietary storefronts, Instagram Checkout, and TikTok Shop with warehouse and 3PL systems. Digitally native labels in the United States and United Kingdom abandon wholesale dependency, requiring real-time inventory exposure across fragmented consumer touchpoints.
- Warehouse Automation:WMS integration with robotic picking, automated sortation, and RFID-enabled cycle counting. India's PLI scheme incentives accelerate domestic deployment among export-oriented garment manufacturers seeking BIS-certified cloud infrastructure.
- Wholesale Management:B2B order portals with tiered pricing, line sheet distribution, and showroom appointment scheduling.
- Retail Store Operations:POS-integrated clienteling, endless aisle, and buy-online-pickup-in-store fulfillment coordination.
- Quality Control:Defect tracking, supplier scorecards, and audit workflow management with photographic documentation standards.
Warehouse Automation leads capital deployment today; E-Commerce Platforms climb the fastest as direct-to-consumer channels displace wholesale reliance.
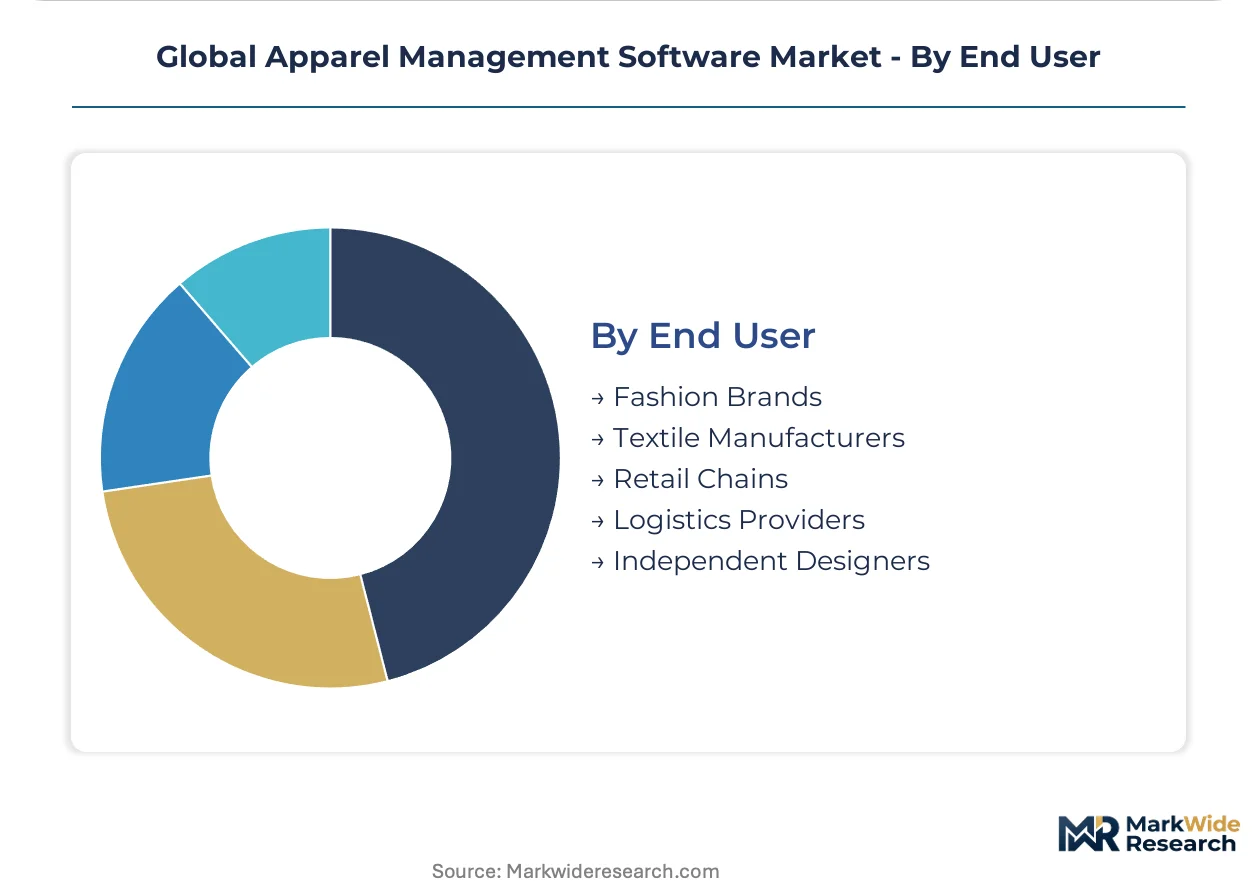
End User:
Customer type determines procurement sophistication, with fashion brands driving platform consolidation while logistics providers seek API interoperability.
- Fashion Brands:Multi-brand retailers and vertically integrated labels requiring PLM-to-ERP connectivity across design, sourcing, and distribution. Mid-market players in Germany and the United States accelerate integrated platform adoption to compress design-to-shelf timelines against fast-fashion competitors.
- Textile Manufacturers:Mill operators managing yarn procurement, loom scheduling, and dye lot traceability with BIS compliance for Indian export markets.
- Retail Chains:Multi-location operators standardizing operations across franchise and corporate-owned doors.
- Logistics Providers:3PL and 4PL operators requiring system-agnostic data exchange with diverse shipper technology stacks.
- Independent Designers:Small-scale creators leveraging lightweight SaaS tools for sample development and limited production runs.
Fashion Brands dominate current spending; Logistics Providers expand most quickly as nearshoring multiplies third-party coordination requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German textile manufacturers anchor software procurement volumes as mid-market fashion brands accelerate cloud migration to compress design-to-shelf timelines. The United States, Germany, and India concentrate demand as these markets build digital textile infrastructure and navigate divergent regulatory frameworks.
United States
Digitally native labels and multi-brand retailers drive consumption-based pricing adoption for API-connected order orchestration. State-level data privacy patchwork from California's CCPA to Virginia's CDPA fragments compliance roadmaps for multi-territory deployments. New York and Los Angeles fashion clusters pilot generative AI pattern optimization tools to respond to TikTok Shop demand signals within days.
Germany
Mid-market fashion brands demand integrated PLM-to-ERP connectivity to compete with fast-fashion competitors. The EU AI Act imposes algorithmic transparency requirements on demand forecasting modules, elevating pre-certified AI governance stacks as a procurement criterion. Munich and Düsseldorf industrial clusters sustain deep ERP integration renewal rates among established textile manufacturers.
India
Export-oriented garment manufacturers seek BIS-certified cloud infrastructure under the PLI scheme incentives for technical textiles. BIS cloud security guidelines and DGFT export promotion frameworks catalyze domestic vendor ecosystems for GDPR-compliant offshore development. Tiruppur and Surat textile clusters accelerate warehouse automation deployment with RFID-enabled cycle counting systems.
France
AGEC law mandates for extended producer responsibility create pull for product passport and circular economy traceability functionality. CNIL enforcement of GDPR data localization requirements elevates regional instance architectures for customer data flows within CRM functions. Paris luxury houses pilot 3D design-to-production convergence for sample-less development workflows.
United Kingdom
Post-Brexit regulatory divergence from EU AI Act frameworks creates parallel certification requirements for vendors serving both markets. London-based digitally native labels unbundle after-sales service from perpetual licenses, demanding consumption-based pricing tied to order volume. Manchester and Birmingham manufacturing clusters navigate customs documentation complexity for nearshored vendor coordination.
Global Apparel Management Software Market Competitive Landscape
Global majors compete with regional champions across compliance certification and vertical integration depth. Enterprise software conglomerates anchor multi-brand retail deployments through database heritage and ERP integration capabilities. Mid-market specialists capture share through industry-specific micro-verticals and rapid TikTok Shop API connectivity. Strategic moves concentrate on M&A for AI governance stacks and strategic partnerships for regional cloud residency.
Within the enterprise tier, Oracle Corporation and SAP exemplify divergent anchoring strategies for European textile manufacturers. Oracle leverages database heritage for enterprise-grade deployments, while SAP sustains renewal rates through deep ERP integration. Infor occupies a position as a micro-vertical specialist differentiating from horizontal alternatives. Among mid-market pure-plays, ApparelMagic and AIMS360 Apparel Software represent the API-native order orchestration archetype capturing digitally native label procurement cycles.
| Leading Market Players |
|---|
| ApparelMagic |
| AIMS360 Apparel Software |
| Apparel Business Systems |
| Oracle Corporation |
| SAP |
| Infor |
| Microsoft |
| Computer Generated Solutions |
| Systech Infovations Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
PLM configuration expertise concentrated in Germany, the United States, and India creates wage-premium differentials that widen pricing spreads between premium certified deployments and economy-tier SaaS offerings for mid-market fashion brands.
Pricing Analysis
Input-cost pass-through from specialized talent scarcity and GDPR-compliant regional instance architectures drives subscription pricing stratification across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade PLM-to-ERP connectivity from lightweight SaaS tools, with certification investment and after-sales service bundling as key differentiation drivers. Pricing pressure stems from consumption-based procurement demands among digitally native labels seeking cash-flow flexibility over capitalized assets. Independent designers and small-scale creators exhibit highest price sensitivity, while multi-brand retailers prioritize functional capability over unit economics.
Supply Chain Analysis
Logistics and freight cost volatility from nearshoring initiatives into Mexico, Turkey, and Portugal reshapes vendor coordination economics for supply chain module providers. Software development and cloud infrastructure provisioning concentrate in the United States, Germany, and India, with API connectivity components and AI governance stacks as critical input dependencies. Single-source vulnerability in specialized PLM configuration talent pools creates project bottlenecks outside core talent clusters. Distribution runs through direct vendor relationships with fashion brands and textile manufacturers, supplemented by channel partnerships with systems integrators in regional industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where the EU AI Act's algorithmic transparency mandates create sustained demand pull for pre-certified AI governance stacks across European deployments.
For Market Incumbents: Cement renewal rates among European textile manufacturers through deep ERP integration investments that resist displacement by cloud-native entrants. Prioritize certification roadmaps for EU AI Act compliance to capture algorithmic transparency premiums before regulatory deadlines harden procurement criteria. Defend against API-native mid-market specialists by embedding TikTok Shop and Instagram Checkout connectivity into existing platform architectures. For New Entrants and Emerging Players: Generative AI pattern optimization tools offer a technology-first wedge into digitally native label procurement cycles in the United States and United Kingdom. Target warehouse automation segments in India's Tiruppur and Surat textile clusters where BIS-certified cloud infrastructure demand outpaces domestic vendor supply. Lead with consumption-based pricing models tied to order volume rather than seat count to align with CFO cash-flow priorities. For Investors and Strategic Acquirers: Enterprise software conglomerates pursuing vertical consolidation are the most active acquirer in this space, seeking AI governance stack capabilities to satisfy European regulatory requirements. Long-term viability hinges on compliance certification depth rather than functional feature parity, favoring targets with established EU AI Act documentation protocols. Monitor BIS cloud security guideline enforcement in India as an inflection indicator for offshore development demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Stack Acquisition | Pre-certified algorithmic transparency capabilities satisfy EU AI Act procurement criteria in France and Germany. |
| Regional Cloud Residency Partnership | GDPR-compliant data localization in European instances reduces fragmentation costs for multi-territory deployments. |
| TikTok Shop API Integration | Direct-to-consumer order orchestration captures digitally native label procurement cycles in Los Angeles and New York. |
| 3D Design-to-Production Convergence | Sample-less development workflows compress design-to-shelf timelines for Paris luxury houses. |
| Circular Economy Module Development | France's AGEC law mandates product passport functionality for extended producer responsibility compliance. |
Research Methodology
Coverage spans the United States, Germany, India, France, and the United Kingdom, with primary inputs from each market informing demand quantification and competitive positioning assessments. Primary interviews with CTOs at fashion brands, IT procurement officers at textile manufacturers, platform engineers at cloud infrastructure providers, and integration specialists at systems integrators combined with secondary validation from SEC filings, hyperscaler capex disclosures, and customs records. Bottom-up sizing of vendor license revenues triangulated against top-down macroeconomic indicators and digital textile infrastructure investment flows.
Rate-of-change decomposition across deployment models, organization size tiers, solution types, application segments, and regional adoption patterns anchored CAGR derivation. Segmentation modeling incorporated cloud migration velocity, regulatory compliance burden intensity, and direct-to-consumer channel penetration as industry-specific forecast inputs. Value outputs reflect installed base evolution, replacement cycle compression, and pricing tier shifts throughout the forecast period.
The model holds under sustained regulatory enforcement of GDPR and EU AI Act provisions; deviation in BIS guideline implementation timelines or state-level US privacy law harmonization would shift vendor certification investment returns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Freight Forwarding Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Session Support Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Global Chromatography Software Market
Software & Services
Android Emulator Market
Software & Services
Automotive Hypervisor Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Sports League Management Software Market
Software & Services
Content Creation Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
App Creation Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
App Building Software Market