
 Global Business Management Software Market | 2026-2036
Global Business Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Management Software Market Foresight
Subscription-based financing and asset-light SaaS licensing is tilting competitive dynamics toward vendors with scalable cloud infrastructure. Microsoft leverages its Azure backbone to dominate enterprise deployments across hybrid environments. SAP sustains deep integration advantages in manufacturing verticals through specialized ERP modules. Salesforce competes aggressively in CRM segments by extending platform extensibility through low-code customization tools.
Business management software encompasses integrated application suites that automate core operational workflows including financial ledger processing, inventory optimization algorithms, and human capital allocation protocols. Cloud-native architectures now support sub-100-millisecond latency thresholds for real-time analytics dashboards serving distributed workforces. Enterprise Resource Planning retains the largest installed base while Customer Relationship Management segments show the fastest migration velocity from legacy on-premises systems. Supply Chain Management modules command premium pricing where multi-tier supplier visibility and predictive demand forecasting capabilities justify implementation costs.
The US Federal Risk and Authorization Management Program, EU GDPR certification requirements, and India's BIS cloud security standards collectively elevate compliance infrastructure to a primary procurement criterion. ISO 27001 and SOC 2 Type II attestations now function as table-stakes credentials for vendor shortlists across regulated industries. Stakeholders must evaluate vendor roadmaps against evolving AI governance frameworks before committing to long-term platform contracts.
Market Dynamics
Cloud-native ERP architectures are compressing deployment timelines from 18 months to under 90 days, forcing incumbent vendors to restructure professional services revenue models around subscription retention rather than implementation fees.
Growth Catalysts
- GDPR Article 32 mandates:European manufacturers face compulsory data residency requirements that accelerate private cloud ERP procurement. Mid-market automotive suppliers in Germany and France now prioritize ISO 27001-certified platforms for supplier audit compliance.
- AI-powered predictive analytics:Machine learning modules embedded in supply chain management suites reduce inventory carrying costs. Discrete manufacturers deploy these tools for demand forecasting across multi-tier supplier networks.
- India's BIS cloud security standards:Domestic software vendors gain procurement preference in government tenders. State-level digital transformation mandates in Maharashtra and Karnataka drive SaaS adoption among textile and pharmaceutical exporters.
Market Restraints
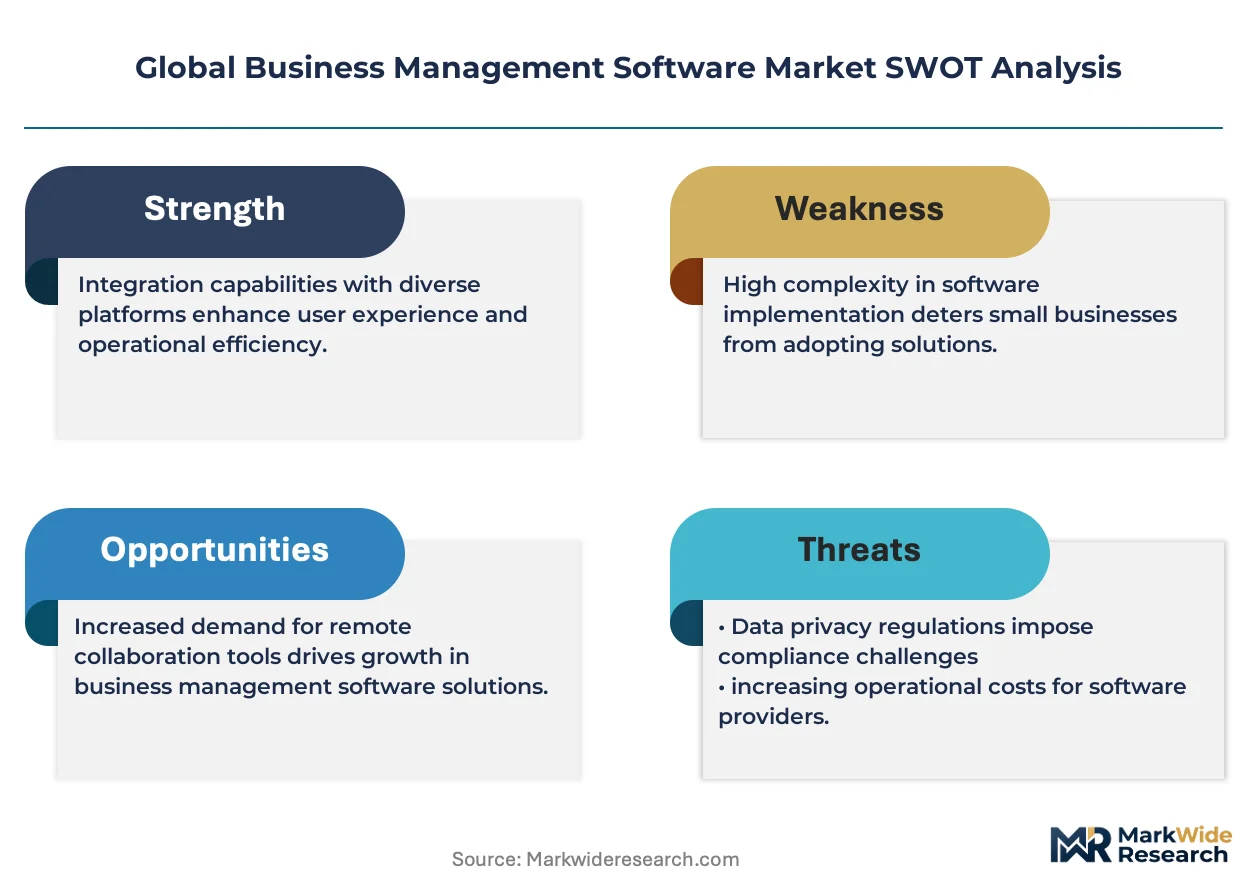
- Specialized implementation talent scarcity:Certified SAP S/4HANA and Oracle Cloud consultants command 40-60% wage premiums. System integrator capacity constraints extend project initiation queues to 8-12 months in North American and Western European markets.
- Data sovereignty fragmentation:Conflicting localization requirements across Brazil's LGPD, China's PIPL, and Russia's data localization laws force vendors to maintain redundant infrastructure. Compliance architecture costs consume 15-25% of cloud platform operating budgets.
- Legacy technical debt:Custom-coded ABAP and COBOL extensions in incumbent ERP systems resist standard API migration. Manufacturing enterprises retain 20-30 year old core systems due to replacement risk aversion.
Strategic Opportunities
- Indonesia's MSME digitalization incentives:Government co-financing covers 50% of cloud software licensing for firms below 300 employees. Local system integrators partner with global vendors to capture this underserved segment.
- Convergence of IoT sensor networks with ERP platforms:Real-time shop-floor data ingestion enables predictive maintenance modules. Asset-intensive industries in oil and gas and mining pilot these integrated stacks.
- EU AI Act compliance tooling:Risk management documentation and algorithmic audit trails become mandatory for high-stakes automated decision systems. Governance software modules command premium pricing in financial services and healthcare verticals.
Industry Challenges
- Multi-cloud integration complexity:Enterprises operating AWS, Azure, and Google Cloud environments struggle with unified identity management. Cross-platform data orchestration requires specialized middleware that fragments vendor accountability.
- SOC 2 Type II audit preparation:Startups and mid-market SaaS providers face 6-9 month certification timelines. Control documentation and third-party attestation costs delay enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Management Software Market |
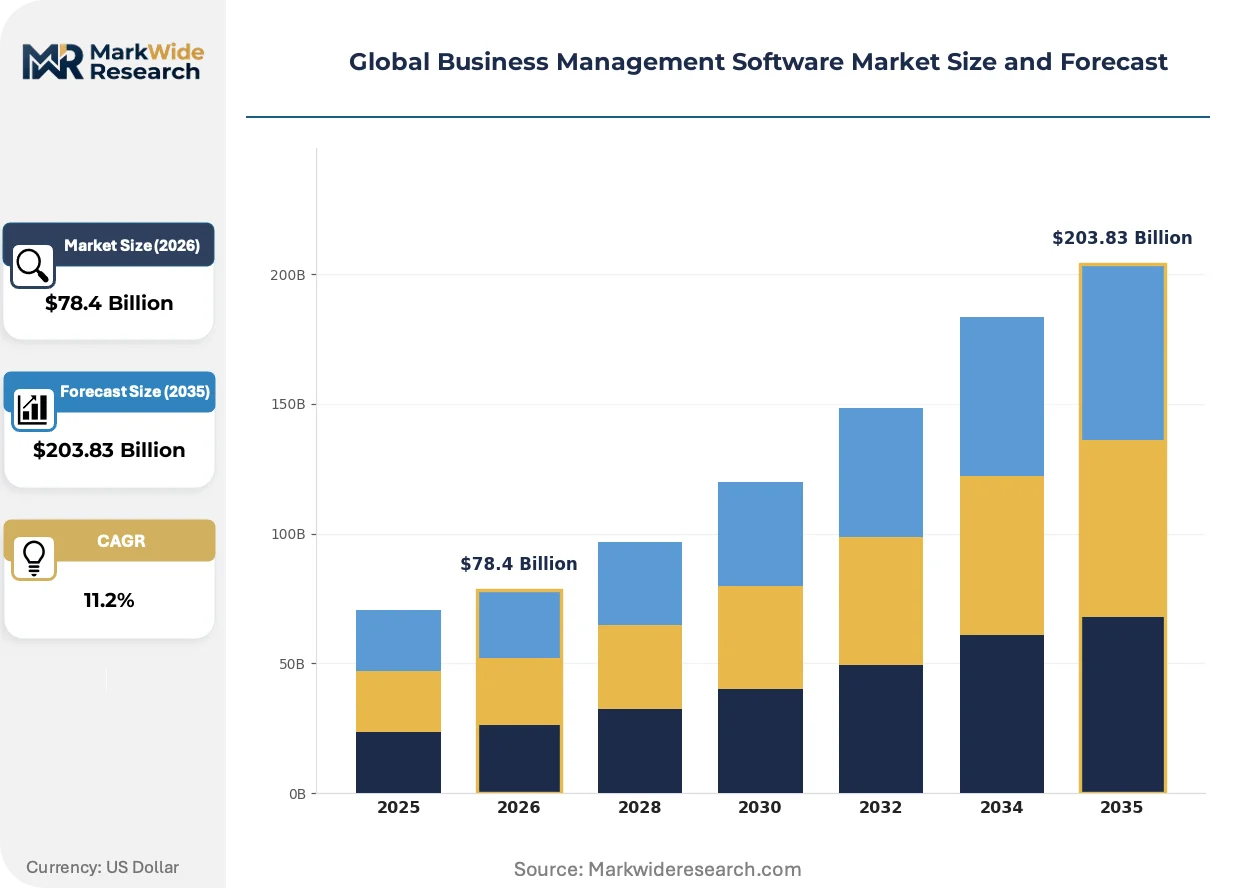
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $203.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Enterprise Resource Planning, Customer Relationship Management, Supply Chain Management, Human Capital Management Application: Financial Management, Sales Management, Inventory Control, Project Management, Compliance Tracking End User Industry: Manufacturing, IT Services, Hospitality, Telecommunications, Transportation |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, IBM Corporation, Salesforce Inc., Infor Inc., Adobe Inc., Workday Inc., ServiceNow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Management Software Market Shifts & Advancements
Agentic AI architectures are redefining workflow automation boundaries, shifting competitive advantage from feature breadth to autonomous task completion reliability. This transformation compresses the traditional software value chain.
Generative AI copilots embedded in financial planning modules is rendering obsolete manual variance analysis and static forecasting spreadsheets. Fortune 500 treasury departments pilot these tools for real-time scenario modeling. The technology compresses analyst headcount requirements while elevating strategic finance function status.
EU CSRD sustainability reporting mandates force ERP vendors to embed emissions calculation engines directly into procurement and logistics workflows. Scope 3 supplier data collection becomes a configurable module rather than external spreadsheet exercise. Automotive and electronics manufacturers in Germany and the Netherlands face the steepest compliance timelines and drive vendor roadmap prioritization.
Mid-market buyers now demand consumption-based pricing tied to transaction volumes rather than named user licenses. Distributors and value-added resellers in the United States and United Kingdom restructure compensation models around customer success metrics. This shift pressures traditional perpetual license vendors to accelerate subscription transitions or cede share to cloud-native competitors.
Global Business Management Software Market Segmentation
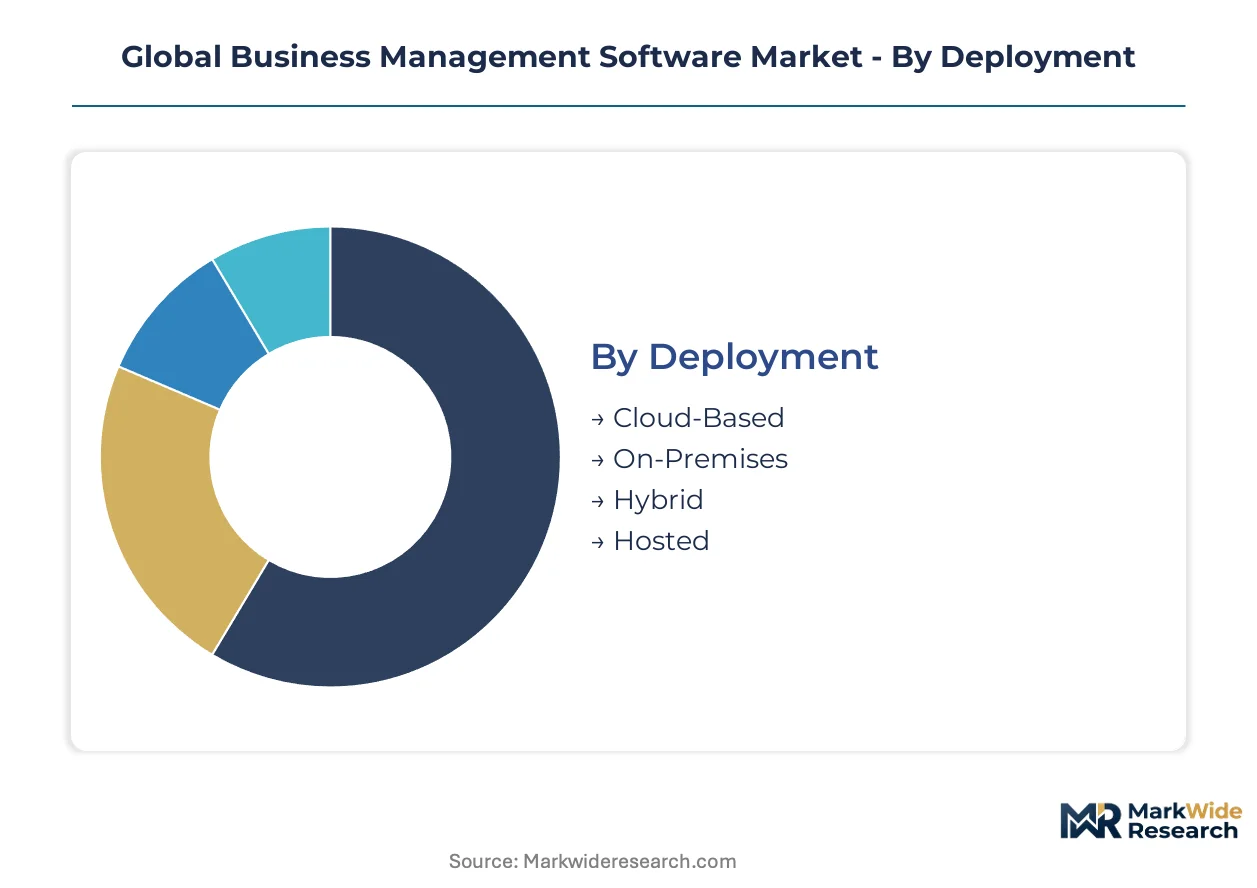
Deployment architecture determines total cost of ownership and compliance posture for procurement committees. Solution modularity shapes vendor lock-in risk and integration complexity across enterprise technology stacks.
Deployment:
Use-case spectrum spans asset-light startups to sovereignty-bound defense contractors with divergent infrastructure requirements.
- Cloud-Based:Multi-tenant SaaS architectures deliver sub-100-millisecond latency for distributed workforces. Demand concentrates among mid-market manufacturers in Germany and the United States where GDPR Article 32 and state-level privacy statutes mandate ISO 27001-certified platforms.
- On-Premises:Single-tenant installations retain full data custody within corporate firewalls. Defense contractors and classified government facilities in India and the United States specify these deployments under BIS and FedRAMP High baselines.
- Hybrid:Workload portability between private data centers and public cloud zones. Financial services firms in the United Kingdom and Singapore deploy hybrid stacks for latency-sensitive trading systems alongside archival cloud storage.
- Hosted:Dedicated single-tenant instances managed by vendor or third-party operators. Small healthcare providers in Brazil and Mexico favor hosted models for HIPAA and LGPD compliance without internal infrastructure investment.
The dominant share belongs to Cloud-Based, while Hybrid is closing the gap fastest.
Solution Type:
Cost tier stratification separates comprehensive suite vendors from point-solution specialists with divergent pricing models.
- Enterprise Resource Planning:Integrated modules spanning financial ledger, procurement, and manufacturing execution. Discrete manufacturers in Japan and South Korea deploy these systems for ISO 9001 quality traceability across multi-tier supplier networks.
- Customer Relationship Management:Sales pipeline automation and service desk orchestration with embedded analytics. Retail banking and insurance distributors in Australia and Canada prioritize CRM replacement for legacy Siebel and on-premises Microsoft Dynamics instances.
- Supply Chain Management:Multi-echelon inventory optimization and demand sensing algorithms. Automotive OEMs in Germany and electronics assemblers in Taiwan justify premium pricing for predictive supplier risk scoring.
- Human Capital Management:Payroll, talent acquisition, and workforce analytics suites. Professional services firms in the United Kingdom and Netherlands adopt these for remote hiring compliance across EU member states.
Enterprise Resource Planning commands the largest installed base, though Supply Chain Management is gaining share fastest among asset-intensive verticals.
Application:
Volume concentration follows procurement cycle intensity with financial modules leading replacement frequency.
- Financial Management:General ledger, accounts payable automation, and consolidation engines. Publicly traded corporations in the United States and Japan prioritize these modules for SOX and J-SOX audit readiness.
- Sales Management:Quotation-to-cash workflows and commission calculation engines. B2B distributors in Germany and France deploy these for EU CSRD-aligned revenue recognition documentation.
- Inventory Control:Warehouse management and demand forecasting with IoT sensor integration. Third-party logistics providers in Singapore and the Netherlands specify these for real-time stock visibility.
- Project Management:Resource allocation, time tracking, and milestone billing for professional services. Engineering consultancies in Canada and Australia standardize on these tools for fixed-price contract margin protection.
- Compliance Tracking:Regulatory deadline monitoring and audit trail preservation. Pharmaceutical manufacturers in Switzerland and medical device firms in Ireland embed these for EMA and FDA inspection readiness.
Financial Management retains the deepest penetration, while Compliance Tracking is expanding most quickly under intensifying ESG and AI governance mandates.
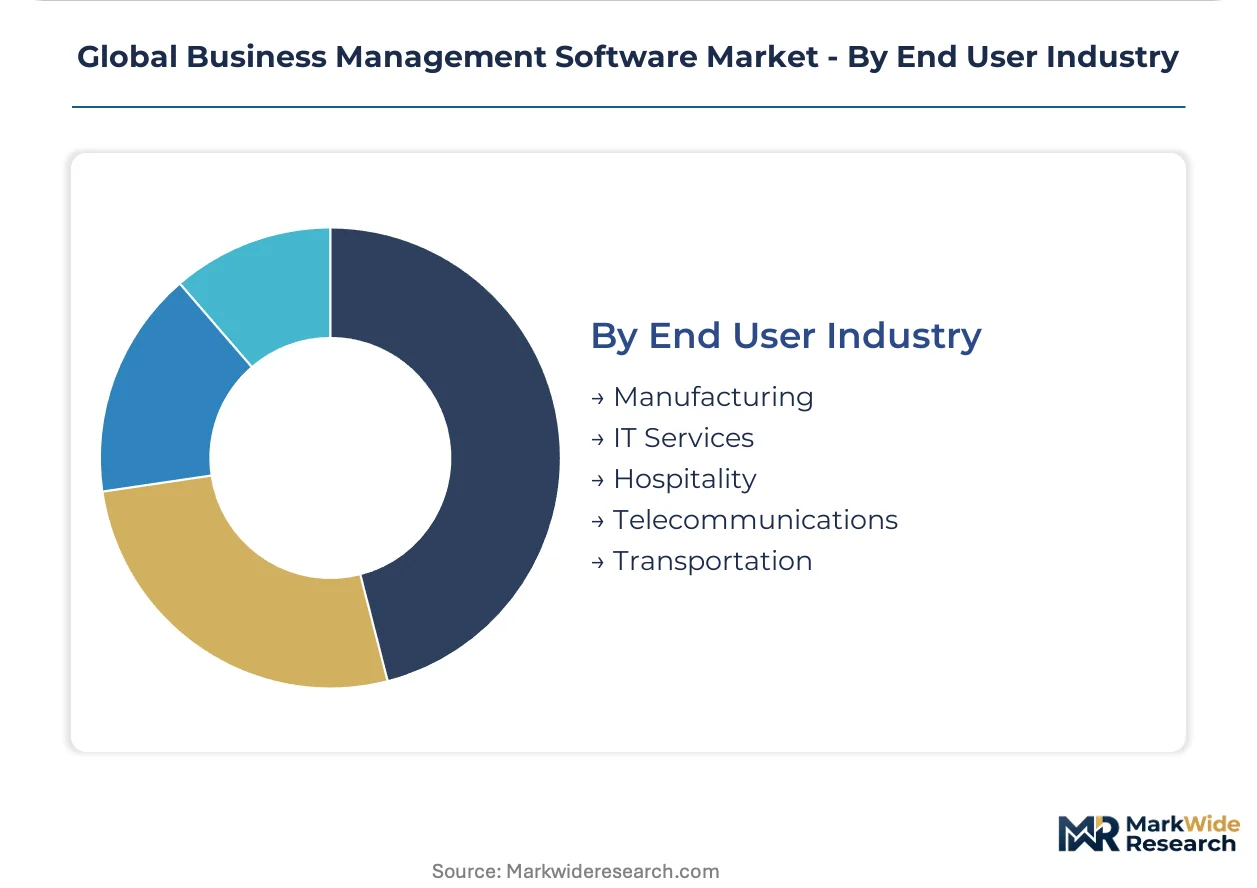
End User Industry:
Customer type differentiation separates complex multi-site manufacturers from standardized service operations with simpler configuration requirements.
- Manufacturing:Discrete and process production environments with shop-floor system integration. Automotive suppliers in Germany and semiconductor fabricators in South Korea drive demand for MES-ERP unified data models.
- IT Services:Project-based delivery organizations with utilization and margin tracking needs. Software consultancies in India and Poland adopt these for export invoicing and GST/VAT automation.
- Hospitality:Property management and revenue optimization across distributed locations. Hotel chains in the United Arab Emirates and Thailand prioritize cloud deployments for centralized yield management.
- Telecommunications:Subscription billing and network asset lifecycle management. Mobile operators in Brazil and Nigeria specify these for prepaid revenue recognition and tower maintenance scheduling.
- Transportation:Fleet dispatch, route optimization, and freight billing systems. Trucking operators in the United States and last-mile delivery platforms in Indonesia deploy these for fuel tax reporting and driver hour compliance.
Manufacturing holds the dominant position, though IT Services is climbing the fastest as remote delivery models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement committees in Germany, the United States, and India command the largest contract values, while mid-market manufacturers in Japan and the United Kingdom accelerate replacement cycles for legacy on-premises systems.
United States
Defense contractors and classified government facilities specify FedRAMP High baseline deployments under strict data custody requirements. The SEC's cybersecurity disclosure rules now mandate incident reporting timelines that compress vendor selection cycles. Silicon Valley SaaS vendors and Chicago-based system integrators dominate cloud-native ERP implementations for Fortune 500 treasury departments.
Germany
Automotive OEMs and discrete manufacturers prioritize ISO 9001 quality traceability across multi-tier supplier networks. GDPR Article 32 data residency mandates accelerate private cloud procurement for mid-market automotive suppliers in Bavaria and Baden-Württemberg. Stuttgart's manufacturing cluster drives demand for MES-ERP unified data models with sub-100-millisecond latency thresholds.
India
State-level digital transformation mandates in Maharashtra and Karnataka propel SaaS adoption among textile and pharmaceutical exporters. BIS cloud security standards grant domestic software vendors procurement preference in government tenders. Bangalore's IT services corridor and Mumbai's financial district anchor hybrid deployment demand for GST automation and export invoicing compliance.
Japan
Semiconductor fabricators and electronics assemblers deploy integrated ERP modules for J-SOX audit readiness and inventory optimization. METI's supply chain resilience initiatives subsidize predictive analytics adoption among discrete manufacturers. Tokyo-Osaka industrial corridor buyers emphasize API migration compatibility for 20-30 year old legacy core systems.
United Kingdom
Financial services firms deploy hybrid stacks for latency-sensitive trading systems alongside archival cloud storage mandates. The FCA's operational resilience requirements accelerate compliance tracking module procurement. London's professional services cluster and Manchester's emerging tech hub drive consumption-based pricing negotiations tied to transaction volumes rather than named user licenses.
Global Business Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement committee attention across deployment architecture decisions. The vendor base stratifies into three tiers: hyperscale cloud platforms with infrastructure moats, vertical ERP specialists with manufacturing integration depth, and point-solution CRM vendors with low-code extensibility. Dominant competitive moves include strategic partnerships for multi-cloud integration middleware and portfolio diversification into AI governance tooling.
Within the hyperscale tier, Microsoft Corporation exemplifies channel control through Azure backbone dominance in hybrid enterprise environments. SAP SE anchors the vertical integration archetype with specialized manufacturing modules that resist displacement by cloud-native competitors. Salesforce Inc. occupies the platform extensibility position, competing aggressively through low-code customization tools that compress implementation timelines for mid-market buyers.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Salesforce Inc. |
| Infor Inc. |
| Adobe Inc. |
| Workday Inc. |
| ServiceNow Inc. |
| Others |
Supply & Pricing Matrix
The Singapore-Hamburg maritime corridor's container rate fluctuations compress margins for cloud infrastructure providers deploying across European and Asian data centers, concentrating pricing power with hyperscale vendors who absorb freight volatility through captive submarine cable networks while tiering subscription rates by compliance certification grade.
Pricing Analysis
Cost-plus contracts indexed to hyperscaler compute unit pricing dominate enterprise SaaS procurement, with subscription tiers stratifying across ISO 27001-certified premium deployments, SOC 2-attested standard offerings, and economy tiers lacking dedicated tenancy. Price differentiation hinges on data residency guarantees and AI module inclusion, while cost compression in mid-market segments intensifies due to consumption-based pricing demands. Financial services buyers in London and Singapore exhibit lowest price sensitivity, whereas Indonesian MSMEs and Brazilian healthcare providers face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for cloud infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with memory modules and AI accelerators representing critical component dependencies. Supply chain risk centers on single-source vulnerability for advanced node chips subject to export control restrictions. Distribution runs through hyperscale data center operators, systems integrators, and value-added resellers with vertical specialization in manufacturing or financial services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agentic AI architectures and EU AI Act compliance mandates are compressing traditional software value chains, creating asymmetric opportunities for vendors with autonomous workflow capabilities and governance tooling.
For Market Incumbents: Insulate recurring revenue streams by embedding predictive analytics modules directly into core ERP workflows, neutralizing point-solution disintermediation. Accelerate ISO 27701 privacy certification investments to maintain procurement eligibility under GDPR Article 32 and India's BIS cloud security standards. Prioritize backward integration into specialized AI training infrastructure to reduce dependency on third-party model providers. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's government-subsidized MSME digitalization segment, where 50% co-financing lowers customer acquisition costs. Target compliance tracking modules for EU CSRD and AI Act documentation requirements, as automotive and electronics manufacturers in Germany and the Netherlands face compressed implementation timelines. Pursue partnership-first go-to-market strategies with local system integrators possessing existing manufacturing relationships. For Investors and Strategic Acquirers: Cloud-native ERP specialists with pre-built connector libraries for legacy ABAP and COBOL systems represent priority acquisition targets, given technical debt barriers that extend replacement cycles. Long-term viability rests on platform extensibility and multi-cloud orchestration capabilities. Monitor hyperscaler capex allocation shifts toward sovereign cloud infrastructure as an inflection indicator for regional vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified MES-ERP data models reduce Stuttgart automotive supplier deployment timelines below 90 days. |
| Strategic Partnership | Multi-cloud middleware alliances resolve identity fragmentation across AWS, Azure, and Google Cloud environments. |
| Acquisition of Specialist Firm | Legacy system migration expertise addresses 20-30 year old core system replacement aversion in Japan. |
| Geographic Expansion | Maharashtra and Karnataka state mandates create immediate addressable market for GST automation platforms. |
| Product Launch | EU AI Act risk management modules command premium pricing in Frankfurt financial services procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory databases, combining structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across Germany, the United States, India, and Japan. Bottom-up deployment volume estimates triangulate against top-down market sizing derived from vendor revenue disclosures and systems integrator capacity data.
Forecast inputs span deployment architecture, organization size tier, vertical industry, integration complexity level, and regional adoption pattern across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macroeconomic indicators and technology substitution curves. AI governance framework evolution and data sovereignty regulation expansion constitute industry-specific forecast inputs.
Sensitivities concentrate around export control expansion affecting semiconductor supply, abrupt data localization mandate proliferation, and generative AI capability commoditization. Forecasts reflect documented assumptions regarding vendor roadmap execution and enterprise procurement cycle normalization. Cross-checking against hyperscaler earnings call commentary on enterprise cloud consumption trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Course Authoring Software Market
Software & Services
Global Continuous Testing Market
Software & Services
Vlog Editing Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Global Configuration Management Software Market
Software & Services
India Sports Management Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Family Law Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Japan IT Services Market
Software & Services
Nonconformance Management Software Market