
 Global Shirt Market | 2026-2036
Global Shirt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shirt Market Outlook
Bangladesh is reconfiguring its garment export infrastructure with dedicated shirt manufacturing zones and upgraded compliance facilities. Inditex leverages vertical control from fiber sourcing to retail distribution across European and Asian markets. Fast Retailing sustains its position through technical fabric development and responsive replenishment systems in Japan and Southeast Asia. Gildan Activewear anchors North American supply with concentrated hemispheric production and private-label scale.
A shirt is an upper-body garment constructed from woven or knitted textiles, typically featuring a collar, sleeves, and front closure, with specifications ranging from single-needle stitching at 12-14 stitches per inch to fused or floating canvas interlinings in formal constructions; its commercial purpose spans professional dress codes, casual identity expression, and performance-oriented athletic coverage. Cotton shirts retain the largest volume share but carry thinner margins amid agricultural input volatility, while polyester and blended fabrics capture athletic and easy-care segments with faster replenishment cycles. The unisex category is expanding fastest among younger demographics, though men's dress shirts still command the highest unit economics in wholesale and direct channels.
The EU Green Deal and REACH chemical restrictions are tightening dye and finishing standards for shirts entering European markets, while India's BIS certification and China's GB standards govern fiber content labeling and flammability thresholds in their respective domestic markets. Bangladesh's factory safety accords and wage board revisions continue reshaping cost structures for export-oriented producers. Stakeholders must monitor how regulatory divergence between the EU, United States, and Asian manufacturing hubs affects sourcing decisions and compliance investment thresholds.
Market Dynamics
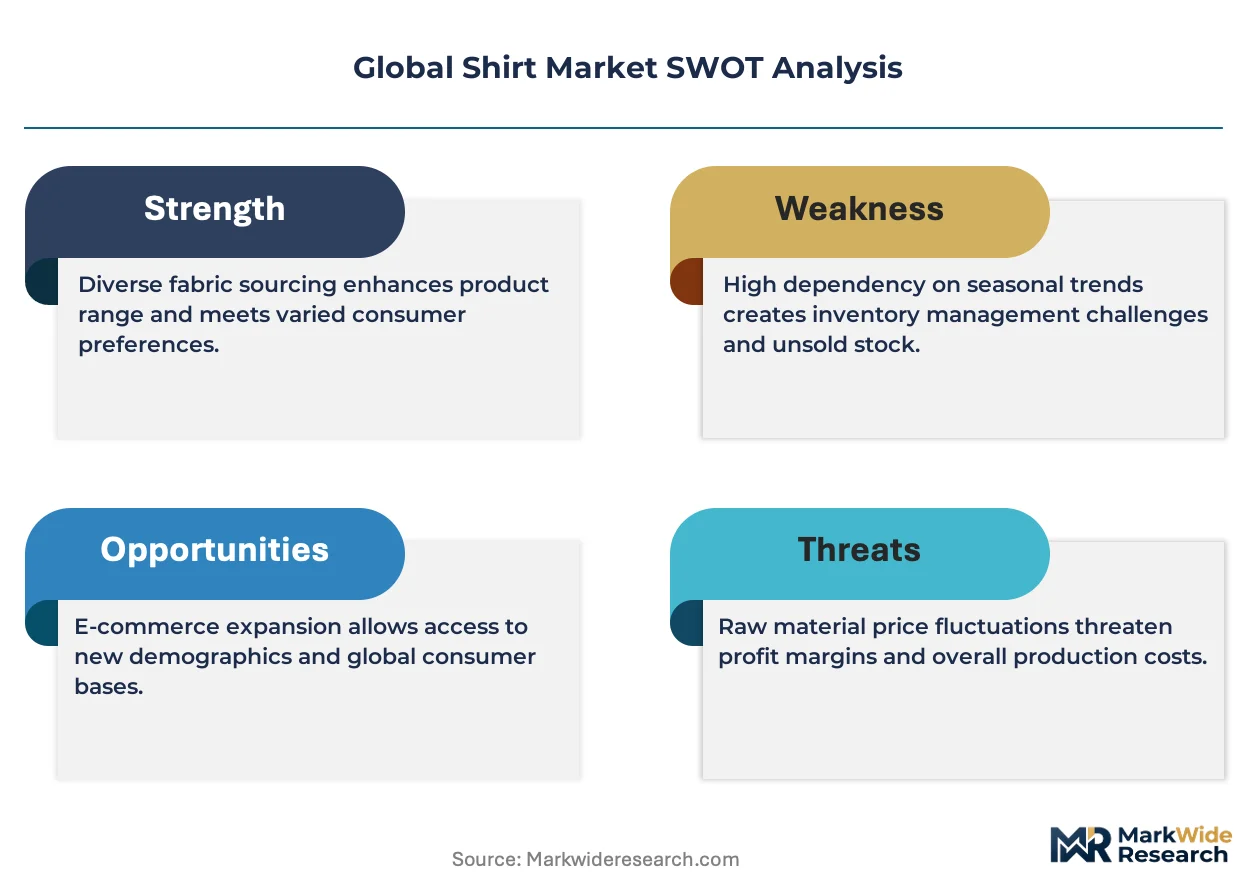
EU Green Deal textile sustainability mandates are forcing material transitions across shirt supply chains, compressing lead times for compliant fiber sourcing while elevating compliance costs for non-EU exporters.
Growth Catalysts
- REACH chemical restrictions:European dye and finishing standards are accelerating adoption of bio-based colorants and closed-loop water systems in Turkish and Moroccan finishing facilities.
- Hybrid workforce normalization:Professional dress codes are fragmenting into performance-casual segments, expanding addressable demand for wrinkle-resistant cotton-poly blends in North American corporate procurement.
- India's integrated manufacturing clusters:Export-oriented units in Tiruppur and Surat are scaling automated cutting and sewing lines, reducing unit costs for both mass and premium shirt categories.
Market Restraints
- Cotton price volatility:Agricultural input costs for raw cotton fluctuate with climate patterns in Texas and Maharashtra, compressing margins for pure-cotton shirt producers.
- Single-country supply concentration:Bangladesh's dominance in basic woven shirts creates vulnerability to factory safety accord disruptions and minimum wage board revisions.
- Polyester microfiber regulation:France's anti-waste law and proposed EU-wide restrictions on synthetic fiber shedding threaten easy-care blended fabric demand.
Strategic Opportunities
- Brazil's underpenetrated premium segment:Domestic formalwear brands lack technical fabric capabilities, creating entry points for Portuguese and Italian shirt makers with performance cotton expertise.
- Digital custom-fit platforms:AI-driven measurement apps and 3D body scanning are enabling made-to-measure shirts at ready-to-wear price points in Japanese and South Korean urban markets.
- India's PLI scheme for textiles:Production-linked incentives for man-made fiber apparel are attracting polyester and viscose shirt investments in Gujarat and Tamil Nadu.
Industry Challenges
- Technical skill scarcity:Pattern-making and fused-canvas construction expertise is aging out in Italian and Portuguese artisan workshops without sufficient apprenticeship pipelines.
- Multi-standard certification complexity:Simultaneous compliance with EU Green Deal, India's BIS labeling, and China's GB flammability standards extends product development timelines by 4-6 months.
- Legacy ERP integration:Tier-2 Asian suppliers struggle to connect factory-floor IoT sensors with European retailer demand-forecasting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shirt Market |
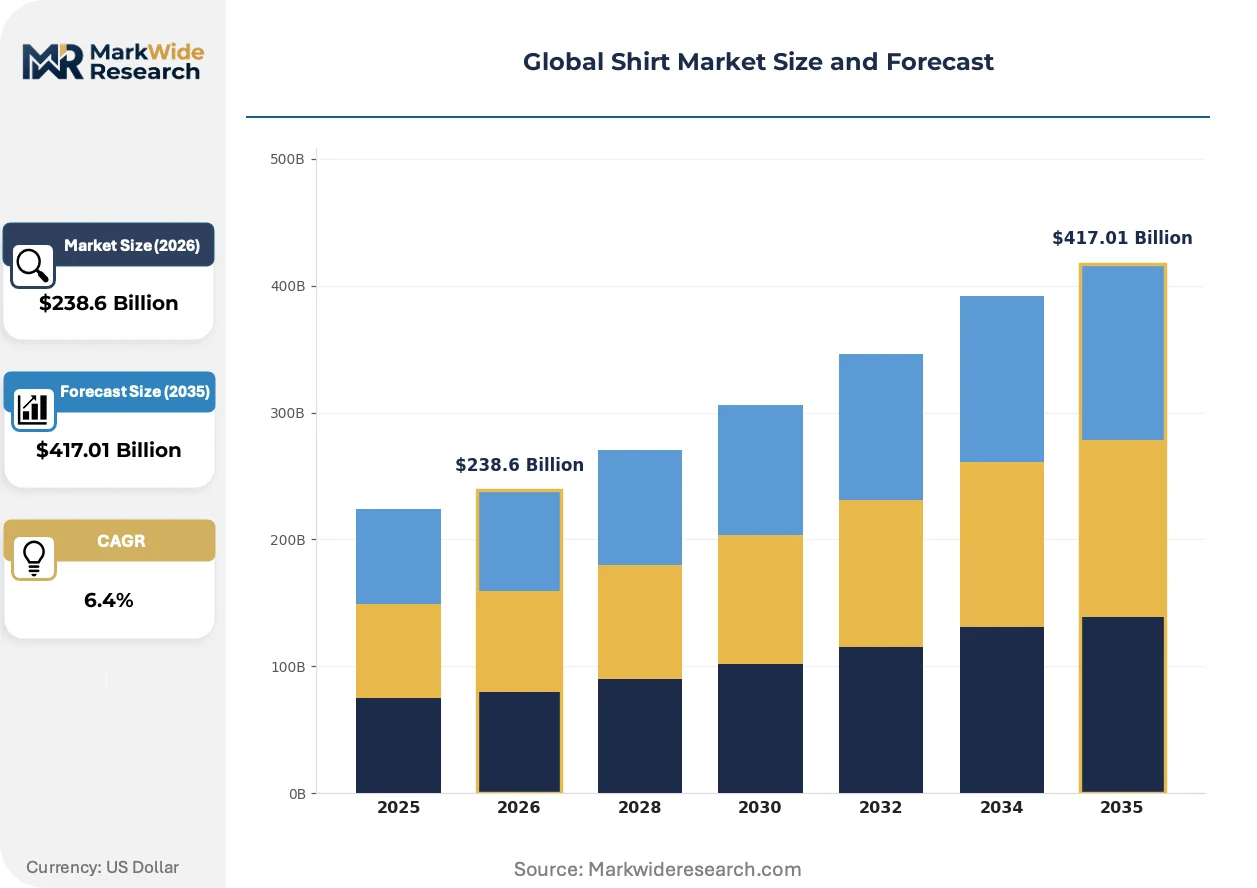
| Market Size in 2026 | $238.6 Billion |
| Market Size in 2035 | $417.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirt, Dress Shirt, Casual Shirt, Sports Shirt Fabric Type: Cotton, Polyester, Linen, Blended Fabrics Customer Type: Men, Women, Children, Unisex Distribution Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Wholesale |
| Companies Covered | Nike, Inditex, H&M, Fast Retailing, Adidas, Shein, PVH Corp, Ralph Lauren Corporation, Gildan Activewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shirt Market Strategic Shifts
Digitalization is penetrating shirt manufacturing from fiber traceability to retail inventory management, while regulatory pressure on chemical inputs and water consumption accelerates process reinvention across finishing and dyeing stages.
Laser-based denim and fabric finishing is migrating from boutique Italian and Japanese mills to mass-market suppliers in Vietnam and Indonesia. Premium workwear brands in Germany and the Netherlands are adopting the technology for localized abrasion and whiskering effects. The shift is compressing water consumption in finishing by 60-80% while enabling smaller batch sizes that align with fast-fashion replenishment cycles.
EU Green Deal textile sustainability requirements are tightening disclosure obligations for fiber origin and chemical content across all shirt categories entering European markets. The ECHA's expanded SVHC candidate list now captures additional dye intermediates and formaldehyde-based resins common in wrinkle-free cotton treatments. Formal shirt suppliers in Egypt and Turkey are restructuring finishing partnerships to maintain market access.
Corporate procurement departments are unbundling shirt specifications from bundled uniform contracts, creating direct relationships with technical fabric mills in Portugal and technical garment contractors in Romania. This disintermediation is most pronounced in German and French pharmaceutical and automotive sectors, where sustainability auditing of tier-2 suppliers now extends to employee housing and transport conditions in manufacturing locations.
Global Shirt Market Segmentation
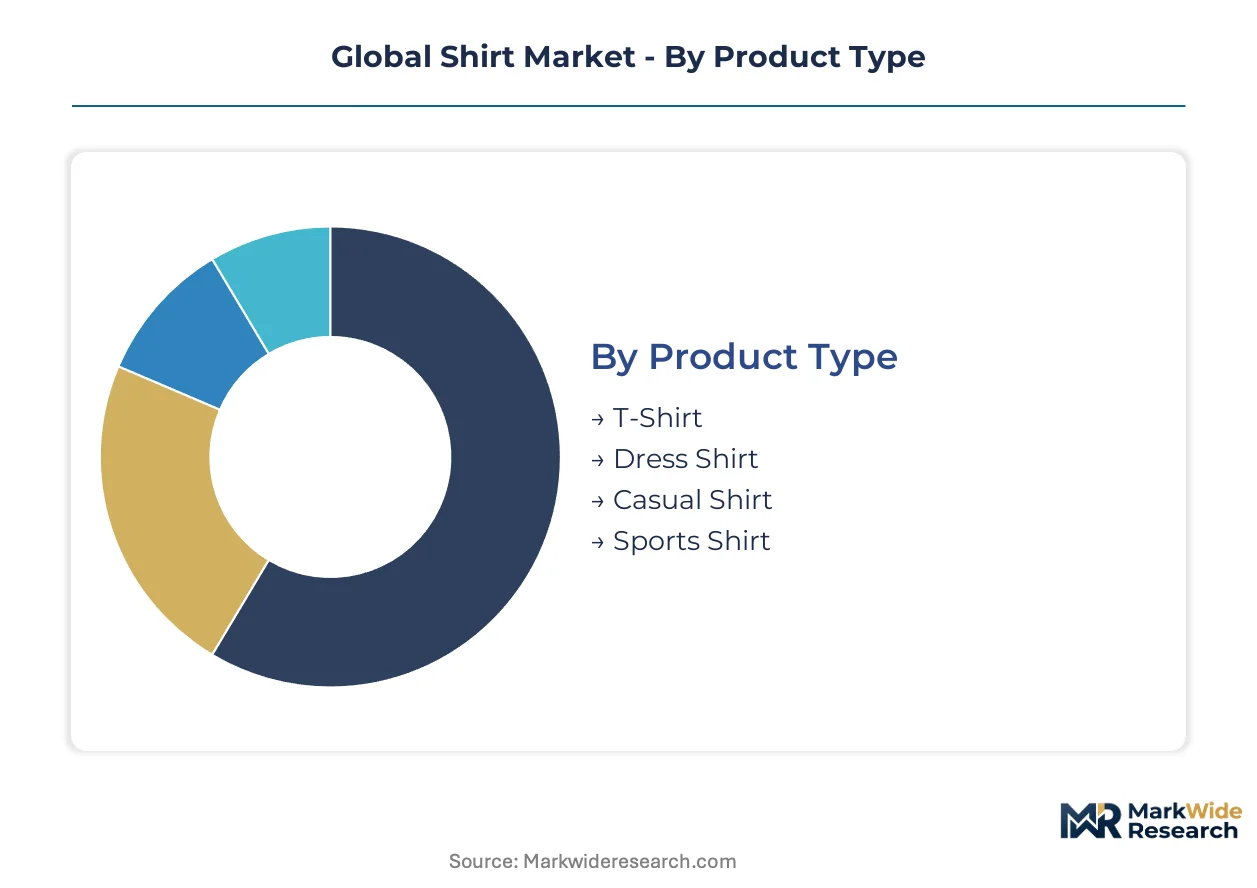
Shirt segmentation reveals how fiber technology, distribution infrastructure, and demographic targeting create distinct competitive arenas. Manufacturers align production capabilities against specific margin and velocity profiles rather than pursuing undifferentiated volume.
Product Type:
Shirt construction varies from minimal-seam knit tops to complex woven assemblies with fused interlinings and precise collar roll.
- T-Shirt:Knitted tubular or cut-and-sew construction in cotton jersey, modal, or technical synthetics. Demand concentrates in Southeast Asian export manufacturing and North American promotional channels where decoration and quick-turn replenishment drive procurement. Volume leadership masks margin compression from commodity cotton pricing and energy-intensive dye sublimation.
- Dress Shirt:Woven cotton or cotton-blend shells with structured collars, French or barrel cuffs, and fused or floating canvas construction. German and Japanese corporate procurement sustains premium demand for non-iron finishes certified under OEKO-TEX Standard 100, though REACH restrictions on formaldehyde-based resins are forcing reformulation investments.
- Casual Shirt:Flannel, chambray, or lightweight poplin constructions bridging office and leisure contexts. Portuguese mills supply washed and garment-dyed finishes to mid-tier European retailers seeking differentiation from mass-market basics.
- Sports Shirt:Performance-oriented knit or woven constructions with moisture-wicking polyester or nylon blends, often incorporating elastane for stretch recovery. Compression and ventilated panel designs target gym and outdoor segments in South Korea and Australia.
The dominant share belongs to T-Shirt, while Sports Shirt is closing the gap fastest.
Fabric Type:
Raw material selection determines finishing compatibility, care requirements, and regulatory compliance burden across export destinations.
- Cotton:Natural cellulosic fiber ranging from carded open-end yarn for basics to long-staple Egyptian or Pima for premium woven shirts. Maharashtra and Texas growing regions supply spinning mills in India and Central America, though drought-induced price spikes disrupt contract pricing stability.
- Polyester:Petroleum-derived filament or staple fiber enabling durable press, stretch recovery, and sublimation printing. Microfiber shedding regulations in France and proposed EU-wide restrictions threaten athletic and easy-care blended applications.
- Linen:Bast fiber from flax cultivation concentrated in Belgium, France, and Belarus. Belgian dew-retted linen commands premium positioning in Mediterranean summer collections, though wrinkling limits machine-washable mass adoption.
- Blended Fabrics:Cotton-polyester, cotton-linen, or tri-blend constructions balancing performance and aesthetics. Tiruppur and Surat manufacturers optimize ratios for specific end-use durability and dye uptake requirements.
Cotton retains volume leadership, though Blended Fabrics are gaining share fastest as mills engineer performance hybrids that satisfy multiple care and wear scenarios.
Customer Type:
Demographic targeting shapes pattern grading, size curve distribution, and marketing channel allocation.
- Men:Standardized sizing with neck-and-sleeve measurements for dress shirts, S-XXL grading for casual styles. Wholesale and direct channels sustain higher unit economics than women's equivalents due to lower return rates and simpler fit standardization.
- Women:Contoured darting, varied sleeve lengths, and extended size ranges driving higher SKU complexity. Fast-fashion retailers manage inventory risk through test-and-replenish algorithms tied to social media trend velocity.
- Children:Growth-accommodating features including adjustable waists, reinforced knees, and stain-resistant finishes. Seasonal back-to-school concentration creates demand spikes requiring flexible cut-make-trim capacity.
- Unisex:Relaxed fits with neutral grading curves, expanding fastest among Gen Z consumers in Japanese and South Korean urban markets where gender-fluid styling drives premium positioning.
Men's shirts dominate wholesale value, while Unisex is expanding most quickly as sizing standardization and marketing neutrality reduce inventory fragmentation.
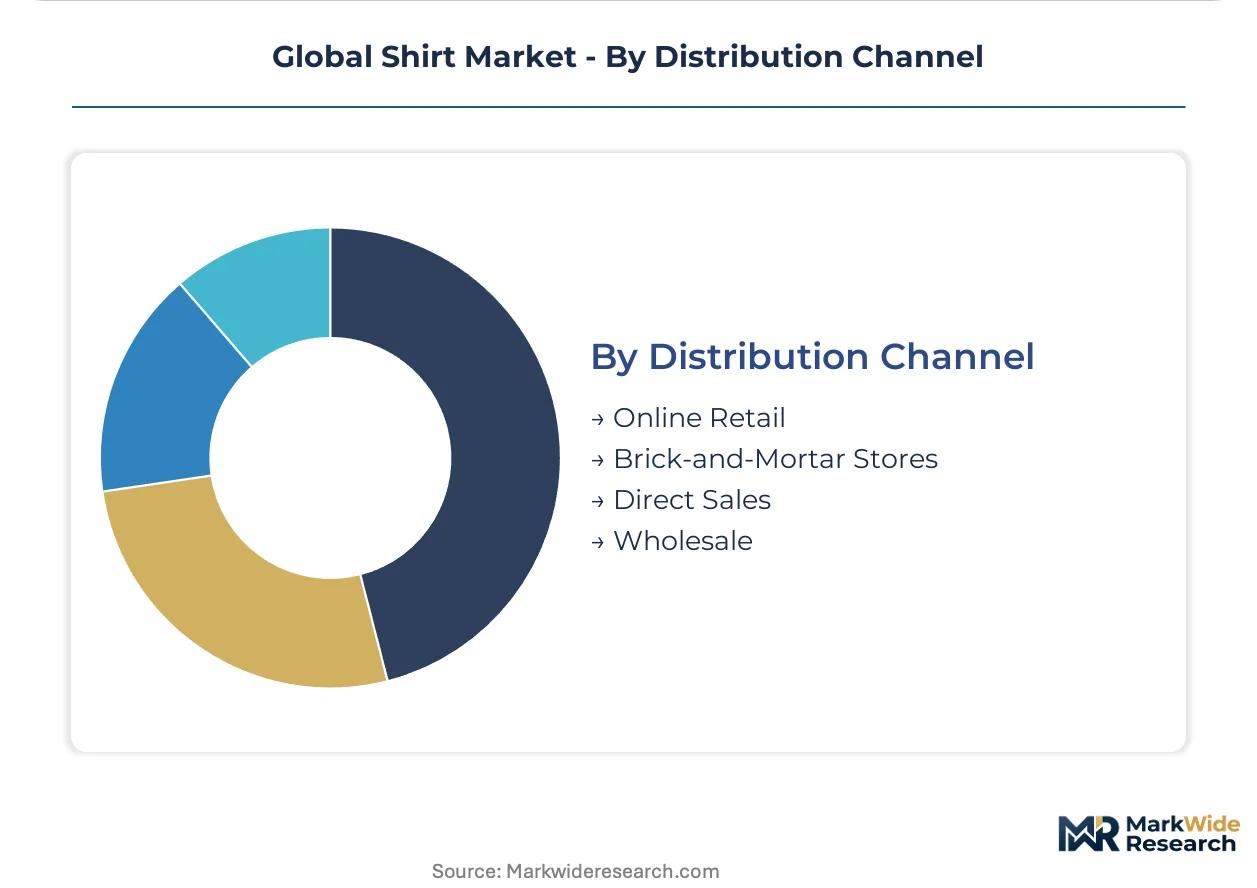
Distribution Channel:
Channel selection determines margin structure, brand control, and data capture depth for demand forecasting.
- Online Retail:Direct-to-consumer platforms, marketplace listings, and social commerce integration enabling size recommendation algorithms and virtual try-on. Return rates of 20-40% for fit-driven categories pressure logistics economics.
- Brick-and-Mortar Stores:Department store concessions, specialty retailers, and flagship locations providing tactile evaluation and immediate fulfillment. German and Japanese markets sustain higher physical retail share than North American equivalents.
- Direct Sales:Corporate uniform contracts, made-to-measure ateliers, and trunk show models. Pharmaceutical and automotive sectors in France and Germany are disintermediating traditional workwear suppliers for direct mill relationships with sustainability auditing.
- Wholesale:Volume contracts to multi-brand retailers, private-label manufacturing for department stores, and export trading house arrangements. Bangladesh and Vietnam producers rely on wholesale for basic woven shirt capacity utilization.
Online Retail commands the fastest expansion trajectory, though Wholesale retains dominant volume for mass-market woven shirts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Garment manufacturing concentrates in a handful of Asian economies where export-oriented zones and preferential trade agreements sustain cost-competitive production. Regulatory divergence between the EU, United States, and Asian manufacturing hubs is reshaping sourcing decisions and compliance investment thresholds.
Bangladesh
Export-oriented shirt production dominates the economy, with the Dhaka-Chittagong corridor hosting dedicated garment manufacturing zones and upgraded compliance facilities. Factory safety accords and wage board revisions continue reshaping cost structures for basic woven shirt exporters. The government is expanding bonded warehouse infrastructure to maintain duty-free raw material access for EU and US markets.
China
Domestic demand for mid-tier and premium shirts stabilizes as GB standards on fiber content labeling and flammability thresholds tighten enforcement. NMPA-aligned quality inspections are accelerating consolidation among smaller Guangdong and Zhejiang manufacturers. The Yangtze River Delta maintains concentration in technical fabric development for performance-oriented segments.
India
Integrated manufacturing clusters in Tiruppur and Surat are scaling automated cutting and sewing lines for both mass and premium categories. The PLI scheme for textiles is attracting polyester and viscose shirt investments in Gujarat and Tamil Nadu. BIS certification requirements on fiber content and care labeling are elevating compliance costs for domestic market entry.
Vietnam
Laser-based fabric finishing technology is migrating from boutique Italian and Japanese mills to mass-market suppliers in Ho Chi Minh City and Binh Duong provinces. EU-Vietnam free trade agreement tariff advantages are drawing order diversion from China for European-bound woven shirts. Technical skill gaps in pattern-making and complex construction limit premium segment penetration.
Turkey
REACH chemical restrictions on dye intermediates and formaldehyde-based resins are accelerating adoption of bio-based colorants and closed-loop water systems in Istanbul and Izmir finishing facilities. Proximity to EU markets enables shorter replenishment cycles for Spanish and German retailers. Egyptian cotton sourcing partnerships sustain premium positioning in Mediterranean summer collections.
Global Shirt Market Competitive Environment
Vertically integrated apparel conglomerates and specialized garment contractors split the market between scale-driven volume production and responsive fast-fashion replenishment. The vendor base spans three tiers: global sportswear licensors with technical fabric R&D, European and Asian fast-fashion operators with compressed design-to-shelf cycles, and regional private-label manufacturers serving concentrated hemispheric demand. Dominant competitive moves include backward integration into fiber sourcing and strategic partnerships with automated finishing technology providers.
Within the fast-fashion tier, Inditex and Fast Retailing exemplify divergent geographic emphases—European versus Japanese and Southeast Asian market concentration. Gildan Activewear occupies a position in the North American private-label and promotional channel, leveraging concentrated hemispheric production for volume contracts. Among sportswear licensors, Nike and Adidas represent the technical performance segment where fabric innovation and brand licensing sustain premium positioning.
| Leading Market Players |
|---|
| Nike |
| Inditex |
| H&M |
| Fast Retailing |
| Adidas |
| Shein |
| PVH Corp |
| Ralph Lauren Corporation |
| Gildan Activewear |
| Others |
Value Chain & Pricing Dynamics
Tiruppur's automated manufacturing clusters are compressing unit costs for mass-market cotton shirts while elevating pricing power for premium exports through OEKO-TEX and BIS certifications that command buyer premiums in European and domestic Indian channels.
Pricing Analysis
EU Green Deal textile sustainability mandates dictate the pricing tier structure across export-oriented shirt manufacturing, separating premium OEKO-TEX certified garments from standard BIS-compliant domestic production and economy-grade basic woven shirts. Price differentiation rests on certification grade and vertical integration depth, with Portuguese and Italian mills capturing brand premiums while Bangladeshi contract manufacturers compete on volume scale. Pricing pressure stems from REACH chemical restriction compliance costs that squeeze mid-tier producers without premium positioning. Corporate procurement departments in German pharmaceutical and automotive sectors demonstrate lowest price sensitivity due to sustainability auditing requirements, while North American promotional channels exhibit highest sensitivity to commodity cotton fluctuations.
Supply Chain Analysis
Tariff exposure between Bangladesh and the European Union dominates supply chain risk calculus for basic woven shirt exporters navigating factory safety accord disruptions and minimum wage board revisions. Manufacturing gravity centers on Bangladesh, Vietnam, and India, with raw material dependencies drawing from Texas and Maharashtra cotton cultivation, Belgian and French flax linen, and petroleum-derived polyester filament. Single-country supply concentration in Bangladesh's Dhaka-Chittagong corridor creates vulnerability to regulatory restriction cascades. Distribution runs through wholesale trading houses for mass-market volume, direct mill relationships for corporate uniform contracts, and vertically controlled retail networks for fast-fashion replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global shirt manufacturing is recovering from pandemic-era inventory destocking as hybrid workforce normalization restocks professional wardrobes across North American and European corporate procurement channels.
For Market Incumbents: Entrench compliance infrastructure ahead of EU Green Deal enforcement waves by restructuring finishing partnerships in Turkey and Morocco to maintain REACH-compliant market access. Deepen backward integration into Egyptian cotton sourcing and Belgian linen partnerships to defend margin position against agricultural input volatility. Prioritize captive supply of bio-based colorants and closed-loop water systems as regulatory leverage against emerging Asian competitors.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's underpenetrated premium formalwear segment where domestic brands lack technical fabric capabilities. Target Portuguese and Italian performance cotton expertise for white-space entry, leveraging AI-driven measurement apps and 3D body scanning to enable made-to-measure positioning at ready-to-wear price points. Pursue direct-to-corporate channel strategies in German and French pharmaceutical sectors where sustainability auditing requirements disintermediate traditional workwear suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated cutting and sewing line operators in India's PLI scheme beneficiary states. Long-term viability over the next decade hinges on laser-based fabric finishing capabilities that compress water consumption and enable fast-fashion replenishment cycles. Acquisition target archetype: Vietnamese mass-market suppliers adopting Italian laser finishing technology with EU-Vietnam free trade agreement tariff advantages. Signal to watch: order diversion velocity from China to Vietnam for European-bound woven shirts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sourcing | Egyptian cotton and Belgian linen partnerships insulate margin from agricultural volatility in Texas and Maharashtra. |
| Laser-Based Fabric Finishing Adoption | Vietnamese suppliers deploying Italian and Japanese mill technology capture EU sustainability compliance premiums. |
| AI-Driven Custom-Fit Platform Launch | Japanese and South Korean urban markets enable made-to-measure shirts at ready-to-wear economics. |
| Direct-to-Corporate Channel Expansion | German pharmaceutical and automotive sectors demand sustainability auditing that bypasses traditional workwear intermediaries. |
| PLI Scheme Manufacturing Scale-Up | Gujarat and Tamil Nadu polyester and viscose investments attract export-oriented capacity under India's textile incentives. |
Study Parameters
Desk research of customs and trade flow databases, SEC and regulatory filings, and industry association technical reports preceded structured interviews with garment manufacturing executives, retail category buyers, textile mill procurement directors, and corporate uniform program managers. Primary fieldwork captured operating dynamics across Bangladesh's factory safety accord implementation, India's PLI scheme beneficiary investments, and Vietnam's laser finishing technology migration. Secondary validation drew from EU ECHA regulatory documentation, India's BIS certification records, and Chinese GB standards enforcement reports. Bottom-up demand modeling triangulated against top-down macroeconomic consumption projections.
Assumptions held fixed include continuation of EU-Vietnam free trade agreement tariff advantages, REACH chemical restriction enforcement trajectories, and hybrid workforce normalization patterns across North American and European corporate environments. Variables modeled across the analysis window encompass fiber technology substitution rates, automation adoption curves in Indian integrated manufacturing clusters, and generational demand shifts toward unisex sizing. Segmentation dimensions included product construction type, fabric technology, customer demographic, and distribution channel architecture. CAGRs derived from historical volume and value trajectories adjusted for regulatory inflection points and technology substitution elasticities.
Sensitivities concentrate around EU Green Deal textile sustainability mandate acceleration, Bangladesh factory safety accord disruption scenarios, and cotton price volatility induced by climate patterns in major growing regions. Forecasts reflect documented assumptions regarding trade agreement continuity, regulatory enforcement intensity, and technology adoption timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Cosplay Costumes Market
Apparel & Footwear
Asia-Pacific Lingerie Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Men Jeans Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
Maternity Intimate Wear Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Mister Cap Market