
 Southeast Asia Lingerie Market | 2026-2036
Southeast Asia Lingerie Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Lingerie Market Insights
The capital-intensity divergence between integrated manufacturers and brand-assemblers is unwinding competitive stability across Southeast Asia. Triumph Intertrade AG sustains its position through captive European design studios paired with Thai production facilities. Hop Lun (Hong Kong) Limited leverages vertical control over elastic and lace sourcing to compress lead times for European retailers. WACOAL HOLDINGS CORP. anchors its regional footprint through dedicated R&D centers in Thailand that specialize in anatomical fit mapping for tropical body types.
Southeast Asia lingerie encompasses intimate apparel engineered with specific technical parameters: bras incorporate underwire gauges from 18-22mm and hook-and-eye closures tested to 5,000-cycle durability standards, while shapewear employs powernet fabrics with 25-40% elastane content to deliver graduated compression. The product serves both functional support and fashion-forward consumption across tropical climates where moisture-wicking properties determine repeat purchase rates. Bras occupy the dominant revenue position given higher unit values and replacement frequency, though shapewear registers the fastest structural expansion as Indonesian and Vietnamese consumers prioritize silhouette control for professional settings. Cotton dominates material mix for daily wear in humid climates, while lace segments command premium positioning through Thai and Vietnamese artisanal embroidery clusters.
Thailand's Ministry of Industry enforces TISI textile standards governing fiber content disclosure and colorfastness under perspiration testing, while Vietnam's Ministry of Science and Technology applies QCVN labeling rules that mandate Vietnamese-language care instructions for all imported intimate apparel. Malaysia's Department of Standards Malaysia (DSM) coordinates with SIRIM to certify flame resistance and phthalate limits in elastic components, shaping supplier qualification requirements for brands entering the market. Stakeholders must monitor how Indonesia's forthcoming national halal certification framework for textiles will reshape material sourcing and dye chemistry decisions across the supply base.
Market Dynamics
Factory capacity concentration in Vietnam's manufacturing corridors near Ho Chi Minh City and Da Nang is compressing lead times and rewiring supplier qualification protocols across the Southeast Asia lingerie ecosystem.
Growth Catalysts
- Urban professional demand:Young professional women in urban Indonesia and Vietnam are expanding purchase frequency for silhouette-control shapewear in workplace settings.
- Technical moisture management:Cotton-lace blends with engineered wicking properties are driving repeat purchase rates in humid tropical climates.
- QCVN labeling alignment:Vietnam's Ministry of Science and Technology mandates Vietnamese-language care instructions, streamlining import clearance for compliant suppliers.
Market Restraints
- Elastic component certification:Malaysia's Department of Standards Malaysia flame resistance and phthalate limits require SIRIM testing that extends supplier onboarding timelines.
- Artisanal embroidery bottleneck:Thai and Vietnamese lace clusters face capacity constraints on premium hand-finished units.
- Underwire gauge standardization:18-22mm underwire specifications limit interchangeability between integrated manufacturers and brand-assemblers.
Strategic Opportunities
- Halal textile certification:Indonesia's forthcoming national halal framework for textiles creates first-mover positioning for dye chemistry reformulation.
- E-commerce consumer protection evolution:Thailand's tightening digital commerce codes favor brands with transparent fiber disclosure and return infrastructure.
- Powernet fabric innovation:25-40% elastane content shapewear with graduated compression protocols opens professional wardrobe segments.
Industry Challenges
- Anatomical fit mapping specialization:Tropical body type R&D requires dedicated facilities and trained pattern technicians scarce outside Thailand's existing centers.
- Hook-and-eye durability testing:5,000-cycle closure standards demand capital-intensive equipment that smaller cut-and-sew operators struggle to acquire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Lingerie Market |
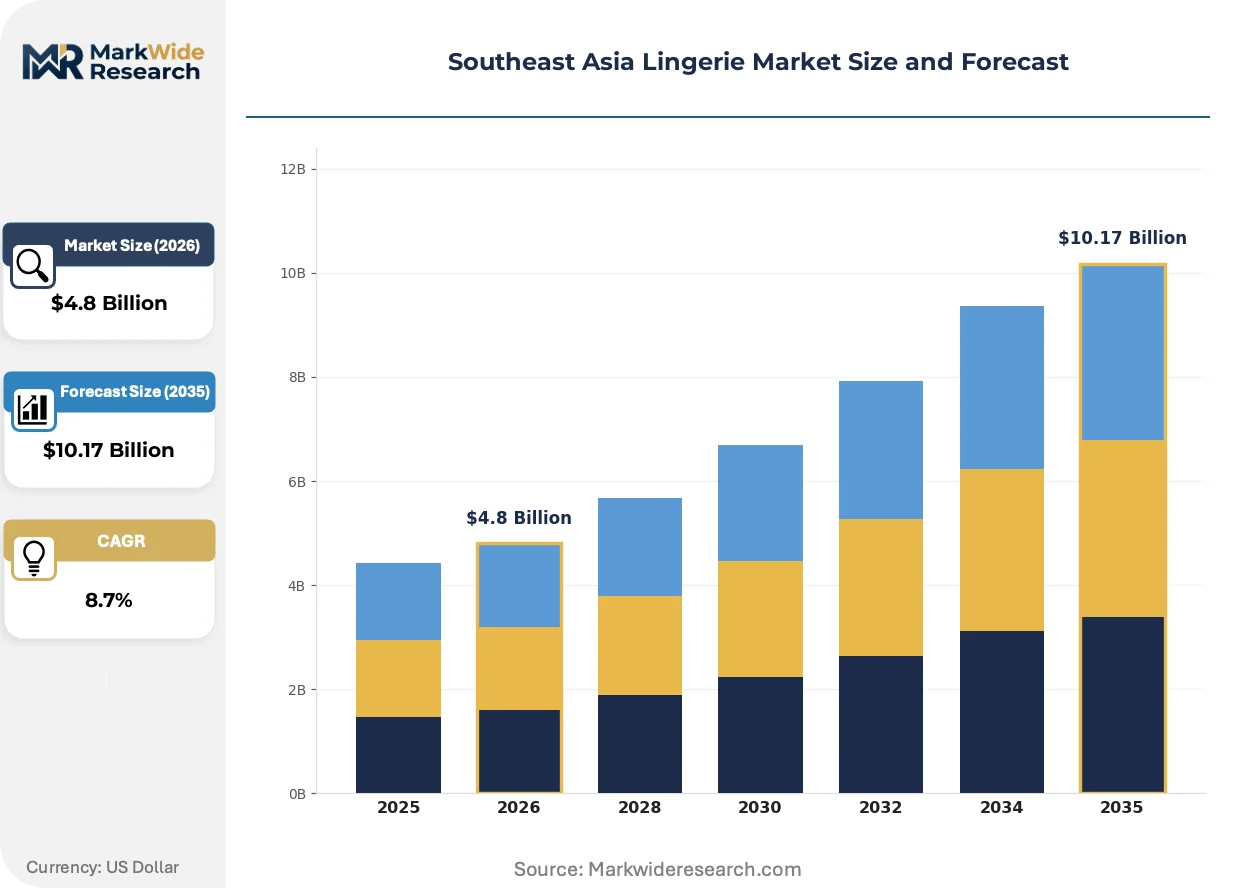
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Sleepwear, Shapewear Material: Cotton, Lace, Satin, Polyester End User: Women, Teens, Plus Size, Maternity Distribution Channel: Online, Department Stores, Specialty Stores, Supermarkets |
| Companies Covered | Aímer, Hop Lun (Hong Kong) Limited, Triumph Intertrade AG (Triumph Group), Tantex Pte Ltd, LOVELY-VN LINGERIE MANUFACTURING COMPANY LIMITED, WACOAL HOLDINGS CORP., Sabina Public Company Limited, Phattaya Industrial Co., Ltd., XIXILI Intima Sdn Bhd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Lingerie Market Trends and Innovations
Technical specification convergence between functional support and fashion-forward design is collapsing traditional category boundaries across Southeast Asia lingerie manufacturing.
Seamless bonding technology is miniaturizing garment construction by eliminating traditional stitch lines in bra cup assemblies. Indonesian and Vietnamese urban professionals are adopting bonded-edge daily wear bras at accelerating rates. This compression is enabling single-piece molding that reduces labor intensity in Ho Chi Minh City factories.
Thailand's Ministry of Industry TISI textile standards on perspiration colorfastness are tightening fiber disclosure requirements for all imported intimate apparel. Industrial consequence includes mandatory third-party testing for European brands sourcing from Thai facilities. Premium lace segments are responding by consolidating artisanal embroidery clusters under certified quality protocols.
Direct-to-consumer channel migration is fragmenting traditional wholesale dependency among Southeast Asia lingerie brands. Department store buyers in Kuala Lumpur and Jakarta are losing volume share to brand-operated digital storefronts with virtual fitting tools. Vietnam's manufacturing corridors are adapting by developing small-batch rapid response lines for e-commerce private labels.
Southeast Asia Lingerie Market Segmentation
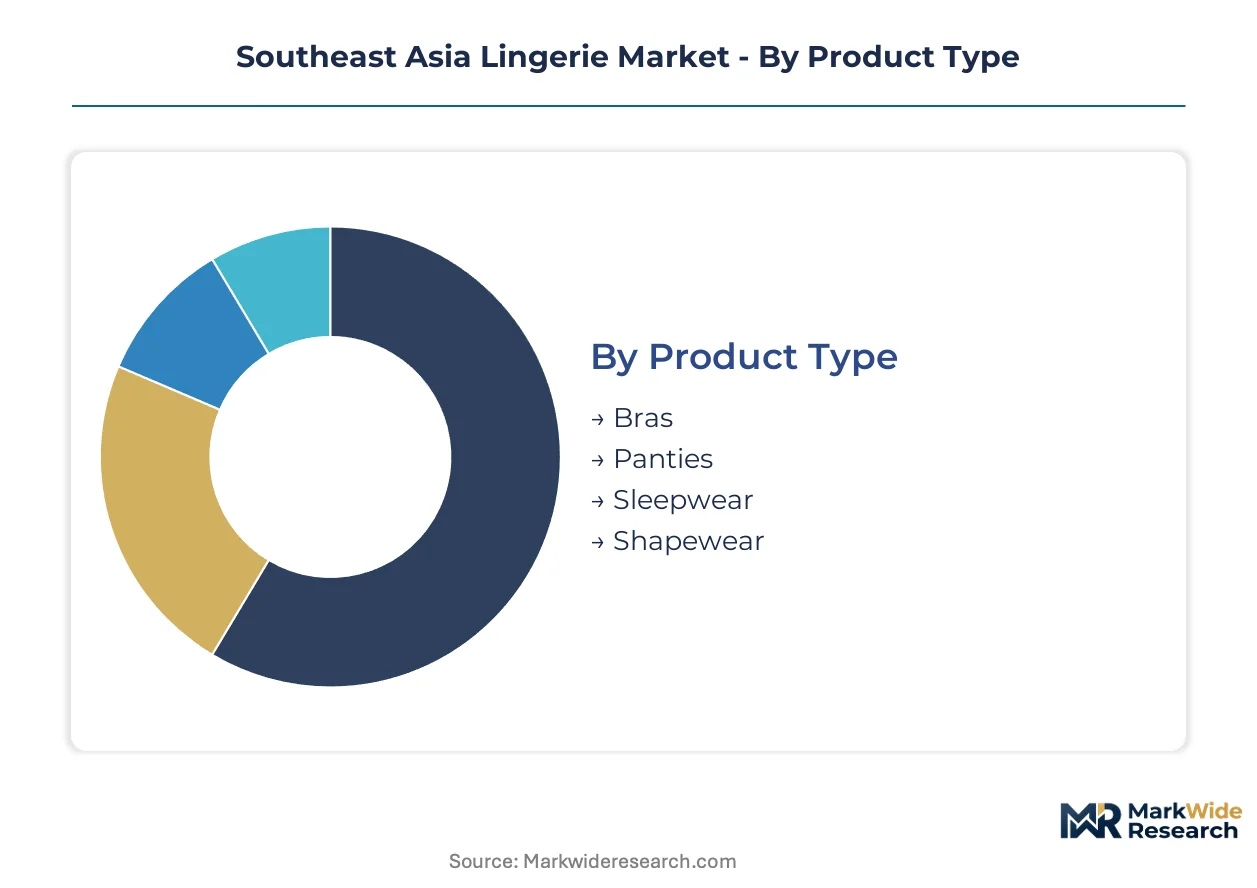
Technical specification divergence across Southeast Asia lingerie segments creates distinct sourcing and compliance pathways. Manufacturers optimize factory configurations differently for moisture-wicking daily wear versus structured occasion pieces, while distribution infrastructure varies sharply between bonded seamless units and artisanal lace assemblies.
Product Type:
Bras and shapewear face intensifying substitution pressure from athleisure crossover garments, while sleepwear competes with loungewear expansion from regional apparel brands.
- Bras:Underwire gauges from 18-22mm and hook-and-eye closures tested to 5,000-cycle durability standards define structural integrity requirements. Demand concentrates among young professional women in urban Indonesia and Vietnam, where workplace dress codes drive replacement frequency for silhouette-control styles.
- Shapewear:Powernet fabrics with 25-40% elastane content deliver graduated compression protocols engineered for tropical humidity. Indonesian and Vietnamese consumers prioritize these units for professional settings, compressing lead times for Ho Chi Minh City factories.
- Panties:Cotton-dominant daily wear segments serve humid climate requirements with moisture-wicking properties determining repeat purchase rates.
- Sleepwear:Satin and lace blends occupy premium positioning through Thai and Vietnamese artisanal embroidery clusters facing capacity constraints.
Bras anchors the volume base while shapewear gains share at the steepest rate.
Material:
Cost tier stratification separates commodity fiber sourcing from certified specialty inputs, with compliance testing requirements widening the procurement gap between cotton and lace segments.
- Cotton:Dominates material mix for daily wear in humid climates, with fiber content disclosure mandated under Thailand's TISI textile standards and Vietnam's QCVN labeling rules. Malaysian SIRIM flame resistance testing extends onboarding timelines for elastic-cotton blend suppliers.
- Lace:Commands premium positioning through Thai and Vietnamese artisanal embroidery clusters, where hand-finished units face capacity bottlenecks. Indonesia's forthcoming national halal certification framework for textiles will reshape dye chemistry decisions across these supply bases.
- Satin:Sleepwear and occasion-piece applications concentrate in bonded-edge construction eliminating traditional stitch lines.
- Polyester:Synthetic blends serve price-sensitive volume segments with engineered wicking properties for tropical performance.
Cotton anchors the volume base while lace expands most quickly on premium positioning.
End User:
Application-driven fit specialization creates divergent R&D requirements, with anatomical mapping protocols for tropical body types concentrated in Thailand's existing technical centers.
- Women:The core buyer cohort spans functional support and fashion-forward consumption, with young professional women in urban Indonesia and Vietnam representing the fastest-expanding segment. WACOAL HOLDINGS CORP.'s dedicated R&D centers in Thailand specialize in anatomical fit mapping for this tropical body type concentration.
- Plus Size:Specialized grading protocols and extended size ranges require pattern technicians scarce outside Thailand's technical infrastructure, creating supply-side constraints.
- Teens:Entry-price positioning competes with fast fashion crossover, compressing margin structures for dedicated lingerie brands.
- Maternity:Functional support requirements overlap with medical-grade compression garment specifications, subject to additional regulatory scrutiny.
Women anchors the volume base while plus size climbs the fastest on underserved demand.
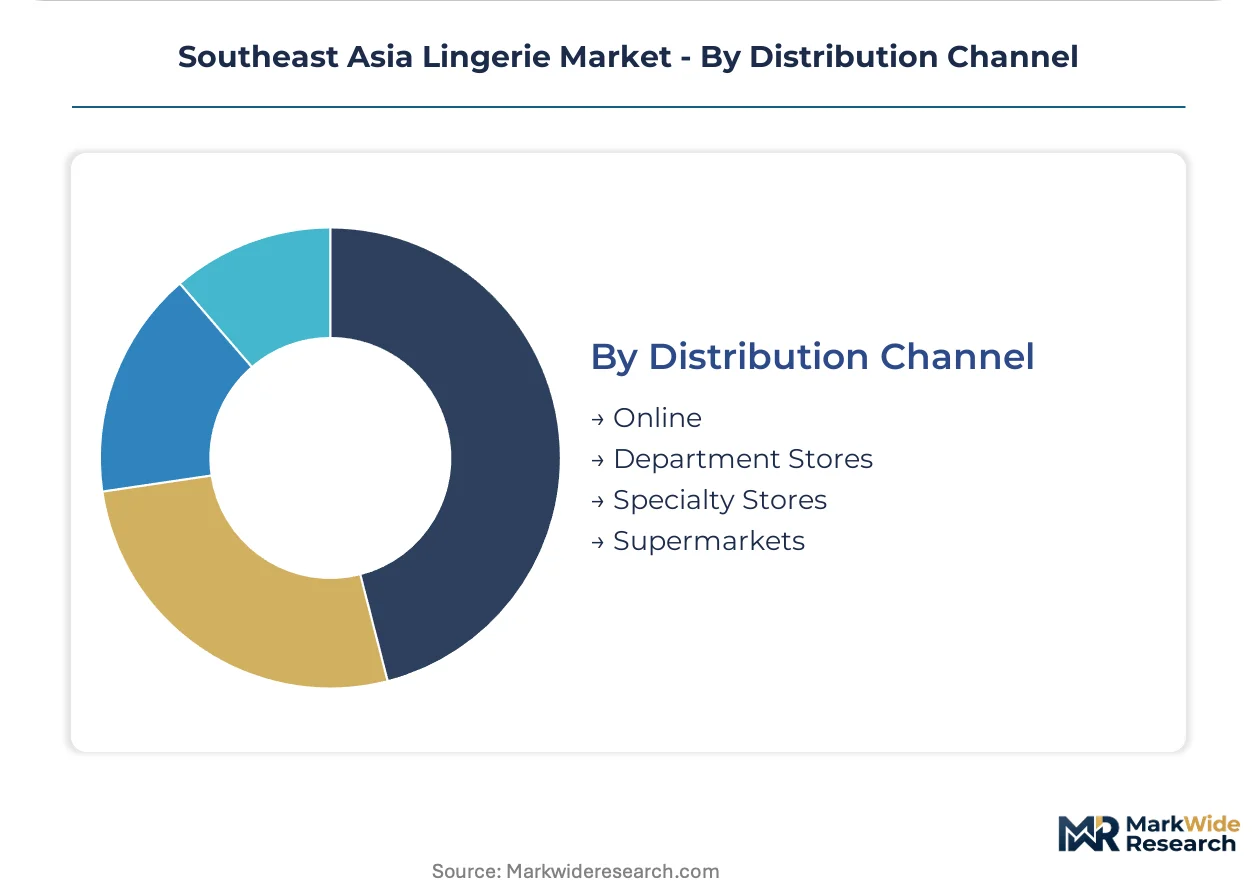
Distribution Channel:
Customer type migration from wholesale dependency to direct engagement is fragmenting traditional volume concentration, with digital infrastructure investments determining competitive survival.
- Online:Brand-operated digital storefronts with virtual fitting tools are displacing department store volume share in Kuala Lumpur and Jakarta. Thailand's tightening e-commerce consumer protection codes favor brands with transparent fiber disclosure and return infrastructure.
- Specialty Stores:Fitting expertise and private label development concentrate in Vietnam's manufacturing corridors, where small-batch rapid response lines serve e-commerce private labels.
- Department Stores:Traditional wholesale buyers in Kuala Lumpur and Jakarta are losing volume share to direct channels, compressing negotiating leverage.
- Supermarkets:Price-driven mass market positioning competes on cotton basic replenishment cycles.
Online anchors the volume base while specialty stores gain share fastest on service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam commands superior pricing leverage against Indonesian buyers due to concentrated factory capacity near Ho Chi Minh City and Da Nang, while Thailand's captive R&D infrastructure locks in premium positioning across the regional hierarchy.
Thailand
Thailand's Ministry of Industry enforces TISI textile standards governing fiber content disclosure and perspiration colorfastness testing. These regulations mandate third-party certification for all imported intimate apparel, elevating compliance costs for foreign suppliers. Bangkok and surrounding industrial zones host Triumph Intertrade AG's production facilities alongside WACOAL HOLDINGS CORP.'s dedicated R&D centers specializing in anatomical fit mapping.
Vietnam
Young professional women in urban centers drive accelerating demand for silhouette-control shapewear in workplace settings. The Ministry of Science and Technology applies QCVN labeling rules mandating Vietnamese-language care instructions for all imported lingerie. Manufacturing corridors near Ho Chi Minh City and Da Nang have expanded cut-and-sew capacity substantially, compressing lead times for European retailers.
Indonesia
Urban professional women represent the fastest-expanding buyer cohort for functional support and fashion-forward lingerie consumption. The forthcoming national halal certification framework for textiles will reshape material sourcing and dye chemistry decisions across the supply base. Jakarta and Surabaya concentrate demand while manufacturing remains import-dependent due to limited domestic elastic and lace production.
Malaysia
Department store buyers in Kuala Lumpur are losing volume share to brand-operated digital storefronts with virtual fitting tools. The Department of Standards Malaysia coordinates with SIRIM to certify flame resistance and phthalate limits in elastic components, extending supplier onboarding timelines. Textile labeling regulations tighten product compliance requirements for brands entering the market through Penang and Johor logistics corridors.
Singapore
High-income consumers anchor premium positioning for artisanal lace segments with Thai and Vietnamese embroidery clusters. E-commerce consumer protection evolution favors brands with transparent fiber disclosure and return infrastructure. The city-state functions as regional headquarters and distribution hub rather than manufacturing center, connecting Southeast Asian production with global brand management.
Southeast Asia Lingerie Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive European design studios and vertical control over elastic and lace sourcing. The vendor base stratifies across three tiers: multinational brand-assemblers with dedicated R&D facilities, Hong Kong-based vertical specialists compressing lead times through upstream control, and regional cut-and-sew operators serving e-commerce private labels. Dominant competitive moves include strategic partnerships with artisanal embroidery clusters and geographic expansion into Vietnam's manufacturing corridors.
Among Thailand-based integrated manufacturers, Triumph Intertrade AG and WACOAL HOLDINGS CORP. exemplify the R&D-intensive archetype through dedicated technical centers. Hop Lun (Hong Kong) Limited represents the vertical specialist model with control over elastic and lace sourcing. These three entities occupy distinct positioning within a market where anatomical fit specialization and supply chain compression determine competitive survival.
| Leading Market Players |
|---|
| Aímer |
| Hop Lun (Hong Kong) Limited |
| Triumph Intertrade AG (Triumph Group) |
| Tantex Pte Ltd |
| LOVELY-VN LINGERIE MANUFACTURING COMPANY LIMITED |
| WACOAL HOLDINGS CORP. |
| Sabina Public Company Limited |
| Phattaya Industrial Co., Ltd. |
| XIXILI Intima Sdn Bhd |
| Others |
Pricing and Supply Chain Analysis
Thailand's TISI textile standards on fiber content disclosure and perspiration colorfastness simultaneously gate supplier qualification and enable price differentiation through certified premium tiers. Compliance investment separates bonded-edge seamless manufacturers from commodity cut-and-sew operators, concentrating margin capture among integrated producers with captive testing infrastructure.
Pricing Analysis
Configured-to-order pricing for custom-fitted bras with anatomical mapping commands substantial premiums over standard-size daily wear. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and vertical integration depth. Cost compression in economy cotton basics is intensifying because Vietnamese factory capacity expansion feeds price competition among undifferentiated assemblers. Brand-assemblers sourcing from Ho Chi Minh City corridors exhibit highest price sensitivity, while integrated manufacturers with Thai R&D facilities maintain lowest sensitivity through proprietary fit technology.
Supply Chain Analysis
Vietnam and Thailand anchor cut-and-sew lingerie production, while China and Hong Kong feed elastic, lace, and specialized powernet fabrics. The supply chain draws from petrochemical-derived elastane, cotton fiber from South Asian ginning operations, and artisanal embroidery clusters concentrated in Thai and Vietnamese craft zones. Single-source vulnerability sits with European design studios controlling premium pattern libraries. Distribution runs through brand-operated digital storefronts displacing traditional department store wholesale in Kuala Lumpur and Jakarta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's forthcoming national halal certification framework for textiles constitutes a regulatory inflection that will reshape material sourcing and reward first-mover chemistry reformulation. This disruption amplifies growth capture for suppliers aligning dye and fiber decisions ahead of mandatory compliance deadlines.
For Market Incumbents: Consolidate artisanal embroidery cluster partnerships under certified quality protocols to defend premium lace positioning against emerging Vietnamese competitors. Deepen captive R&D investment in tropical body type anatomical mapping to maintain differentiation as bonded-edge seamless technology commoditizes. Threat substitution from athleisure crossover garments demands accelerated silhouette-control innovation in shapewear lines.
For New Entrants and Emerging Players: Lead with halal-certified textile sourcing to capture underserved Indonesian professional women demand ahead of incumbent retooling cycles. Target plus-size segments where specialized grading protocols and pattern technician scarcity create penetrable white space. Go-to-market through specialty store partnerships in Vietnam's manufacturing corridors leverages existing small-batch rapid response infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational apparel conglomerates with underoptimized lingerie divisions lacking dedicated Southeast Asian production footprint. Long-term viability centers on vertical control over elastic and lace inputs combined with e-commerce return infrastructure. Signal to watch: Indonesian halal certification implementation timeline accelerating dye chemistry supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Alignment | First-mover positioning in Indonesian market ahead of mandatory textile framework implementation. |
| Artisanal Cluster Consolidation | Certified quality protocols for Thai and Vietnamese embroidery secure premium lace supply. |
| Direct-to-Consumer Infrastructure | Virtual fitting tools and return logistics capture volume share from Kuala Lumpur department stores. |
| Tropical R&D Center Expansion | Anatomical fit mapping specialization addresses fastest-growing urban Indonesia and Vietnam cohorts. |
| Powernet Fabric Innovation | Graduated compression protocols with 25-40% elastane content open professional wardrobe segments. |
Research Methodology
Cross-validation between primary interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners and secondary sources including customs records, Nielsen retail audit data, and Ministry of Industry filings anchors the qualitative findings. Bottom-up factory capacity assessments across Ho Chi Minh City and Da Nang corridors triangulate with top-down consumer expenditure surveys in Jakarta, Bangkok, and Kuala Lumpur.
Sensitivity analysis across product type, material grade, end-user application, and distribution channel dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by replacement frequency differentials and professional wardrobe adoption curves. Industry-specific inputs include moisture-wicking fabric technology penetration rates and e-commerce consumer protection code evolution in Thailand.
The analysis sits within stated boundaries; outcomes outside sustained urban professional income growth and halal certification implementation timelines would require recalibration. Forecasts reflect assumptions on factory capacity utilization and artisanal embroidery labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Maternity Intimate Wear Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Seamless Underwear for Men Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Fast Fashion Market