
 Outdoor Jacket Market | 2026-2036
Outdoor Jacket Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Jacket Market Analysis
Modular layering systems is shifting how consumers assemble protection across conditions rather than buying single-purpose garments. Arc'teryx anchors this trend through system-compatible shells and mid-layers designed for interchangeable use. Patagonia leverages repair infrastructure and resale channels to sustain customer relationships beyond initial purchase. Columbia Sportswear competes on accessible price points while maintaining waterproof-breathable performance across mass retail.
An outdoor jacket is a weather-protective outer garment engineered with laminated membranes, taped seams, and synthetic insulation to manage heat, moisture, and wind exposure during outdoor activity. Construction typically involves multi-layer fabric assemblies with hydrostatic head ratings and breathability indices measured in grams per square meter per day. Waterproof jackets lead volume due to universal utility across hiking and casual use, while insulated jackets capture premium margin pools in cold-climate alpine applications. Softshell jackets represent the fastest-expanding category as trail runners and fast hikers prioritize breathability over absolute storm protection. Synthetic fabrics dominate material supply as brands reduce reliance on down insulation amid wash-cycle performance concerns.
The EU Green Deal and REACH chemical restrictions shape material choices by limiting perfluorinated compounds in durable water repellent treatments across European supply chains. The Ecodesign for Sustainable Products Regulation extends these constraints to product-level durability and recyclability requirements. Stakeholders must monitor how California's Safer Consumer Products program and China's GB standards evolve in parallel, as diverging compliance obligations will fragment testing and certification costs for multi-region brands.
Market Dynamics
Modular layering systems are restructuring demand patterns as consumers assemble interchangeable protection components rather than purchasing standalone garments. REACH chemical restrictions and the EU Green Deal are simultaneously forcing material substitutions across European supply chains.
Growth Catalysts
- EU Green Deal textile requirements:Mandates for recycled synthetic fabrics and PFC-free waterproofing treatments are accelerating sustainable material adoption across manufacturing bases.
- Alpine tourism expansion:Switzerland and Austria are scaling uniform and rental jacket procurement as guided expedition volumes climb in the Eastern Alps.
- Fast-hiker breathability priorities:Trail runners and speed-oriented trekkers are pulling demand toward softshell constructions that trade absolute storm protection for moisture management.
Market Restraints
- Petrochemical input volatility:Synthetic fabric production remains exposed to oil price swings that compress margin predictability for membrane and insulation suppliers.
- Fluorinated chemistry phase-out:REACH restrictions on perfluorinated compounds are forcing reformulation of durable water repellent treatments without fully mature alternatives.
- Down insulation substitution limits:Wash-cycle performance degradation in natural fill materials restricts premium positioning for certain cold-climate applications.
Strategic Opportunities
- Repair and resale infrastructure:Brands can capture extended customer lifetime value through post-purchase service channels that delay replacement cycles.
- Club-organized hiking density:Germany's Bavarian and Baden-Württemberg regions present concentrated demand pools through established outdoor association networks.
- Ecodesign for Sustainable Products Regulation:Early compliance with durability and recyclability mandates positions suppliers for preferred procurement status.
Industry Challenges
- Multi-regulatory testing fragmentation:Diverging compliance obligations across California's Safer Consumer Products program, China's GB standards, and EU REACH are inflating certification costs.
- Membrane-breathability trade-off engineering:Achieving hydrostatic head ratings alongside moisture vapor transmission targets requires specialized lamination expertise that concentrates among limited equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Jacket Market |
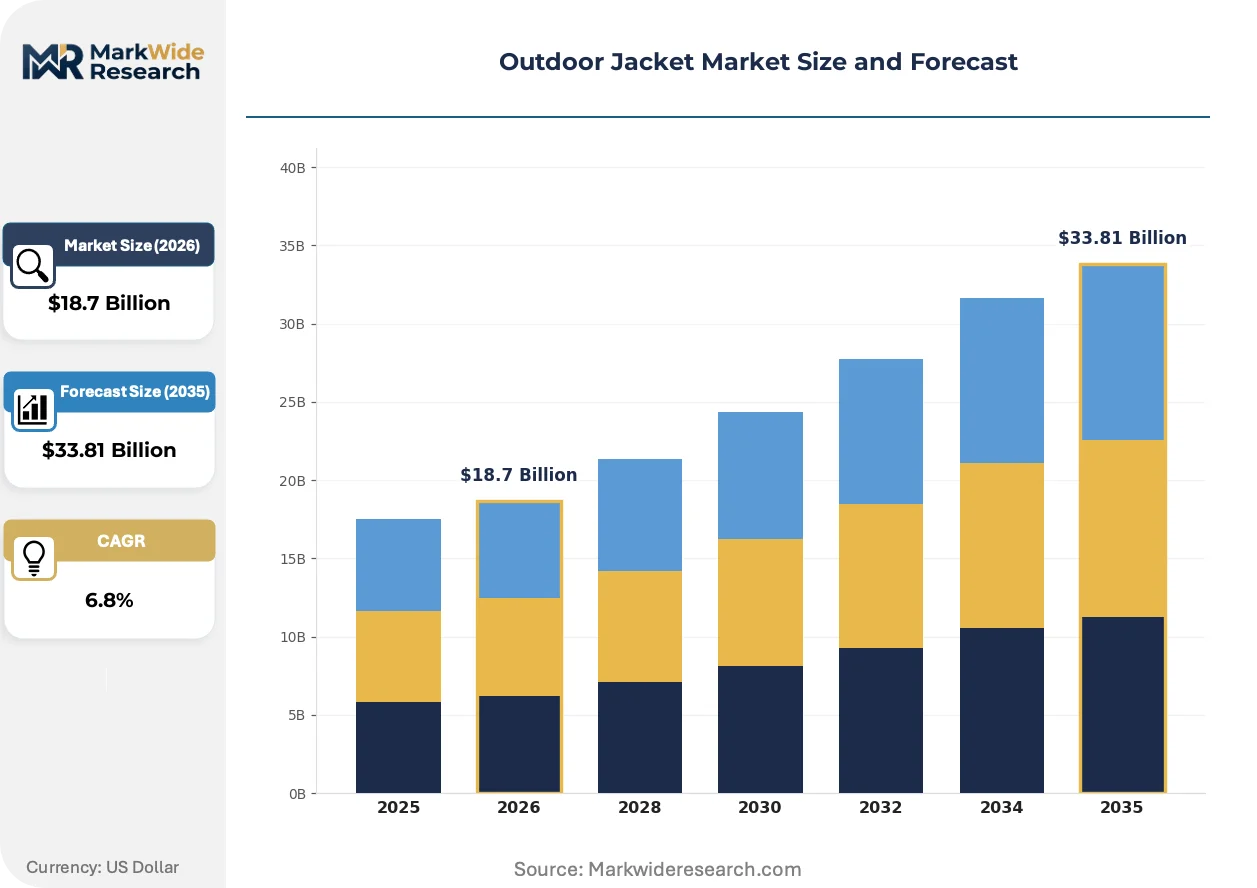
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Jackets, Waterproof Jackets, Softshell Jackets, Windbreakers Material: Synthetic Fabrics, Gore-Tex, Nylon, Cotton Application: Hiking, Camping, Climbing, Casual Wear End User: Men, Women, Youth, Unisex |
| Companies Covered | Arc'teryx, Fjällräven, The North Face, Peak Performance, Canada Goose, Patagonia, Helly Hansen, Craghoppers, Columbia Sportswear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Jacket Market Emerging Trajectories
Material science advances and circular economy mandates are converging to redefine how weather protection garments are engineered, sold, and retired. Three developments are actively reshaping competitive positioning.
Biomimetic membrane technology is decentralizing the performance advantage historically held by centralized fluoropolymer suppliers. Mid-tier manufacturers are adopting plant-derived waterproofing chemistries that achieve comparable hydrostatic resistance without perfluorinated compounds. This diffusion is compressing premium pricing power among incumbent membrane patent holders.
REACH chemical restrictions are eliminating legacy durable water repellent formulations from European supply chains. Manufacturers are reformulating with silicone-based and hydrocarbon alternatives that sacrifice some oil repellency for regulatory compliance. Softshell and hybrid jacket categories are absorbing the most disruption as brands recalibrate performance claims.
Rental and subscription models are fragmenting traditional ownership patterns in alpine tourism corridors. Swiss and Austrian expedition operators are shifting capital expenditure toward fleet procurement with integrated maintenance services. This behavior concentrates volume among contract-capable suppliers while sidelining retail-dependent brands.
Outdoor Jacket Market Segmentation
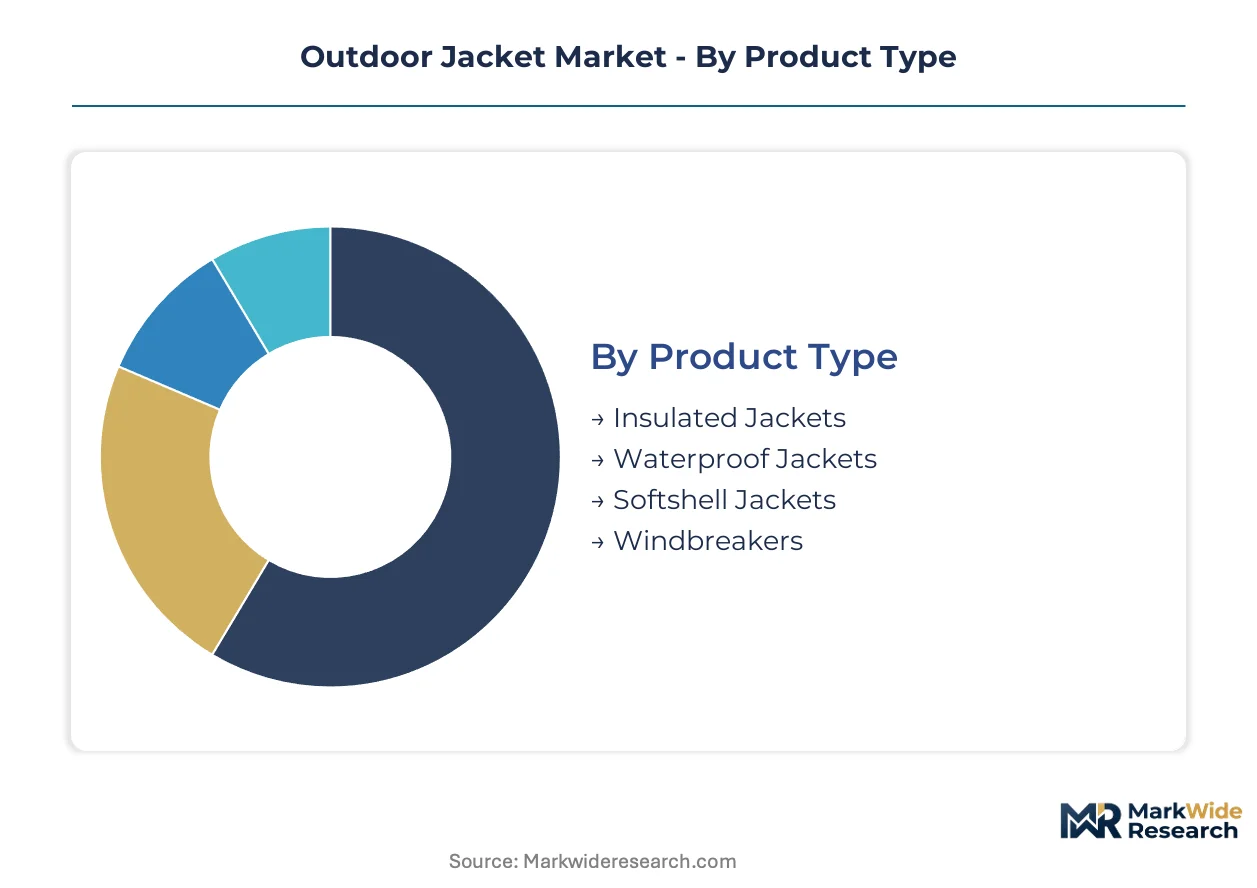
Product architecture in outdoor jackets determines membrane sourcing strategies, lamination partnerships, and retail channel placement. Segmentation reveals how technical specifications map to distinct margin structures and replacement cycle patterns across consumer cohorts.
Product Type:
Supply concentration in membrane lamination equipment shapes which constructions achieve scale economics.
- Waterproof Jackets:Multi-layer fabric assemblies with hydrostatic head ratings above 10,000mm and fully taped seams. Bavarian hiking clubs and Austrian alpine rental fleets drive volume procurement for universal trail protection.
- Insulated Jackets:Synthetic or natural fill combined with weather-resistant face fabrics for cold-climate performance. Premium positioning concentrates in Swiss guided expedition markets where thermal efficiency commands price tolerance.
- Softshell Jackets:Stretch-woven constructions prioritizing breathability over absolute waterproofing. Trail running communities in Germany's Black Forest and speed-oriented trekkers are pulling demand toward this category.
- Windbreakers:Lightweight, packable shells with DWR treatments for wind resistance. Casual urban cyclists and day hikers seeking minimal bulk.
Waterproof jackets absorb the bulk of installed capacity; softshell jackets are expanding most quickly.
Material:
Petrochemical feedstock exposure and REACH compliance costs stratify supplier tiers.
- Synthetic Fabrics:Polyester and polyamide constructions dominate insulation and face fabrics. Recycled polymer adoption is accelerating under EU Green Deal mandates, with German manufacturers leading integration.
- Gore-Tex:Expanded polytetrafluoroethylene membranes with proprietary lamination technology. Patent-protected supply chains concentrate among licensed partners serving premium alpine segments.
- Nylon:High-tenacity yarns for abrasion-resistant face fabrics. Lightweight packable applications favor this material for tear strength.
- Cotton:Limited penetration in performance applications due to moisture retention. Niche positioning in heritage-styled casual wear.
Synthetic fabrics carry the heaviest procurement volume; Gore-Tex commands the steepest expansion trajectory in premium tiers.
Application:
Activity intensity dictates breathability requirements and replacement frequency.
- Hiking:Moderate-output aerobic activity requiring balanced waterproof-breathable performance. Club-organized participation in Baden-Württemberg sustains consistent replacement demand.
- Camping:Static thermal protection with durability emphasis. Family-oriented outdoor recreation in Austrian lake districts.
- Climbing:Abrasion-resistant constructions with harness-compatible pocket placement. Technical alpine routes in Swiss Valais and Tyrolean limestone.
- Casual Wear:Style-forward designs with minimal technical specification. Urban consumers prioritizing aesthetic over performance metrics.
Hiking absorbs the bulk of installed capacity; climbing applications are expanding most quickly.
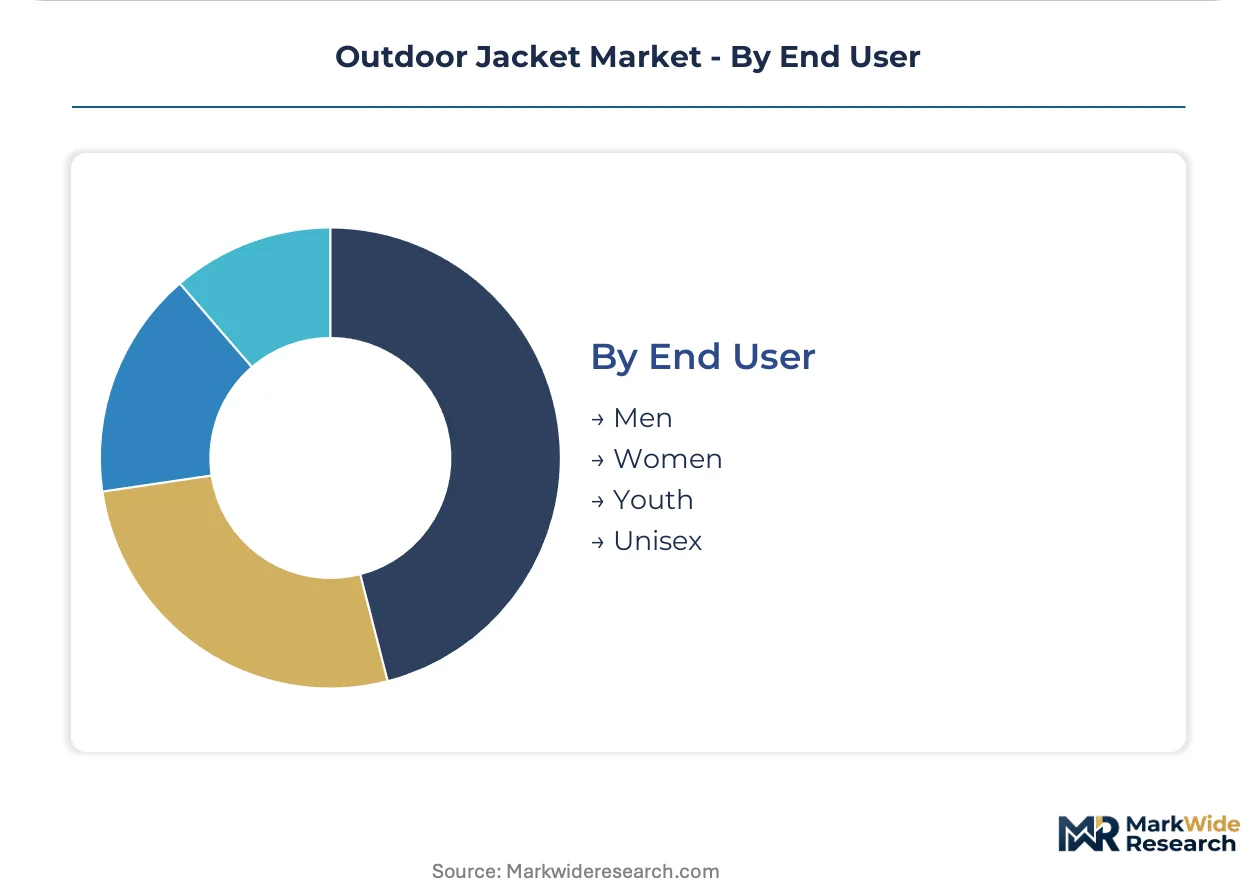
End User:
Fit engineering and sizing granularity determine pattern-making complexity.
- Men:Standardized sizing with broader shoulder construction. Volume concentration in German-speaking alpine markets.
- Women:Contoured patterning with adjusted torso length and hip articulation. Growing technical specification parity with men's offerings.
- Youth:Rapid size turnover requiring adjustable feature integration. School-organized outdoor education programs in Austria.
- Unisex:Simplified sizing matrices reducing inventory complexity. Rental fleet standardization in Swiss tourism corridors.
Men's segments absorb the bulk of installed capacity; women's technical lines are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers dominate membrane lamination capacity while Swiss and Austrian tourism operators drive fleet procurement. Consumption concentrates in Alpine corridors where club-organized hiking and guided expedition volume sustain replacement cycles.
Germany
Bavarian and Baden-Württemberg hiking clubs sustain waterproof jacket demand through organized trail networks. REACH chemical restrictions from ECHA force PFC-free durable water repellent reformulation across domestic supply chains. Membrane lamination clusters in southern manufacturing zones near Stuttgart supply Alpine-facing brands.
Switzerland
Guided expedition operators in Valais and Bernese Oberland scale rental fleet procurement with integrated maintenance contracts. Swissmedic regulates textile chemical safety alongside EU alignment measures. Zürich-based sustainability consultancies advise brands on Ecodesign for Sustainable Products Regulation compliance.
Austria
Tyrolean limestone climbing routes and Eastern Alps ski touring pull technical softshell demand from speed-oriented trekkers. National implementation of EU Green Deal textile requirements accelerates recycled synthetic fabric adoption. Innsbruck anchors alpine equipment testing and certification services for central European brands.
United States
Pacific Northwest trail running communities and Colorado backcountry skiing drive breathable softshell preference over absolute waterproofing. California's Safer Consumer Products program restricts fluorinated chemistry in durable water repellent treatments. Seattle and Denver retail corridors concentrate specialty outdoor merchant density.
China
Domestic outdoor participation growth in Sichuan and Yunnan provinces expands mid-tier waterproof jacket consumption. GB standards from SAMR diverge from EU REACH on chemical safety thresholds, fragmenting compliance testing. Yangtze River Delta membrane lamination suppliers serve both export and domestic brand production.
Outdoor Jacket Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Premium membrane technology concentrates among licensed partners with proprietary lamination access, while mass-market players compete on recycled material integration and repair infrastructure scale. Three archetypes dominate: heritage alpine specialists, sustainability-positioned outdoor lifestyle brands, and diversified apparel conglomerates with outdoor divisions. Consolidation pressure operates through strategic partnerships for biomimetic membrane licensing and geographic expansion into Asian outdoor participation growth corridors.
Within the heritage alpine specialist tier, Arc'teryx and Fjällräven exemplify system-compatible layering architecture and durable construction positioning. Patagonia occupies a distinct archetype as a sustainability-integrated operator with resale channel infrastructure. Columbia Sportswear represents the diversified conglomerate model with accessible price point coverage across mass retail distribution.
| Leading Market Players |
|---|
| Arc'teryx |
| Fjällräven |
| The North Face |
| Peak Performance |
| Canada Goose |
| Patagonia |
| Helly Hansen |
| Craghoppers |
| Columbia Sportswear |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock costs cascade through synthetic fabric production into three-tier pricing structure across premium, standard, and economy levels, with REACH compliance expenses and membrane licensing fees stratifying final price points before reaching Bavarian hiking clubs and Austrian rental fleets.
Pricing Analysis
Margin tightening in mid-tier waterproof jackets reflects silicone-based DWR reformulation costs and recycled polymer premiums under EU Green Deal mandates. Price differentiation hinges on hydrostatic head certification tiers and Gore-Tex membrane licensing status. Cost compression accelerates in mass-market channels as Columbia Sportswear and comparable players compete on accessible price points. German club-organized hikers exhibit highest price sensitivity; Swiss guided expedition operators tolerate premium positioning for thermal efficiency.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta membrane lamination equipment suppliers serving both export and domestic brand production. Manufacturing draws from China, Vietnam, and Bangladesh for cut-and-sew assembly, with German and Italian specialists controlling lamination technology. Raw material dependencies include polyester polymer chips, PTFE membrane substrates, and fluorine-free DWR chemistries. Tariff exposure on Chinese synthetic fabric imports fragments procurement strategies. Distribution runs through specialty outdoor retailers in Stuttgart and Zürich, mass merchant channels in Denver and Seattle, and direct rental fleet contracts in Valais and Tyrol.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Ecodesign for Sustainable Products Regulation erects a compliance moat that favors incumbents with early durability and recyclability certification, while fragmenting testing costs for multi-region challengers.
For Market Incumbents: Deepen repair infrastructure scale to capture extended customer lifetime value and delay replacement cycles threatened by rental model proliferation. Strengthen backward integration into recycled polymer sourcing to secure margin position amid petrochemical volatility. Prioritize PFC-free DWR certification investment to defend preferred procurement status under REACH restrictions.
For New Entrants and Emerging Players: Biomimetic membrane technology offers entry wedge into mid-tier waterproof segments where incumbent patent concentration is weakening. Target Austrian school-organized outdoor education programs and German youth hiking associations as underpenetrated demand pools. Pursue direct-to-rental-fleet go-to-market angle with integrated maintenance service bundling.
For Investors and Strategic Acquirers: Accelerated procurement volume from Swiss and Austrian tourism operators is the leading indicator that rental-subscription infrastructure will consolidate around contract-capable suppliers. Five-to-ten year viability favors vertically integrated manufacturers with captive lamination capacity and circular economy service channels. Monitor biomimetic membrane patent filings as inflection signal for technology disruption timing.
| Strategic Initiative | Industry Significance |
|---|---|
| PFC-Free DWR Reformulation | REACH compliance secures European market access for licensed membrane partners. |
| Repair Infrastructure Scale-Up | Patagonia-style resale channels extend customer relationships beyond initial purchase cycles. |
| Rental Fleet Contracting | Swiss and Austrian tourism operators concentrate volume among maintenance-integrated suppliers. |
| Recycled Polymer Integration | EU Green Deal mandates accelerate sustainable material adoption across German manufacturing bases. |
| Biomimetic Membrane Licensing | Plant-derived waterproofing chemistries decentralize incumbent fluoropolymer patent advantages. |
Methodological Framework
Multi-period observation of alpine tourism procurement patterns, club-organized hiking participation rates, and membrane technology patent filings anchored the trend analysis, supplemented by interviews with membrane lamination equipment suppliers, outdoor brand sustainability directors, Austrian rental fleet operators, and German retail category buyers. Secondary validation drew from ECHA REACH substance restrictions, EU Ecodesign regulatory texts, customs trade data for synthetic fabric imports, and SEC filings from publicly traded outdoor apparel conglomerates. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Input-output matrices mapped hydrostatic head ratings, breathability indices, and replacement cycle frequencies across product type, material composition, application intensity, and end-user demographics over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by regional consumption clusters. Forecast inputs incorporated petrochemical price elasticity coefficients and regulatory compliance cost curves specific to fluorinated chemistry phase-outs.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Chinese synthetic fabric tariffs, breakthrough membrane technologies achieving sub-micron pore structures, and pandemic-scale disruptions to alpine tourism demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Global Apparel and Footwear Market
Apparel & Footwear
Global Shirt Market
Apparel & Footwear
Men's Coats and Jackets Market