
 Bra Cups Market | 2026-2036
Bra Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Bra Cups Market Analysis
Custom sizing and virtual fitting subscription services is restructuring how bra cup manufacturers monetize fit accuracy and reduce return rates. Triumph International leverages its European heritage and technical pattern libraries to sustain premium positioning across mature markets. Hanesbrands Inc. anchors mass-market volume through dominant shelf placement in North American big-box retail channels. Youngor Group Co., Ltd. dominates integrated textile-to-garment production in Ningbo, controlling cost structures that Western competitors struggle to match.
Bra cups are engineered support structures—typically molded from polyurethane foam, spacer fabric, or laminated fiber blends—that shape, lift, or stabilize breast tissue within brassiere garments. Manufacturing employs heat-press molding, ultrasonic welding, or 3D knitting to achieve dimensional stability and wash-cycle durability, with functional parameters including compression resistance, moisture-wicking coefficient, and skin-contact biocompatibility. The sports segment leads absolute volume due to performance-grade moisture management requirements, while push-up configurations command higher per-unit margins through specialized foam densities and graduated padding architectures. Cotton and nylon material categories split the market between breathability-focused everyday wear and elasticity-driven active applications.
The European Chemicals Agency (ECHA) enforces REACH substance restrictions on azo dyes and formaldehyde-releasing agents used in foam padding and textile finishes, compelling reformulation of core materials. The U.S. Consumer Product Safety Commission and state-level California Proposition 65 requirements govern flammability and chemical disclosure for intimate apparel sold domestically. China's GB standards and Market Regulation Administration (SAMR) oversight mandate fiber content labeling and product safety testing for domestic circulation and export certification. Stakeholders must monitor divergence between EU chemical hazard classifications and U.S. state-level disclosure thresholds, as compliance fragmentation threatens to segment supply chains by destination market rather than by brand.
Market Dynamics
REACH substance restrictions and California Proposition 65 disclosure mandates are forcing foam suppliers to reformulate polyurethane padding chemistries, while Guangdong's vertically integrated textile clusters concentrate molding capacity and compress lead times for both domestic Chinese brands and export orders.
Growth Catalysts
- REACH azo dye restrictions:ECHA-mandated elimination of carcinogenic colorants in textile finishes accelerates migration toward OEKO-TEX certified foam suppliers across European supply chains.
- Spacer fabric adoption:3D-knit polyester mesh structures replace molded foam in high-heat athletic applications, driven by moisture-vapor transmission requirements in performance intimates.
- Guangdong cluster concentration:Ningbo-to-Guangdong production corridors achieve 72-hour sample-to-ship cycles for North American private-label programs.
Market Restraints
- TDI/MDI price volatility:Polyurethane foam feedstock costs fluctuate with crude-linked petrochemical indices, squeezing converter margins on fixed-price annual contracts.
- Single-region mold tooling:Heat-press die manufacturing concentrates in Dongguan specialty machine shops, creating 6-8 week capacity bottlenecks during Q3 seasonal ramps.
- Biopolymer performance gaps:Castor-oil-derived foam alternatives fail compression-set durability standards required for 50-wash lifecycle certification.
Strategic Opportunities
- India PLI scheme for technical textiles:Production-linked incentives for man-made fiber processing attract bra cup molding investments to Tamil Nadu and Gujarat corridors.
- Virtual fitting API integration:Computer-vision sizing tools embedded in direct-to-consumer checkout flows reduce bracketed-purchase return rates from 35% to sub-12%.
- EU Green Deal circularity mandates:Ecodesign for Sustainable Products Regulation creates certified-recycled-content premiums for polyester foam from chemical depolymerization streams.
Industry Challenges
- Pattern engineering talent scarcity:3D bra cup last development requires specialized technical apparel training unavailable outside Milan, Hong Kong, and Foshan vocational pipelines.
- Multi-jurisdiction certification stacking:Simultaneous OEKO-TEX Standard 100, bluesign, and ZDHC MRSL compliance extends new material qualification timelines to 14-18 months.
- Legacy ERP integration friction:Size-grade complexity in bra cup SKUs overwhelms SAP AFS implementations originally architected for basic apparel categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bra Cups Market |
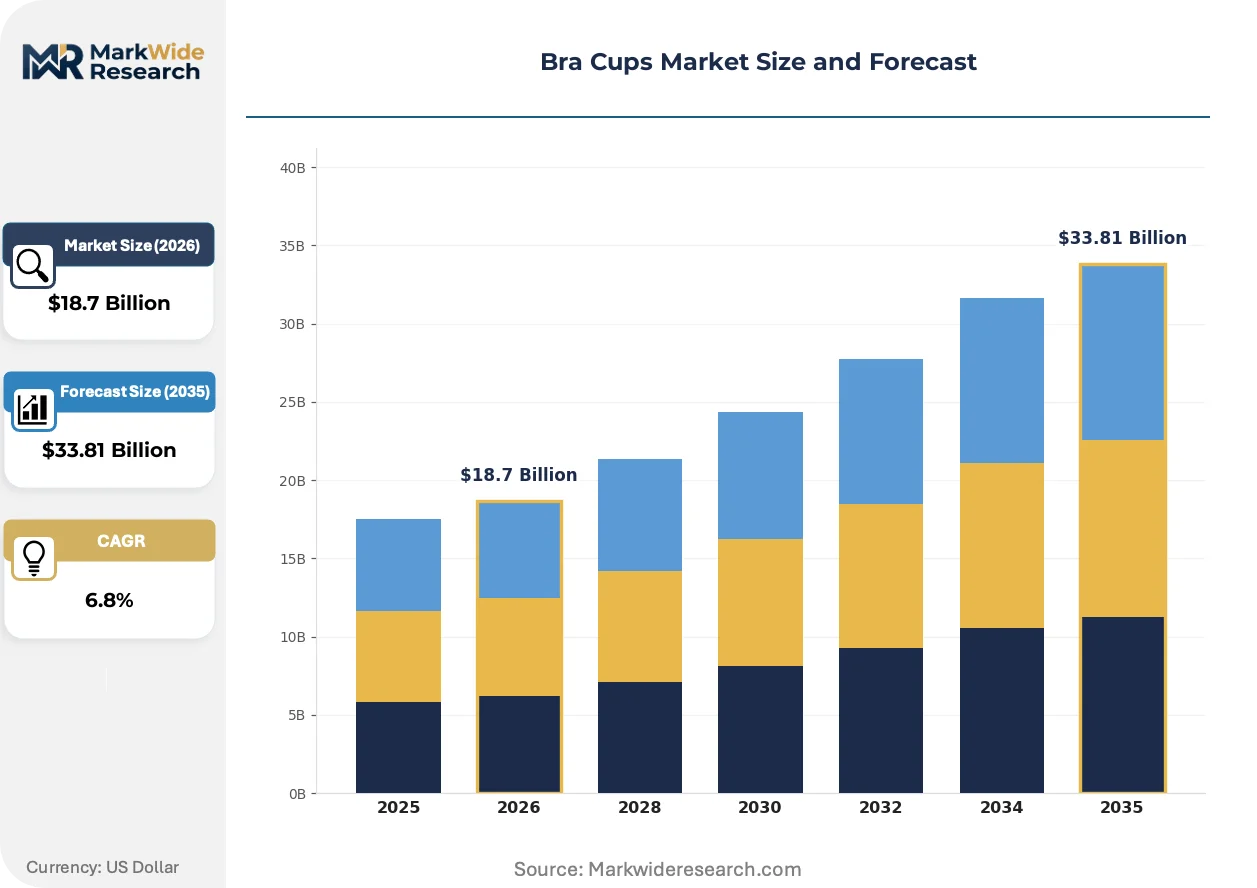
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Padded, Non-Padded, Push-Up, Sports Material: Cotton, Lace, Polyester, Nylon End User: Women, Teens, Plus-Size, Maternity Distribution Channel: Online, Retail Stores, Specialty Shops, Department Stores |
| Companies Covered | Youngor Group Co., Ltd., Magnolia Group, M.S. International, Triumph International, Nissen Holdings Co., Ltd., Hanesbrands Inc., Vanity Fair Brands, Livi Activewear Inc., Clovia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bra Cups Market Emerging Trajectories
Digital measurement protocols and bio-based material platforms are compressing traditional fit-iteration cycles while regulatory chemical disclosure requirements propagate through tier-two foam suppliers.
Spacer fabric technology is integrating graduated-density 3D-knit structures that eliminate laminated foam layers entirely. Performance intimates brands in Germany and South Korea adopt these architectures for marathon-distance support garments. The technology is integrating moisture-management and structural support into single-construction components, collapsing supplier tiers from three to one.
ECHA's 2023 restriction proposal on microplastic release from synthetic textiles targets polyurethane foam fragmentation during garment washing. The industrial consequence mandates bonded-fiber alternative development or closed-loop filtration system installation at wet-processing facilities. Sports and swimwear categories face earliest compliance deadlines, with Dutch and Danish brands already specifying pre-certified foam sources.
Direct-to-consumer subscription fitting services displace traditional wholesale buying patterns for core replenishment styles. Specialty retailers in France and Japan now license virtual try-on modules rather than carrying deep size-range inventory. This channel compression concentrates demand forecasting risk with brand-side data science teams and eliminates distributor markup recovery for mid-tier molded cup programs.
Bra Cups Market Segmentation
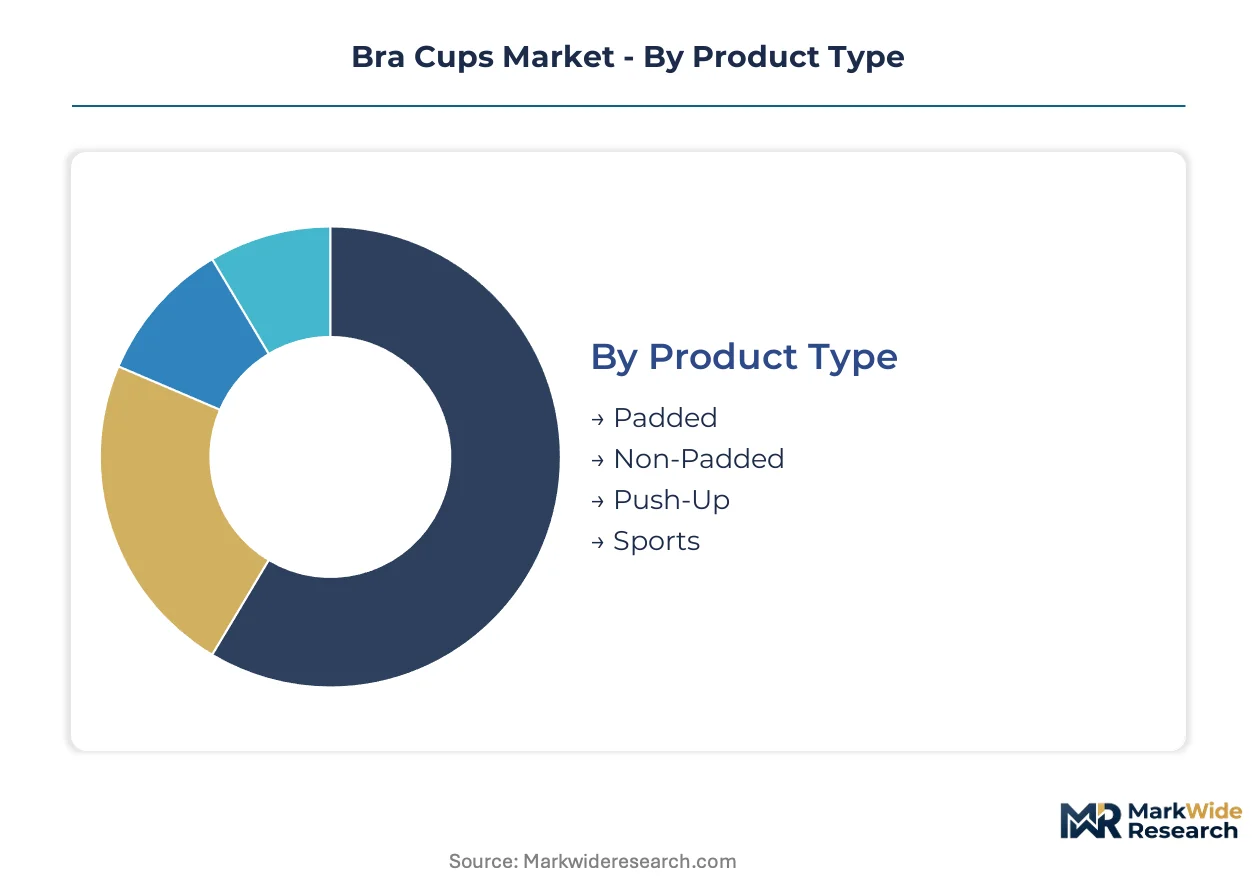
Bra cup segmentation reveals divergent margin architectures across product tiers. Material chemistry and distribution channel economics create distinct competitive battlegrounds that separate premium positioning from volume capture.
Product Type:
Performance requirements and aesthetic intent split purchasing decisions across functional use cases.
- Padded:Molded polyurethane or fiberfill constructions provide modesty coverage and uniform silhouette under fitted garments. Everyday wear applications in Germany and France sustain steady replenishment cycles through private-label department store programs.
- Push-Up:Graduated foam densities and angled underwire integration create lift mechanics through engineered mass redistribution. Specialty retailers in Japan and South Korea command premium positioning through proprietary last libraries and seasonal fashion cycles.
- Non-Padded:Single-layer fabric constructions prioritize breathability and natural drape for comfort-focused segments. Cotton-rich variants dominate South Asian domestic markets where climate and price sensitivity align.
- Sports:Compression-molded spacer fabrics and moisture-wicking laminates address high-impact movement stabilization. Marathon and triathlon participation rates in Australia and California drive technical specification escalation.
Padded configurations lead volumes today; sports applications are gaining share fastest.
Material:
Cost structures and regulatory compliance burdens vary dramatically by fiber chemistry and finishing requirements.
- Polyester:Spun-dye and solution-dye variants offer colorfastness and dimensional stability for molded cup applications. Guangdong-based vertical mills achieve lowest unit costs through captive filament production and integrated heat-press molding.
- Nylon:Polyamide 6,6 delivers superior elasticity recovery for stretch-lace overlays and power-mesh wings. REACH-certified European supply chains command 15-20% premiums over Asian-sourced alternatives due to restricted substance compliance.
- Cotton:Natural fiber positioning targets skin-sensitivity and sustainability preferences in North American and Western European markets. Organic certification requirements extend qualification timelines for tier-two spinning mills.
- Lace:Raschel-knit or embroidered constructions serve decorative and ventilation functions in premium lingerie assortments. Swiss and French technical textile houses maintain pattern design leadership through generational craft preservation.
Polyester dominates unit economics; nylon commands highest per-kilogram pricing.
End User:
Body morphology and life-stage requirements dictate fit engineering complexity and size-grade proliferation.
- Women:Core demographic spanning standard size matrices with established measurement protocols. Mature markets exhibit polarization between mass-market replenishment and boutique customization.
- Plus-Size:Extended band and cup combinations require reinforced underband construction and wider strap anchoring. Underpenetration in professional fitting services creates e-commerce opportunity for algorithmic sizing tools.
- Teens:Entry-price positioning with simplified construction and fashion-forward aesthetics drives seasonal turnover. School uniform compliance requirements in UK and Australian markets sustain predictable demand windows.
- Maternity:Nursing access mechanisms and fluctuating breast volume accommodation necessitate adjustable frameworks. Hospital gift shop and baby registry channels concentrate initial purchase occasions.
Women's standard sizing anchors volume; plus-size specifications are expanding most quickly.
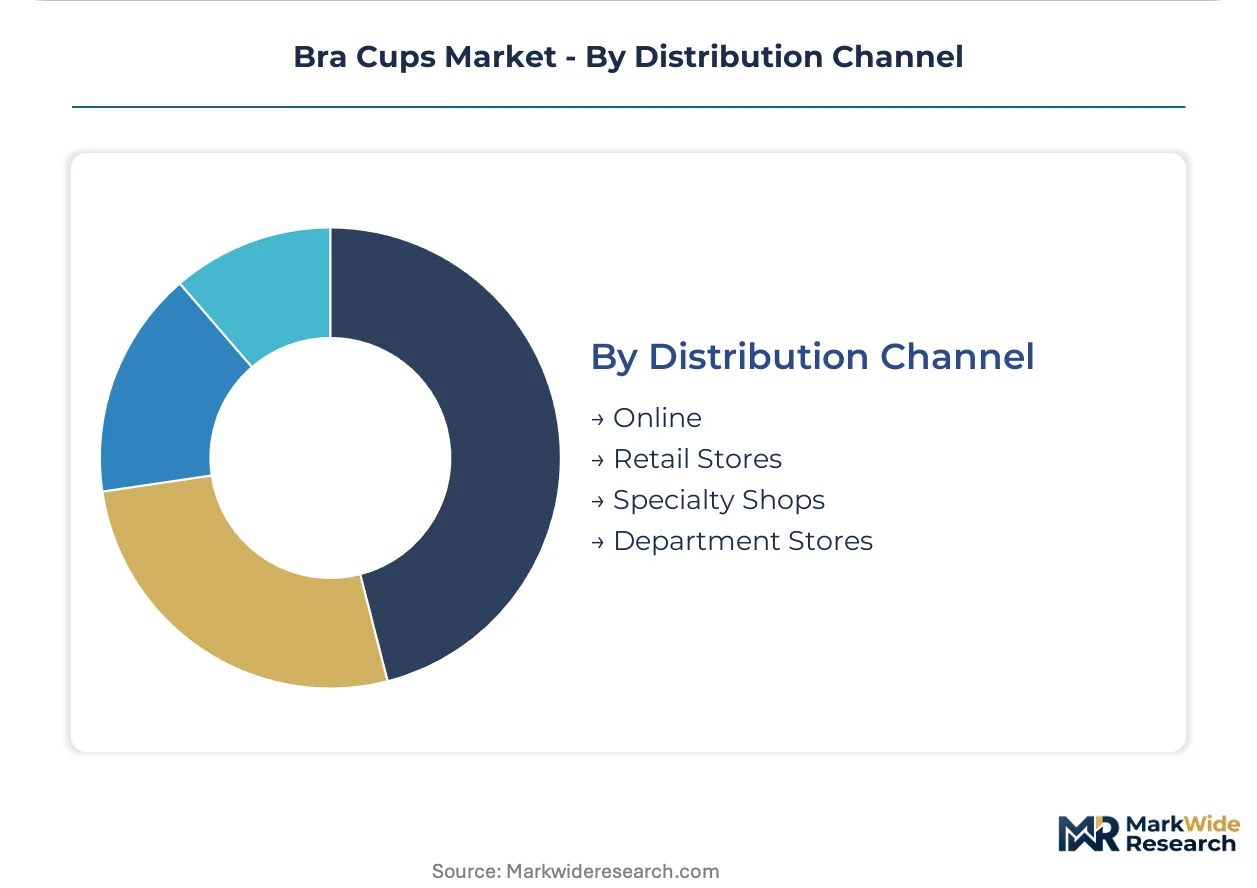
Distribution Channel:
Inventory risk allocation and customer acquisition economics separate channel strategies.
- Online:Direct-to-consumer platforms absorb return logistics costs in exchange for data capture and margin retention. Virtual fitting APIs reduce bracketed-purchase behavior in subscription-model implementations.
- Retail Stores:Big-box and hypermarket placement secures impulse replenishment through dominant shelf positioning. Hanesbrands leverages this channel for mass-market volume capture in North America.
- Specialty Shops:Professional fitting services justify premium pricing through expertise differentiation. Triumph International sustains European heritage positioning through controlled boutique networks.
- Department Stores:Curated brand assortments and seasonal promotional calendars serve discovery-oriented shoppers. Private-label penetration is accelerating as retailers capture margin from national brand displacement.
Retail stores maintain volume leadership; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between REACH-mandated European reformulation costs and Asia's vertically integrated production clusters is redirecting molding capacity toward Guangdong and Tamil Nadu corridors. Manufacturers migrate to jurisdictions where chemical compliance overhead compresses against scale economies.
China
Guangdong province concentrates polyurethane foam molding for export programs serving North American private-label buyers. SAMR fiber-content labeling mandates and GB standards testing create domestic certification friction that vertically integrated mills absorb through captive laboratory capacity. Ningbo-to-Guangdong production corridors achieve 72-hour sample-to-ship cycles.
United States
California Proposition 65 disclosure thresholds and CPSC flammability standards drive reformulation costs for polyurethane suppliers serving the domestic market. Big-box retail channel concentration in the Southeast and Midwest sustains mass-market volume through dominant shelf placement economics. Dallas and Atlanta distribution hubs consolidate inbound container flows from Asian molding facilities.
Germany
ECHA REACH azo dye restrictions and emerging microplastic release proposals reshape material qualification timelines for foam suppliers serving European lingerie brands. Bavaria and North Rhine-Westphalia host technical pattern engineering talent pools developed through generational vocational pipelines. Berlin-based direct-to-consumer brands license virtual fitting modules to reduce bracketed-purchase returns.
India
PLI scheme incentives for technical textiles attract bra cup molding investments to Tamil Nadu and Gujarat production corridors. BIS fiber-content standards and DGFT export certification requirements create compliance layering for integrated garment exporters. Mumbai and Bangalore direct-to-consumer platforms deploy computer-vision sizing tools to compress fit-iteration cycles.
Japan
METI circular economy guidelines and emerging EPR frameworks for synthetic textiles drive recycled-content specification adoption among domestic intimates brands. Osaka and Nagoya industrial clusters maintain precision molding equipment for high-compression athletic applications. Tokyo-based specialty retailers consolidate professional fitting service networks to justify premium positioning.
Bra Cups Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage positioning commanding premium tiers and scale-driven OEMs capturing private-label volume. Market structure exhibits moderate concentration at the top, followed by fragmented mid-tier converters and regional fabricators. Three archetypes dominate: European heritage brands with technical pattern libraries, Asian vertically integrated textile-to-garment producers, and North American mass-market shelf-space anchors. Competitive moves concentrate on API integration for virtual fitting and backward integration into foam compounding to secure margin.
Among Asian vertically integrated producers, Youngor Group Co., Ltd. and Nissen Holdings Co., Ltd. occupy positions exemplifying captive textile-to-garment cost structures that Western competitors struggle to replicate. Triumph International and Hanesbrands Inc. represent divergent archetypes—heritage European positioning versus North American mass-market scale—each defending distinct channel economics. These four entities anchor competitive dynamics across premium and volume tiers without exhaustive market coverage.
| Leading Market Players |
|---|
| Youngor Group Co., Ltd. |
| Magnolia Group |
| M.S. International |
| Triumph International |
| Nissen Holdings Co., Ltd. |
| Hanesbrands Inc. |
| Vanity Fair Brands |
| Livi Activewear Inc. |
| Clovia |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Guangdong and Ningbo anchor foam molding capacity, translating captive textile production into pricing discipline that resists Western contract manufacturers' margin compression tactics. Their ownership structure eliminates quarterly earnings pressure, enabling multi-year capacity planning that stabilizes input cost pass-through mechanics for North American private-label buyers.
Pricing Analysis
Capacity additions in Tamil Nadu are reshaping price floors for standard-grade molded cups, compressing contract manufacturer quotes against Guangdong's established scale advantages. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified European supply from uncertified Asian spot production, with REACH compliance costs widening the gap. Pricing pressure stems from TDI/MDI feedstock volatility squeezing converter margins on fixed-price annual agreements. Mass-market big-box buyers exhibit highest price sensitivity; specialty lingerie boutiques absorb premium tiers with minimal volume negotiation.
Supply Chain Analysis
Freight cost differentials between Ningbo-to-Los Angeles and Chennai-to-Rotterdam corridors influence sourcing decisions for European versus North American program allocations. Supply concentrates in China, India, and Vietnam, with polyurethane foam feedstock, spacer fabric 3D-knit equipment, and heat-press mold tooling as critical input dependencies. Single-region mold tooling concentration in Dongguan machine shops creates structural vulnerability during Q3 seasonal ramps. Distribution runs through vertically integrated brand-owned channels, third-party logistics consolidators in Dallas and Rotterdam, and direct-to-consumer parcel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through virtual fitting API adoption, which cuts return logistics costs from 35% to sub-12% and shifts pricing power toward data-rich brand operators. Premium-tier displacement of wholesale-dependent mid-market players accelerates as specialty retailers license sizing modules rather than carrying deep inventory.
For Market Incumbents: Hedge against spacer fabric substitution by securing exclusive 3D-knit equipment partnerships with German and South Korean technical textile houses. Incumbents should consolidate pattern engineering talent through acquisition of Milan and Hong Kong vocational pipeline graduates, countering the scarcity that extends new material qualification timelines to 14-18 months. Backward integration into polyurethane foam compounding secures margin capture currently lost to petrochemical feedstock volatility. For New Entrants and Emerging Players: Enter via plus-size algorithmic sizing tools, where underpenetration in professional fitting services creates white-space opportunity for direct-to-consumer platforms. India's PLI scheme corridors in Tamil Nadu and Gujarat offer the most penetrable geography for technical textile investments with government-backed cost offsets. A subscription-model go-to-market angle compresses customer acquisition costs against incumbent wholesale dependency. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier molded cup converters lacking virtual fitting API integration or OEKO-TEX certification assets. Long-term viability favors targets with captive Guangdong production corridors and established North American private-label relationships. The signal to watch is ECHA microplastic restriction implementation timelines, which will force premature asset obsolescence for non-compliant foam suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Fitting API Integration | Computer-vision sizing tools embedded in checkout flows reduce bracketed-purchase return rates for direct-to-consumer brands. |
| Backward Integration into Foam Compounding | In-house polyurethane production insulates margins from TDI/MDI petrochemical feedstock price volatility. |
| PLI Scheme Capacity Expansion | Technical textile investments in Tamil Nadu corridors attract government incentives for export-oriented molding facilities. |
| OEKO-TEX Certification Investment | Standard 100 compliance opens European supply chains blocked by REACH azo dye restrictions on carcinogenic colorants. |
| Spacer Fabric Technology Licensing | 3D-knit polyester mesh patents from German and South Korean houses displace laminated foam layers in performance intimates. |
Methodological Framework
Direct dialogue with bra cup molders, technical pattern engineers, specialty lingerie buyers, and polyurethane foam compounders grounded qualitative assessment in operational reality. Secondary validation drew from ECHA restriction proposals, U.S. CPSC flammability standards, China SAMR fiber-content labeling mandates, and customs trade flow records. Bottom-up SKU-level modeling triangulated against top-down category spend estimates to isolate genuine volume drivers from inventory cycle noise.
Segmentation outputs across material chemistry, product configuration, end-user morphology, and distribution channel economics anchored the analytical framework across the projection horizon. CAGRs emerged from fitted trend extrapolation moderated by regulatory inflection points and technology substitution curves. Key inputs included spacer fabric adoption rates in athletic applications, virtual fitting API penetration in direct-to-consumer channels, and PLI scheme disbursement trajectories for Indian technical textile investments.
Inputs from ECHA regulatory filings, Guangdong provincial industrial statistics, and North American big-box procurement databases were available through the study window; gaps in real-time polyurethane feedstock contract pricing introduce uncertainty bands around converter margin forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Boot Market
Apparel & Footwear
Intimate Lingerie Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Sequins Apparels Market