
 Asia-Pacific Jeans Market | 2026-2036
Asia-Pacific Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Jeans Market Outlook
Asset-light licensing and franchise-based expansion is reconfiguring competitive entry costs across the Asia-Pacific jeans landscape. Levi Strauss & Co leverages its direct-to-consumer infrastructure to control pricing in premium urban corridors. Hennes & Mauritz AB anchors its position through rapid-turn supply chains that compress design-to-rack cycles. VF Corporation competes via specialized outdoor and workwear denim extensions that command higher unit economics.
Asia-Pacific jeans denote cotton-dominant trousers typically containing 98-100% cotton or cotton-elastane blends, constructed through indigo rope-dyeing and sanforization processes to achieve dimensional stability and colorfastness for casual and semi-formal wear. Skinny and straight-leg cuts dominate volume in East Asian markets where slim silhouettes align with prevailing fashion norms, while wide-leg styles are gaining traction among younger demographics in South Korea and Australia. Online retail channels are capturing the fastest growth trajectory as platform ecosystems integrate live-streaming commerce with same-day fulfillment networks.
China's MEE enforces wastewater discharge limits that compel dye houses to adopt closed-loop filtration or relocate to compliant industrial parks. India's BIS certification mandates fiber content labeling that shapes import compliance costs for foreign brands. Australia's ACCC consumer protection standards govern durability claims and return policies. Stakeholders must monitor how divergent national sustainability mandates reshape sourcing geography and factory certification requirements across the region.
Market Dynamics
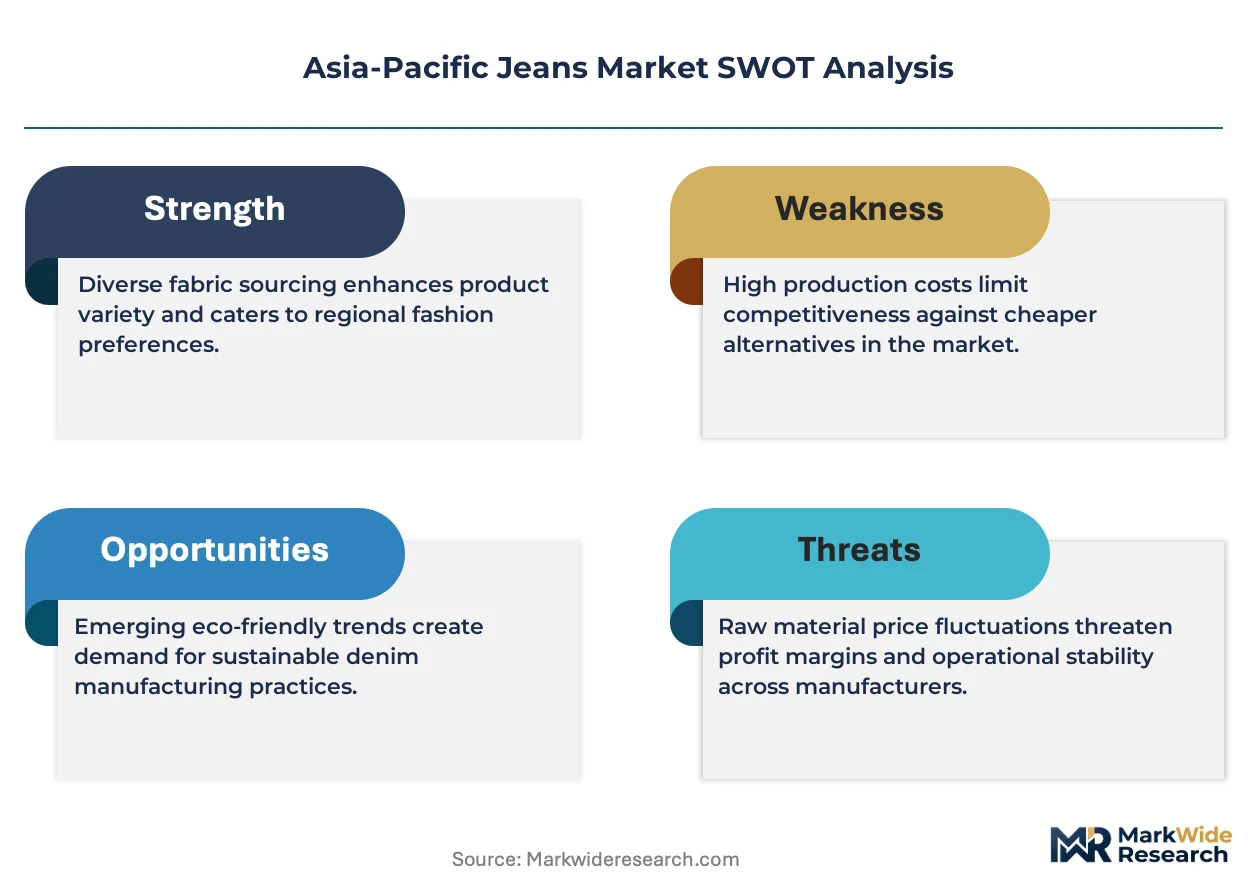
China's MEE wastewater discharge mandates are forcing denim dye houses toward closed-loop filtration systems or relocation to compliant industrial parks, compressing supplier margins and redrawing the Asia-Pacific sourcing map.
Growth Catalysts
- Live-streaming commerce integration:Platform ecosystems in Southeast Asia weave real-time video selling with same-day fulfillment networks, accelerating conversion rates among young adult urban consumers.
- BIS fiber labeling mandates:India's certification requirements create compliance barriers that favor organized domestic manufacturers over informal imports.
- Waterless dyeing adoption:Laser and ozone finishing technologies reduce water consumption by 90% compared to traditional rope-dyeing, attracting ESG-focused procurement from Australian retailers.
Market Restraints
- Cotton price volatility:Raw fiber input costs swing with climate-driven harvest uncertainty in Punjab and Maharashtra, squeezing margin structures for mid-tier producers.
- Supplier concentration in Guangdong:Three coastal provinces account for 70% of regional denim finishing capacity, creating geographic vulnerability to typhoon disruption and power rationing.
- Technical limitation in stretch recovery:Cotton-elastane blends above 2% elastane content suffer accelerated bagging in tropical humidity, constraining product performance claims in Southeast Asian climates.
Strategic Opportunities
- Tier-two Indian cities:Organized retail penetration in Jaipur, Lucknow, and Indore deepens as mall operators target aspirational middle-class denim buyers outside metro corridors.
- Workwear denim extensions:Industrial safety regulations in Australian mining and construction sectors create demand for flame-resistant and high-visibility denim variants.
- MEE carbon intensity audits:China's dual carbon goals incentivize dye houses achieving near-zero discharge certification to capture premium pricing from EU-bound export orders.
Industry Challenges
- Skilled pattern-making shortage:Traditional denim cutting expertise concentrates in aging workforces in Osaka and Hong Kong, with insufficient vocational pipeline replacement.
- Sanforization equipment capex:Dimensional stability machinery requires 18-24 month payback periods that strain balance sheets of small-batch Japanese selvedge producers.
- Cross-border e-commerce compliance:Australia's ACCC durability claim standards and India's BIS labeling create fragmented documentation requirements for direct-to-consumer shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Jeans Market |
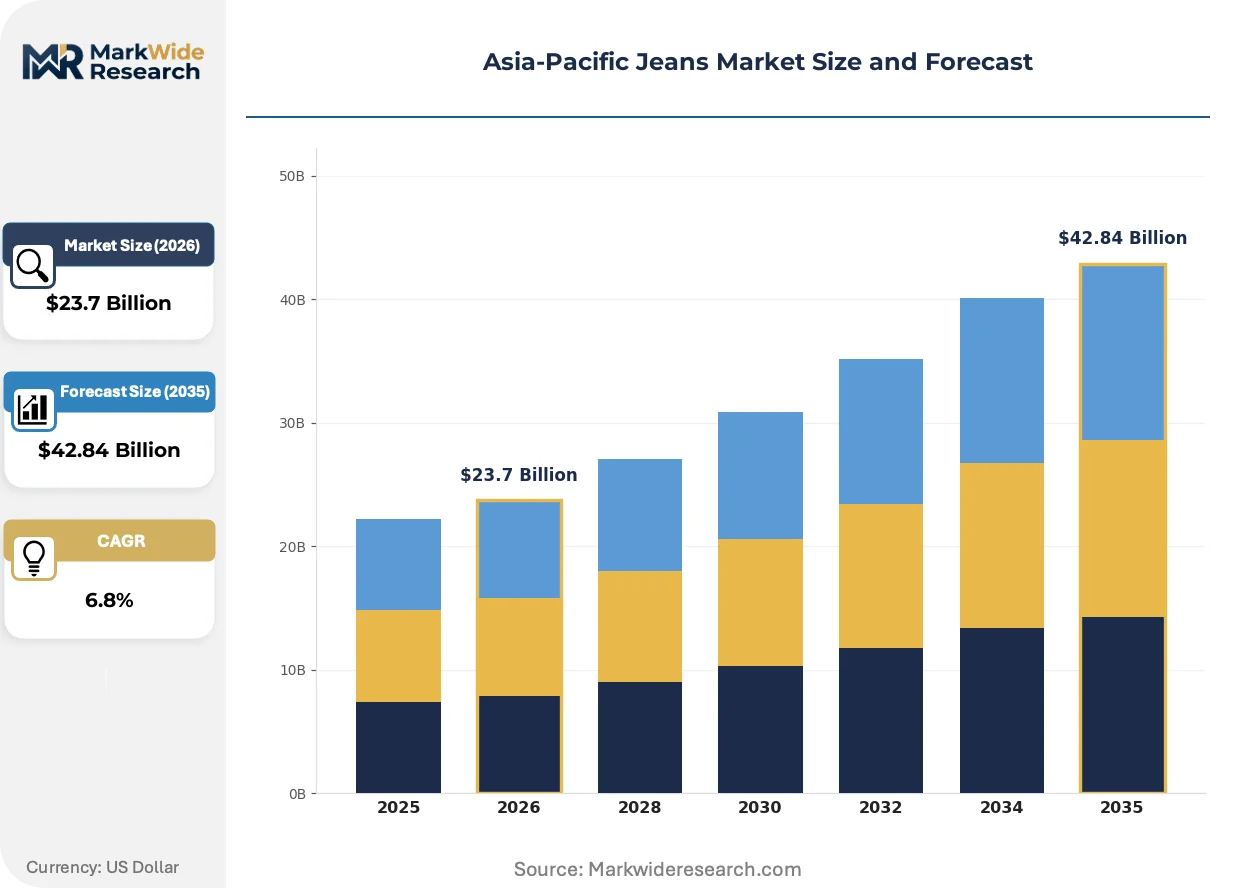
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinny, Bootcut, Straight-Leg, Wide-Leg Customer Type: Men, Women, Children, Unisex Distribution Channel: Online Retail, Department Stores, Specialty Stores, Outlets Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Gap Inc., Hennes & Mauritz AB, Levi Strauss & Co, Pepe Jeans, Kering SA, VF Corporation, Uniqlo, Diesel S.p.A., PVH Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Jeans Market Strategic Shifts
Digital sampling and virtual showroom technologies are compressing design-to-production timelines while regulatory pressure on wet processing accelerates capital redeployment toward dry-finishing alternatives.
Laser-based surface finishing is virtualizing the traditional manual scraping and whiskering operations that dominated denim aging workflows. Premium Japanese and South Korean manufacturers deploy 3D body scanning linked to automated laser units, cutting sample development from three weeks to 48 hours. This virtualization collapses the minimum order quantities that previously gated small-brand access to quality suppliers.
China's MEE enforcement of GB 4287 textile wastewater standards is shuttering non-compliant dye houses in Zhejiang and Jiangsu provinces. Surviving facilities absorb 15-20% cost premiums for closed-loop filtration, passing these through to export pricing. Australian and New Zealand import buyers now require third-party MEE compliance documentation as a condition of purchase order acceptance.
Platform-native buying behavior is fragmenting traditional seasonal collection cycles. Southeast Asian consumers purchase denim through TikTok Shop and Shopee Live flash events triggered by influencer styling rather than retail calendar releases. South Korean brands respond with micro-drops of 200-500 units manufactured domestically in Seoul's Seongsu-dong cluster, compressing design-to-doorstep to under ten days.
Asia-Pacific Jeans Market Segmentation
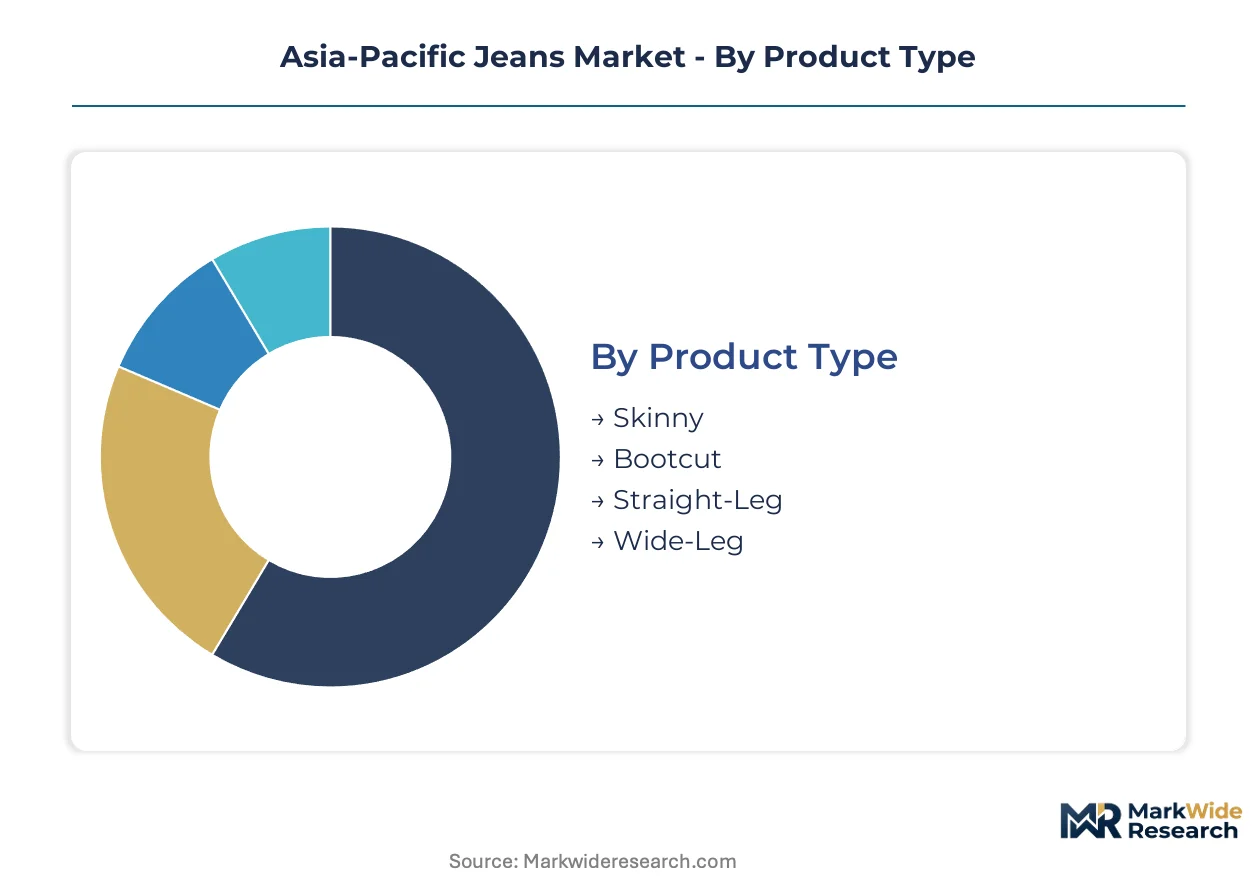
Segmentation in the Asia-Pacific jeans market reveals divergent velocity profiles across product, customer, and channel dimensions. Cycle-time compression in e-commerce channels contrasts with slower inventory turns in premium specialty retail, shaping working capital requirements and markdown risk exposure for manufacturers and distributors.
Product Type:
Skinny and straight-leg silhouettes turn inventory fastest through Southeast Asian e-commerce flash sales, while wide-leg styles command longer production lead times and higher price premiums in South Korean and Australian boutiques.
- Skinny:Cotton-elastane blends with 1-2% elastane content dominate volume in East Asian markets where slim silhouettes align with prevailing fashion norms. Demand concentrates in Tokyo, Seoul, and Shanghai urban corridors where young adult consumers prioritize fitted aesthetics for professional-casual hybrid wardrobes.
- Straight-Leg:Classic 98-100% cotton constructions with sanforization for dimensional stability serve as the workhorse category across Indian tier-two cities and Australian regional markets. Jaipur, Lucknow, and Indore shopping malls report strongest straight-leg uptake among aspirational middle-class buyers seeking versatile day-to-evening transitions.
- Bootcut:Flared-leg profiles with elongated inseams retain niche positioning in Australian and New Zealand markets influenced by American workwear heritage styling.
- Wide-Leg:Relaxed silhouettes with high-rise waists gain traction among Gen Z demographics in Seoul's Seongsu-dong cluster and Sydney's inner suburbs, though volumes remain constrained by higher fabric consumption per unit.
Skinny and straight-leg cuts dominate installed base. Wide-leg is where expansion concentrates.
Customer Type:
Women's denim commands the highest average selling prices and most frequent purchase frequency, while children's segments exhibit pronounced seasonality tied to school calendar cycles across the region.
- Women:Design-to-rack cycles compress to under ten days for South Korean micro-drop specialists serving platform-native buying behavior through TikTok Shop and Shopee Live events. High-rise and vintage-wash variants drive premium pricing power in premium urban corridors.
- Men:Standardized fits and conservative color palettes reduce return rates in Indian online retail, where BIS fiber labeling compliance creates documentation barriers for cross-border direct-to-consumer shipments. Workwear denim extensions for Australian mining and construction sectors anchor industrial safety demand.
- Children:Size turnover velocity peaks during March-April and August-September school preparation windows across Southeast Asian markets, with elasticated waistbands and reinforced knee panels as standard technical specifications.
- Unisex:Gender-neutral sizing and minimalist branding attract younger demographics in Melbourne, Bangkok, and Taipei, though manufacturing complexity from extended size runs limits supplier participation.
Women's segments capture the steepest expansion trajectory. Men's categories provide the most stable replenishment base.
Distribution Channel:
Channel economics diverge sharply between asset-light platform ecosystems and fixed-cost brick-and-mortar infrastructure, with implications for margin capture and brand control.
- Online Retail:Live-streaming commerce integration with same-day fulfillment networks accelerates conversion rates among young adult urban consumers in Indonesia, Vietnam, and Philippines. Laser-based virtual sampling reduces return rates by improving fit accuracy.
- Department Stores:Multi-brand fixtures in Indian mall operators' tier-two expansions provide brand discovery venues for organized domestic manufacturers facing BIS compliance costs.
- Specialty Stores:Curated denim boutiques in Osaka, Hong Kong, and Melbourne concentrate skilled pattern-making expertise and selvedge production knowledge.
- Outlets:Off-price channels absorb excess inventory from seasonal collection cycles, with Australian and New Zealand locations capturing trans-Tasman tourist traffic.
Online retail is gaining share fastest. Department stores retain the broadest geographic footprint.
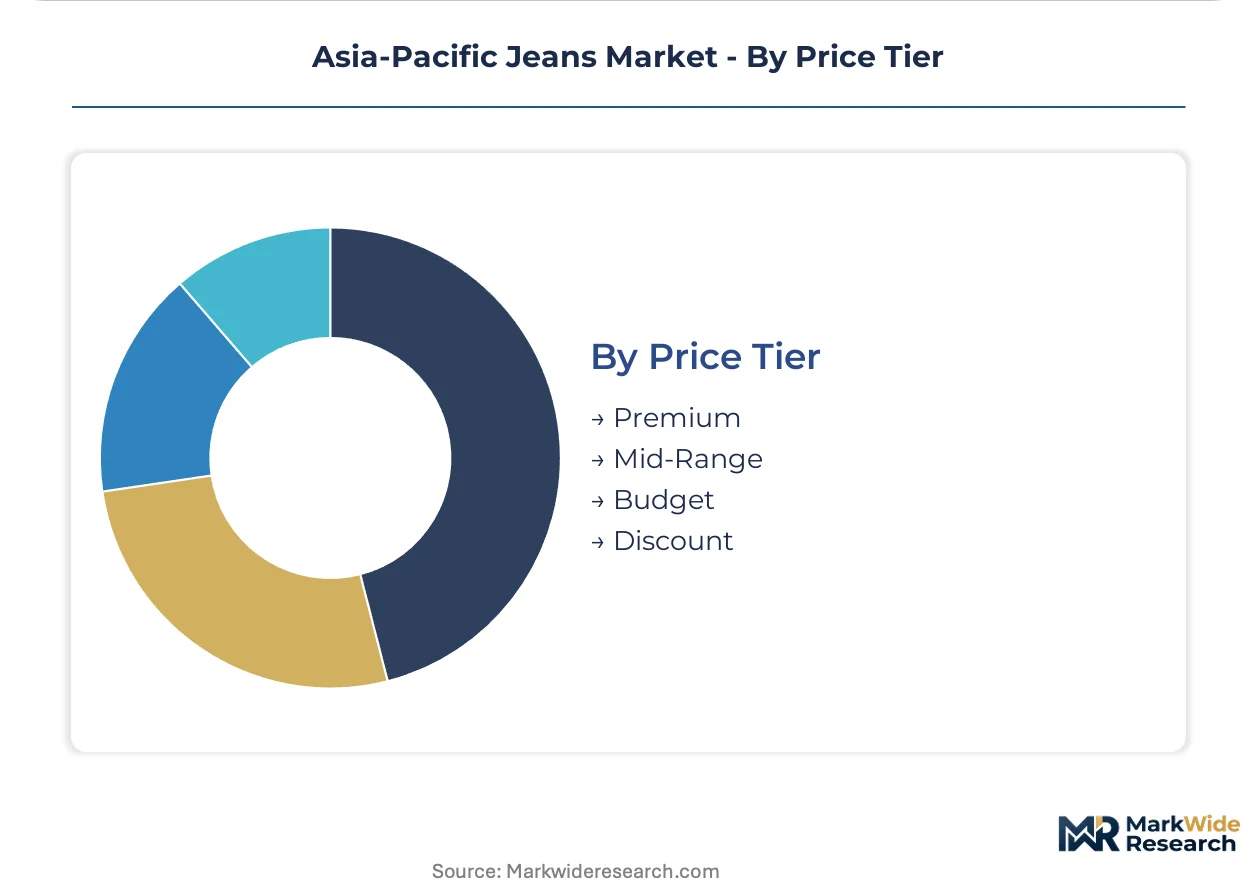
Price Tier:
Premium positioning requires MEE-compliant dye house certification and closed-loop filtration documentation, while budget tiers compete on Guangdong supplier concentration and scale economies.
- Premium:Japanese selvedge and South Korean laser-finished products command 15-20% cost premiums passed through from MEE-compliant facilities. Near-zero discharge certification unlocks EU-bound export order access.
- Mid-Range:Organized Indian manufacturers leverage BIS fiber labeling mandates to displace informal imports in tier-two city mall expansions.
- Budget:Cotton price volatility in Punjab and Maharashtra squeezes margin structures for producers dependent on undifferentiated rope-dyed constructions.
- Discount:Flash event pricing through Southeast Asian platform ecosystems fragments traditional seasonal collection cycles and compresses full-price selling windows.
Mid-range holds the largest volume position. Premium is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium Japanese selvedge commands 40-60% price premiums over Guangdong mass-market output, creating a two-tier sourcing architecture across the region. This asymmetry shapes procurement strategies for Australian retailers and Southeast Asian platform sellers. Demand fragmentation accelerates as tier-two Indian cities and Seoul's Seongsu-dong cluster pursue divergent denim aesthetics.
China
Guangdong, Zhejiang, and Jiangsu provinces host 70% of regional denim finishing capacity, concentrating supplier exposure to typhoon disruption and power rationing. The MEE enforces GB 4287 wastewater discharge limits that shutter non-compliant dye houses, forcing survivors to absorb 15-20% cost premiums for closed-loop filtration. Surviving facilities in Shaoxing and Changzhou industrial parks now require third-party compliance documentation for Australian and New Zealand purchase orders.
India
Jaipur, Lucknow, and Indore shopping malls report strongest straight-leg denim uptake among aspirational middle-class buyers seeking versatile day-to-evening transitions. The BIS mandates fiber content labeling that creates compliance barriers favoring organized domestic manufacturers over informal imports. Ahmedabad and Surat textile clusters deepen sanforization and rope-dyeing capacity to serve tier-two city expansions.
Japan
Kojima district in Okayama Prefecture retains concentrated selvedge production knowledge and skilled pattern-making expertise in an aging workforce. METI industrial heritage programs sustain artisanal denim tourism that subsidizes small-batch premium output. Osaka-based manufacturers deploy 3D body scanning linked to automated laser units, collapsing sample development timelines from three weeks to 48 hours.
South Korea
Seoul's Seongsu-dong cluster produces micro-drops of 200-500 units with sub-ten-day design-to-doorstep cycles for TikTok Shop and Shopee Live flash events. MFDS textile safety standards govern chemical finishing residues for domestic consumption and re-export. Wide-leg and high-rise vintage-wash variants drive premium pricing power among Gen Z demographics in Gangnam and Hongdae retail corridors.
Australia
Sydney and Melbourne boutiques curate premium Japanese and South Korean imports requiring MEE-compliant dye house certification and near-zero discharge documentation. The ACCC enforces durability claims and return policies that fragment cross-border e-commerce documentation requirements. Industrial safety regulations in Queensland mining and Western Australian construction sectors create demand for flame-resistant and high-visibility denim workwear extensions.
Asia-Pacific Jeans Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in dyeing, finishing, and fabric innovation. The Asia-Pacific jeans market structures around three archetypes: heritage denim houses with century-old brand equity, fast-fashion retailers with rapid-turn supply chains, and conglomerate-held luxury labels leveraging vertical control over Italian and Japanese mills. Dominant competitive moves include M&A to capture distressed Guangdong finishing capacity and strategic partnerships with MEE-compliant dye houses for EU-bound export certification.
Within the heritage tier, Levi Strauss & Co and VF Corporation occupy positions defined by direct-to-consumer infrastructure and workwear denim extensions. Hennes & Mauritz AB exemplifies the rapid-turn archetype through supply chain compression. These three anchors represent divergent margin capture strategies across premium urban corridors, mid-range volume plays, and specialized industrial safety applications.
| Leading Market Players |
|---|
| Gap Inc. |
| Hennes & Mauritz AB |
| Levi Strauss & Co |
| Pepe Jeans |
| Kering SA |
| VF Corporation |
| Uniqlo |
| Diesel S.p.A. |
| PVH Corp |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo port freight corridors transmit cost volatility from Guangdong dye house consolidation directly into Australian retailer procurement spreads, compressing margin buffers for mid-tier brands while amplifying premium capture for MEE-certified suppliers.
Pricing Analysis
The customization-premium spread between laser-finished selvedge and standard rope-dyed constructions spans 40-60% in Australian and Japanese import markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by MEE compliance certification and closed-loop filtration documentation. Cost compression in budget tiers is intensifying because cotton price volatility in Punjab and Maharashtra squeezes undifferentiated producers. Platform-native buyers in Southeast Asia exhibit highest price sensitivity, while Sydney and Melbourne boutique purchasers show lowest elasticity for heritage Japanese provenance.
Supply Chain Analysis
Extended payment terms from Australian retailers now stretch to 90-120 days, forcing Guangdong and Zhejiang dye houses to absorb supply-chain finance facility costs. Raw material sourcing draws from Xinjiang cotton, Indian BCI-certified fiber, and Australian merino wool blends for premium lines. Single-source vulnerability concentrates in Shaoxing industrial park filtration-dependent facilities. Distribution runs through platform-integrated fulfillment networks in Jakarta, Manila, and Ho Chi Minh City alongside traditional department store wholesale in Indian tier-two mall expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific jeans market sits at a platform-economics inflection where TikTok Shop and Shopee Live interoperability with same-day fulfillment networks rewires brand-consumer relationships beyond traditional retail gatekeeping.
For Market Incumbents: Pre-empt platform-native challengers by captive supply of MEE-certified dye house capacity in Changzhou and Shaoxing industrial parks. Secure exclusive laser-finishing equipment allocations from Osaka and Seoul technology vendors before capacity constraints harden. Reinforce direct-to-consumer infrastructure with live-streaming commerce integration to retain pricing control in premium urban corridors.
For New Entrants and Emerging Players: Jaipur, Lucknow, and Indore mall expansions present white-space access with BIS-compliant domestic manufacturing partnerships displacing informal imports. Target workwear denim extensions for Australian mining and construction safety regulations as the most penetrable premium segment. Deploy micro-drop production in Seoul's Seongsu-dong cluster with sub-ten-day design-to-doorstep cycles as the go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from distressed Guangdong finishing capacity facing MEE wastewater enforcement shutdowns. Long-term viability hinges on backward integration into compliant industrial park real estate and filtration technology ownership. Watch for third-party MEE compliance documentation becoming mandatory for Australian and New Zealand purchase order acceptance as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MEE Compliance Certification Investment | Unlocks premium pricing from EU-bound export orders and Australian retailer procurement. |
| Laser-Finishing Technology Deployment | Collapses sample development timelines from weeks to 48 hours for Seoul and Osaka manufacturers. |
| Platform-Native Commerce Integration | Captures conversion acceleration from TikTok Shop and Shopee Live flash event ecosystems. |
| Tier-Two Indian Mall Expansion | Deepens organized retail penetration among aspirational middle-class denim buyers outside metros. |
| Workwear Denim Extension Development | Addresses industrial safety regulations in Queensland mining and Western Australian construction sectors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade records, BIS certification databases, and MEE compliance documentation registries. Primary interviews engaged denim brand managers, dye house operations directors, Australian retail category buyers, and Indian mall operator leasing heads. Secondary validation drew from platform ecosystem disclosures, textile machinery vendor specifications, and industrial park regulatory filings. Bottom-up supplier capacity assessments triangulate against top-down retail channel revenue attribution.
Forecast inputs incorporate product type velocity differentials, channel economics divergence, and regional regulatory enforcement trajectories across the analysis window. Segmentation modeling spans silhouette category, customer demographic, distribution channel, and price tier dimensions. CAGRs derive from time-series projection of installed base turnover and replacement cycle compression. Industry-specific inputs include MEE enforcement phase-in schedules and BIS labeling mandate adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-native micro-drop specialists or accelerated MEE enforcement would shift outcomes. Macroeconomic cotton price shocks, typhoon disruption to Guangdong capacity clusters, or regulatory deviation in wastewater standards would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Global Adaptive Clothing Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Hats Market