
 Decorated Apparel Market | 2026-2036
Decorated Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Decorated Apparel Market Intelligence
Water-based ink chemistry is shifting decorated apparel economics by reducing curing energy and enabling finer halftone detail on cotton-polyester blends. Gildan leverages vertical integration from yarn to finished garment to control base goods supply for its print-on-demand channels. Hanesbrands Inc. anchors its position through mass retail distribution and licensed sports partnerships. Fruit of the Loom, Inc. competes on volume scale in the promotional products segment.
Decorated apparel encompasses garments enhanced with applied graphics through mechanical or chemical bonding processes, typically involving pigment deposition at 40-120 mesh counts for screen printing or 12,000-15,000 stitches per design for automated embroidery, serving identification, promotion, and team unity functions. Screen printing dominates volume in the decoration method category due to its cost efficiency at scale, while direct-to-garment captures the fastest expansion as digital workflows reduce setup waste for short runs. T-shirts occupy the largest product type position, though hoodies generate higher unit margins in fall-winter seasonal cycles.
EPA regulations on volatile organic compound emissions from textile printing operations constrain solvent-based process adoption in US manufacturing facilities. REACH compliance in Europe mandates phased reduction of certain phthalate plasticizers common in legacy heat transfer films. OEKO-TEX Standard 100 certification increasingly functions as a market access requirement for decorated apparel entering German and French retail channels. Stakeholders must monitor how digital printing equipment amortization cycles interact with tightening chemical disclosure rules across multiple jurisdictions.
Market Dynamics
Water-based ink chemistry is compressing energy costs and curing times while EPA volatile organic compound enforcement accelerates the phase-out of plastisol systems across contract decorating shops.
Growth Catalysts
- Team Sports Participation:Youth leagues and amateur athletic associations in the United States are expanding custom uniform programs for identification and unity functions.
- REACH Phthalate Restrictions:European heat transfer film reformulation is redirecting procurement toward compliant water-based alternatives certified under OEKO-TEX Standard 100.
- Direct-to-Garment Digital Workflows:Short-run production without screen setup waste is capturing promotional products demand from corporate buyers and event organizers.
Market Restraints
- Cotton-Polyester Blend Inconsistency:Variable fiber composition disrupts ink adhesion and colorfastness across garment batches, raising rework rates.
- Specialized Equipment Concentration:Automated embroidery machine production clusters in East Asian manufacturing hubs, creating lead time vulnerability for North American decorators.
- Energy Cost Volatility:Curing oven and flash unit electricity consumption exposes contract shops to utility price swings in deregulated state markets.
Strategic Opportunities
- Corporate Promotional Spending:United States enterprise marketing budgets sustain volume leadership for logoed T-shirts and outerwear in employee engagement programs.
- Fall-Winter Hoodie Margins:Higher unit economics on fleece and thermal garments offset seasonal volume compression in screen printing operations.
- Digital-Embroidery Convergence:Hybrid decoration systems combining direct-to-garment base printing with automated stitch finishing open premium positioning in team sports.
Industry Challenges
- Mesh Count Calibration Expertise:Screen printers face shortages of technicians capable of optimizing 40-120 mesh configurations for halftone detail on blended substrates.
- Multi-Jurisdiction Chemical Disclosure:Simultaneous compliance with EPA emissions rules, REACH substance restrictions, and OEKO-TEX certification timelines strains quality assurance resources.
- Legacy Heat Transfer Integration:Shops with invested plastisol infrastructure confront stranded asset risk during water-based system transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorated Apparel Market |
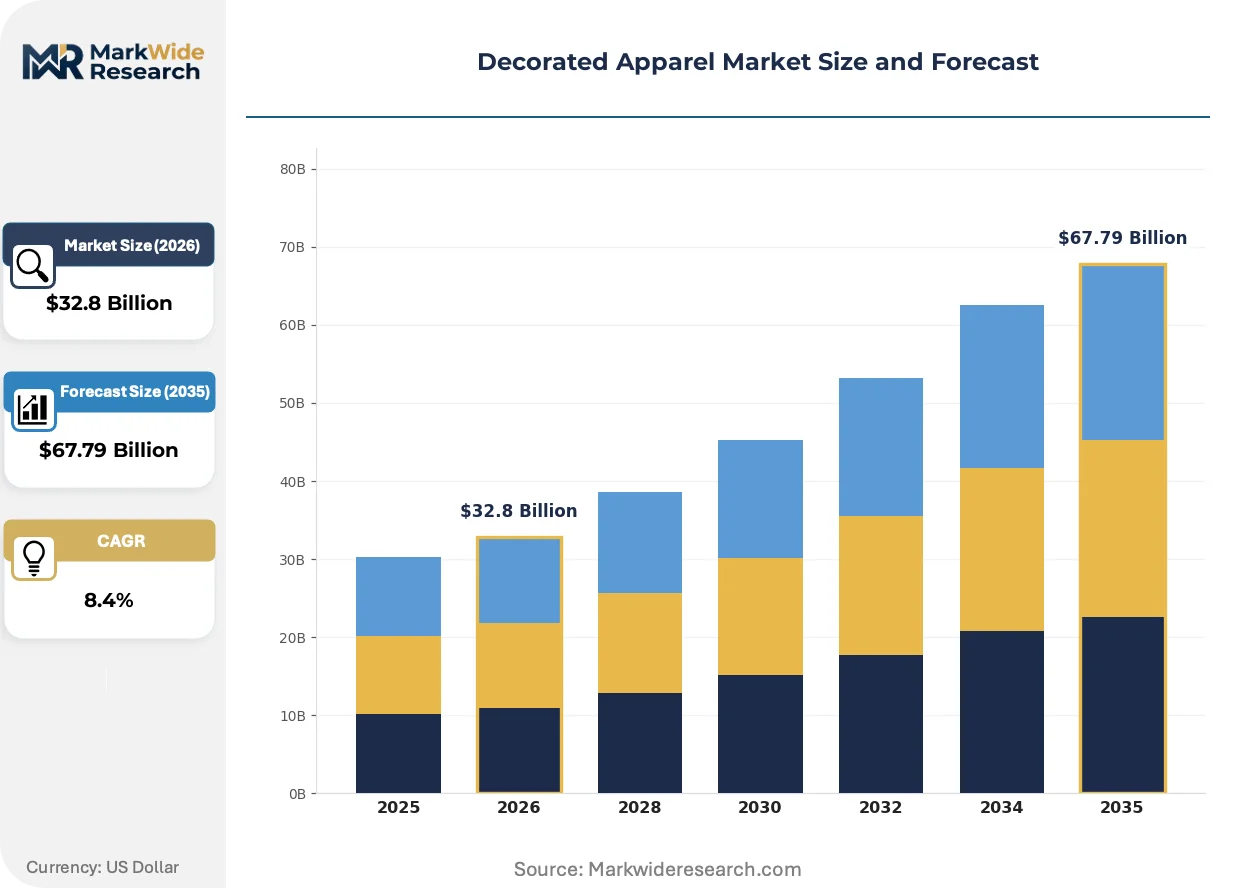
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Hoodies, Caps, Bags Decoration Method: Screen Printing, Embroidery, Heat Transfer, Direct-to-Garment End User: Retailers, Businesses, Events, Sports Teams Distribution Channel: Online, Brick-and-Mortar, Wholesale, Custom Orders |
| Companies Covered | Gildan, Fruit of the Loom, Inc., Hanesbrands Inc., Delta Apparel, Inc., Downtown Custom Printwear, Master Printwear, Target Decorated Apparel, Advance Printwear Limited, Lynka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorated Apparel Market Strategic Shifts & Innovations
Active chemistry reformulation and digital workflow adoption are restructuring production economics while regulatory disclosure mandates reshape material sourcing protocols.
Water-based pigment dispersions are electrifying contract decorating operations by slashing curing energy requirements and enabling 85-line halftone reproduction on cotton-polyester blends. North American and European contract shops are retrofitting conveyor dryers to accommodate lower-temperature curing profiles. The technology is electrifying competitive positioning among mid-volume decorators competing for athletic league and corporate accounts.
EPA volatile organic compound emission limits for textile printing operations are constraining solvent-based process adoption in United States manufacturing facilities. Facilities in California, Texas, and North Carolina face inspection frequency increases and penalty escalation for non-compliant curing operations. Screen printing shops are responding by accelerating water-based ink conversion and submitting Title V permit modifications.
Team sports buyers are consolidating decoration procurement through league-level master service agreements rather than individual club vendor selection. This concentration is displacing fragmented local shop relationships with regional contract decorators capable of uniform program management. The pattern is most visible in United States youth baseball, soccer, and volleyball league administration.
Decorated Apparel Market Segmentation
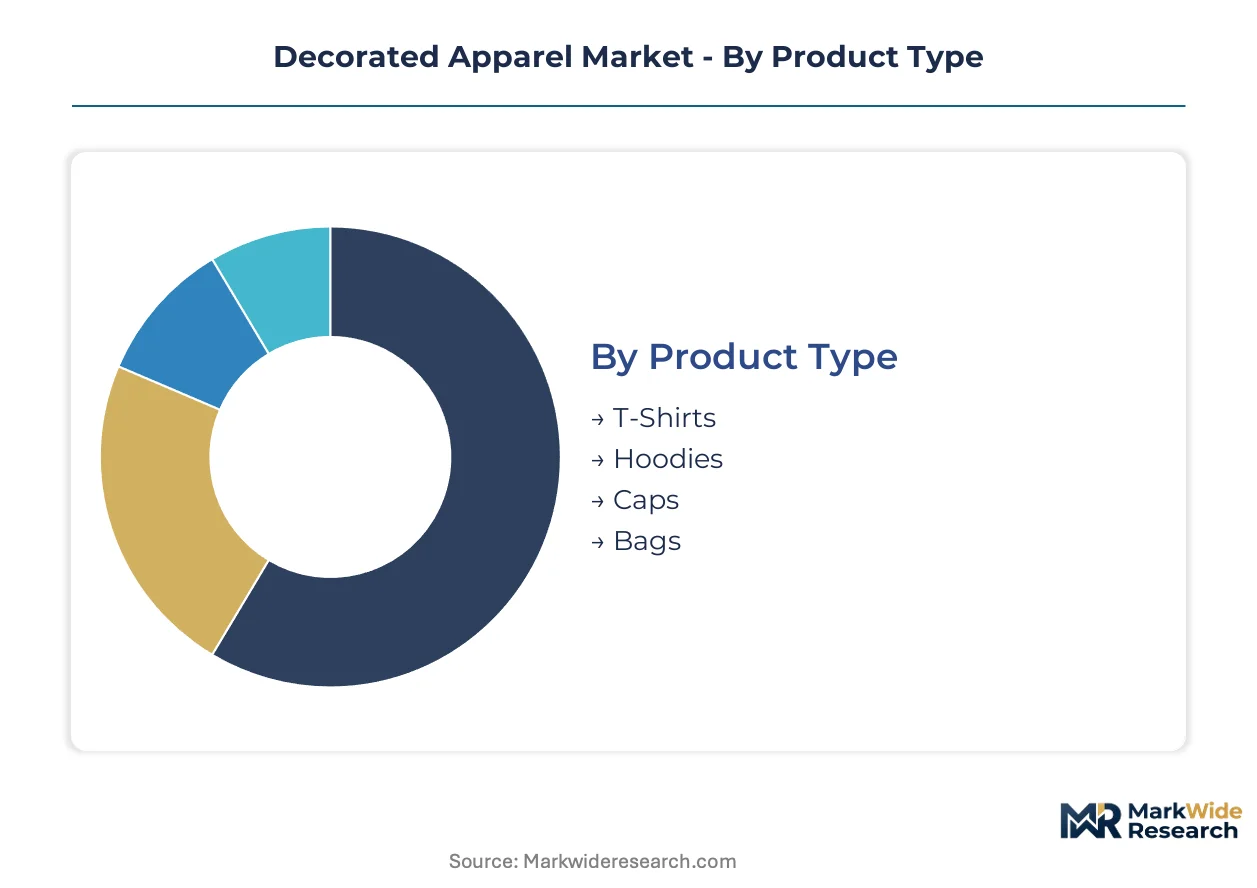
Segmentation in decorated apparel reveals how upgrade cycles and replacement demand concentrate across product categories, decoration technologies, and procurement channels. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Replacement cycles vary dramatically across garment categories, with daily-wear items refreshing faster than seasonal outerwear and accessories.
- T-Shirts:Cotton and cotton-polyester blends dominate unit volume through corporate promotional programs and team uniform baselayers. United States youth sports leagues and enterprise employee engagement programs sustain replenishment demand for logoed tees at 40-120 mesh screen specifications.
- Hoodies:Fleece and thermal constructions command premium unit economics during fall-winter procurement cycles, with higher stitch counts and specialized curing requirements for water-based ink adhesion on blended substrates.
- Caps:Six-panel and structured headwear serve event merchandising and team identity functions through curved-brim embroidery at 12,000-15,000 stitch densities.
- Bags:Tote and duffel configurations carry promotional messaging through heat transfer and screen applications, with OEKO-TEX Standard 100 certification increasingly required for European retail channel entry.
T-Shirts sit at the top of the volume ranking, with Hoodies climbing the fastest.
Decoration Method:
Cost tier differentiation separates high-volume mechanical processes from precision digital workflows, with capital intensity and setup waste determining competitive viability across run lengths.
- Screen Printing:Squeegee-driven pigment deposition through calibrated mesh screens dominates contract decorating economics at scale, with water-based formulations displacing plastisol under EPA volatile organic compound enforcement in United States facilities.
- Embroidery:Automated needle systems executing programmed stitch patterns deliver durability and premium tactile quality for team sports and corporate outerwear, though machine production concentration in East Asian hubs creates lead time exposure for North American decorators.
- Heat Transfer:Film-based graphic application enables complex multi-color designs without screen setup, with REACH phthalate restrictions in Europe forcing reformulation toward compliant water-based adhesive systems.
- Direct-to-Garment:Inkjet deposition eliminates screen preparation waste and captures short-run promotional demand from corporate buyers and event organizers seeking rapid turnaround without minimum order constraints.
Screen Printing holds the volume leadership position, while Direct-to-Garment gains share fastest among decoration technologies.
End User:
Customer type segmentation maps procurement sophistication, with institutional buyers consolidating vendor relationships while fragmented retail channels sustain local decorator ecosystems.
- Retailers:Branded apparel merchandisers and specialty stores demand consistent color matching and rapid replenishment, with OEKO-TEX certification functioning as a market access requirement for German and French channel entry.
- Businesses:Corporate promotional spending on employee engagement and trade show programs sustains volume leadership in the United States, with logoed T-shirts and outerwear anchoring enterprise marketing budgets.
- Events:Single-occasion merchandising for concerts, festivals, and conferences favors digital workflows that accommodate variable design specifications without screen inventory carrying costs.
- Sports Teams:League-level master service agreements are consolidating procurement away from fragmented local shop relationships, with youth baseball, soccer, and volleyball administration driving uniform program standardization.
Businesses anchor the volume ranking among end users, with Sports Teams expanding most quickly through league consolidation.
Distribution Channel:
Channel structure determines margin capture and customer data ownership, with digital platforms disintermediating traditional wholesale relationships while custom order workflows retain service premiums.
- Online:Direct-to-consumer and B2B platforms enable design visualization tools and automated pre-press workflows, capturing promotional products demand from geographically dispersed corporate buyers.
- Brick-and-Mortar:Physical retail locations sustain impulse merchandising and local team uniform fitting services, with energy cost volatility in deregulated United States state markets pressuring storefront profitability.
- Wholesale:Volume distributors aggregate demand across multiple decorators, with Gildan and Hanesbrands leveraging mass retail distribution and licensed sports partnerships to anchor shelf presence.
- Custom Orders:Relationship-based procurement through dedicated account management serves institutional buyers requiring color consistency across seasonal replenishment cycles and specialized finishing services.
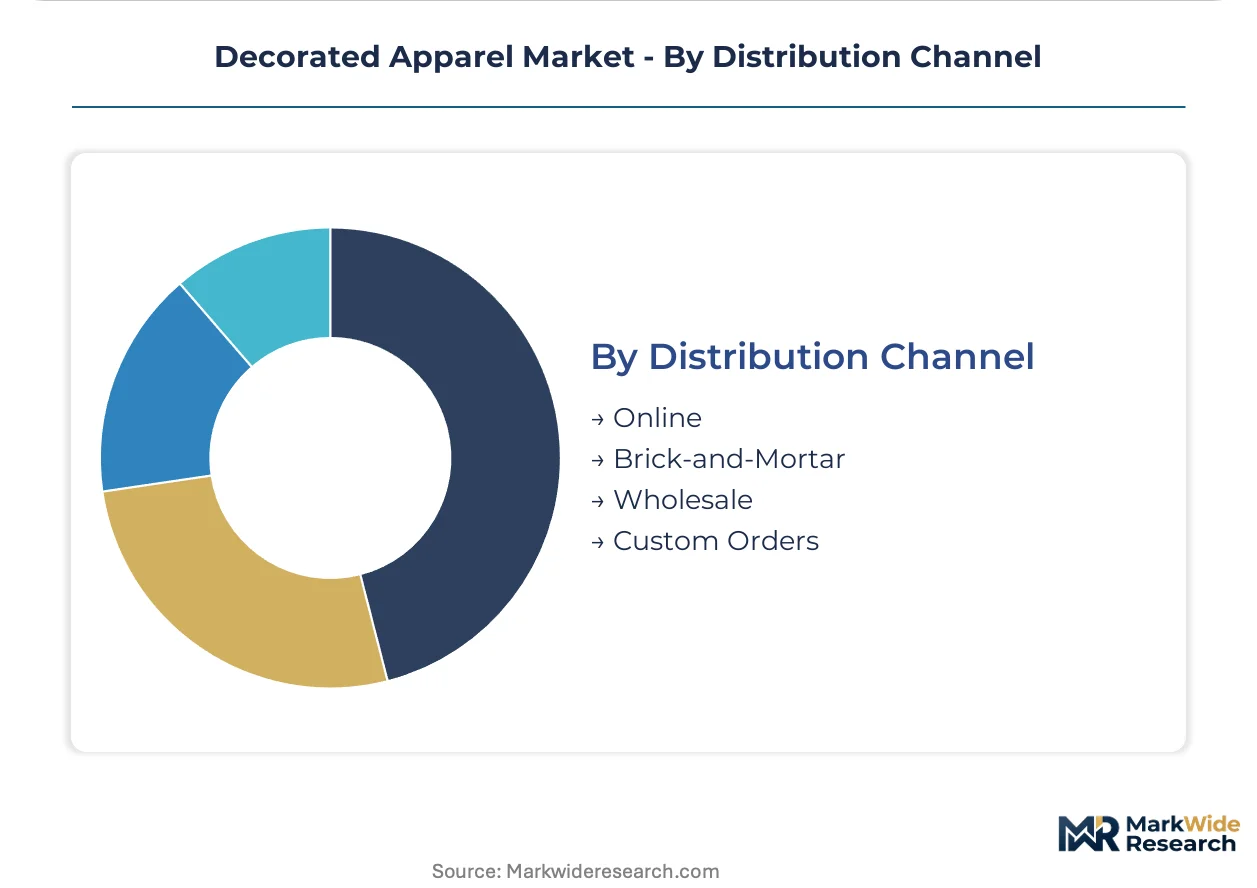
Online channels sit at the top of the volume ranking, with Custom Orders climbing the fastest as institutional buyers consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract decorating shops in the Carolinas region anchor decorated apparel production, with water-based ink conversion accelerating under EPA volatile organic compound enforcement. Demand concentrates in metropolitan clusters where team sports leagues and corporate promotional buyers sustain procurement volumes.
United States
Youth baseball and soccer leagues drive custom uniform program expansion across the Southeast and Midwest. EPA Title V permit modifications compel screen printing facilities in California, Texas, and North Carolina to accelerate plastisol phase-out. Charlotte and Greensboro host dense concentrations of contract decorators retrofitting conveyor dryers for lower-temperature curing profiles.
Germany
Corporate promotional spending from Mittelstand manufacturers sustains logoed T-shirt and outerwear procurement. REACH phthalate restrictions force heat transfer film reformulation toward OEKO-TEX Standard 100 compliant alternatives. The Ruhr industrial corridor and Bavarian manufacturing belt concentrate decorated apparel distributors serving French and Benelux retail channels.
China
Automated embroidery machine production clusters in Guangdong and Zhejiang provinces, creating lead time exposure for North American decorators dependent on East Asian equipment supply. GB standards on textile chemical safety tighten disclosure requirements for export-oriented printing operations. The Pearl River Delta hosts vertically integrated garment-to-decoration facilities serving European fast fashion accounts.
United Kingdom
Sports team merchandise demand from Premier League and rugby union licensing programs sustains premium decoration volumes. The country's national environmental regulator enforces emissions controls on textile printing operations comparable to REACH-aligned standards. Manchester and Birmingham metropolitan areas concentrate hybrid digital-embroidery service providers.
Mexico
Nearshoring trends redirect North American promotional products procurement toward Monterrey and Mexico City metro contract decorators. The country's federal environmental authority implements volatile organic compound monitoring at textile facilities in border states. Nuevo León hosts expanding screen printing capacity serving United States corporate accounts seeking reduced freight lead times.
Decorated Apparel Market Key Industry Players
Backward integration into yarn and fabric production dominates the current landscape as base goods supply security becomes critical for print-on-demand channel fulfillment. The market exhibits consolidated upstream supply with fragmented downstream decoration services, creating tiered competitive dynamics. Three archetypes define positioning: vertically integrated apparel manufacturers controlling raw material-to-garment supply chains, regional contract decorators specializing in league-level uniform program management, and digital-native platforms capturing short-run promotional demand. Capacity expansion in water-based curing infrastructure and strategic partnerships with sports licensing rights holders constitute the dominant competitive moves.
Within the integrated manufacturing tier, Gildan and Hanesbrands Inc. exemplify archetypes leveraging captive supply of cotton and polyester base goods to anchor wholesale and retail distribution channels. Fruit of the Loom, Inc. occupies a position representing volume-scale competition in promotional products segments. These three entities collectively demonstrate how upstream control over yarn-to-garment production creates defensive positioning against input cost volatility and supply disruption.
| Leading Market Players |
|---|
| Gildan |
| Fruit of the Loom, Inc. |
| Hanesbrands Inc. |
| Delta Apparel, Inc. |
| Downtown Custom Printwear |
| Master Printwear |
| Target Decorated Apparel |
| Advance Printwear Limited |
| Lynka |
| Others |
Cost & Logistics Intelligence
Mesh-count calibration specialists in the Carolinas region command wage premiums that compress standard-tier margins while amplifying spreads between economy and premium decoration services. Labor-cost differentials between certified technicians and general production workers determine pricing-tier boundaries across screen printing and embroidery operations.
Pricing Analysis
Input-cost pass-through from cotton-polyester blend volatility and water-based ink reformulation is reshaping contract decorator economics. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified league uniform programs from promotional T-shirt runs. Price differentiation hinges on certification grade and volume scale, with fall-winter hoodie procurement absorbing higher unit premiums. Cost compression in standard-tier screen printing is intensifying because EPA compliance retrofitting concentrates fixed costs among mid-volume shops. Corporate promotional buyers exhibit lowest price sensitivity due to brand consistency requirements, while event merchandisers maximize cost minimization.
Supply Chain Analysis
Domestic-content mandates in United States federal procurement are redirecting uniform program sourcing toward North American base goods suppliers. Geographic supply concentration centers on China for automated embroidery equipment, Bangladesh for cotton knit fabric, and Vietnam for polyester fleece. Raw material dependencies draw from cotton futures markets, water-based pigment dispersions, and phthalate-compliant heat transfer films. Single-source vulnerability clusters in Guangdong province embroidery machine production, creating lead time exposure for decorators dependent on East Asian equipment supply. Distribution runs through wholesale aggregators serving mass retail channels and direct-to-garment platforms capturing short-run corporate demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based curing infrastructure amortization and premium-tier certification positioning create margin expansion headroom for operators mastering compliance workflows. The shift from plastisol to EPA-compliant chemistry rewards early movers with cost-structure advantages and league contract eligibility.
For Market Incumbents: Cement defensive positioning through captive base goods supply and OEKO-TEX certification investment. Accelerate conveyor dryer retrofitting for lower-temperature curing profiles before EPA enforcement escalates penalty structures. Backward integration into yarn-to-garment production insulates against cotton-polyester blend price volatility threatening standard-tier margins.
For New Entrants and Emerging Players: Enter via digital-embroidery hybrid service models targeting youth sports league consolidation. The most penetrable segment sits in regional uniform program management displaced from fragmented local shop relationships. Lead with rapid-turnaround direct-to-garment capabilities for event merchandising and corporate promotional short runs.
For Investors and Strategic Acquirers: Apparel manufacturers with print-on-demand channel infrastructure are the most active acquirer in this space, seeking decoration capabilities to complete vertical control. Long-term viability favors operators with water-based curing capacity and league-level master service agreements. Monitor EPA Title V permit modification timelines as inflection indicator for compliance-driven consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Curing Infrastructure Investment | EPA volatile organic compound enforcement in California and Texas accelerates plastisol phase-out economics. |
| League-Level Master Service Agreement Procurement | Youth baseball and soccer league consolidation displaces fragmented local decorator relationships. |
| OEKO-TEX Standard 100 Certification Program | German and French retail channel entry requires compliant water-based ink and heat transfer systems. |
| Direct-to-Garment Platform Integration | Corporate promotional buyers seek rapid turnaround without screen setup waste minimums. |
| Backward Integration into Base Goods Supply | Captive yarn-to-garment production secures print-on-demand fulfillment against input cost volatility. |
Research Approach
Coverage spans United States, Germany, China, United Kingdom, and Mexico, with primary inputs from each market informing cross-regional pattern identification. Primary interviews with contract decorating shop owners, league uniform program administrators, corporate promotional procurement managers, and water-based ink formulation chemists combined with secondary validation from EPA enforcement records, REACH substance restriction databases, OEKO-TEX certification registries, and United States customs trade data. Bottom-up and top-down triangulation reconciles facility-level capacity estimates with aggregate demand projections across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by product type, decoration method, end user archetype, and distribution channel, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from replacement cycle analysis and technology adoption S-curves applied to institutional procurement patterns. Industry-specific forecast inputs include youth sports participation trajectories and corporate promotional spending elasticity to economic cycles.
Inputs from EPA enforcement action records and OEKO-TEX certification databases were available through the study window; gaps in real-time contract decorator capacity utilization data introduce uncertainty bands around near-term supply-side estimates. Forecasts reflect assumptions regarding water-based ink conversion velocity and league procurement consolidation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Body Shaper Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
New Smart Wardrobe Market