
 Pitting Machines Market | 2026-2036
Pitting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pitting Machines Market Insights
A capital-intensity divergence between automated and manual pitting specialists is redrawing competitive boundaries in the equipment sector. Sormac leverages its European engineering base to sustain premium positioning in olive and cherry processing lines. GELGOOG anchors its expansion across Asian fruit processing markets with cost-optimized mechanical technology platforms. Atlas Pacific dominates North American citrus and stone fruit applications through extensive aftermarket service networks.
Pitting machines are industrial food processing equipment engineered to remove seeds, stones, and pits from fruits, olives, and related agricultural products through mechanical, pneumatic, or hydraulic force application, typically operating at throughputs ranging from 500 kilograms to over 10,000 kilograms per hour depending on product density and pit hardness. Their primary commercial purpose centers on enabling downstream processing efficiency, yield recovery, and food safety compliance in high-volume operations where manual pitting creates contamination risk and labor cost escalation. Automated pitting systems command the steepest technology premiums while batch pitting retains relevance in artisan olive oil and specialty fruit segments where product integrity outweighs speed metrics. Mechanical technology still occupies the largest installed base, though pneumatic configurations are gaining traction in delicate fruit applications where bruising reduction drives purchase criteria.
FDA food safety modernization standards and EU machinery safety directives shape equipment design mandates, forcing manufacturers to integrate hygienic design principles and traceable control systems. BIS certification requirements in India and China's GB standards for food contact machinery create additional compliance layers for exporters targeting emerging processing hubs. Stakeholders must weigh technology migration timelines against regional regulatory phase-in schedules when allocating R&D and certification budgets.
Market Dynamics
Automated pitting systems are compressing batch processing margins as California and Italian facilities accelerate technology migration to meet throughput and traceability mandates from FDA and EU machinery safety frameworks.
Growth Catalysts
- EU Machinery Safety Directives:European processing facilities face mandatory guard interlock and hygienic design upgrades, forcing replacement cycles in Italy's olive oil belt and Spain's stone fruit cooperatives.
- Pneumatic bruise-reduction technology:Delicate cherry and apricot processors in Washington State and British Columbia are specifying air-actuated pit extraction to minimize flesh damage and downstream waste.
- California Central Valley cluster:Consolidation among stone fruit canneries in Fresno and Modesto counties is driving centralized procurement of high-throughput automated lines.
Market Restraints
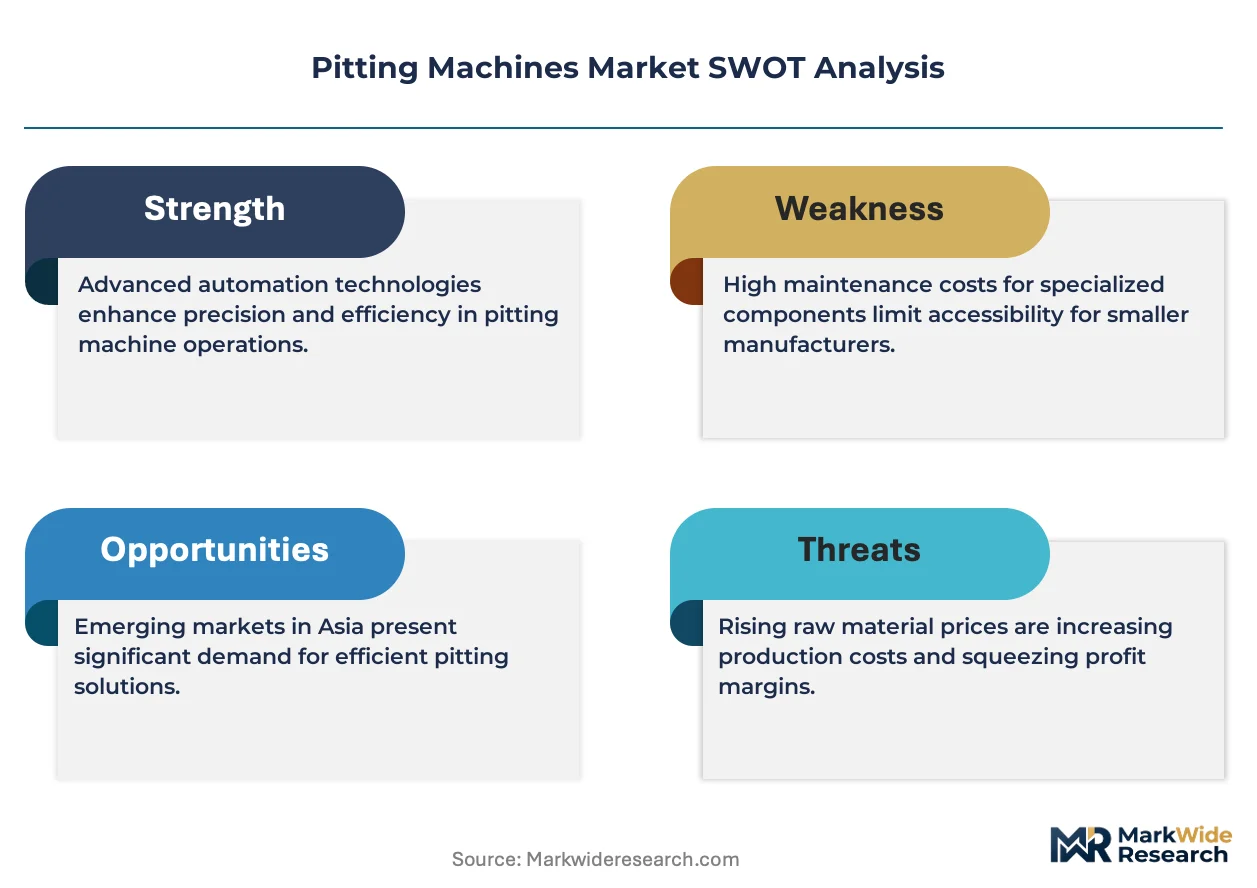
- Stainless steel input volatility:Grade 316L and 304 price swings from Chinese and Indonesian mills compress equipment margin buffers for European fabricators.
- Specialized component concentration:Precision servo drives and hygienic bearings concentrate supply among German and Japanese industrial automation suppliers, creating single-source vulnerability.
- Manual pitting substitution:Artisan olive oil producers in Andalusia and Puglia retain hand-pitting for premium extra-virgin grades, capping automated penetration in price-sensitive segments.
Strategic Opportunities
- India BIS certification pathway:Maharashtra and Karnataka fruit processing clusters lack compliant domestic pitting equipment, creating first-mover advantage for certified exporters.
- Dual mechanical-pneumatic hybrid platforms:Convergence of force-adjustable mechanical drives with precision air ejection enables single-line flexibility across hard-pit and soft-fruit rotations.
- Direct-to-cooperative sales channels:Bypassing traditional distributor networks in Chile's Maule Valley and Argentina's Mendoza province captures margin and accelerates installation timelines.
Industry Challenges
- Food safety validation timelines:FDA hazard analysis verification and EU CE conformity assessment cycles extend 8-14 months, delaying revenue recognition for new platform launches.
- Legacy line integration complexity:Retrofitting automated pitting cells into 1990s-era canning and brining infrastructure in Greece and Portugal requires custom mechanical interfacing and control system bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pitting Machines Market |
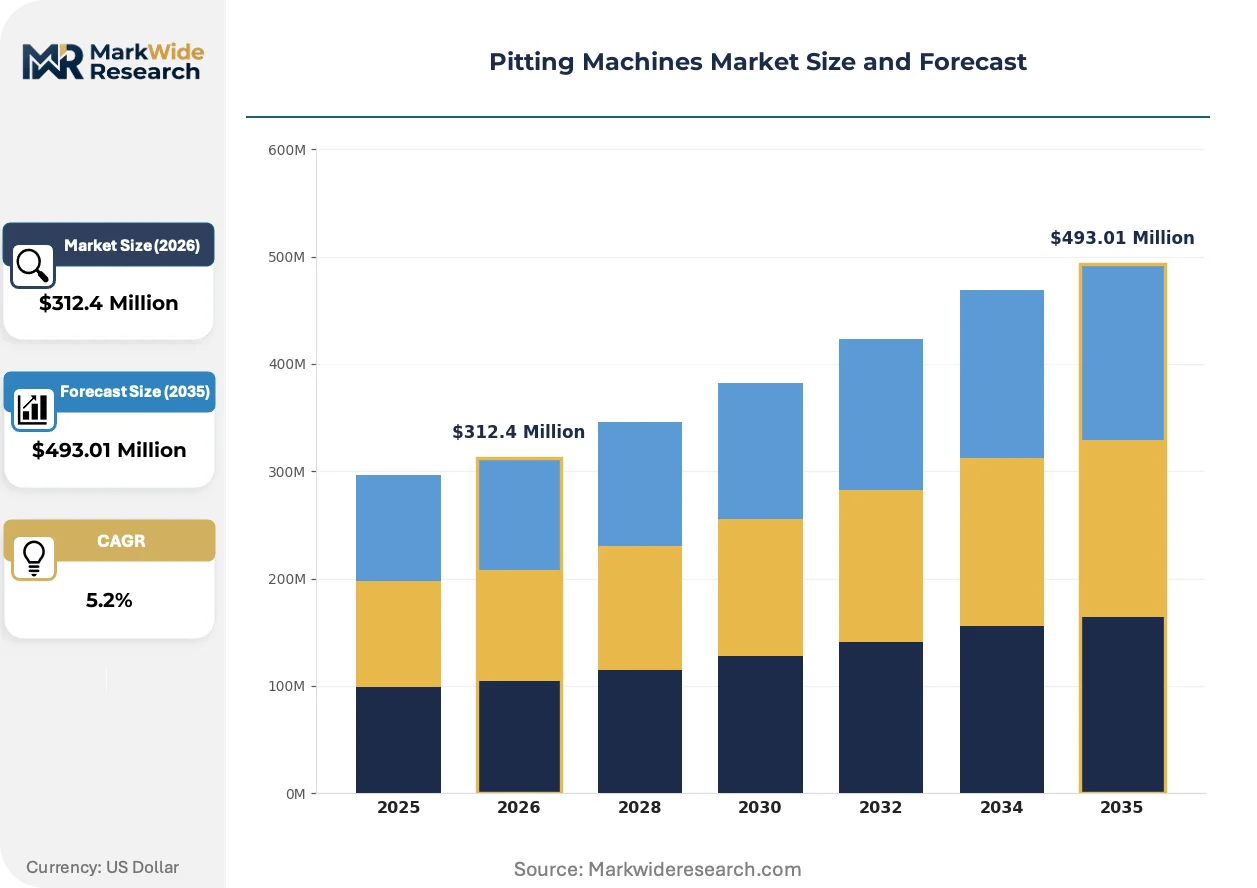
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $493.01 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Pitting, Batch Pitting, Automated Pitting, Manual Pitting End User: Food Processing, Packaging Industry, Beverage Industry, Agricultural Sector Technology: Mechanical Technology, Pneumatic Technology, Hydraulic Technology, Electrical Technology Application: Fruit Processing, Olive Oil Production, Snack Manufacturing, Others |
| Companies Covered | Sormac, Sunkist Growers, Romiter Machinery, CTI FoodTech Group, GELGOOG, MORI-TEM, OMIP, Atlas Pacific, Pigo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pitting Machines Market Trends and Innovations
Vision-guided pit detection and adaptive force control are rewriting equipment specifications as processors confront labor scarcity and zero-defect export requirements. Three developments dominate current engineering priorities.
Machine vision with spectral imaging is decomposing the traditional mechanical sizing-calibration model. Cherry and plum processors in British Columbia and Washington State are deploying real-time stone detection to adjust extraction force per fruit. This capability is decomposing the premium attached to uniform feedstock grading, allowing mixed-lot processing without yield penalty.
REACH substance restrictions on lubricants and hydraulic fluids are forcing formulation switches in European-manufactured equipment. Italian and Spanish OEMs are certifying plant-based and synthetic ester alternatives for incidental food contact. Stone fruit canneries in Northern Italy report accelerated compliance audits as EU enforcement tightens.
Service contract unbundling is fragmenting traditional bundled maintenance relationships. Large Central Valley processors are separating preventive maintenance, spare parts logistics, and remote diagnostics into discrete supplier relationships. This pattern is most pronounced among publicly traded fruit processors with procurement centralization mandates.
Pitting Machines Market Segmentation
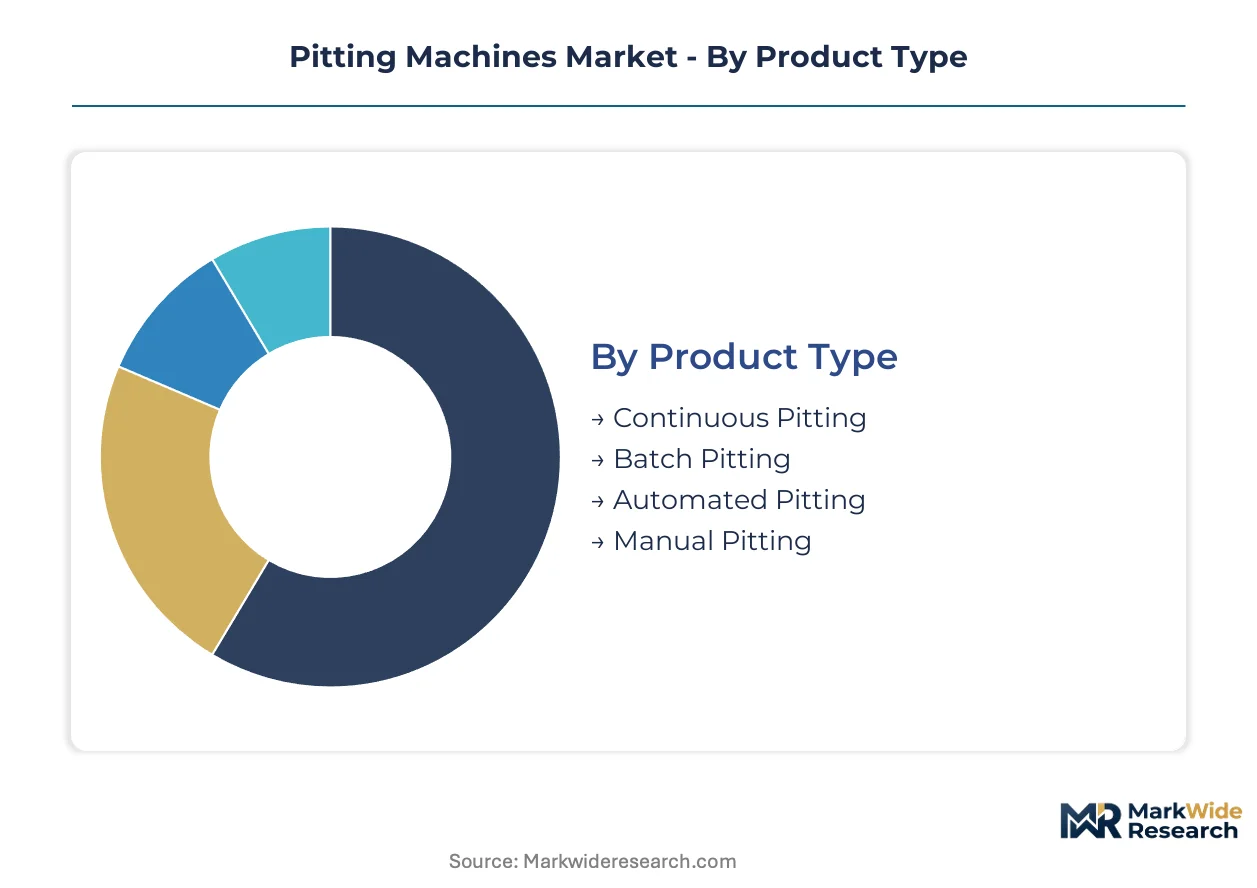
Pitting machines serve distinct operational profiles across throughput scales and product fragility. Segment boundaries reflect capital intensity divergence, regulatory compliance tiers, and regional processing infrastructure maturity.
Product Type:
Channel flows split between turnkey integrators serving high-volume processors and specialized distributors supplying artisan operations.
- Continuous Pitting:High-throughput rotary or linear systems processing 2,000-10,000 kg/hour through synchronized feed mechanisms and extraction drums. California Central Valley stone fruit canneries and Spanish olive cooperatives specify these for integrated canning and oil extraction lines where downtime costs exceed equipment capital.
- Automated Pitting:Servo-driven vision-guided platforms with adaptive force control and real-time pit detection. Washington State cherry processors and Northern Italian plum concentrators deploy these to meet FDA traceability mandates and EU machinery safety directives for guard interlock compliance.
- Batch Pitting:Semi-automated chamber systems for 200-800 kg/hour cycles. Andalusian extra-virgin olive oil mills and Puglia artisan producers retain these for premium grades where flesh integrity commands price premiums over throughput.
- Manual Pitting:Hand-fed bench units with mechanical or pneumatic assist. Greek island cooperatives and small-scale Argentine Mendoza fruit processors use these where labor availability exceeds capital access.
By volume, continuous pitting leads. By growth pace, automated pitting is climbing the fastest.
End User:
Cost tier stratification separates capital-heavy integrated processors from price-sensitive agricultural cooperatives.
- Food Processing:Large-scale canneries, concentrate plants, and frozen fruit operations running multi-shift schedules. Fresno County peach processors and Modesto apricot dryers specify stainless steel 316L construction with CIP compatibility for FDA food safety modernization compliance.
- Agricultural Sector:Cooperative-owned oil mills and fresh-market packing houses with seasonal utilization patterns. Italy's olive oil belt and Chile's Maule Valley fruit cooperatives dominate procurement, prioritizing equipment financing over technology sophistication.
- Beverage Industry:Juice concentrate and smoothie ingredient suppliers requiring pit-free purees. Brazilian orange processors and Turkish pomegranate concentrate exporters specify these for export-grade aseptic filling compatibility.
- Packaging Industry:Contract packers and private-label suppliers running diverse fruit rotations. These operators favor quick-changeover mechanical platforms over specialized single-fruit lines.
Food processing commands the largest installed base. Agricultural sector procurement is expanding most quickly as cooperative consolidation accelerates.
Technology:
Application requirements drive technology selection across fruit hardness spectra and bruise sensitivity thresholds.
- Mechanical Technology:Rotating blades, augers, and compression drums using direct motor drive. Still dominates olive and hard-pit stone fruit applications in Spain, Italy, and California where pit hardness exceeds 50 Shore D.
- Pneumatic Technology:Air-actuated ejection with pressure-modulated force control. British Columbia cherry processors and Tasmanian apricot dryers specify these for flesh damage reduction below 3% in delicate varieties.
- Hydraulic Technology:Oil-pressure systems for high-force extraction in dense tropical fruits. Limited penetration outside Brazilian açaí and date processing operations due to REACH lubricant compliance costs in European markets.
- Electrical Technology:Direct servo and linear motor actuation with precision position feedback. Emerging in hybrid platforms combining mechanical robustness with pneumatic delicacy for multi-fruit flexibility.
Mechanical technology retains volume leadership. Pneumatic configurations are gaining share fastest as bruise-reduction specifications tighten in export markets.
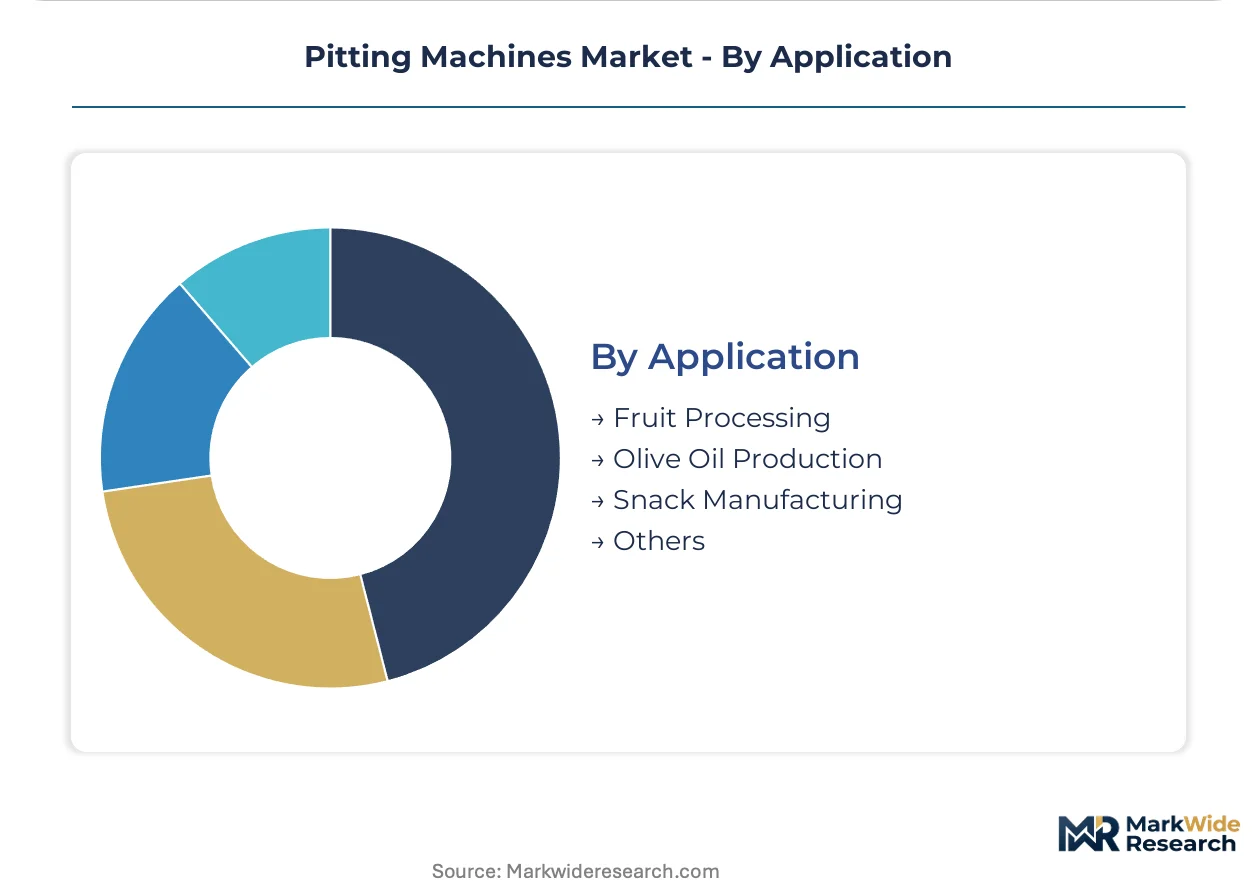
Application:
Customer type divergence separates commodity volume processors from premium product specialists.
- Fruit Processing:Stone fruit canning, freezing, and drying operations across California, Washington State, and British Columbia. These facilities specify throughput-optimized continuous lines with integrated waste separation.
- Olive Oil Production:Extra-virgin and refined oil mills concentrated in Andalusia, Puglia, and California's Central Coast. Two-tier demand splits between automated malaxing-integrated pitters for volume producers and batch units for single-estate premium labels.
- Snack Manufacturing:Dried fruit and energy bar ingredient suppliers. Turkish apricot dryers and Chilean cranberry processors specify pit-free guarantees for retail-ready packaging lines.
- Others:Seed extraction for breeding programs, pharmaceutical ingredient preparation, and cosmetic oil processing. Niche volumes with specialized hygienic and containment requirements.
Fruit processing leads by unit volume. Olive oil production shows the steepest expansion trajectory as Mediterranean and New World plantings mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented pitting equipment flows from Italian and German engineering bases toward processing clusters in California, Chile, and emerging Asian markets. Import dependency concentrates in cooperative-dominated Mediterranean olive belts and Latin American fruit valleys where domestic fabrication capacity remains thin. Currency volatility and shipping cost spikes are compressing cross-border equipment margins.
United States
California's Central Valley stone fruit canneries drive automated line procurement as FDA food safety modernization mandates tighten traceability requirements. Fresno County and Modesto County processing corridors specify stainless steel 316L construction with CIP compatibility. Washington State cherry processors in Yakima Valley deploy pneumatic bruise-reduction systems for export-grade delicate varieties.
Italy
Andalusian olive oil cooperatives and Puglia's extra-virgin producers sustain two-tier demand splitting between automated malaxing-integrated lines and batch units for single-estate premium labels. EU machinery safety directives force guard interlock and hygienic design upgrades across Emilia-Romagna and Tuscany processing belts. REACH substance restrictions on lubricants accelerate formulation switches in domestic OEM supply chains.
Spain
Stone fruit cooperatives in Murcia and Valencia accelerate replacement cycles to meet EU machinery safety framework compliance deadlines. Olive oil volume producers in Andalusia consolidate procurement of high-throughput continuous pitters. Spanish fabricators leverage proximity to Portuguese and Moroccan processing markets for cross-border equipment sales.
China
GB standards for food contact machinery and SAMR enforcement create compliance layers for imported European equipment. Zhengzhou and Shandong fruit processing clusters lack compliant domestic pitting capacity, opening first-mover pathways for certified exporters. Dual carbon goals pressure energy-intensive foundry suppliers serving equipment fabricators.
India
Maharashtra and Karnataka fruit processing clusters face BIS certification gaps in domestic pitting equipment supply. Nashik grape processors and Bengaluru mango concentrate plants import European mechanical platforms despite landed cost premiums. FSSAI hygiene mandates and PLI scheme incentives reshape procurement timelines for cooperative-owned facilities.
Pitting Machines Market Competitive Landscape
Concentration sits with European engineering specialists and Asian cost-optimized fabricators occupying distinct technology tiers. Italian and German OEMs anchor premium positioning through aftermarket service density and regulatory certification depth. Chinese and Turkish producers compress price points for emerging market penetration. Strategic moves center on hybrid technology licensing and direct-to-cooperative sales channel bypass.
Among European engineering specialists, Sormac exemplifies premium-tier positioning anchored in olive and cherry processing line expertise. GELGOOG occupies the cost-optimized technology vector across Asian fruit processing markets. Atlas Pacific represents North American aftermarket service density in citrus and stone fruit applications. CTI FoodTech Group sits within the mid-tier integration specialist archetype serving cannery retrofit requirements.
| Leading Market Players |
|---|
| Sormac |
| Sunkist Growers |
| Romiter Machinery |
| CTI FoodTech Group |
| GELGOOG |
| MORI-TEM |
| OMIP |
| Atlas Pacific |
| Pigo |
| Others |
Pricing and Supply Chain Analysis
Capital-intensity divergence between automated and batch pitting platforms concentrates manufacturing scale among Italian and German engineering specialists, compressing price floors for cost-optimized Asian fabricators while elevating entry barriers for mid-tier European producers serving cooperative buyers in Spain and California.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by CE/FDA certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese fabricators are penetrating India's BIS-compliant equipment gap. Agricultural cooperatives in Andalusia and Puglia exhibit highest price sensitivity, while Central Valley canneries prioritize traceability compliance over capital outlay.
Supply Chain Analysis
China and Indonesia anchor stainless steel 316L and 304 supply for European fabricators, while Germany and Japan concentrate precision servo drive and hygienic bearing production. Raw material input draws from nickel ore processing in Indonesia and cold-rolled steel mills in Shandong province. Single-source vulnerability in motion control components creates supply chain risk. Distribution runs through turnkey integrators serving high-volume processors and specialized distributors supplying artisan operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between vision-guided pit detection and legacy canning infrastructure is creating platform-economics inflection, as processors demand modular retrofit kits rather than greenfield line replacements.
For Market Incumbents: Shield installed-base revenue by deepening aftermarket service density in California's Central Valley and Italy's olive oil belt against Chinese cost-optimized entrants. Prioritize CE/FDA dual-certification investment to maintain specification control in EU machinery safety directive upgrade cycles. Vertical integration into precision bearing supply reduces exposure to Japanese automation supplier concentration. For New Entrants and Emerging Players: Aftermarket retrofit expertise represents the most penetrable white-space, as Greek and Portuguese canneries struggle with legacy line integration complexity. Target Maharashtra and Karnataka fruit processing clusters with BIS-certified mechanical platforms before domestic Indian fabrication matures. Direct-to-cooperative sales channels in Chile's Maule Valley bypass entrenched distributor margin capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid technology licensors offering adaptive force control patents across mechanical-pneumatic platforms. Long-term viability favors mid-tier integration specialists with cannery retrofit capabilities rather than pure-play automated platform developers. Watch FDA hazard analysis verification timeline compression as inflection indicator for revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing | Enables single-line flexibility across hard-pit olives and delicate cherries for multi-fruit processors. |
| Direct-to-Cooperative Sales Channel | Bypasses distributor networks in Chile's Maule Valley to capture margin and accelerate installation timelines. |
| CE/FDA Dual Certification Investment | Secures specification control in EU machinery safety directive and FDA food safety modernization upgrade cycles. |
| Aftermarket Service Unbundling | Separates preventive maintenance, spare parts logistics, and remote diagnostics for procurement-centralized processors. |
| BIS Certification Pathway Entry | Creates first-mover advantage in Maharashtra and Karnataka clusters lacking compliant domestic equipment supply. |
Research Methodology
A standing panel of plant engineers at Central Valley canneries, aftermarket service directors at European OEMs, and procurement leads at Italian olive cooperatives provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from EU machinery safety directive filings, FDA food safety modernization audit records, and customs trade data on stainless steel equipment imports. Bottom-up equipment shipment analysis triangulated against top-down processing capacity expansion in key fruit and olive production belts.
Consistency checks validated volume and value outputs against external benchmarks including agricultural processing machinery trade associations and regional cooperative procurement disclosures. The analytical framework modeled segmentation across technology type, operational scale, and regulatory compliance tier throughout the projection horizon. CAGRs derived from equipment replacement cycle analysis, cooperative consolidation patterns, and technology migration timelines in FDA and EU enforcement jurisdictions.
Forecasts assume regulatory continuity in FDA food safety modernization and EU machinery safety directive enforcement; material policy shifts in REACH substance restrictions or BIS certification scope would require re-modeling. Specific risks include stainless steel price volatility from Indonesian nickel ore supply and single-source vulnerability in German and Japanese motion control components. Recalibration cycles align with material shifts in regulatory enforcement intensity and cooperative consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Global Oxidative Stress Assay Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Gold Tester Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Gas Calorimeter Market