
 Revenue Management Software Market | 2026-2036
Revenue Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Revenue Management Software Market Outlook
Multi-source vendor strategies is hardening across enterprise procurement teams evaluating revenue management platforms. Salesforce Revenue Cloud leverages its CRM-native architecture to anchor pricing intelligence within existing sales workflows. IDeaS sustains deep specialization in hospitality yield algorithms, while Zenskar competes through modern usage-based billing integrations that extend platform utility beyond traditional sectors.
Revenue management software encompasses algorithmic platforms that ingest demand signals, inventory levels, and competitive pricing data to automate optimal rate-setting decisions, typically processing millions of price points through machine learning models with sub-minute refresh cycles. The primary commercial purpose centers on maximizing yield per available unit across perishable inventory categories such as hotel rooms, airline seats, and digital advertising slots. Cloud-based deployment now captures the dominant margin pool as vendors shift from perpetual licenses to recurring SaaS structures, while dynamic pricing modules lead product-type adoption due to their direct revenue impact. Data analytics represents the fastest-growing segment as enterprises demand predictive capabilities that unify historical booking patterns with external macroeconomic indicators.
FCC guidelines on data transmission integrity and GDPR requirements in Europe shape how cross-border pricing data flows through vendor cloud infrastructure, creating compliance barriers for non-certified providers. The EU AI Act introduces additional algorithmic transparency mandates that will filter vendor eligibility for European hospitality and airline accounts. Stakeholders must monitor regulatory divergence between US federal privacy frameworks and state-level legislation to determine whether single-tenant or multi-tenant architectures offer superior risk-adjusted deployment paths.
Market Dynamics
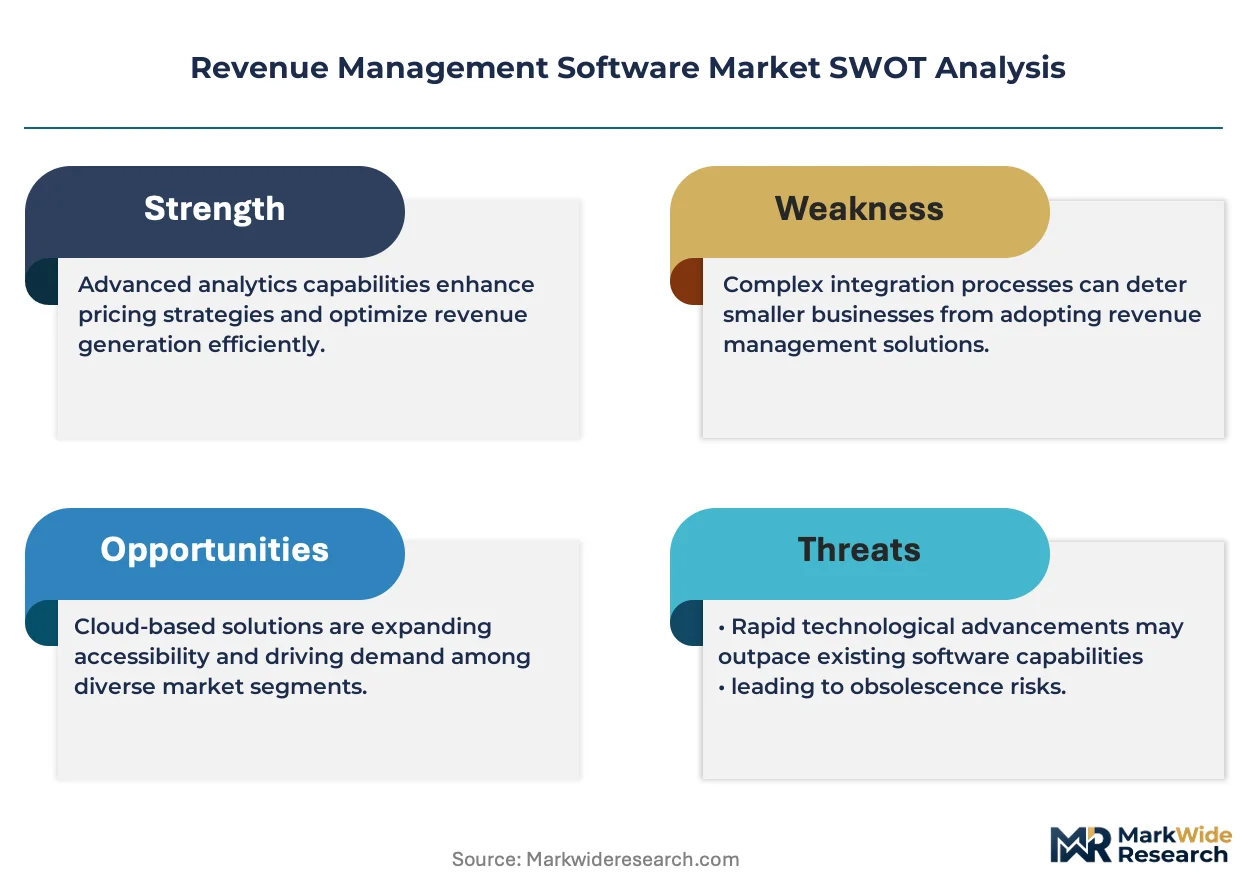
Cloud migration is compressing vendor switching costs while EU AI Act transparency mandates are forcing algorithmic audit investments that reshape competitive moats in hospitality and airline procurement cycles.
Growth Catalysts
- GDPR-driven data governance upgrades:European hospitality chains are replacing legacy systems with certified platforms to maintain cross-border pricing data flows without regulatory interruption.
- Real-time inventory perishability:Airlines and hotels face margin compression from unsold seats and rooms, accelerating demand for sub-minute price refresh capabilities.
- Mid-market SaaS procurement:Independent hotel operators in the United States are consolidating onto cloud-native platforms to match enterprise yield management sophistication.
Market Restraints
- Algorithmic audit infrastructure costs:EU AI Act compliance requires explainable ML pipelines that inflate platform development budgets by 20-40% for non-legacy vendors.
- Data residency fragmentation:Divergent US state privacy laws (California, Virginia, Colorado) force multi-tenant architecture compromises that increase operational complexity.
- Legacy system entrenchment:Major hotel chains carry decades-old property management systems with brittle APIs that resist dynamic pricing module integration.
Strategic Opportunities
- Usage-based billing convergence:SaaS vendors can extend platform utility into subscription revenue recognition by embedding modern metering engines alongside yield algorithms.
- India hospitality digitization:Budget hotel aggregators and airline OTAs lack sophisticated revenue optimization, creating whitespace for mid-market cloud deployments.
- CSRD sustainability reporting:European corporate travel buyers now require carbon-adjusted pricing transparency, opening modules that unify yield with emissions data.
Industry Challenges
- Revenue science talent scarcity:Hotel chains and vendors compete for data scientists with hospitality-specific demand forecasting expertise, compressing implementation timelines.
- Multi-cloud integration complexity:Enterprises running pricing engines across AWS, Azure, and GCP environments face latency inconsistencies that degrade real-time rate synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revenue Management Software Market |
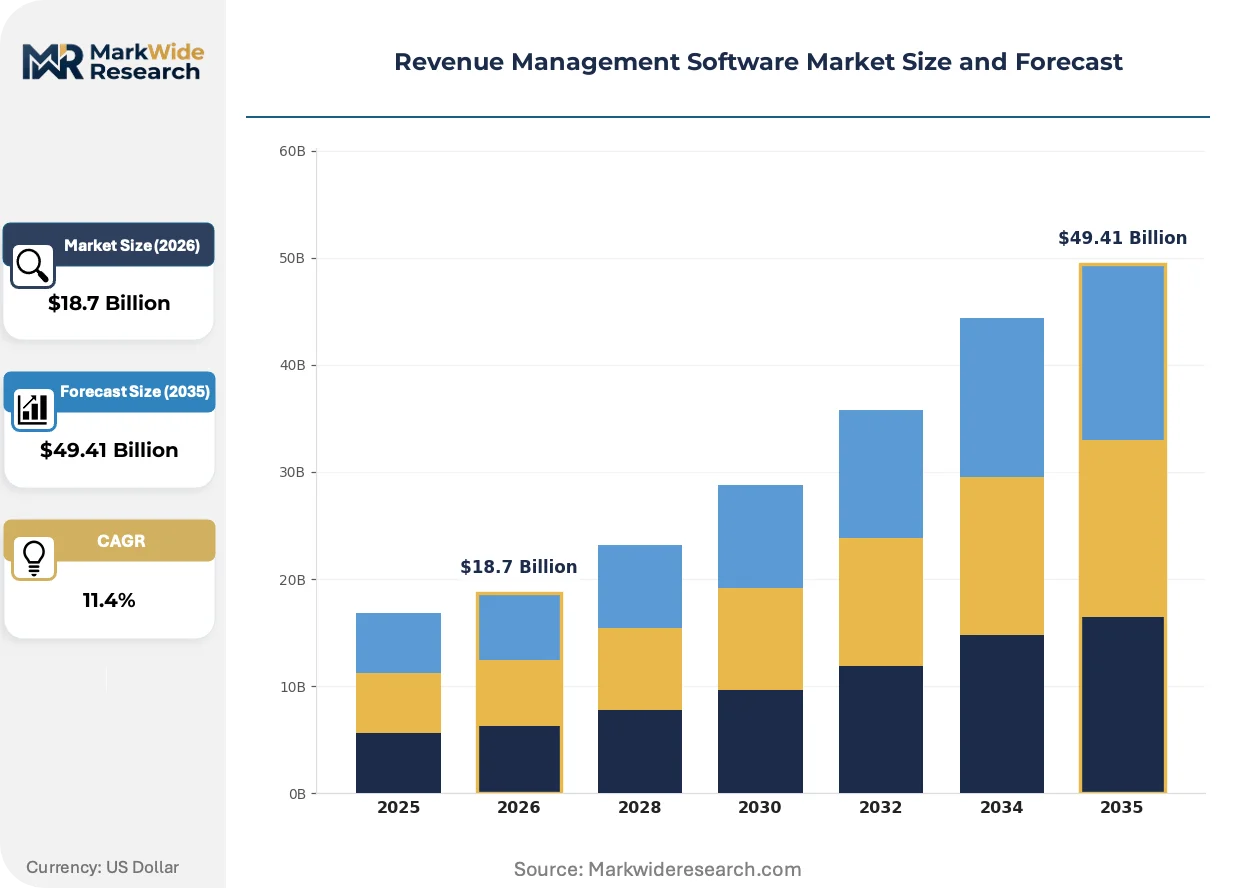
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Pricing, Demand Forecasting, Inventory Optimization, Data Analytics Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Tenant End User: Hospitality, Airlines, Retail, E-Commerce Solution: Revenue Optimization, Pricing Strategy, Yield Management, Reservation Management |
| Companies Covered | Salesforce Revenue Cloud, NetSuite, Pipedrive, Zoho, Chargebee, Mews, IDeaS, Zenskar, monday CRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revenue Management Software Market Strategic Shifts
Machine learning inference at the edge is reshaping how pricing decisions reach property-level systems, while regulatory transparency mandates and buyer procurement centralization are rewriting vendor qualification criteria.
Embedded machine learning is absorbing demand signal processing directly into property management system workflows, eliminating batch-update delays. Mid-market hotel operators in the United States are adopting these modules fastest, drawn by subscription economics that replace capital-intensive legacy upgrades. The technology is absorbing pricing decision latency from hours to seconds, compressing competitive differentiation around refresh speed rather than algorithm sophistication alone.
EU AI Act algorithmic transparency requirements are mandating interpretable demand forecasting models with auditable decision trails. Hospitality vendors serving European airline and hotel accounts must now maintain technical documentation that exposes feature weights and training data provenance. This regulatory shift most affects black-box neural network architectures, pushing vendors toward gradient-boosted or linear surrogate models that sacrifice marginal accuracy for compliance certainty.
Centralized procurement offices at multinational hospitality groups are consolidating vendor relationships from property-level to enterprise-wide master agreements. Regional revenue managers lose autonomy over platform selection as headquarters negotiates unified pricing and data governance terms. This concentration is most visible across United States-based hotel portfolios, where procurement teams now mandate single-tenant cloud deployments with dedicated infrastructure isolation.
Revenue Management Software Market Segmentation
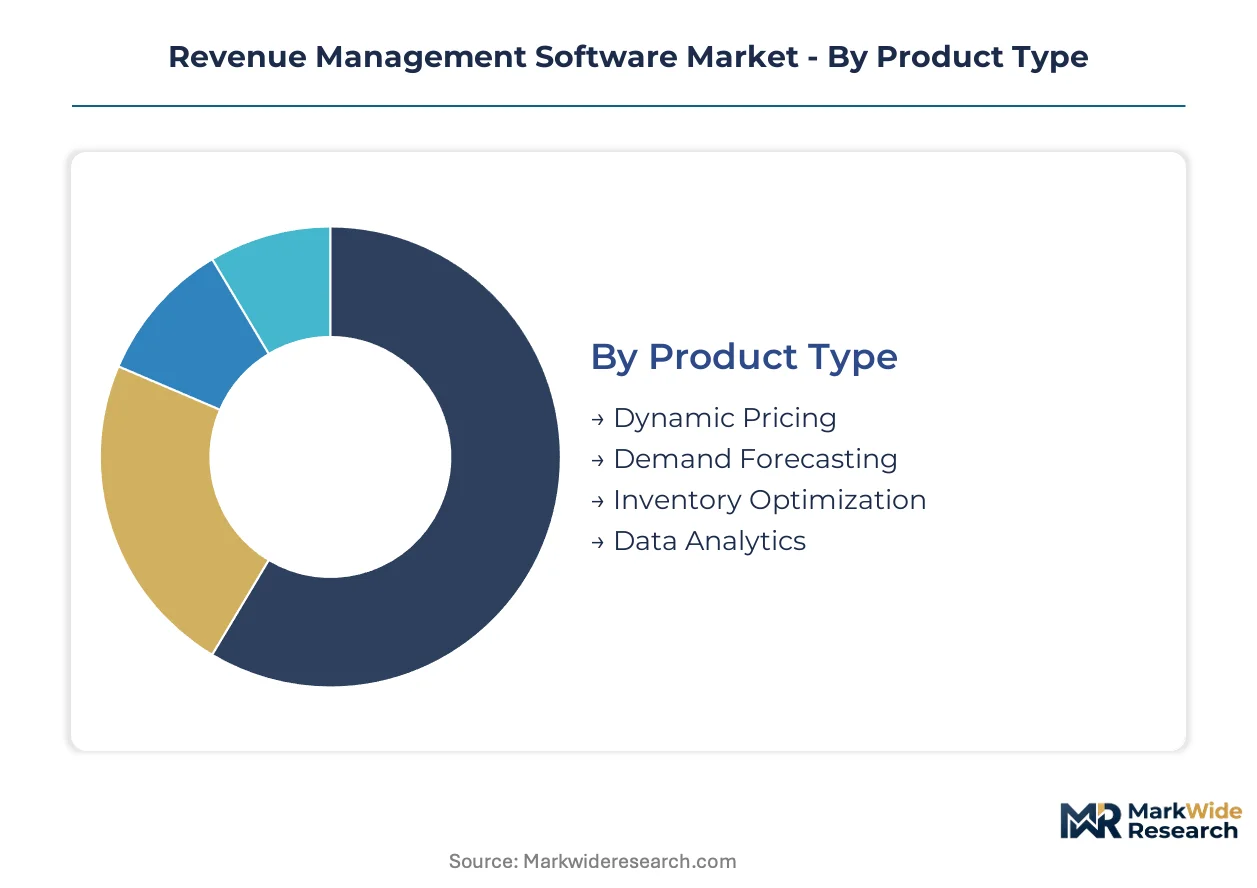
Revenue management software segmentation reveals how vendor R&D budgets and procurement priorities diverge across technical architectures and commercial applications. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Supply concentration in algorithmic pricing modules has concentrated vendor patent portfolios around real-time inference engines.
- Dynamic Pricing:Algorithms ingest competitive rate feeds, inventory levels, and demand signals to automate price adjustments with sub-minute refresh cycles. Airlines and hotel chains in the United States deploy these engines to capture revenue from perishable seat and room inventory before departure or check-in deadlines.
- Data Analytics:Predictive platforms unify historical booking patterns with external macroeconomic indicators to forecast demand curves. European hospitality groups under GDPR and EU AI Act mandates prioritize these modules for auditable decision trails that satisfy algorithmic transparency requirements.
- Demand Forecasting:Machine learning models project occupancy and load factors using seasonal patterns and event calendars.
- Inventory Optimization:Systems allocate constrained capacity across customer segments to maximize yield per available unit.
Today's leader: Dynamic Pricing. Tomorrow's challenger: Data Analytics.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from subscription-native cloud alternatives.
- Cloud-Based:SaaS delivery eliminates hardware procurement and enables elastic scaling during peak booking windows. Mid-market hotel operators in the United States favor this model for its replacement of perpetual licenses with predictable operational expenditures.
- Multi-Tenant:Shared infrastructure architectures reduce per-customer hosting costs while maintaining data isolation through logical partitioning. Vendors targeting European accounts face EU AI Act compliance overhead that inflates development budgets for these configurations.
- On-Premises:Single-tenant installations within customer data centers address stringent data residency requirements.
- Hybrid:Split deployments process sensitive pricing data locally while offloading analytics workloads to cloud infrastructure.
Cloud-Based captures current procurement volume. Multi-Tenant architectures are climbing the fastest as vendors optimize unit economics.
End User:
Application intensity varies sharply across sectors with differing inventory perishability and pricing frequency requirements.
- Hospitality:Hotel chains and independent properties apply yield algorithms to room inventory with nightly rate refresh cycles. Enterprise groups in the United States consolidate property-level systems onto centralized platforms to standardize revenue science capabilities across portfolios.
- Airlines:Carriers process millions of fare combinations across origin-destination pairs with continuous adjustment based on competitor pricing and booking pace.
- Retail:Merchants optimize markdown timing and promotional depth for seasonal merchandise with finite selling windows.
- E-Commerce:Digital marketplaces adjust product pricing dynamically based on competitor monitoring and conversion rate signals.
Hospitality dominates current platform deployments. Airlines present the steepest expansion trajectory as legacy revenue management systems reach replacement cycles.
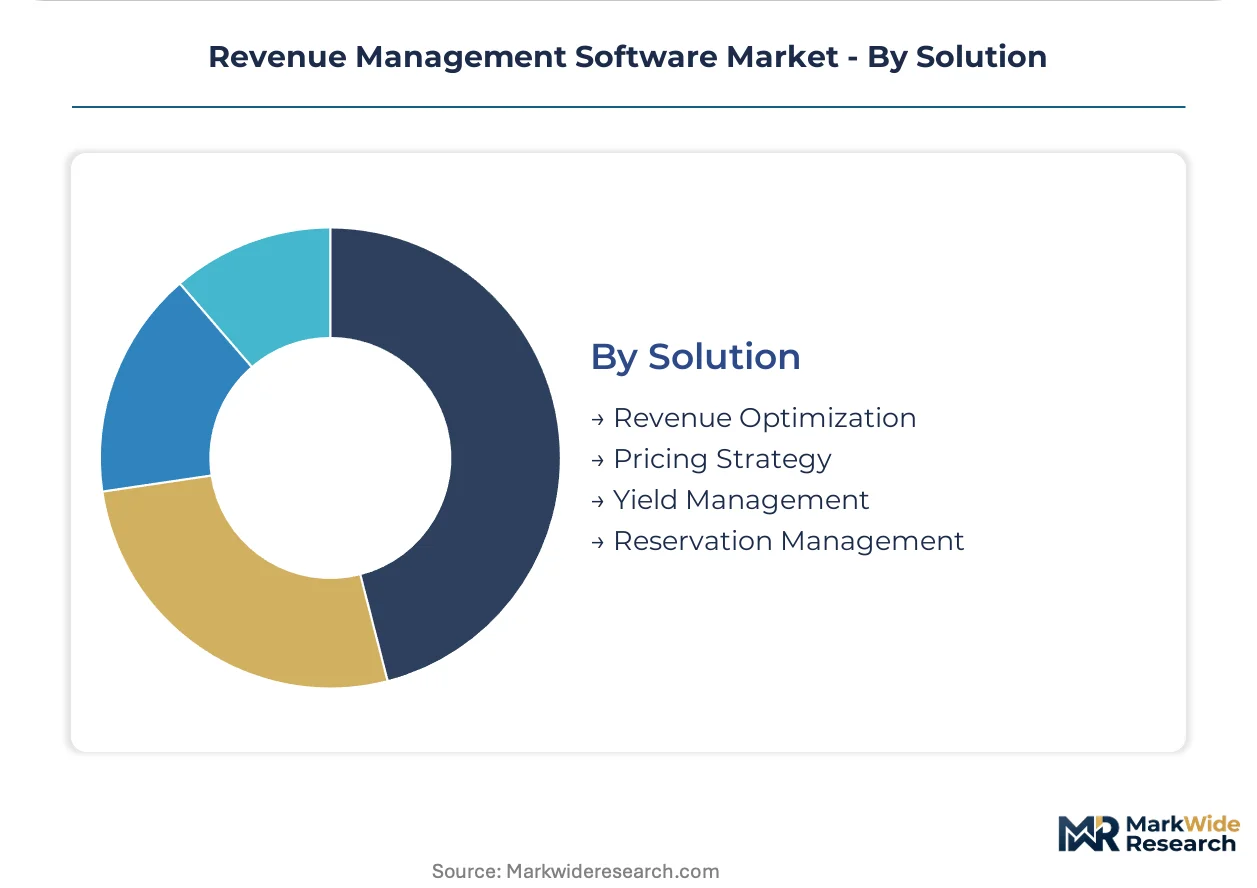
Solution:
Customer type segmentation separates enterprise yield management suites from specialized point solutions for pricing strategy execution.
- Revenue Optimization:Comprehensive platforms integrate forecasting, pricing, and inventory allocation into unified decision engines. Multinational hospitality groups deploy these systems to enforce corporate pricing policies across geographically dispersed properties.
- Yield Management:Specialized modules focus on capacity-constrained industries where unsold inventory represents permanent revenue loss.
- Pricing Strategy:Tools support scenario modeling and competitive positioning analysis for strategic rate architecture design.
- Reservation Management:Systems connect booking engines with revenue algorithms to enforce optimal rate availability at point of sale.
Revenue Optimization leads enterprise procurement. Yield Management is gaining share fastest as airlines modernize legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting software procurement budgets toward jurisdictions with clearer AI governance frameworks. Vendors face divergent compliance costs between markets with established algorithmic transparency rules and those still formulating standards.
United States
Enterprise SaaS procurement budgets remain the largest globally, with hospitality groups consolidating property-level systems onto centralized cloud platforms. FCC guidelines on data transmission integrity shape how cross-border pricing data flows through vendor infrastructure. The Southeast region, particularly Florida and Georgia, hosts rapid independent hotel operator digitization.
Germany
Industrial hospitality chains demand auditable revenue optimization systems under GDPR and emerging EU AI Act mandates. The KBA and federal data protection authorities enforce strict algorithmic documentation requirements for pricing automation. Bavaria's Munich-Stuttgart corridor concentrates vendor R&D investments in explainable machine learning pipelines.
United Kingdom
Post-Brexit regulatory divergence creates procurement complexity for multinational hotel groups operating across European and domestic frameworks. The Information Commissioner's Office maintains GDPR-equivalent data governance standards for pricing data residency. London's financial district anchors fintech-hospitality convergence projects embedding revenue management into corporate travel platforms.
India
Budget hotel aggregators and airline OTAs lack sophisticated yield optimization, creating whitespace for mid-market cloud deployments. TRAI guidelines on data localization influence vendor infrastructure placement decisions. Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore cluster host emerging hospitality technology adoption among regional chain operators.
Japan
Legacy airline revenue management systems reach replacement cycles, driving demand for modern forecasting platforms. METI industrial digitization programs subsidize hospitality technology upgrades for regional hotel associations. The Kansai Osaka-Kyoto tourism corridor experiments with real-time pricing integration across traditional ryokan properties.
Revenue Management Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent billing and CRM-native integration spaces. The vendor base stratifies between legacy hospitality specialists and horizontal SaaS platforms extending into yield management. Three archetypes dominate: CRM-anchored pricing intelligence, dedicated hospitality yield algorithms, and modern usage-based billing engines. Consolidation pressures favor platforms with pre-built property management system connectors, while algorithmic audit capabilities separate compliant from non-compliant vendors in European procurement cycles.
Within the CRM-native tier, Salesforce Revenue Cloud represents horizontal platform extension into revenue intelligence workflows. IDeaS occupies the specialist position exemplifying deep hospitality yield algorithm heritage. Zenskar anchors the billing-convergence archetype, extending platform utility through modern metering engines. These three patterns illustrate how vendor positioning diverges between workflow embedding, sector specialization, and financial operations integration.
| Leading Market Players |
|---|
| Salesforce Revenue Cloud |
| NetSuite |
| Pipedrive |
| Zoho |
| Chargebee |
| Mews |
| IDeaS |
| Zenskar |
| monday CRM |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure cost indices cascade through vendor pricing tiers, compressing margins for multi-tenant architectures while amplifying premiums for single-tenant deployments serving GDPR-sensitive European hospitality chains.
Pricing Analysis
Input-cost pass-through from compliance infrastructure reshapes SaaS subscription tiers. Three-tier pricing structure across enterprise, mid-market, and independent operator levels reflects algorithmic audit investments and data residency guarantees. Pricing pressure stems from EU AI Act documentation requirements that inflate development overhead. Independent hotel operators in the United States exhibit highest price sensitivity, while multinational hospitality groups absorb premiums for dedicated infrastructure isolation.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud providers concentrated in the United States, Ireland, and Germany. Vendor platform development draws from machine learning inference engines, property management system APIs, and explainable model documentation frameworks. Supply chain risk centers on regulatory restriction as EU AI Act mandates filter vendor eligibility. Distribution runs through direct enterprise sales teams and hospitality technology integrators serving regional hotel associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where EU AI Act compliance costs exceed United States development overhead by substantial margins, rewarding vendors with dual-architecture capabilities.
For Market Incumbents: Anticipate procurement consolidation by embedding pre-built property management system connectors that accelerate deployment timelines. Defend against CRM-native horizontal platforms by deepening hospitality-specific yield algorithm specialization. Prioritize certification investment for EU AI Act algorithmic transparency to maintain European account access.
For New Entrants and Emerging Players: Begin with India's budget hotel aggregator whitespace, where yield optimization penetration remains minimal and cloud infrastructure costs favor SaaS economics. Target mid-market airline revenue management replacement cycles as legacy systems age. Pursue channel partnerships with hospitality technology distributors rather than direct enterprise sales buildout.
For Investors and Strategic Acquirers: Consolidation pressure builds where property management system API fragmentation creates integration bottlenecks that specialist vendors can resolve. Long-term viability favors platforms with embedded usage-based billing convergence extending beyond hospitality verticals. Monitor EU AI Act enforcement intensity as inflection indicator for compliant vendor valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic transparency documentation unlocks European hospitality and airline procurement eligibility. |
| Property Management System Integration | Pre-built connectors compress implementation timelines for independent hotel operator consolidation. |
| Usage-Based Billing Convergence | Embedded metering engines extend platform utility into subscription revenue recognition workflows. |
| Single-Tenant Cloud Deployment | Dedicated infrastructure isolation satisfies multinational hospitality group data governance mandates. |
| India Market Entry Partnership | Budget hotel aggregator relationships establish foothold in underpenetrated yield optimization market. |
Study Parameters
Coverage spans the United States, Germany, United Kingdom, India, and Japan, with primary inputs from each market triangulated through interviews with revenue management software executives, hospitality chain procurement officers, airline yield management directors, property management system integration specialists, and cloud infrastructure architects. Secondary validation draws from SEC SaaS company filings, EU regulatory documentation, hospitality technology trade publications, and airline industry association reports. Bottom-up deployment estimates and top-down market sizing were cross-referenced for consistency.
Granularity-level modeling captured deployment architecture, organization size tier, vertical application, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic hospitality indicators. Forecast inputs incorporated airline seat inventory perishability curves, hotel room night elasticity patterns, and cloud infrastructure cost trajectories.
Caveats apply where EU AI Act enforcement timing or United States state privacy law divergence could materially shift the outlook for vendor compliance investments and procurement eligibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Super Apps Market
Digital Solutions
Transit Station Display Board Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Open-Source Intelligence (OSINT) Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Virtual Office Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Shipping Software Market
Digital Solutions
Container Management Software Market